
 Europe Clear Aligners Market | 2026-2036
Europe Clear Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Clear Aligners Market Intelligence
Adult aesthetic dentistry is rebalancing the Europe clear aligners end-use mix, pulling volume from traditional teen bracket systems toward discretionary smile correction. Align Technology leverages its proprietary thermoplastic material science and direct-to-practitioner digital workflow to sustain category leadership across Western Europe. Dentsply Sirona anchors its position through integrated intraoral scanning and CAD/CAM chairside ecosystems that lock clinicians into captive aligner production. Institut Straumann AG competes via its orthodontic subsidiary channel, extending implant patient relationships into adjacent aesthetic procedures.
Clear aligners are transparent, removable orthodontic devices fabricated from multilayer thermoplastic polymers, typically ethylene vinyl acetate or polyethylene terephthalate glycol, through computer-aided design and thermoforming processes; they apply controlled mechanical force to sequentially reposition teeth without fixed brackets. Their primary commercial purpose is to deliver clinically equivalent orthodontic outcomes with superior aesthetics and oral hygiene compliance versus conventional bonded appliances. Removable aligners dominate volume across Europe, though hybrid systems that combine fixed attachments with removable trays are capturing complex malocclusion cases previously excluded from aligner therapy. Dental clinics and orthodontic practices remain the principal end-user channel, with direct sales and distributor networks controlling the bulk of aligner flow in Germany, France, and Spain.
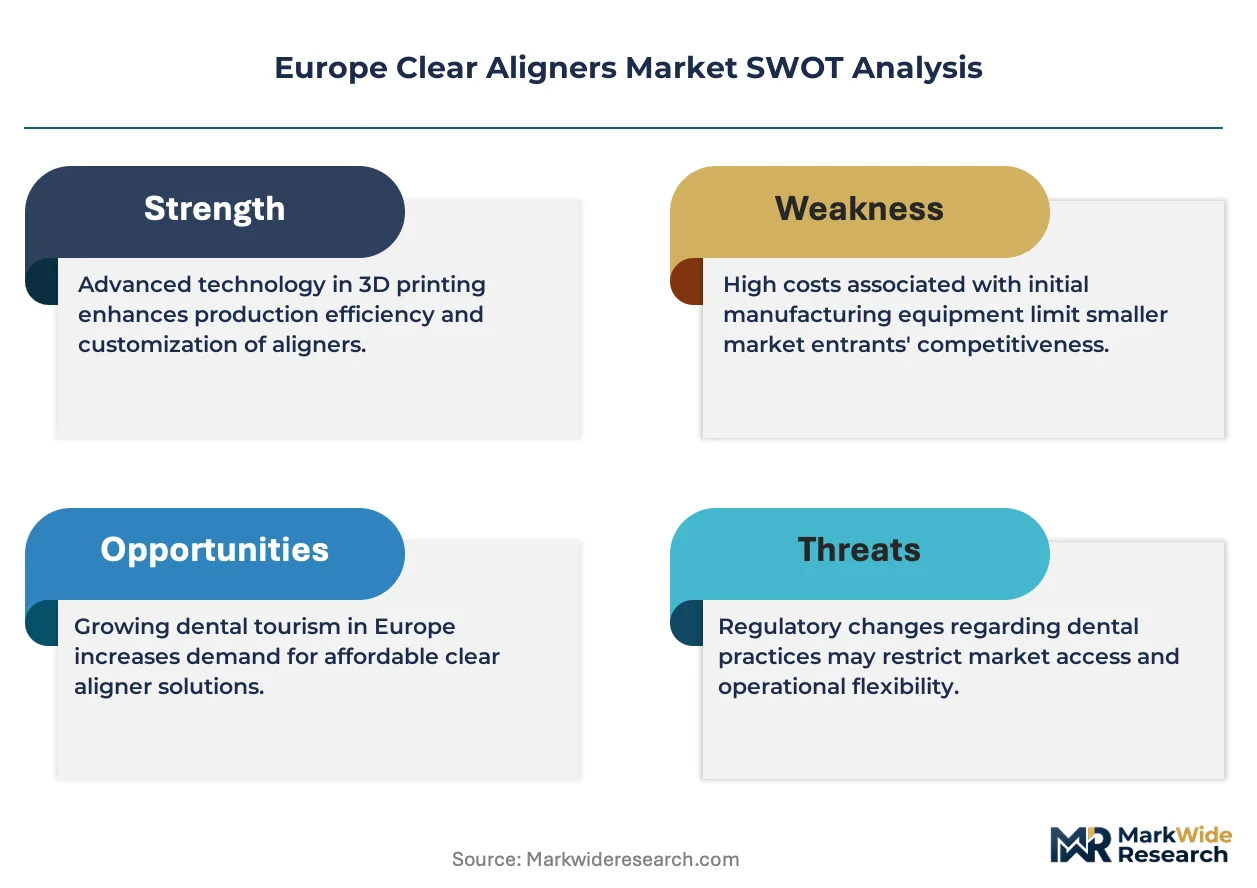
The EU MDR and CE marking requirements enforce clinical performance documentation and post-market surveillance obligations on clear aligner manufacturers, raising barriers for new entrants without established quality management systems. Germany's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices (BfArM), coordinates with notified bodies to enforce MDR compliance timelines that compress certification windows for thermoplastic orthodontic devices. France's ANSM and the United Kingdom's MHRA maintain parallel vigilance reporting systems that shape product liability exposure and recall protocols across the three largest national markets. Stakeholders must monitor how MDR implementation delays and divergent national reimbursement classifications reshape competitive access and pricing power across European jurisdictions.
Market Dynamics
EU MDR reclassification of custom orthodontic appliances is compressing certification timelines and forcing manufacturers to rebuild clinical evidence dossiers from legacy predicate devices, fundamentally restructuring competitive access across Western Europe.
Growth Catalysts
- Aesthetic preference migration:Adult patients across Germany, France, and the United Kingdom are selecting removable thermoplastic aligners over fixed bracket systems for discretionary smile correction, expanding addressable volume beyond traditional teen orthodontics.
- Digital workflow penetration:Intraoral scanning and CAD/CAM chairside production ecosystems are reducing laboratory turnaround times from weeks to days, enabling same-visit treatment planning in high-density orthodontic practices.
- REACH-compliant polymer innovation:Multilayer ethylene vinyl acetate formulations meeting ECHA substance restrictions are delivering improved force retention profiles that extend replacement intervals and improve patient compliance metrics.
Market Restraints
- Notified body capacity constraints:EU MDR implementation has thinned the pool of certified assessors for Class IIa medical devices, extending CE marking timelines for new aligner product lines by 12-18 months and freezing pipeline launches.
- Thermoplastic resin price volatility:Ethylene and vinyl acetate monomer supply disruptions tied to European petrochemical feedstock markets are compressing gross margins on aligner fabrication without commensurate pricing power recovery.
- Complex malocclusion exclusion:Severe skeletal discrepancies and vertical dimension anomalies remain outside aligner biomechanical capabilities, preserving fixed appliance dominance in hospital-based orthodontic departments.
Strategic Opportunities
- Spain and Italy private dental expansion:Underpenetrated orthodontic specialist density in Madrid, Barcelona, Milan, and Rome creates whitespace for premium aligner positioning where reimbursement flexibility mirrors German private sector conditions.
- Hybrid fixed-removable systems:Convergence of temporary anchorage devices with sequential aligner protocols is opening extraction and deep-bite cases previously reserved for fixed mechanics, expanding treatable case mix.
- Tele-dentistry channel development:Remote monitoring applications and direct-to-consumer impression kits are creating alternative patient acquisition pathways that bypass traditional orthodontic referral networks in the United Kingdom.
Industry Challenges
- Orthodontic specialist training deficits:European universities are graduating insufficient numbers of orthodontists trained in digital treatment planning and biomechanical simulation, creating bottlenecks for aligner case complexity expansion.
- Post-market surveillance infrastructure:EU MDR mandates for systematic clinical follow-up and adverse event reporting require manufacturers to build patient registries and quality management systems that strain mid-cap operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Clear Aligners Market |
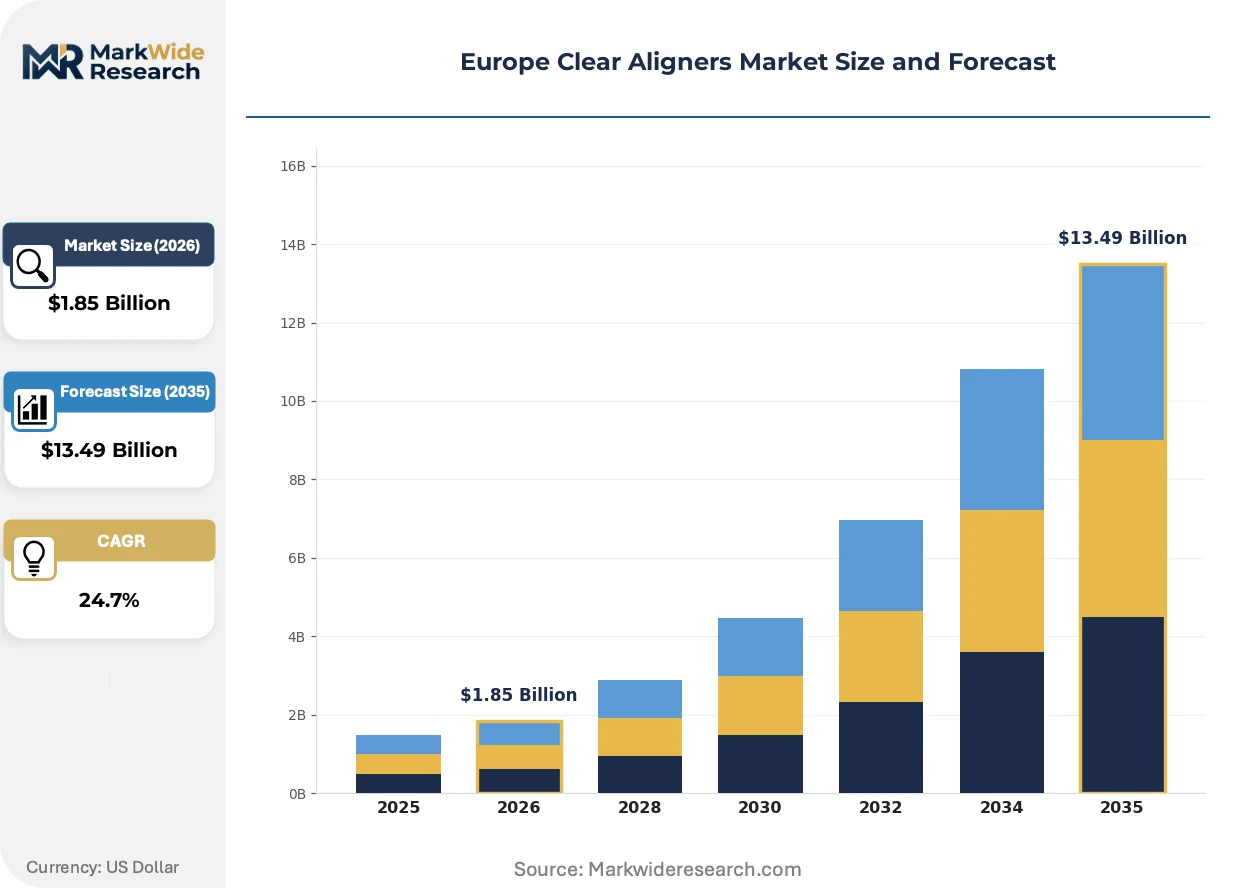
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $13.49 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Removable, Fixed, Hybrid, Customized End User: Dental Clinics, Orthodontic Practices, Hospitals, Homecare Technology: 3D Printing, CAD/CAM Systems, Virtual Treatment Planning, Thermoplastic Materials Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | 3M Company, Argen Corporation, Align Technology, K Line Europe GmbH, Ormco Corporation, Dentsply Sirona, Envista Holdings Corporation, Dentaurum GmbH & Co. Kg, Institut Straumann AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Clear Aligners Market Strategic Shifts & Innovations
Digital fabrication protocols and regulatory data requirements are converging to reshape how clear aligners are designed, manufactured, and brought to market across European jurisdictions.
Artificial intelligence-driven treatment planning software is decentralizing orthodontic expertise from university hospital centers to general dental practices with limited specialist training. General practitioners across France and the United Kingdom are adopting automated cephalometric analysis and predictive outcome simulation to manage moderate malocclusion cases previously referred to orthodontists. This capability diffusion is compressing the specialist gatekeeper role and redistributing aligner volume toward primary dental channels.
EU MDR clinical evidence requirements are mandating prospective patient registry studies and systematic literature reviews for legacy aligner products seeking renewed CE certification. Manufacturers must now submit post-market clinical follow-up data demonstrating sustained orthodontic stability beyond active treatment phases. German and French notified bodies are enforcing these dossier standards most stringently, delaying market access for products with predicate device reliance on pre-MDR approvals.
Subscription-based aligner programs are displacing traditional per-case fee structures in United Kingdom private dental practices. Patients commit to multi-year monitoring contracts bundling retention protocols and refinement aligners, while practices secure predictable recurring revenue streams independent of new patient acquisition cycles. This model concentrates most visibly in London and Manchester aesthetic dentistry clinics competing for adult discretionary spend.
Europe Clear Aligners Market Segmentation
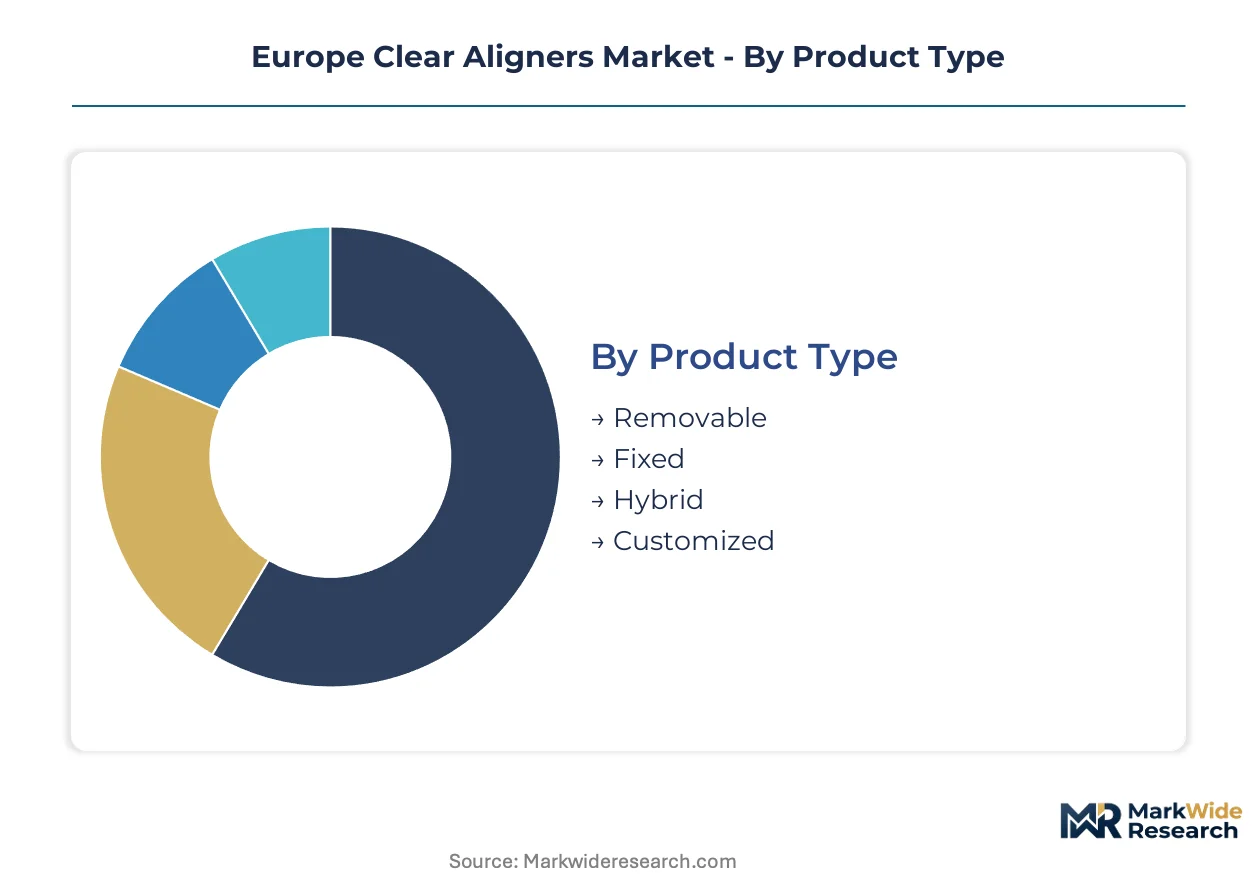
Segmentation in Europe's clear aligners market reveals how reimbursement structures, clinical workflows, and patient acquisition channels reshape competitive positioning across national boundaries. Manufacturers must navigate divergent regulatory requirements and end-user preferences that fragment addressable volume across product tiers and delivery models.
Product Type:
Removable aligners dominate European volume, yet premium positioning and clinical complexity tolerance vary sharply between private German practices and Spain's emerging aesthetic dentistry clusters.
- Removable:Transparent thermoplastic trays fabricated from multilayer ethylene vinyl acetate polymers apply sequential mechanical force without bonded attachments. Demand concentrates in Germany's private dental sector, where orthodontic specialist density and flexible reimbursement support premium per-case pricing for adult aesthetic patients.
- Hybrid:Convergence systems combine temporary anchorage devices or limited fixed attachments with removable sequential trays to manage extraction cases and deep-bite malocclusions previously excluded from aligner protocols. Adoption is accelerating in French university hospital orthodontic departments seeking to preserve aesthetic outcomes for complex adolescent cases.
- Fixed:Bonded ceramic or lingual bracket systems retain dominance for severe skeletal discrepancies and vertical dimension anomalies outside thermoplastic biomechanical capabilities.
- Customized:Patient-specific fabrication through direct intraoral scanning and chairside CAD/CAM production enables same-visit treatment planning in high-throughput London and Manchester practices.
Mature deployment sits with Removable systems. Newer deployment is concentrated in Hybrid configurations.
End User:
Channel selection in Europe tracks national reimbursement classifications and orthodontic specialist training availability, with private dental clinics capturing disproportionate premium volume in high-income markets.
- Dental Clinics:General practitioner adoption of AI-driven treatment planning software is redistributing moderate malocclusion volume from specialist referrals to primary dental channels across France and the United Kingdom.
- Orthodontic Practices:Specialist-gatekeeper practices in Germany maintain premium positioning through proprietary digital workflows and direct manufacturer relationships that bypass distributor markups.
- Hospitals:Public hospital orthodontic departments in Spain and Italy retain fixed appliance dominance for complex cases requiring skeletal correction and multidisciplinary coordination.
- Homecare:Direct-to-consumer impression kits and remote monitoring applications are creating alternative patient acquisition pathways that compress traditional referral networks in the United Kingdom's deregulated private dentistry environment.
Orthodontic Practices command premium pricing power. Homecare represents the steepest expansion trajectory.
Technology:
Technology selection determines manufacturing turnaround, regulatory evidence requirements, and clinician training intensity across European notified body jurisdictions.
- 3D Printing:Photopolymer resin and selective laser sintering protocols enable rapid prototype iteration and same-day aligner fabrication in chairside production ecosystems.
- CAD/CAM Systems:Integrated intraoral scanning and computer-aided design platforms lock clinicians into captive aligner production workflows that reduce laboratory dependency.
- Virtual Treatment Planning:Artificial intelligence-driven cephalometric analysis and predictive outcome simulation decentralizes orthodontic expertise from university centers to general practices with limited specialist training.
- Thermoplastic Materials:REACH-compliant multilayer ethylene vinyl acetate formulations meeting ECHA substance restrictions deliver improved force retention profiles that extend replacement intervals.
CAD/CAM Systems anchor established clinical workflows. Virtual Treatment Planning is gaining share fastest among general practitioner adopters.
Distribution Channel:
Channel strategy in Europe must reconcile EU MDR post-market surveillance obligations with patient acquisition cost efficiency across divergent national regulatory environments.
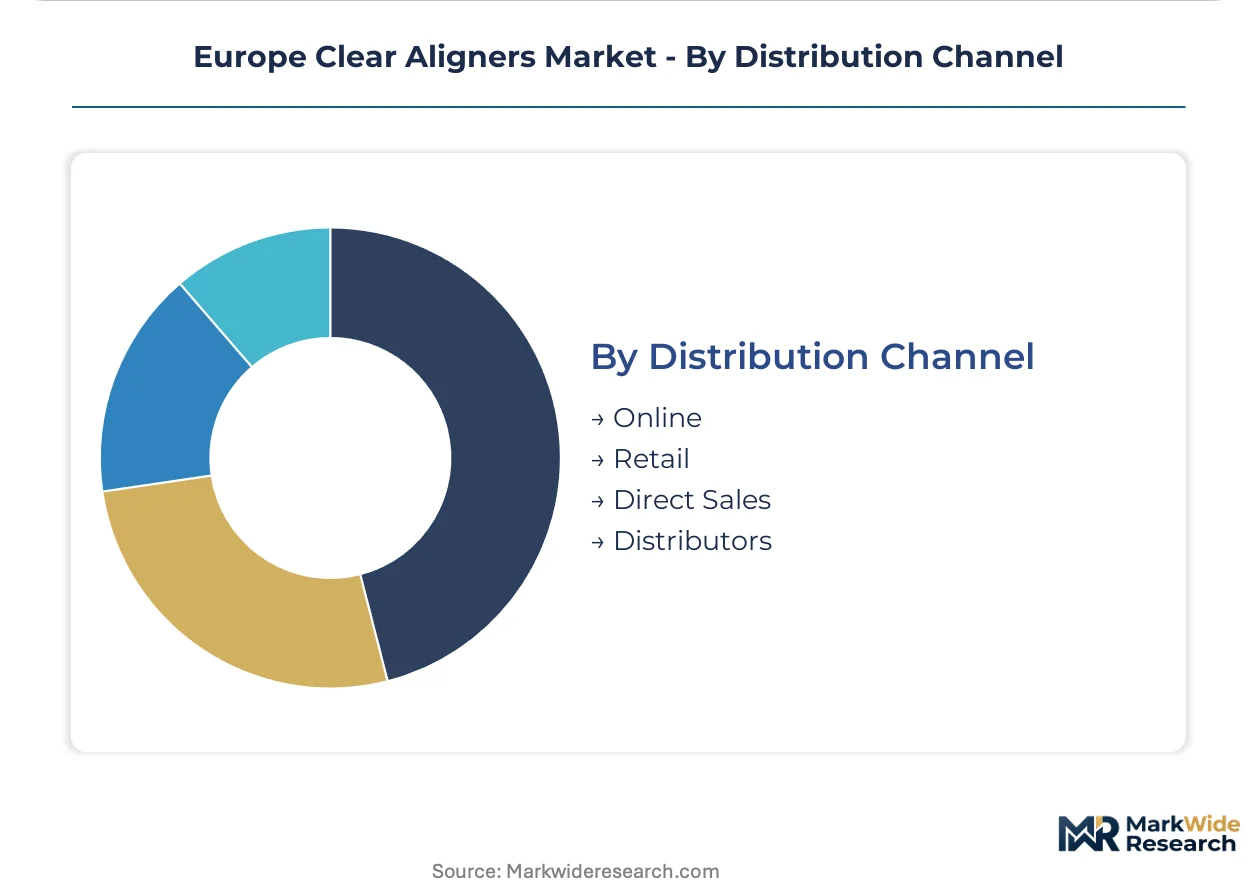
- Direct Sales:Manufacturer-to-practitioner relationships dominate premium aligner flow in Germany, France, and Spain, enabling clinical training investment and quality management system integration.
- Distributors:Third-party logistics networks control volume in Italian and smaller national markets where manufacturer direct presence remains economically unviable.
- Online:E-commerce platforms and tele-dentistry applications facilitate direct-to-consumer acquisition in the United Kingdom's less regulated private dentistry environment.
- Retail:Limited pharmacy and optical chain presence for impression kit distribution operates at the margins of European aligner commerce.
Direct Sales capture premium margin concentration. Online channels are expanding most quickly in deregulated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's private dental sector and the United Kingdom's deregulated aesthetic dentistry clusters concentrate aligner demand within Europe's high-income orthodontic markets, with regulatory divergence across national notified bodies reshaping competitive access timelines.
Germany
Orthodontic specialist density and flexible private reimbursement protocols drive premium aligner uptake in Munich and Hamburg aesthetic practices. The Federal Institute for Drugs and Medical Devices coordinates with notified bodies to enforce EU MDR certification timelines that compress market entry windows for thermoplastic orthodontic devices. Bavaria's dental technology corridor anchors chairside CAD/CAM production ecosystems serving high-throughput orthodontic clinics.
United Kingdom
Direct-to-consumer impression kits and subscription-based retention programs capture adult discretionary spend in London and Manchester private dentistry markets. The Medicines and Healthcare products Regulatory Agency maintains vigilance reporting systems that shape product liability exposure and recall protocols distinct from EU frameworks post-Brexit. Southeast England's tele-dentistry startups bypass traditional orthodontic referral networks through remote monitoring applications.
France
General practitioner adoption of AI-driven treatment planning software redistributes moderate malocclusion volume from specialist referrals to primary dental channels in Paris and Lyon. The National Agency for Food, Environmental and Occupational Health Safety enforces parallel post-market surveillance obligations that extend CE marking documentation requirements. Auvergne-Rhône-Alpes university hospital orthodontic departments pioneer hybrid fixed-removable systems for complex adolescent cases.
Spain
Underpenetrated orthodontic specialist density in Madrid and Barcelona creates whitespace for premium aligner positioning where reimbursement flexibility mirrors German private sector conditions. Spanish notified bodies face capacity constraints that extend certification timelines for Class IIa medical devices by 12-18 months. Catalonia's dental technology clusters attract manufacturer direct sales investment bypassing distributor markups.
Italy
Third-party distributor networks control aligner volume in Milan and Rome where manufacturer direct presence remains economically unviable for mid-cap producers. Italy's national pharmaceutical regulator enforces EU MDR clinical evidence standards that predicate device reliance struggles to satisfy. Northern Italy's orthodontic practices concentrate hybrid system adoption for extraction cases previously excluded from clear aligner protocols.
Europe Clear Aligners Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium-tier players commanding direct-to-practitioner relationships while mid-cap fabricants rely on distributor networks. Market structure tilts toward consolidation around proprietary thermoplastic material science and integrated digital workflow ecosystems. Three archetypes dominate: integrated dental technology conglomerates with captive aligner production, orthodontic-focused specialists leveraging direct sales forces, and contract manufacturers serving private-label programs. Competitive dynamics center on M&A activity targeting intraoral scanning capabilities and strategic partnerships bundling aligner supply with CAD/CAM chairside systems.
Among US-based dental technology conglomerates, Align Technology and Dentsply Sirona occupy positions exemplifying divergent ecosystem strategies. Align Technology anchors the proprietary material science archetype through direct-to-practitioner digital workflows sustaining category leadership. Dentsply Sirona represents the integrated equipment-aligner convergence model, locking clinicians into captive production ecosystems. Institut Straumann AG, the Swiss dental implant specialist, sits within the orthodontic subsidiary expansion archetype, extending implant patient relationships into adjacent aesthetic procedures through its orthodontic channel.
| Leading Market Players |
|---|
| 3M Company |
| Argen Corporation |
| Align Technology |
| K Line Europe GmbH |
| Ormco Corporation |
| Dentsply Sirona |
| Envista Holdings Corporation |
| Dentaurum GmbH & Co. Kg |
| Institut Straumann AG |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between MDR-compliant premium aligners and legacy predicate devices manifests in both pricing power and supply chain configuration across European markets. German orthodontic practices command per-case premiums for CE-marked systems with full clinical evidence dossiers, while distributor-dependent channels in Italy absorb margin compression from extended notified body timelines.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with notified body pre-certification: practices in Munich and Hamburg pay premiums for same-week aligner delivery, while spot inventory from non-compliant legacy stock clears at discounts through Southern European distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, force retention profile, and bundled refinement protocols. Cost compression in economy tiers is intensifying because ethylene vinyl acetate monomer supply disruptions have removed pricing power recovery mechanisms. General dental clinics exhibit highest price sensitivity due to AI-driven treatment planning commoditization, whereas orthodontic specialist practices retain lowest sensitivity through captive manufacturer relationships.
Supply Chain Analysis
Direct-to-practitioner channels handle premium aligner demand from high-density orthodontic clusters in Germany, France, and the United Kingdom. Raw material dependencies center on multilayer ethylene vinyl acetate formulations from REACH-compliant European polymer suppliers, photopolymer resins for 3D-printed attachment templates, and cobalt-chrome alloys for hybrid system temporary anchorage devices. Single-source vulnerability sits with notified body capacity constraints that freeze pipeline launches for 12-18 month certification windows. Distribution runs through manufacturer direct sales in premium markets and third-party logistics networks in Italy and smaller jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR implementation is compressing weaker manufacturers out of the Europe clear aligners market as clinical evidence requirements strain mid-cap operational capacity. Consolidation around integrated digital workflow ecosystems and proprietary thermoplastic material science will accelerate through the forecast window.
For Market Incumbents: Acquire intraoral scanning capabilities and CAD/CAM chairside production assets to lock clinicians into captive aligner ecosystems. Defensive consolidation requires backward integration into REACH-compliant polymer formulation to secure force retention profile differentiation against commodity thermoplastic competitors. Channel control through direct-to-practitioner relationships in Germany and Spain insulates margin position from distributor markup compression. For New Entrants and Emerging Players: EU MDR reclassification in Germany opens a window for tele-dentistry channel development that bypasses traditional orthodontic referral networks. White-space targets include remote monitoring applications in United Kingdom private dentistry and hybrid fixed-removable systems for complex adolescent cases in French university hospitals. Go-to-market execution should anchor in subscription-based retention programs that secure recurring revenue independent of new patient acquisition cycles. For Investors and Strategic Acquirers: Re-rating potential sits with orthodontic-focused specialists possessing direct sales force infrastructure given AI-driven treatment planning diffusion into general dental channels. Long-term viability across the 5-10 year window favors manufacturers with established quality management systems and patient registry capabilities for post-market surveillance compliance. The signal to watch is notified body capacity expansion timelines as inflection indicator for pipeline unfreezing and competitive re-entry.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Early engagement with German and French notified bodies compresses certification timelines for Class IIa thermoplastic devices. |
| Intraoral Scanning Acquisition | Chairside CAD/CAM ecosystem integration locks clinicians into captive aligner production workflows. |
| Hybrid System Development | Convergence with temporary anchorage devices expands treatable case mix into extraction and deep-bite malocclusions. |
| Tele-Dentistry Platform Launch | Remote monitoring applications bypass traditional orthodontic referral networks in United Kingdom deregulated markets. |
| REACH-Compliant Polymer Backward Integration | In-house ethylene vinyl acetate formulation secures force retention profile differentiation and margin protection. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe clear aligners market assessment. Primary interviews with orthodontic specialists, general dental practitioners, biomedical engineers at notified bodies, and procurement managers at hospital orthodontic departments combined with EMA MDR guidance documents, BfArM certification databases, and MHRA vigilance reports. Bottom-up patient volume modeling and top-down manufacturer shipment triangulation validated segmentation outputs across product type, end user, and distribution channel dimensions.
Reconciliation of intraoral scanner deployment statistics, aligner case submission volumes, and polymer raw material import flows informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, clinical setting, technology platform, and national reimbursement classification. CAGRs derived from patient demographic projections, orthodontic specialist density trends, and digital workflow penetration curves. Industry-specific forecast inputs encompass EU MDR implementation delays and divergent national classification of aligner therapy within statutory dental benefit schemes.
Caveats apply where notified body capacity constraints, ethylene vinyl acetate monomer supply disruptions, or AI-driven treatment planning commoditization could materially shift the outlook. Forecasts reflect assumptions regarding MDR compliance timeline adherence and hybrid system clinical validation progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Annuloplasty Rings Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Global Sperm Separation Devices Market