
 Dental Elevator and Luxator Market | 2026-2036
Dental Elevator and Luxator Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Elevator and Luxator Market Intelligence
The European Union's Medical Device Regulation (MDR) is hardening the compliance pathway and cost of entry for new instrument manufacturers. Dentsply Sirona leverages its extensive global distribution network to navigate these complex regulatory landscapes. Straumann differentiates through its focus on premium implantology and associated surgical instruments. Henry Schein sustains its market position by offering a comprehensive portfolio to dental clinics and large group practices.
Dental elevators and luxators are handheld surgical instruments designed for the atraumatic extraction of teeth. These instruments feature precisely engineered tips, often made of stainless steel or titanium, that work to sever the periodontal ligament and gently expand the alveolar bone. While traditional straight elevators dominate the tooth extraction application, specialized luxators and periotomes see increased use in implantology. Material choice, particularly between standard stainless steel and premium titanium, is a primary basis for price differentiation.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and adherence to CE marking protocols in Europe dictate market access. Compliance with ISO 13485, the standard for medical device quality management systems, is a critical prerequisite for all manufacturers targeting professional end users. Future competitive advantage will depend on material science innovations that enhance instrument durability and ergonomic designs that reduce practitioner fatigue.
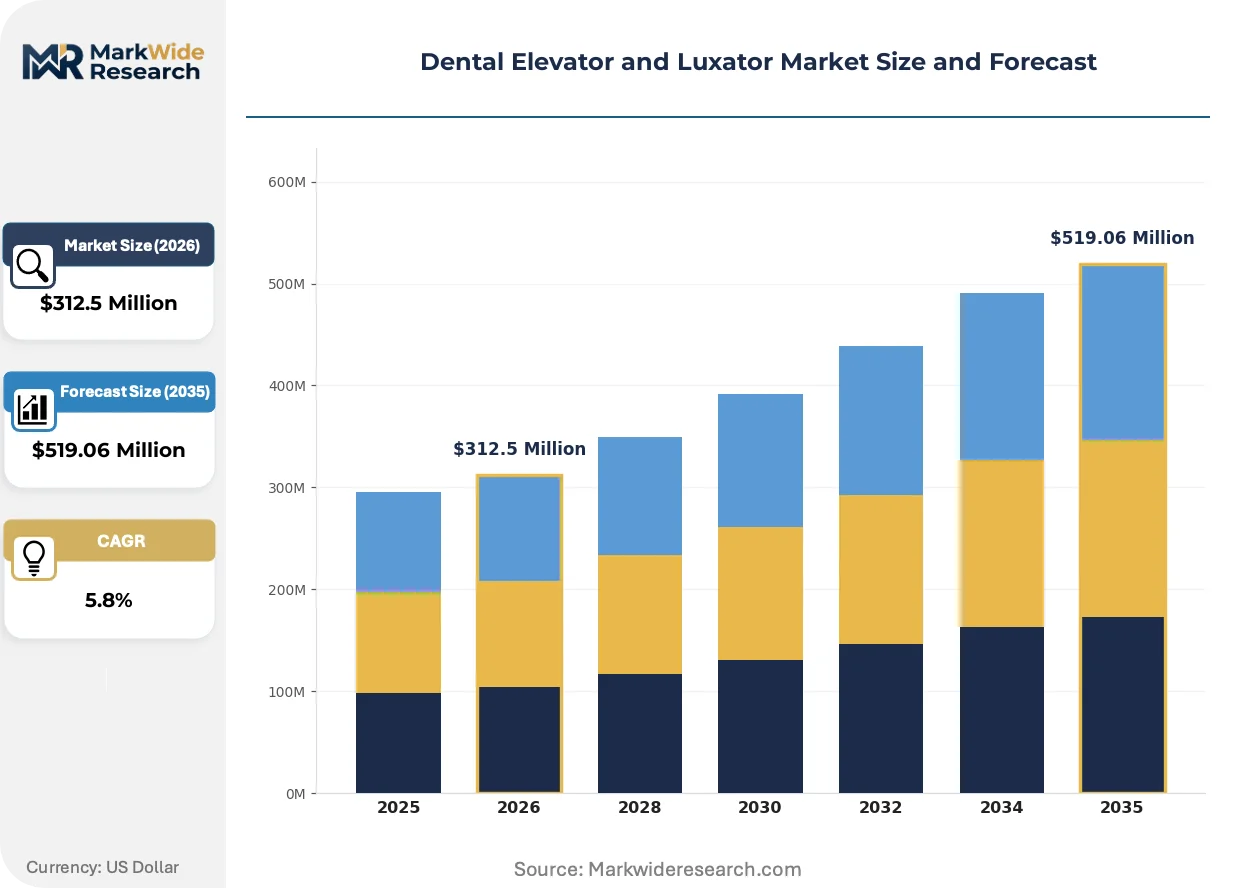
Market Dynamics
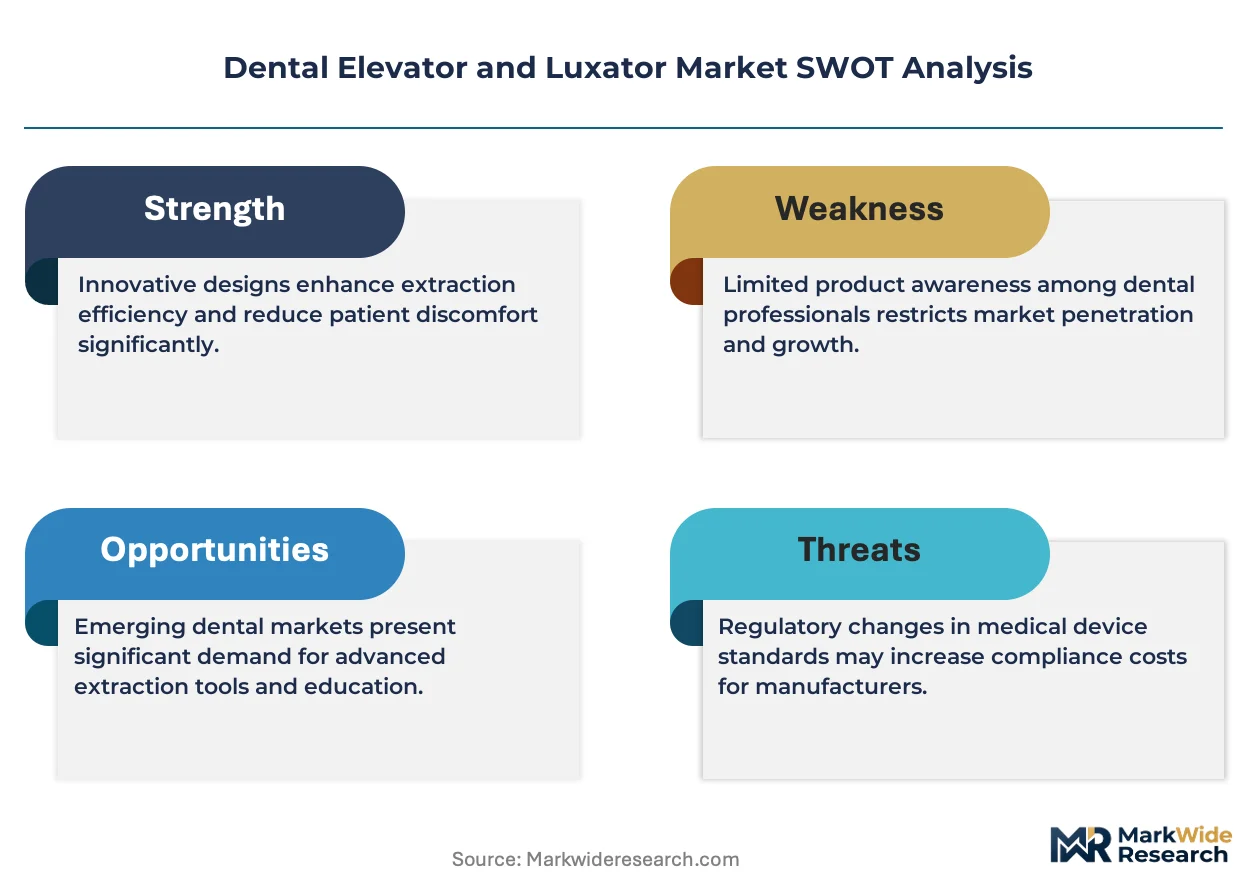
The European Union's Medical Device Regulation (MDR) is a central force, escalating compliance burdens and costs. This regulation elevates requirements for material traceability and quality assurance, reshaping market entry barriers and competitive dynamics for all instrument manufacturers.
Growth Catalysts
- Implantology Procedures:The rising volume of dental implant surgeries drives demand for specialized luxators and periotomes, essential for atraumatic extractions that preserve alveolar bone.
- ISO 13485 Compliance:Mandated adherence to this quality management standard favors manufacturers with proven quality systems, pushing procurement towards certified, higher-grade instruments.
- Specialized Clinic Growth:The expansion of dedicated oral surgery centers concentrates demand for high-precision elevators needed for complex extractions.
Market Restraints
- Material Costs:The high cost of medical-grade titanium, used for premium instruments, constrains affordability and limits adoption in price-sensitive dental clinics.
- Regulatory Barriers:The European Union's Medical Device Regulation (MDR) increases the cost and complexity of achieving CE marking, creating a significant market entry barrier.
- Counterfeit Instruments:The proliferation of low-cost, non-compliant counterfeit products from unregulated markets erodes pricing and poses patient safety and liability risks for practitioners.
Strategic Opportunities
- Emerging Economies:Expanding dental infrastructure in Latin America and Southeast Asia creates opportunity for instruments tailored to the price points of these growing markets.
- Material Science Innovation:Developing instruments with novel surface coatings or alloys to enhance durability and improve sterilization offers a path to premium product differentiation.
- Direct-to-DSO Channels:Establishing direct sales relationships with large Dental Service Organizations (DSOs) offers a streamlined channel to capture high-volume, standardized orders.
Industry Challenges
- Practitioner Training:Ensuring dentists are properly trained on techniques for advanced luxators to achieve atraumatic outcomes remains a significant educational challenge.
- Supply Chain Documentation:Meeting the stringent traceability requirements of regulations like the EU MDR adds significant complexity and cost throughout the supply chain.
- Sterilization Degradation:The degradation of instruments from repeated sterilization cycles challenges manufacturers to improve material durability while managing production costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Elevator and Luxator Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Elevators, Luxators, Periotomes, Root Elevators, Straight Elevators, Others Material: Stainless Steel, Titanium, Carbon Steel, Plastic Handle, Silicone Grip, Others Application: Tooth Extraction, Surgical Procedures, Orthodontic Treatment, Implantology, Periodontal Therapy, Others End User: Dental Clinics, Oral Surgery Centers, Orthodontic Practices, Dental Colleges, Specialty Clinics, Others |
| Companies Covered | 3M, Danaher Corporation, Patterson Dental, Carestream Health, PLANMECA OY, Henry Schein, Straumann, Biolase, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Elevator and Luxator Market Strategic Shifts & Innovations
Material science and manufacturing precision are defining the next generation of dental elevators and luxators. The market is evolving beyond traditional designs, driven by regulatory demands for enhanced safety and clinical demand for instruments that reduce patient trauma.
Physical Vapor Deposition (PVD) and Diamond-Like Carbon (DLC) coatings provide an extremely hard, low-friction surface on instrument tips. Oral surgeons and implantologists adopt these coated instruments for their durability and smoother tissue interaction. This technology is absorbing the premium market segment, positioning traditional uncoated stainless steel as a standard or economy-tier option.
The US Food and Drug Administration's (FDA) Unique Device Identification (UDI) system mandates that most medical devices carry a unique identifier. This regulation forces manufacturers to implement robust track-and-trace systems from production to the final point of use. The entire supply chain is impacted, with smaller manufacturers facing the greatest burden to comply with data submission requirements.
Centralized procurement by large Dental Service Organizations (DSOs) is replacing individual clinic purchasing decisions. This shift diminishes the influence of local sales representatives, favoring manufacturers who can negotiate large-volume contracts and provide standardized instrument kits. This purchasing model is most prominent within the dental markets of the United States and the United Kingdom.
Dental Elevator and Luxator Market Segmentation
The dental elevator and luxator market exhibits distinct segmentation across product types, materials, applications, and end-users. Understanding these divisions clarifies demand drivers and supply dynamics for specialized dental instruments. This analysis highlights the specific characteristics and commercial significance of each segment.
Product Type:
Supply concentration patterns dictate the availability and innovation pace across various dental elevator and luxator product types.
- Dental Elevators:These traditional instruments are designed for general tooth extraction, leveraging leverage to loosen teeth. Demand remains high for standard instruments widely used across general dental practices in the United States and Germany.
- Luxators:Luxators feature fine, sharp blades that sever the periodontal ligament with minimal bone expansion, facilitating atraumatic extractions. There is growing adoption within specialized oral surgery centers in Europe and Asia for atraumatic extractions.
- Periotomes:Periotomes are extremely thin, sharp instruments used to cut the periodontal ligament, preserving bone for immediate implant placement.
- Root Elevators:Specifically designed to remove retained root fragments, these instruments have varied tip designs for accessing different root anatomies.
- Straight Elevators:These instruments feature a straight working end, primarily used for initial tooth mobilization and severing the periodontal ligament.
- Others:This category encompasses specialized or custom-designed elevators and luxators for unique clinical scenarios.
Today's leader: Dental Elevators. Tomorrow's challenger: Luxators.
Material:
Cost tier differentiation significantly influences material choices for dental elevators and luxators, impacting instrument performance and practitioner investment.
- Stainless Steel:This material forms the backbone of the instrument market, offering a balance of durability, corrosion resistance, and cost-effectiveness. Stainless steel is the dominant material for standard instruments in clinics worldwide, valued for its cost-effectiveness and sterilization compatibility.
- Titanium:Titanium instruments provide superior strength, biocompatibility, and lighter weight, reducing practitioner fatigue during prolonged procedures. Titanium is preferred for premium instruments, offering superior strength and biocompatibility, particularly in implantology cases in the US and Japan.
- Carbon Steel:Carbon steel offers high hardness and edge retention but requires specific care to prevent corrosion.
- Plastic Handle:Instruments with plastic handles prioritize ergonomic comfort and provide a lightweight option for practitioners.
- Silicone Grip:Silicone grips enhance instrument control and reduce hand fatigue, improving handling during intricate procedures.
- Others:This segment includes instruments made from specialized alloys or composite materials for enhanced performance characteristics.
Stainless steel instruments maintain volume leadership, while titanium options represent the fastest-growing trajectory in premium segments.
Application:
Application focus drives specific design requirements and material selection for dental elevators and luxators.
- Tooth Extraction:This primary application utilizes a broad range of elevators and luxators for routine and complex tooth removal procedures. Tooth extraction is the primary application for elevators and luxators across all dental settings, from small practices to large clinics in Canada and Australia.
- Implantology:Specialized luxators and periotomes are critical in implantology to preserve alveolar bone structure during atraumatic extractions. Implantology drives demand for specialized luxators and periotomes designed for alveolar bone preservation, especially in Germany and South Korea.
- Surgical Procedures:This broad category includes various oral surgical interventions beyond simple extractions, often requiring specific instrument designs.
- Orthodontic Treatment:Elevators and luxators are sometimes used in orthodontic cases for extractions necessary for space creation or alignment.
- Periodontal Therapy:Instruments can assist in periodontal procedures requiring careful tissue manipulation and tooth mobilization.
- Others:This segment covers niche applications or emerging surgical techniques requiring specific instrument adaptations.
Tooth extraction remains the largest application, but implantology is gaining share fastest due to specialized instrument needs.
End User:
Customer type influences purchasing volumes and preferences for instrument durability and specialized features.
- Dental Clinics:These facilities represent the largest end-user group, encompassing general dentistry practices and multi-specialty clinics. Dental clinics represent the broadest end-user segment, purchasing a wide range of instruments for routine procedures in the UK and Brazil.
- Oral Surgery Centers:Specialized centers focus on complex extractions, implant placements, and other advanced oral surgical procedures. Oral surgery centers require high-precision instruments for complex extractions and implant placements, concentrating demand in high-volume centers in France and India.
- Orthodontic Practices:These practices primarily focus on tooth alignment but may require extraction instruments for specific treatment plans.
- Dental Colleges:Educational institutions purchase instruments for training purposes, often requiring durable and versatile options for student use.
- Specialty Clinics:This category includes endodontic, periodontic, and other specialized dental practices with unique instrument requirements.
- Others:This segment covers government health facilities, military dental units, and research institutions.
Dental clinics represent the broadest end-user base, with oral surgery centers demonstrating the steepest expansion trajectory for high-precision tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled dental practitioners and a robust research ecosystem anchor demand across developed economies. Instrument adoption within specialized oral surgery centers is accelerating for complex extraction cases. Regulatory compliance frameworks significantly influence market access and product development in these regions.
United States
Specialized oral surgery centers and a high volume of implantology procedures drive demand for advanced elevators and luxators. The US Food and Drug Administration (FDA) mandates stringent approval processes for all medical devices. Dental technology clusters in California and the Northeast corridor foster innovation in instrument design and material science.
Germany
Germany's strong emphasis on precision engineering and advanced dental care fuels demand for high-quality instruments. The European Union's Medical Device Regulation (MDR) elevates material traceability and quality assurance requirements. Manufacturing hubs in Bavaria and North Rhine-Westphalia concentrate expertise in surgical instrument production.
Japan
Japan prioritizes premium titanium instruments due to their superior strength and biocompatibility, particularly in implantology cases. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict regulatory protocols for medical device market entry. Advanced material science research centers in Tokyo contribute to ongoing instrument innovation.
China
Expanding dental infrastructure and a rapidly growing patient base drive volume demand for both standard and specialized instruments. The National Medical Products Administration (NMPA) sets guidelines for medical device registration and quality. Production centers in the Yangtze River Delta region are increasing manufacturing capacity for dental tools.
Brazil
Brazil's growing number of dental clinics and increasing access to professional dental care stimulate instrument procurement. ANVISA, the country's health surveillance agency, regulates medical device commercialization. Dental equipment manufacturing facilities in São Paulo cater to both domestic and regional Latin American markets.
Dental Elevator and Luxator Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the dental elevator and luxator market. The market structure exhibits a tiered approach, with large dental solution providers alongside specialized instrument manufacturers and regional players. Portfolio diversification and geographic expansion represent dominant competitive moves among these entities.
Global market participants like Dentsply Sirona leverage extensive distribution networks to navigate complex regulatory landscapes worldwide. Straumann differentiates through its focus on premium implantology and associated surgical instruments, exemplifying a specialized approach. Henry Schein sustains its market position by offering a comprehensive portfolio to dental clinics and large group practices, anchoring the broad-spectrum supply segment.
| Leading Market Players |
|---|
| 3M |
| Danaher Corporation |
| Patterson Dental |
| Carestream Health |
| PLANMECA OY |
| Henry Schein |
| Straumann |
| Biolase |
| Dentsply Sirona |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized material processing anchors both the supply position and the pricing power for premium dental instruments. This strategic choice enables manufacturers to control quality and cost for critical components.
Pricing Analysis
Bundled instrument kits and unbundled individual tools define the pricing landscape. Pricing stratifies across premium, standard, and economy tiers, reflecting material choice and manufacturing precision. Quality grade, particularly between titanium and stainless steel, drives significant price differentiation. Pricing softness reflects intense competition from lower-cost alternatives and counterfeit products. Dental clinics, especially in emerging economies, exhibit higher price sensitivity compared to specialized oral surgery centers.
Supply Chain Analysis
Dual-sourcing requirements for medical-grade materials mitigate risks for major manufacturers. Geographic supply concentrates in Germany, the United States, and China for instrument production. The supply chain draws from medical-grade stainless steel and titanium, with material cost volatility influencing production expenses. Regulatory restrictions, such as the EU MDR's stringent traceability demands, represent a structural supply chain risk. Distribution runs through large Dental Service Organizations and specialized regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, with practitioners increasingly demanding instruments that reduce patient trauma and enhance clinical outcomes.
For Market Incumbents:
Anticipate continued regulatory hardening by investing in advanced material traceability systems to meet EU MDR requirements. Consolidate market share through strategic acquisitions of specialized instrument manufacturers. Counter the threat of counterfeit instruments by enhancing brand protection and educating practitioners on product authenticity. Leverage extensive global distribution networks to maintain market presence against regional challengers.
For New Entrants and Emerging Players:
The expansion of dental infrastructure in Latin America opens a window for cost-effective, yet compliant, instrument solutions. Target the price-sensitive dental clinics in these emerging economies with robust stainless steel options. Focus on specific applications like basic tooth extraction, which remains a high-volume segment. Establish regional partnerships for localized distribution and compliance support, offering a tailored go-to-market angle.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized instrument manufacturers because market fragmentation still provides ample acquisition targets. Long-term viability rests on sustained demand for oral surgical procedures and implantology. Identify acquisition targets with strong material science capabilities or established direct-to-DSO channels. A signal to watch is the adoption rate of advanced PVD/DLC coated instruments, indicating a shift towards premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Material Science R&D | Enhances instrument durability and performance, allowing for premium product differentiation. |
| Expand Direct-to-DSO Sales Channels | Secures high-volume, standardized orders and streamlines procurement for large dental groups. |
| Strengthen Regulatory Compliance Teams | Ensures market access and reduces penalties in regions with stringent medical device regulations. |
| Develop Regional Manufacturing Hubs | Mitigates supply chain risks and reduces logistics costs for specific geographic markets. |
| Acquire Niche Instrument Specialists | Adds specialized product lines and expertise, broadening portfolio for complex procedures. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each key region informing the analysis. The methodology combines in-depth primary interviews with industry stakeholders and rigorous secondary validation. Interviews included oral surgeons, dental practice managers, regulatory officials, and instrument design engineers. Secondary data sources encompassed FDA filings, CE marking databases, ISO 13485 standards, and published industry reports, triangulating insights from both bottom-up and top-down perspectives.
The granularity-level framing involved modeling market segments by product type, material, application, end-user, and geographic region. The analytical framework projects market evolution across the modeling period, incorporating historical trends and future drivers. Compound Annual Growth Rates were derived from an assessment of demand-side factors and supply-side capabilities. Key forecast inputs included dental procedure volumes, raw material costs, and anticipated regulatory changes.
Revisions become necessary when significant macroeconomic shifts or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions documented regarding market dynamics and competitive forces. Deviation in global economic stability or major regulatory overhauls would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market