
 In Vitro and in Vivo Microelectrode Array Market | 2026-2036
In Vitro and in Vivo Microelectrode Array Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro and in Vivo Microelectrode Array Market Foresight
Germany is tilting toward expanded microelectrode array production capacity as European neurotechnology funding intensifies. MaxWell Biosystems AG leverages its Zurich-based engineering heritage to sustain precision manufacturing of high-density CMOS arrays. Multi Channel Systems MCS GmbH anchors electrophysiology instrumentation through integrated hardware-software platforms. 3Brain AG differentiates via proprietary high-resolution microelectrode technology for in vitro neural networks.
In vitro and in vivo microelectrode arrays consist of patterned conductive elements—typically platinum, iridium oxide, or titanium nitride—fabricated on silicon, glass, or flexible polymer substrates at spatial resolutions reaching tens of micrometers, enabling simultaneous recording or stimulation of electrogenic cells. Their primary commercial purpose spans fundamental neurophysiology research, preclinical drug safety assessment, and development of brain-machine interface prototypes. Silicon-based technology dominates current revenue owing to established semiconductor fabrication infrastructure, while polymeric arrays represent the fastest-growing segment as stretchable electronics enable chronic in vivo implantation. Academic research institutions constitute the largest end-user pool, though pharmaceutical companies command premium pricing for validated toxicology and drug discovery platforms.
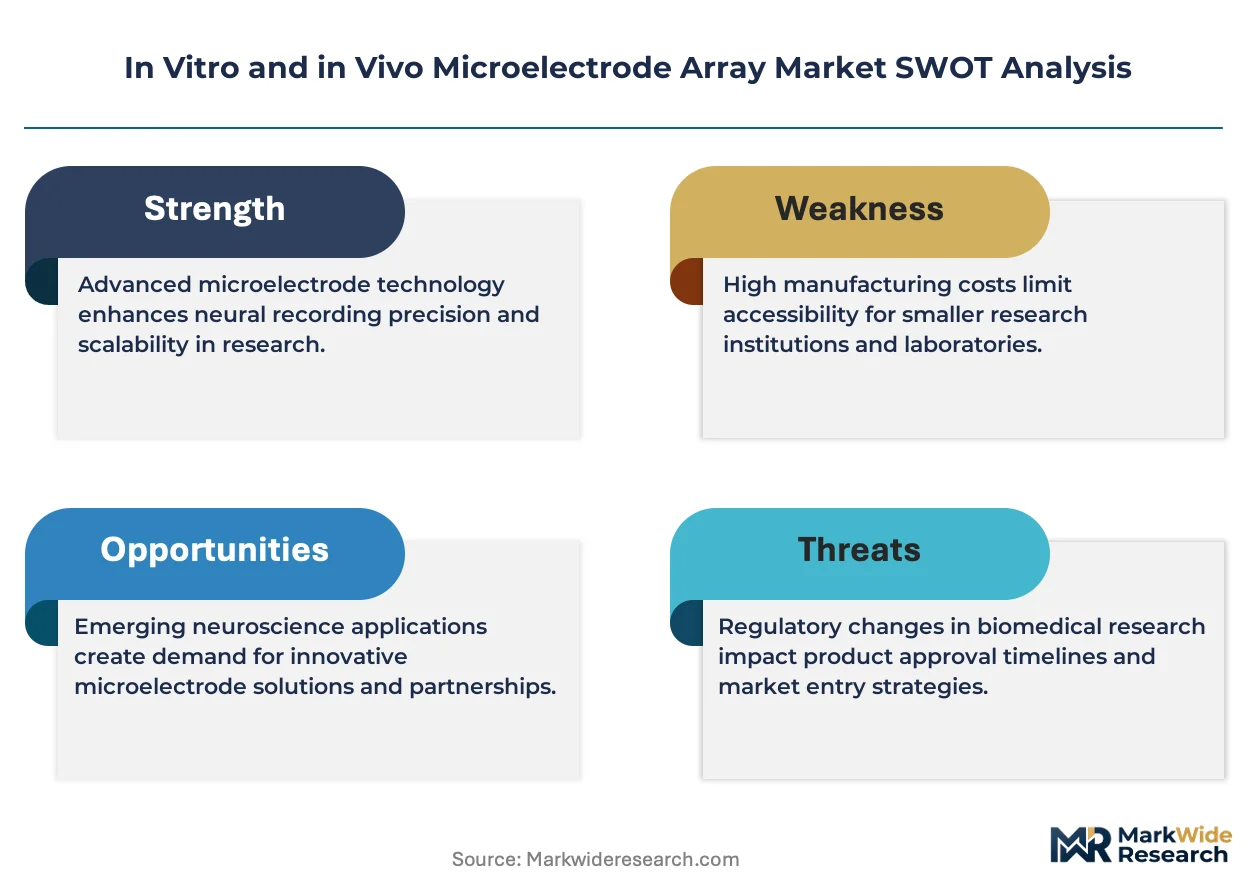
FDA device classification pathways and the EU Medical Device Regulation shape product development timelines and clinical translation requirements for implantable arrays. ISO 10993 biocompatibility standards and GLP toxicology protocols further constrain material selection and manufacturing processes for regulated applications. Stakeholders must monitor evolving reimbursement frameworks for neural interface technologies while calibrating R&D investments against regulatory uncertainty in chronic implantation indications.
Market Dynamics
Silicon foundry capacity constraints are compressing microelectrode array lead times while pharmaceutical toxicology budgets expand, creating a structural squeeze between supply rigidity and demand acceleration.
Growth Catalysts
- NIH Brain Initiative funding:Sustained federal neuroscience investment in the United States accelerates academic procurement of high-density recording platforms for neural circuit mapping.
- High-throughput electrophysiology:Pharmaceutical safety teams integrate microelectrode arrays into cardiotoxicity and neurotoxicity screening workflows, displacing lower-resolution patch-clamp methods.
- Platinum-iridium oxide metallurgy:Advanced thin-film deposition techniques extend electrode longevity in chronic implantation studies, enabling longitudinal preclinical research designs.
Market Restraints
- Silicon wafer supply concentration:Taiwan-based foundry dominance creates single-point vulnerability for CMOS array fabrication, with geopolitical friction threatening substrate access.
- ISO 10993 biocompatibility testing costs:Extended cytotoxicity and sensitization studies for implantable polymer arrays add months to product development cycles.
- Optogenetic alternatives:Fiber-coupled light stimulation systems compete for neural modulation applications where spatial precision requirements are moderate.
Strategic Opportunities
- EU Medical Device Regulation harmonization:Streamlined CE marking pathways for neural interface devices reduce regulatory fragmentation across Germany, France, and Switzerland.
- Brain-machine interface clinical translation:Motor prosthesis and communication aid applications create demand for chronic implantable arrays with multi-year stability.
- Flexible polyimide substrate adoption:Stretchable electronics manufacturing in South Korea and Japan enables conformal neural interfaces for rodent and non-human primate models.
Industry Challenges
- Multiphysics simulation expertise:Electrochemical-mechanical modeling for electrode-tissue interfaces requires rare cross-training in neuroscience and finite element analysis.
- GLP laboratory certification timelines:Pharmaceutical contract research organizations face extended validation periods for microelectrode-based safety studies under FDA Good Laboratory Practice standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro and in Vivo Microelectrode Array Market |
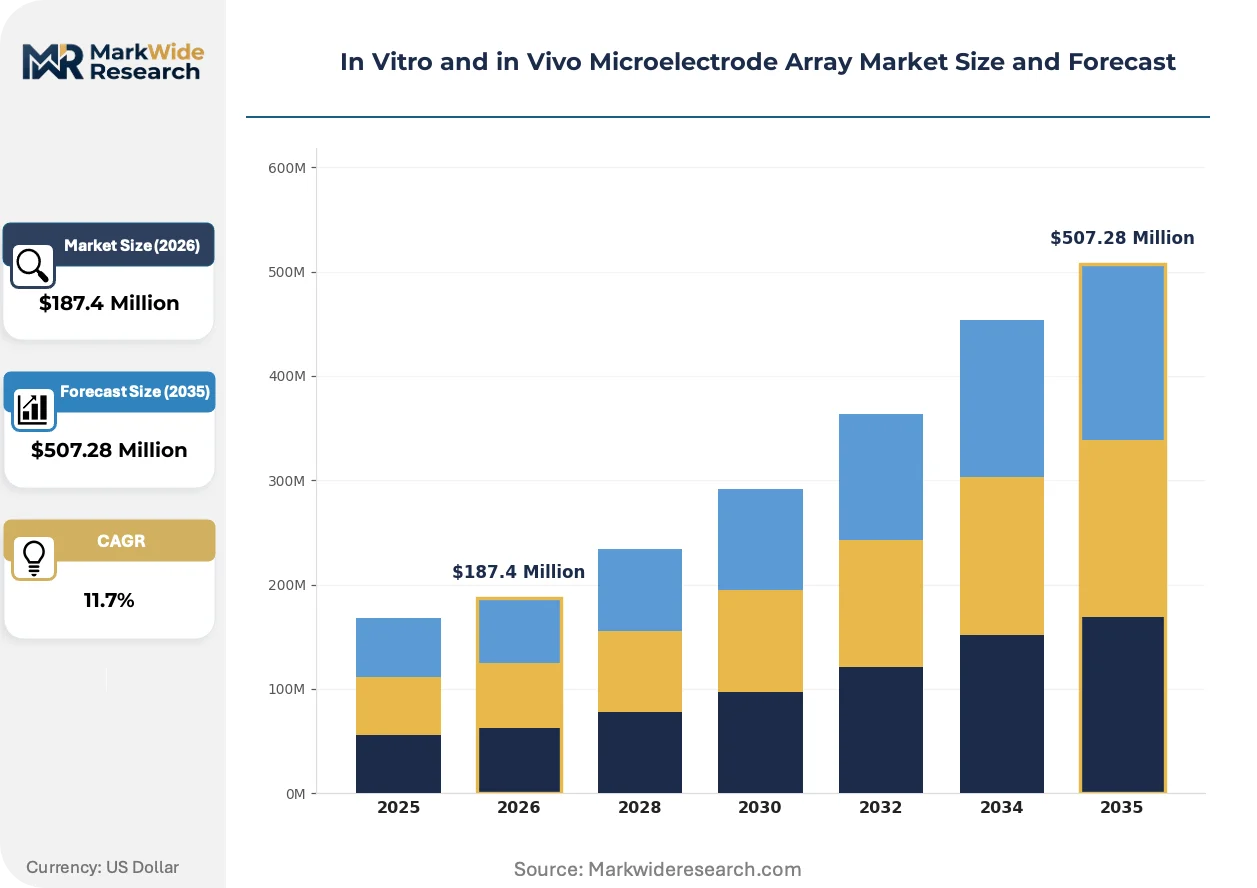
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
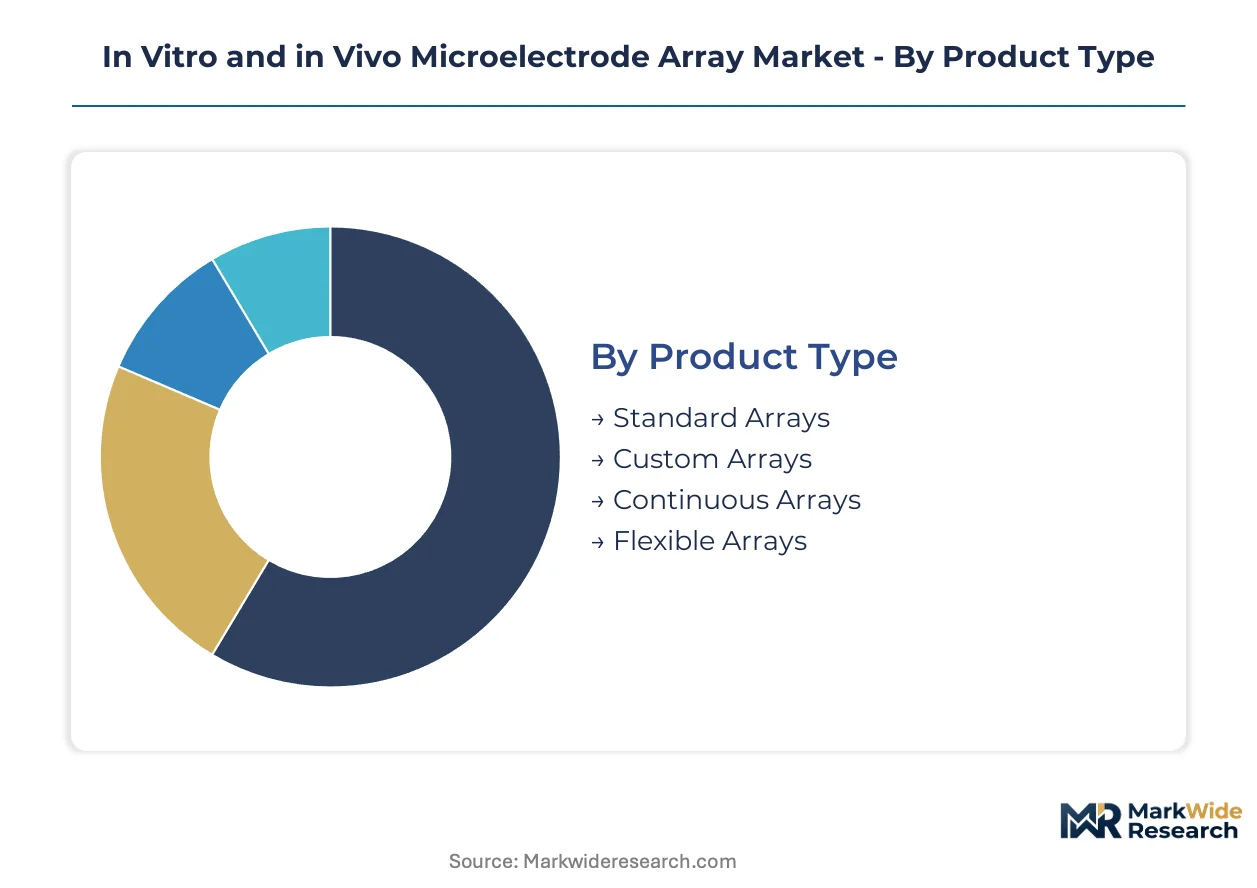
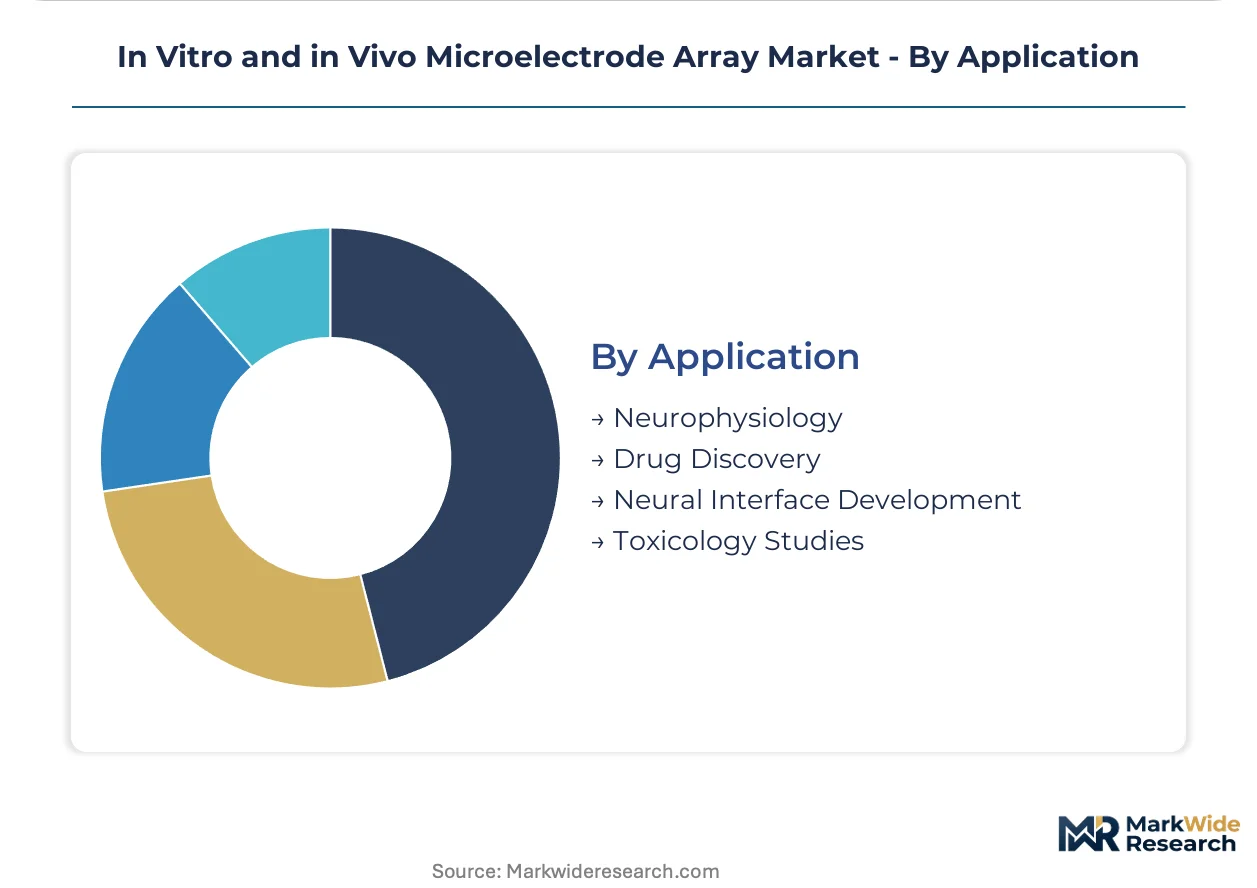
| Segmentation | Product Type: Standard Arrays, Custom Arrays, Continuous Arrays, Flexible Arrays Technology: Silicon-based, Glass-based, Polymeric, Metal-based End User: Academic Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Application: Neurophysiology, Drug Discovery, Neural Interface Development, Toxicology Studies |
| Companies Covered | Axion BioSystems Inc., 3Brain AG, MaxWell Biosystems AG, Multi Channel Systems MCS GmbH, NeuroNexus Technologies Inc., Blackrock Microsystems Inc., Alpha Omega Engineering Ltd., Harvard Bioscience Inc., Cambridge NeuroTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro and in Vivo Microelectrode Array Market Shifts & Advancements
Computational modeling and materials science advances are compressing the iteration cycle between electrode design and biological validation, reshaping how manufacturers prototype and commercialize new array geometries.
CMOS-integrated active pixel sensor technology is virtualizing traditional passive electrode architectures. Neurotechnology startups and academic spinouts in Switzerland and Germany adopt these high-density platforms for network-level recording. The shift is virtualizing the trade-off between channel count and signal fidelity that constrained earlier generations.
EU Medical Device Regulation implementation timelines are tightening clinical evidence requirements for implantable neural interfaces. Manufacturers must now compile biocompatibility and electrical safety documentation earlier in development. Class III device pathways in Germany and the Netherlands are absorbing the most significant procedural adjustments.
Pharmaceutical toxicology teams are consolidating supplier relationships around validated electrophysiology platforms with integrated data analysis pipelines. Multi-site preclinical studies in the United States and United Kingdom increasingly specify hardware-software bundles from single vendors. This preference shift favors integrated platform providers over component specialists in procurement decisions.
In Vitro and in Vivo Microelectrode Array Market Segmentation
Microelectrode array procurement cycles vary dramatically across segments, with pharmaceutical toxicology platforms requiring 18-24 month validation timelines while academic research labs refresh equipment every 3-5 years. Understanding these temporal patterns shapes inventory strategies and customer engagement models for manufacturers.
Product Type:
Replacement cycles stretch from months for consumable standard formats to years for validated custom platforms, creating divergent revenue recognition profiles across the portfolio.
- Standard Arrays:Off-the-shelf configurations with fixed electrode geometries and standardized connector interfaces. Pharmaceutical safety teams in the United States bulk-procure these for cardiotoxicity screening under compressed study timelines.
- Custom Arrays:Application-specific designs with modified electrode density, substrate dimensions, or metallization patterns. Academic neurotechnology clusters in Germany and Switzerland commission these for specialized neural circuit mapping protocols.
- Continuous Arrays:Extended linear or planar configurations for longitudinal tissue recording. Rodent chronic implantation studies drive demand from contract research organizations seeking uninterrupted signal acquisition.
- Flexible Arrays:Polyimide or parylene substrates enabling conformal tissue contact. Stretchable electronics manufacturing in South Korea and Japan accelerates availability for non-human primate motor cortex applications.
Standard arrays dominate installed base. Flexible arrays are where expansion concentrates.
Technology:
Cost tiers stratify sharply, with silicon CMOS platforms commanding 5-10x price multiples over glass substrates while polymeric alternatives capture mid-range positioning for chronic implantation.
- Silicon-based:CMOS-integrated active pixel sensors with thousands of recording channels per device. Taiwan-based foundry capacity constraints currently extend lead times for high-density neurotechnology procurement.
- Glass-based:Transparent substrates enabling concurrent optical imaging and electrical recording. MaxWell Biosystems AG leverages Zurich semiconductor heritage for precision fabrication of these hybrid platforms.
- Polymeric:Stretchable substrates of polyimide, PDMS, or parylene for conformal neural interfaces. FDA biocompatibility testing requirements under ISO 10993 extend development cycles for implantable variants.
- Metal-based:Pure metallic electrode arrays without semiconductor integration for specialized electrochemistry applications. Limited commercial presence outside niche fundamental research settings.
Silicon-based technology anchors revenue concentration. Polymeric platforms are climbing the fastest.
End User:
Customer sophistication tiers separate validation-capable pharmaceutical buyers from price-sensitive academic laboratories, with biotechnology firms occupying an intermediate position on procurement rigor.
- Academic Research Institutions:NIH Brain Initiative funding sustains United States university procurement of high-density recording platforms. Publication-driven refresh cycles prioritize novel capabilities over total cost optimization.
- Pharmaceutical Companies:GLP-validated toxicology workflows demand integrated hardware-software bundles with audit trails. Multi Channel Systems MCS GmbH anchors this segment through certified electrophysiology platforms.
- Biotechnology Firms:Cell therapy developers and gene editing specialists adopt arrays for phenotypic screening. Venture-funded startups in Cambridge and South San Francisco concentrate emerging demand.
- Contract Research Organizations:Outsourced preclinical safety studies require rapid assay deployment across multiple sponsor programs. EU Medical Device Regulation harmonization reduces validation burden for cross-border studies in Germany and the Netherlands.
Academic institutions command channel volume. Pharmaceutical companies drive margin expansion.
Application:
Maturity gradients separate established neurophysiology workflows from emerging neural interface development, with regulatory exposure varying dramatically across use cases.
- Neurophysiology:Fundamental circuit mapping and cellular electrophysiology research. Multi Channel Systems MCS GmbH and 3Brain AG compete for slice recording and dissociated culture applications.
- Drug Discovery:High-throughput cardiotoxicity and neurotoxicity screening displacing patch-clamp methods. FDA Good Laboratory Practice standards constrain supplier qualification to validated platform vendors.
- Neural Interface Development:Brain-machine interface prototyping for motor prosthesis and communication aids. DARPA-funded programs in the United States accelerate chronic implantable array procurement.
- Toxicology Studies:Regulatory safety assessment under OECD and ICH guidelines. Pharmaceutical toxicology budgets are expanding while silicon foundry capacity remains constrained.
Neurophysiology anchors historical revenue. Neural interface development shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan constrains substrate access for CMOS array fabrication, while pharmaceutical toxicology demand accelerates across multiple jurisdictions. NIH-funded neurotechnology clusters in the United States and EU Medical Device Regulation harmonization in Germany and the Netherlands reshape procurement patterns. Stretchable electronics manufacturing in South Korea and Japan enables conformal neural interface development.
United States
NIH Brain Initiative funding sustains academic procurement of high-density recording platforms for neural circuit mapping. FDA device classification pathways compress development timelines for novel neural interface devices. Greater Boston and San Francisco Bay Area clusters concentrate DARPA-funded brain-machine interface prototyping programs.
Germany
EU Medical Device Regulation harmonization streamlines CE marking for implantable neural interfaces across German manufacturing bases. MaxWell Biosystems AG leverages Zurich-based engineering heritage for precision CMOS array production. Baden-Württemberg and North Rhine-Westphalia anchor electrophysiology instrumentation supply chains.
Switzerland
Swissmedic oversight of Class III neural interface devices tightens clinical evidence requirements for chronic implantation studies. 3Brain AG differentiates through proprietary high-resolution microelectrode technology for in vitro neural networks. Zurich and Basel neurotechnology clusters concentrate CMOS-integrated active pixel sensor development.
South Korea
Stretchable electronics manufacturing enables polyimide substrate production for conformal neural interfaces in rodent and non-human primate models. MFDS biocompatibility standards under ISO 10993 extend validation cycles for implantable variants. Seoul Capital Area fabs accelerate flexible array availability for chronic motor cortex applications.
Japan
METI-supported advanced materials programs advance titanium nitride thin-film deposition for electrode longevity in longitudinal preclinical research. PMDA consultation pathways guide neural interface developers through clinical translation requirements. Tokyo-Osaka industrial corridors concentrate precision metallurgy capabilities for electrogenic cell stimulation platforms.
In Vitro and in Vivo Microelectrode Array Market Competitive Landscape
Integrated platform providers and specialized component fabricators split the market between validated toxicology workflows and customizable research instrumentation. The vendor base concentrates around hardware-software bundles for pharmaceutical GLP studies and high-density CMOS arrays for academic neural circuit mapping. Three archetypes dominate: semiconductor-heritage precision manufacturers, electrophysiology instrumentation integrators, and flexible substrate specialists. Competitive moves center on foundry partnerships for silicon capacity access and regulatory pre-certification for EU MDR compliance.
Among Swiss and German precision manufacturers, MaxWell Biosystems AG and 3Brain AG exemplify the semiconductor-heritage archetype, while Multi Channel Systems MCS GmbH anchors the instrumentation-integrator tier. These entities occupy positions spanning Zurich-based CMOS fabrication, high-resolution neural network technology, and certified electrophysiology platforms for pharmaceutical toxicology. Their geographic concentration reflects European neurotechnology funding intensification and the region's regulatory harmonization advantages.
| Leading Market Players |
|---|
| Axion BioSystems Inc. |
| 3Brain AG |
| MaxWell Biosystems AG |
| Multi Channel Systems MCS GmbH |
| NeuroNexus Technologies Inc. |
| Blackrock Microsystems Inc. |
| Alpha Omega Engineering Ltd. |
| Harvard Bioscience Inc. |
| Cambridge NeuroTech |
| Others |
Supply & Pricing Matrix
Taiwan-based foundry concentration for CMOS array fabrication creates single-source vulnerability that simultaneously compresses pricing flexibility for high-density platforms and forces buyers toward multi-year supply contracts with embedded cost escalation clauses. Pharmaceutical toxicology teams absorb premium pricing for GLP-validated platforms while academic laboratories face extended lead times that reshape procurement calendars.
Pricing Analysis
FDA Good Laboratory Practice standards dictate the pricing tier structure across the In Vitro and in Vivo Microelectrode Array Market, separating validated toxicology platforms from research-grade instrumentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and audit trail completeness. Cost compression in standard arrays is intensifying because silicon wafer supply constraints force foundry customers into volume-commitment contracts. Academic research institutions exhibit highest price sensitivity, while pharmaceutical safety teams prioritize validation documentation over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit substrate access for CMOS-integrated arrays, constraining supply chain flexibility across the In Vitro and in Vivo Microelectrode Array Market. Taiwan, South Korea, and the United States anchor high-density array production, drawing from platinum-iridium oxide metallurgy, polyimide substrate films, and precision connector assemblies. Single-source vulnerability around Taiwan-based foundry capacity threatens continuity for active pixel sensor platforms. Distribution runs through direct OEM relationships for pharmaceutical buyers and academic distributors for research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The In Vitro and in Vivo Microelectrode Array Market operates as a regulatory-entrenchment defensive moat, where ISO 10993 biocompatibility certification and GLP validation timelines create switching costs that protect incumbent positions against new entrants.
For Market Incumbents: Entrench through backward integration into platinum-iridium oxide thin-film deposition capabilities, reducing dependency on external metallurgy suppliers. Pursue EU Medical Device Regulation pre-certification for implantable array portfolios before competitors complete documentation cycles. Capacity addition in South Korea for polyimide substrate manufacturing addresses stretchable electronics demand while diversifying geographic production footprint. For New Entrants and Emerging Players: Build out flexible array specialization for rodent chronic implantation studies, where established vendors maintain lighter coverage. Target contract research organizations in Germany and the Netherlands seeking rapid assay deployment with reduced validation burden. A hardware-software bundled go-to-market angle displaces component specialists in pharmaceutical procurement decisions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors semiconductor-heritage precision manufacturers with captive foundry relationships. Long-term viability rests on chronic implantation applications requiring multi-year electrode stability, where materials science differentiation compounds competitive advantage. Watch FDA breakthrough device designation velocity for neural interface technologies as inflection indicator for clinical translation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Pre-Certification Investment | Streamlines CE marking pathways for implantable neural interfaces across German and Swiss manufacturing bases. |
| Foundry Partnership Structuring | Secures Taiwan-based CMOS capacity access against supply concentration risks for high-density array production. |
| GLP Laboratory Certification | Enables pharmaceutical toxicology procurement under FDA Good Laboratory Practice standards with audit trail documentation. |
| Flexible Substrate Manufacturing Scale-Up | Accelerates polyimide array availability for South Korean and Japanese stretchable electronics production. |
| Integrated Platform Development | Consolidates hardware-software bundles that pharmaceutical safety teams specify for multi-site preclinical studies. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with electrophysiology platform directors, biomedical engineering procurement leads, GLP laboratory managers, and neural interface regulatory affairs specialists; and secondary validation against FDA 510(k) filings, ISO 10993 biocompatibility documentation, NIH Brain Initiative funding disclosures, and EU Medical Device Regulation implementation guidance. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates.
Forecast inputs span product type, technology substrate, end-user sophistication tier, and application maturity across the projection horizon. CAGRs were derived from regression analysis against NIH funding trajectories, pharmaceutical toxicology budget expansion, and silicon foundry capacity utilization. Modeled variables include Brain Initiative appropriation levels, FDA breakthrough device designation velocity, and stretchable electronics manufacturing yield improvements.
Stress conditions across Taiwan foundry access restrictions, platinum commodity volatility, and EU MDR implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization timelines and chronic implantation safety study completion rates. Cross-checking against NIH RePORTER expenditure data and pharmaceutical R&D disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mediastinoscope Market
Medical Devices
Gracey Curette Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Medical Electrodes Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Global Self Care Medical Devices Market