
 Facial Implant Market | 2026-2036
Facial Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Implant Market Intelligence
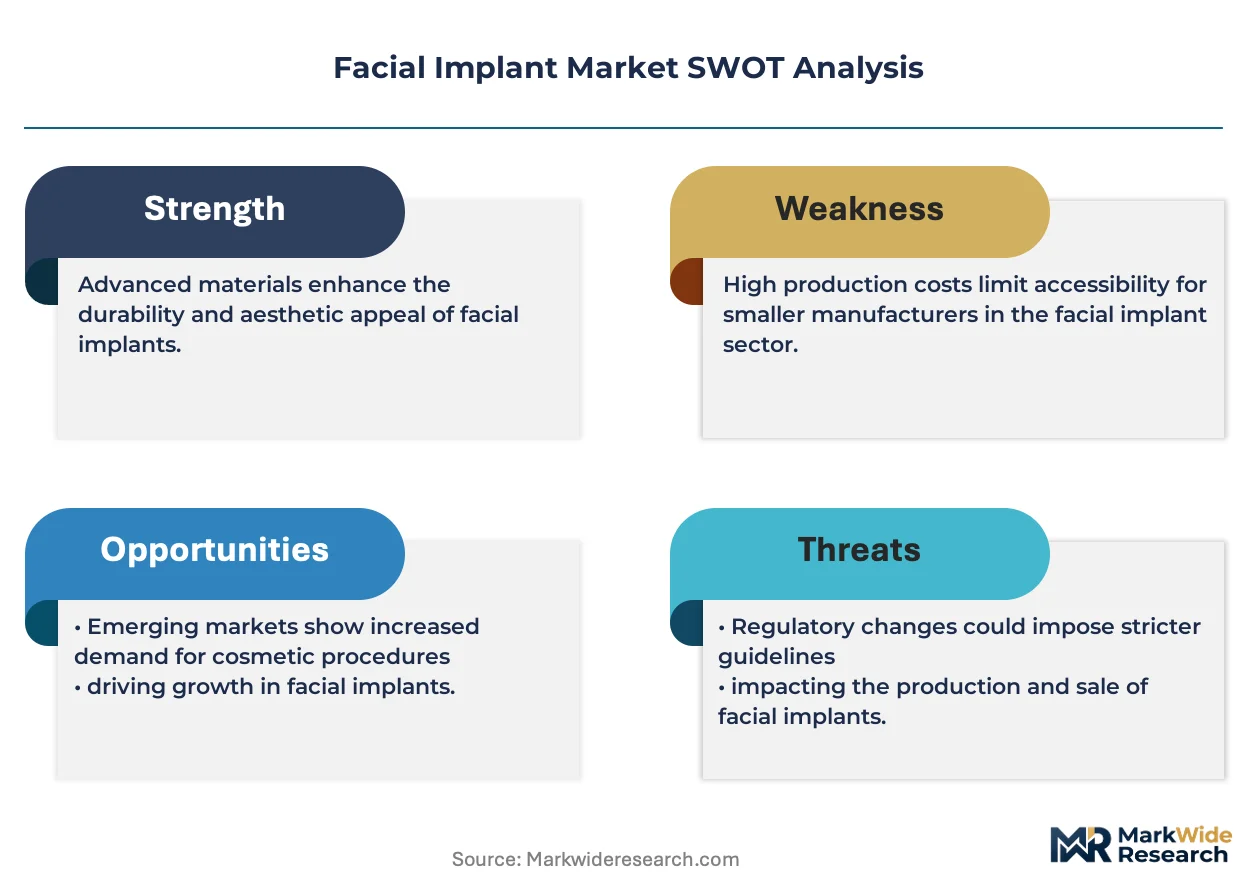
Premium-grade biocompatibility certification is bifurcating the competitive landscape into implant suppliers capable of meeting ISO 10993 cytotoxicity standards versus those confined to lower-tier hospital contracts. Stryker leverages its orthopedic polymer expertise to sustain leadership in craniofacial reconstruction hardware. Medartis AG specializes in patient-specific titanium implants through additive manufacturing workflows, while Zimmer Biomet anchors its position via integrated digital surgical planning platforms.
Facial implants are permanent or semi-permanent prosthetic devices surgically placed to restore craniofacial structure, augment aesthetic contours, or reconstruct defects from trauma or oncologic resection; most polymer variants achieve Shore A durometer readings of 20-40 to mimic soft tissue compliance while maintaining dimensional stability under cyclic loading. Silicone implants occupy the largest revenue pool due to decades of surgical familiarity and reversible placement protocols, though hydroxyapatite variants represent the fastest-growing category as osseointegration performance becomes a decisive procurement criterion for maxillofacial surgeons. Aesthetic surgery applications command premium pricing relative to trauma repair, where hospital procurement committees compress margins through standardized tender processes.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) impose escalating clinical evidence requirements on novel implant surfaces, effectively filtering market access toward manufacturers with dedicated regulatory affairs infrastructure. The EU AI Act introduces additional scrutiny for algorithmic tools used in preoperative implant sizing, compelling vendors to validate machine-learning outputs against clinical outcomes. Stakeholders must monitor how reimbursement authorities in Germany, France, and Japan calibrate procedural codes for patient-specific implants versus off-the-shelf alternatives.
Market Dynamics
Patient-specific implant fabrication via additive manufacturing is compressing lead times from weeks to days while forcing traditional silicone suppliers to defend their standard catalog positions against titanium lattice structures.
Growth Catalysts
- EU MDR clinical evidence pathways:Manufacturers with dedicated regulatory infrastructure capture preferential market access as notified bodies tighten ISO 10993 biocompatibility scrutiny for novel polymer surfaces.
- Cosmetic surgery clinic consolidation:Specialized maxillofacial centers in Seoul and Los Angeles drive procedural volume through integrated digital surgical planning workflows that bundle implant selection with preoperative visualization.
- Hydroxyapatite osseointegration performance:Maxillofacial surgeons increasingly specify ceramic-coated titanium for trauma reconstruction, displacing reversible silicone protocols in permanent facial contouring cases.
Market Restraints
- Medical-grade silicone feedstock concentration:Three chemical suppliers control pharmaceutical-grade elastomer supply, exposing implant manufacturers to input cost volatility when specialty polymer capacity tightens.
- FDA 510(k) predicate device limitations:Novel lattice geometries face extended review timelines when no substantially equivalent prior submission exists, delaying revenue recognition for patient-specific implant innovators.
- Non-surgical facial augmentation alternatives:Hyaluronic acid filler formulations with 18-24 month durability capture budget-conscious aesthetic patients who previously considered permanent implant placement.
Strategic Opportunities
- Brazilian private healthcare expansion:ANVISA streamlined registration pathways for CE-marked devices create first-mover advantage for European implant manufacturers targeting São Paulo's cosmetic surgery corridor.
- AI-assisted preoperative sizing tools:The EU AI Act mandates clinical outcome validation for algorithmic implant selection, rewarding vendors who integrate machine-learning outputs with postoperative complication tracking.
- Telemedicine-enabled remote consultation:Digital patient acquisition channels bypass traditional referral networks between plastic surgeons and maxillofacial specialists, compressing patient decision cycles for elective procedures.
Industry Challenges
- Additive manufacturing technician scarcity:Patient-specific titanium fabrication requires certified operators for electron beam melting systems, constraining production scale-up at mid-tier implant suppliers.
- Legacy ERP integration with digital surgical platforms:Hospital procurement systems struggle to reconcile case-by-case implant pricing with standardized tender workflows, creating billing friction for custom-manufactured devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Implant Market |
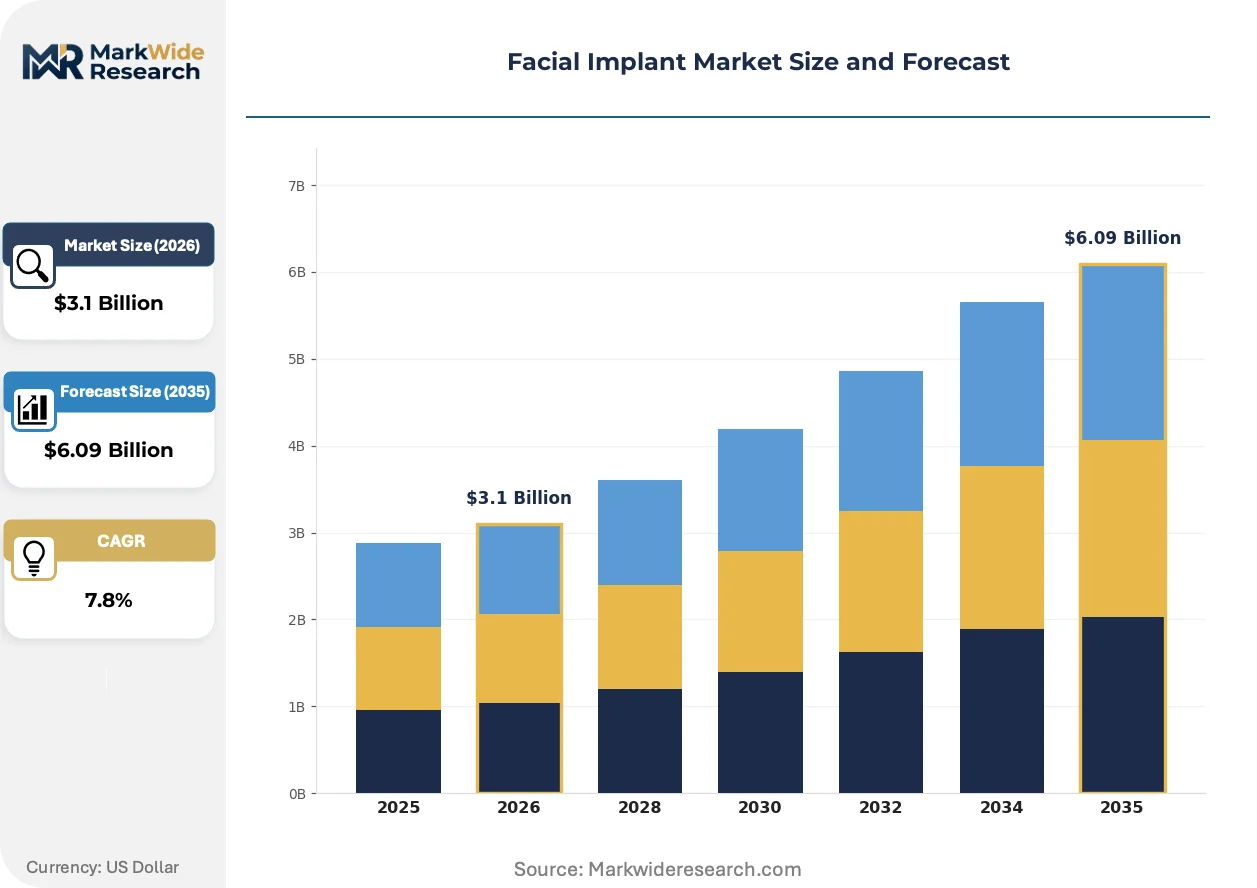
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Implants, Composite Implants, Hydroxyapatite Implants, Gore-Tex Implants Application: Reconstructive Surgery, Aesthetic Surgery, Maxillofacial Surgery, Trauma Repair End User: Hospitals, Cosmetic Surgery Clinics, Ambulatory Surgical Centers, Research Laboratories Material: Polymers, Metals, Ceramics, Biocompatible Materials |
| Companies Covered | Zimmer Biomet, Stryker, Johnson & Johnson, Medartis AG, KLS Martin Group, Integra LifeSciences, OsteoMed, DePuy Synthes, Sientra Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Implant Market Strategic Shifts & Innovations
Computational design tools and biomaterial surface engineering are converging to collapse the traditional boundary between off-the-shelf implant catalogs and patient-matched reconstruction hardware.
Lattice-structured titanium cranial plates is decomposing the historical trade-off between implant strength and tissue integration. Maxillofacial centers in Germany and South Korea now specify porous architectures with 300-500 micron pore sizes for vascularized bone ingrowth. This topology optimization is decomposing the market share of solid silicone chin and cheek implants in trauma reconstruction.
REACH substance restrictions on residual catalysts in medical polymers are forcing silicone manufacturers to reformulate platinum-cured elastomers. The ECHA evaluation of siloxane bioaccumulation has triggered supply chain audits across implant molders serving European aesthetic clinics. German notified bodies now require migration testing data that many Asian polymer suppliers cannot furnish, compressing their CE-marking success rates.
Subscription-based implant inventory models are displacing capital purchase arrangements at multi-site cosmetic surgery groups. United States clinic chains now demand vendor-managed consignment stock for high-value patient-specific titanium devices, transferring working capital burden to manufacturers. This financing structure concentrates procurement leverage with Stryker and Zimmer Biomet, whose balance sheets absorb extended payment terms that smaller additive manufacturing specialists cannot match.
Facial Implant Market Segmentation
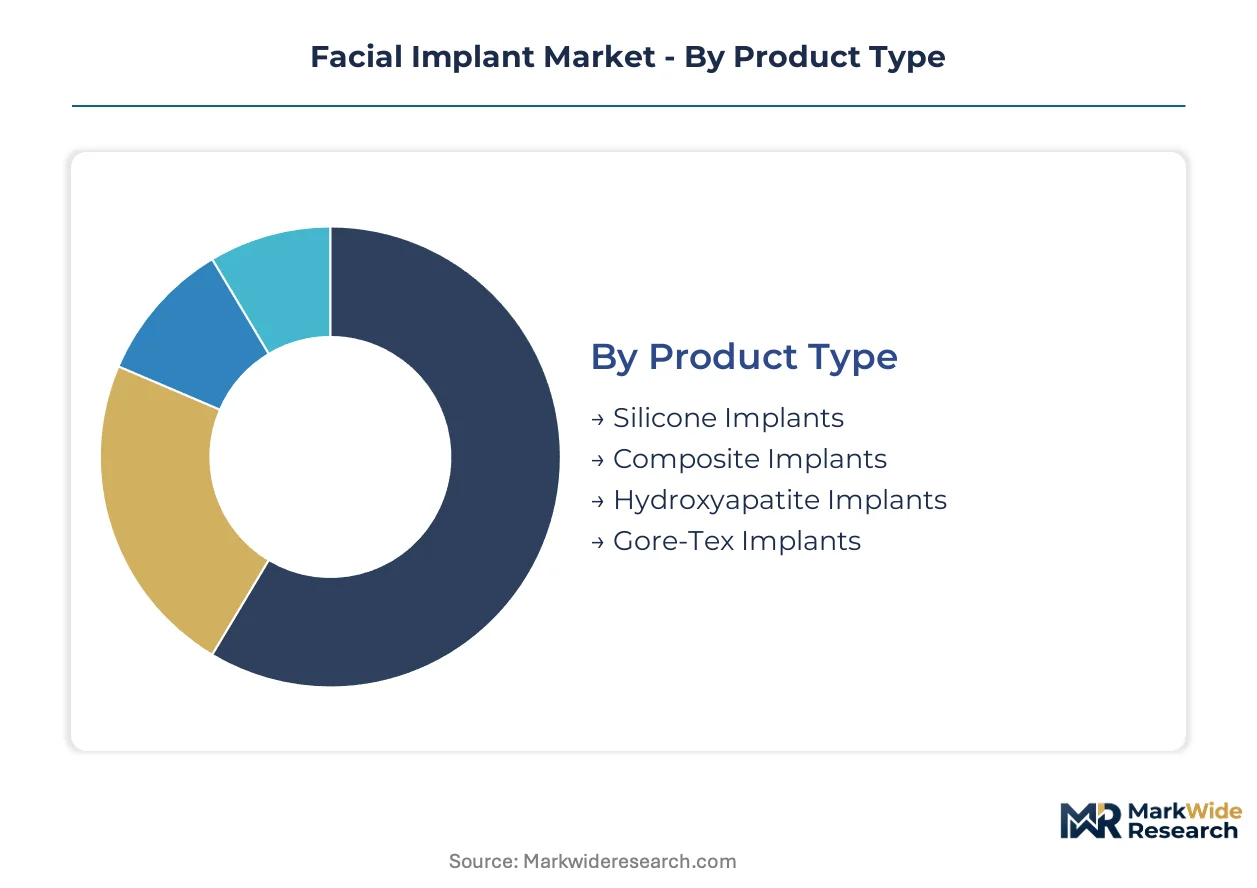
Facial implant segmentation reveals how procurement authority and clinical setting reshape margin capture across material technologies. Surgeons, hospital committees, and clinic owners each impose distinct validation and pricing logics that fragment supplier strategies.
Product Type:
Silicone implants command premium pricing in aesthetic channels where reversibility and surgical familiarity justify elevated unit economics, while hydroxyapatite variants extract value through osseointegration performance in permanent reconstruction cases.
- Silicone Implants:Medical-grade elastomer formulations achieve Shore A durometer readings of 20-40 to replicate soft tissue compliance. Demand concentrates in Los Angeles and Seoul cosmetic surgery corridors where reversible placement protocols reduce patient hesitation. FDA 510(k) predicate device pathways sustain rapid product iteration for established suppliers.
- Hydroxyapatite Implants:Ceramic-coated surfaces enable direct bone apposition without fibrous encapsulation. German and South Korean maxillofacial centers specify these for trauma reconstruction where permanent integration eliminates revision risk. The EU MDR's biocompatibility scrutiny favors manufacturers with ISO 10993 cytotoxicity documentation.
- Composite Implants:Hybrid polymer-ceramic structures balance mechanical strength with biological acceptance.
- Gore-Tex Implants:Expanded polytetrafluoroethylene sheets serve nasal dorsal augmentation with reduced capsule formation.
Silicone implants hold installed capacity. Hydroxyapatite implants are rotating up the share rankings.
Application:
Volume concentrates in trauma repair where hospital procurement committees compress margins through standardized tenders, while aesthetic surgery commands price premiums through direct patient payment.
- Aesthetic Surgery:Elective chin, cheek, and jawline augmentation generates the highest unit margins as patients pay out-of-pocket. Seoul's Gangnam district and Beverly Hills clinic clusters bundle digital surgical planning with implant selection to justify premium positioning.
- Reconstructive Surgery:Post-oncologic and congenital defect correction requires patient-specific hardware. Medartis AG and Stryker compete through additive manufacturing workflows that collapse lead times from weeks to days.
- Maxillofacial Surgery:Orthognathic procedures combine functional correction with aesthetic outcomes.
- Trauma Repair:Emergency craniofacial fracture management prioritizes inventory availability over customization.
Trauma repair holds installed capacity. Aesthetic surgery is climbing the fastest.
End User:
Procurement leverage varies sharply across settings, with cosmetic surgery clinics demanding vendor-managed consignment while hospitals enforce capital purchase discipline.
- Cosmetic Surgery Clinics:Multi-site chains in São Paulo and Dubai now require subscription-based inventory models that transfer working capital burden to manufacturers. Stryker and Zimmer Biomet absorb extended payment terms that smaller additive manufacturing specialists cannot match.
- Hospitals:Maxillofacial centers at academic medical centers in Germany and the United States drive procedural volume through integrated digital surgical planning platforms.
- Ambulatory Surgical Centers:Same-day discharge protocols favor minimally invasive implant placement techniques.
- Research Laboratories:Biomaterial surface engineering studies advance lattice topology optimization for vascularized bone ingrowth.
Hospitals hold installed capacity. Cosmetic surgery clinics are gaining share fastest.
Material:
Supply concentration in pharmaceutical-grade silicone feedstock exposes manufacturers to input cost volatility, while titanium lattice fabrication requires scarce electron beam melting technician certification.
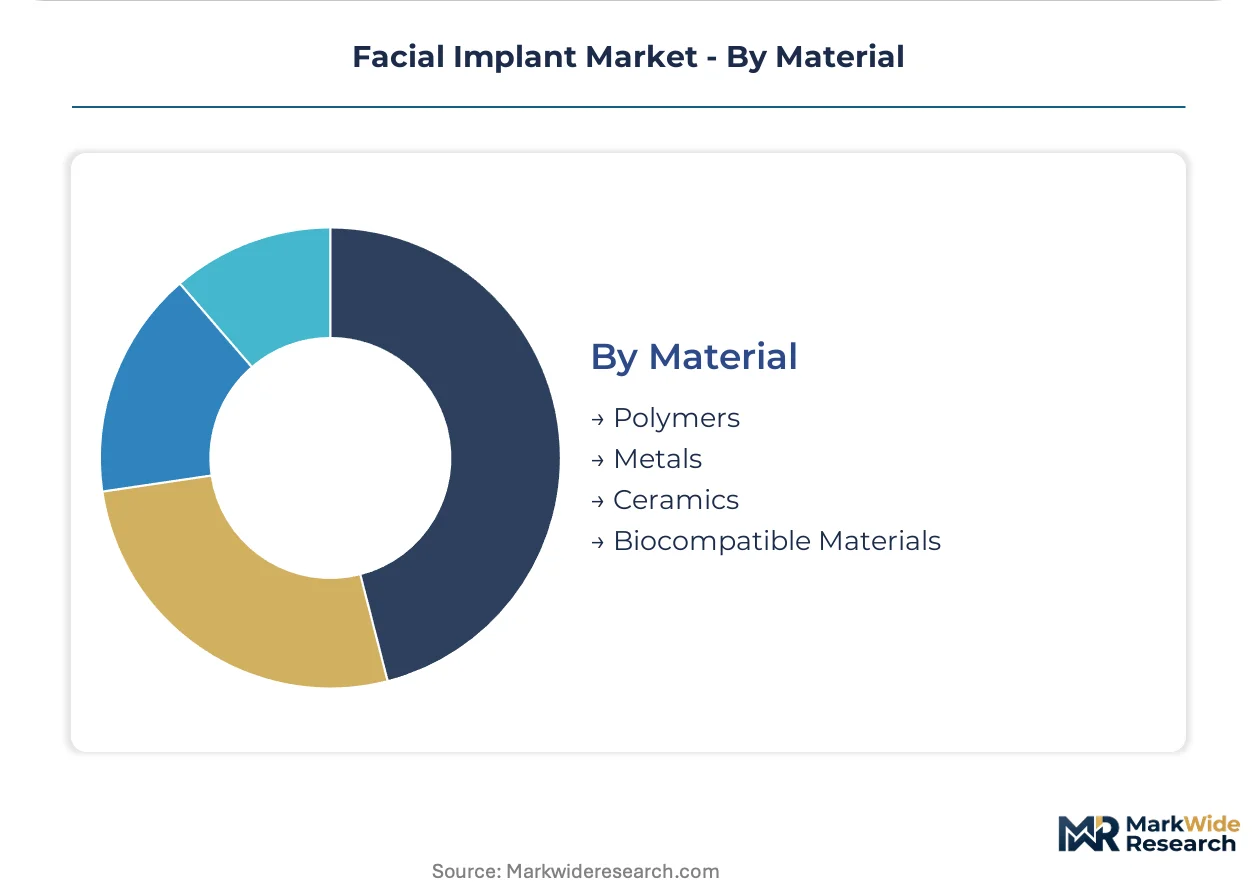
- Polymers:Platinum-cured silicone elastomers dominate aesthetic applications. REACH substance restrictions on residual catalysts force reformulation audits across European supply chains, with German notified bodies now requiring migration testing data many Asian polymer suppliers cannot furnish.
- Metals:Additive-manufactured titanium cranial plates with 300-500 micron pore sizes enable vascularized bone ingrowth. Patient-specific fabrication compresses lead times while forcing traditional silicone suppliers to defend standard catalog positions.
- Ceramics:Hydroxyapatite coatings accelerate osseointegration performance.
- Biocompatible Materials:ISO 10993 validation tiers bifurcate suppliers into premium certification holders versus lower-tier hospital contract competitors.
Polymers hold installed capacity. Metals are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade silicone feedstock concentrates among three chemical suppliers, exposing implant manufacturers to input cost volatility when specialty polymer capacity tightens. This supply concentration shapes regional procurement leverage across the United States, Germany, South Korea, Brazil, and Japan.
United States
FDA 510(k) clearance pathways drive procedural volume through Los Angeles and Beverly Hills cosmetic surgery corridors where reversible silicone protocols reduce patient hesitation. The FDA's predicate device requirements sustain rapid product iteration for established suppliers with dedicated regulatory infrastructure. Academic medical centers in Greater Boston and the Pacific Northwest anchor maxillofacial reconstruction demand through integrated digital surgical planning platforms.
Germany
EU MDR biocompatibility scrutiny and ISO 10993 cytotoxicity standards filter market access toward manufacturers with dedicated regulatory affairs infrastructure. ECHA's REACH substance restrictions on residual catalysts force reformulation audits across silicone supply chains. Notified bodies in Bavaria and Baden-Württemberg now require migration testing data that compresses CE-marking success rates for Asian polymer suppliers.
South Korea
MFDS oversight and Seoul's Gangnam district cosmetic surgery clusters generate premium pricing for elective chin and cheek augmentation. Patient preference shifts toward minimally invasive facial contouring strengthen demand from specialized maxillofacial centers. The Busan-Ulsan corridor anchors additive manufacturing capacity for patient-specific titanium lattice structures with 300-500 micron pore sizes.
Brazil
ANVISA streamlined registration pathways for CE-marked devices create first-mover advantage for European implant manufacturers targeting São Paulo's cosmetic surgery corridor. Private healthcare expansion concentrates procurement leverage with multi-site clinic chains demanding vendor-managed consignment stock. Rio de Janeiro and Minas Gerais surgical centers drive procedural volume through subscription-based inventory models that transfer working capital burden to manufacturers.
Japan
PMDA clinical evidence requirements and METI industrial policy shape procurement patterns for hydroxyapatite-coated titanium in permanent reconstruction cases. The Kanto/Tokyo region anchors demand from academic medical centers specifying ceramic-coated surfaces for trauma reconstruction. Osaka-based maxillofacial surgeons increasingly specify osseointegration performance as a decisive procurement criterion, displacing reversible silicone protocols.
Facial Implant Market Key Industry Players
Concentration sits with diversified orthopedic conglomerates and patient-specific additive manufacturing specialists. The market structures around three tiers: established suppliers with dedicated FDA regulatory infrastructure, mid-tier additive manufacturing specialists constrained by electron beam melting technician scarcity, and Asian polymer molders facing REACH compliance barriers. Dominant competitive moves include subscription-based inventory models at multi-site cosmetic surgery groups and backward integration into pharmaceutical-grade silicone feedstock.
Among diversified orthopedic conglomerates, Stryker and Zimmer Biomet occupy positions sustained by balance sheet capacity to absorb extended payment terms that smaller specialists cannot match. Medartis AG represents the patient-specific fabrication archetype, anchoring competitive positioning through additive manufacturing workflows that collapse lead times from weeks to days. These three companies exemplify how regulatory infrastructure and manufacturing scale bifurcate market access under tightening FDA and EU MDR clinical evidence requirements.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| Johnson & Johnson |
| Medartis AG |
| KLS Martin Group |
| Integra LifeSciences |
| OsteoMed |
| DePuy Synthes |
| Sientra Inc. |
| Others |
Cost & Logistics Intelligence
Vendor-managed consignment contracts for patient-specific titanium implants lock in supply access for multi-site cosmetic surgery chains while transferring working capital burden to manufacturers with balance sheet capacity. This financing structure concentrates procurement leverage with diversified orthopedic conglomerates who absorb extended payment terms that smaller additive manufacturing specialists cannot match.
Pricing Analysis
EU MDR biocompatibility scrutiny dictates the pricing tier structure across the facial implant market. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified suppliers from lower-tier hospital contract competitors and uncertified Asian polymer molders. Cost compression in standard silicone segments is intensifying because REACH substance restrictions on residual catalysts force reformulation audits. Hospital procurement committees exhibit highest price sensitivity through standardized tender processes, while cosmetic surgery clinics in Seoul and Los Angeles demonstrate lowest sensitivity due to direct patient payment models.
Supply Chain Analysis
Germany and South Korea anchor pharmaceutical-grade silicone feedstock and additive manufacturing capacity for patient-specific titanium lattice structures. Medical-grade elastomer supply draws from three chemical suppliers controlling specialty polymer production, while electron beam melting systems for porous cranial plates rest on certified technician availability. Single-source vulnerability concentrates in platinum-cured silicone feedstock when capacity tightens. Distribution runs through vendor-managed inventory models at multi-site cosmetic surgery groups and capital purchase arrangements at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam melting technician certification scarcity constrains production scale-up at mid-tier suppliers, bifurcating market access between balance-sheet-capable conglomerates and constrained specialists. This capability gap shapes competitive positioning across patient-specific fabrication and standard catalog defense.
For Market Incumbents: Shield market position through backward integration into pharmaceutical-grade silicone feedstock and captive certification programs for electron beam melting operators. Regulatory infrastructure investment at FDA and notified bodies creates defensive moats against emerging additive manufacturing specialists. Capacity reservation agreements with German and South Korean titanium powder suppliers secure input access. For New Entrants and Emerging Players: Digital surgical planning software integration represents a service-layer gap where incumbents under-serve mid-tier cosmetic surgery clinics. Telemedicine-enabled remote consultation channels in São Paulo's private healthcare expansion offer penetrable white-space targeting. ANVISA streamlined registration pathways provide go-to-market acceleration for CE-marked device portfolios. For Investors and Strategic Acquirers: Capital is best deployed toward patient-specific additive manufacturing specialists with electron beam melting technician pipelines and ISO 10993 documentation infrastructure. Long-term viability across the analysis window hinges on regulatory affairs capabilities tightening under FDA 510(k) and EU MDR pathways. Watch for consolidation signals when smaller specialists face working capital constraints from vendor-managed consignment demands.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR biocompatibility scrutiny filters market access toward prepared manufacturers. |
| Hospital System Partnership | Integrated digital surgical planning platforms at German maxillofacial centers drive volume. |
| Software Companion Development | AI-assisted preoperative sizing tools require EU AI Act clinical outcome validation. |
| Reimbursement Strategy | German, French, and Japanese authorities calibrate procedural codes for patient-specific implants. |
| FDA Submission Advancement | Predicate device pathways sustain rapid iteration for established regulatory infrastructure holders. |
Research Approach
Cross-validation between primary interviews with maxillofacial surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare procedural data. Bottom-up demand modeling across implant material technologies and top-down macroeconomic triangulation ensures consistency across value estimates.
Sensitivity analysis around electron beam melting capacity constraints and REACH substance restriction timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material technology, application setting, end-user procurement authority, and regional regulatory cluster. CAGRs derive from procedure volume trajectories and unit economics by certification tier, with hydroxyapatite osseointegration performance and silicone reversibility protocols as key forecast inputs.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR biocompatibility scrutiny, and ANVISA registration frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include ECHA siloxane bioaccumulation evaluations, MFDS oversight changes, and additive manufacturing technician availability constraints. Recalibration cycles align with material shifts in notified body interpretation, reimbursement authority decisions, and feedstock capacity utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Portable OT Light Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Patient Lift Slings Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Venous Device Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Power Smart Bed Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
Peripheral Nerve Stimulators Market