
 Industrial Endoscope Market | 2026-2036
Industrial Endoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Endoscope Market Outlook
Specialized industrial distributors is reconfiguring how endoscope manufacturers reach maintenance providers and field technicians across fragmented demand pockets. Olympus Corporation leverages its optical heritage to sustain premium positioning in aerospace inspection channels. Karl Storz SE & Co. KG anchors its European presence through rigid endoscope specialization for automotive and energy applications. FUJIFILM Corporation competes by extending CMOS-based video platforms into manufacturing quality assurance workflows.
An industrial endoscope is a remote visual inspection instrument comprising a lens system, image sensor, and flexible or rigid insertion tube, typically measuring 2 to 10 millimeters in diameter, designed to access confined spaces without disassembling machinery or infrastructure. Fiber optic variants transmit images through coherent glass bundles, while CMOS and CCD technologies convert optical signals into digital outputs for real-time display and documentation. Video endoscope systems command the strongest margin pools due to integrated software analytics and data archiving capabilities. Flexible endoscopes dominate energy sector demand for pipeline and turbine inspections where curved pathways prevent rigid instrument access. Wireless technology adoption is accelerating among field technicians requiring untethered maneuverability in hazardous or elevated environments.
FDA oversight governs medical-adjacent industrial applications where endoscopes contact sterile process equipment, while OSHA mandates drive inspection frequency in US manufacturing and energy facilities. CE marking under EU machinery directives shapes product design requirements for European OEM and maintenance provider procurement. Germany's KBA influences automotive inspection standards that propagate through supplier networks. Stakeholders must monitor how evolving CMOS resolution specifications and wireless cybersecurity protocols reshape competitive differentiation and compliance thresholds.
Market Dynamics
CMOS sensor architectures are compressing equipment replacement cycles across aerospace and automotive inspection channels, forcing manufacturers to recalibrate platform roadmaps and service revenue models around shorter hardware lifespans.
Growth Catalysts
- OSHA inspection mandates:US manufacturing and energy facilities face expanded documentation requirements for confined-space entry protocols, elevating endoscope deployment frequency in preventive maintenance schedules.
- Wireless tether elimination:Field technicians in elevated or hazardous environments demand untethered maneuverability, accelerating battery-powered probe adoption where cable management previously constrained access.
- Germany's KBA quality protocols:Automotive OEM supplier networks propagate tighter visual inspection standards downstream, mandating video documentation capabilities that fiber-optic systems cannot satisfy.
Market Restraints
- CMOS sensor supply concentration:Advanced image sensor fabrication clusters in East Asian foundries expose equipment manufacturers to geopolitical supply disruption risks and extended lead times.
- Fiber-optic stranded asset risk:Maintenance providers holding legacy coherent glass bundle inventories face accelerated obsolescence as digital video platforms capture margin-rich documentation contracts.
- CE marking compliance costs:EU machinery directive certification timelines and testing expenditures create friction for smaller manufacturers seeking European market entry.
Strategic Opportunities
- India PLI scheme alignment:Domestic manufacturing incentives for precision equipment create localized assembly opportunities serving South Asian energy and infrastructure inspection demand.
- AI-assisted defect recognition:Machine vision algorithms integrated into video endoscope platforms enable real-time anomaly flagging, compressing analysis time for non-destructive testing technicians.
- Rental and subscription channels:Project-based inspection providers in construction and maritime sectors prefer operational expenditure models over capital equipment ownership.
Industry Challenges
- Technician certification bottlenecks:ASNT and PCN qualification requirements for remote visual inspection create hiring constraints as aerospace maintenance programs expand.
- Legacy system integration complexity:Video endoscope platforms must interface with existing asset management databases and documentation workflows, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Endoscope Market |
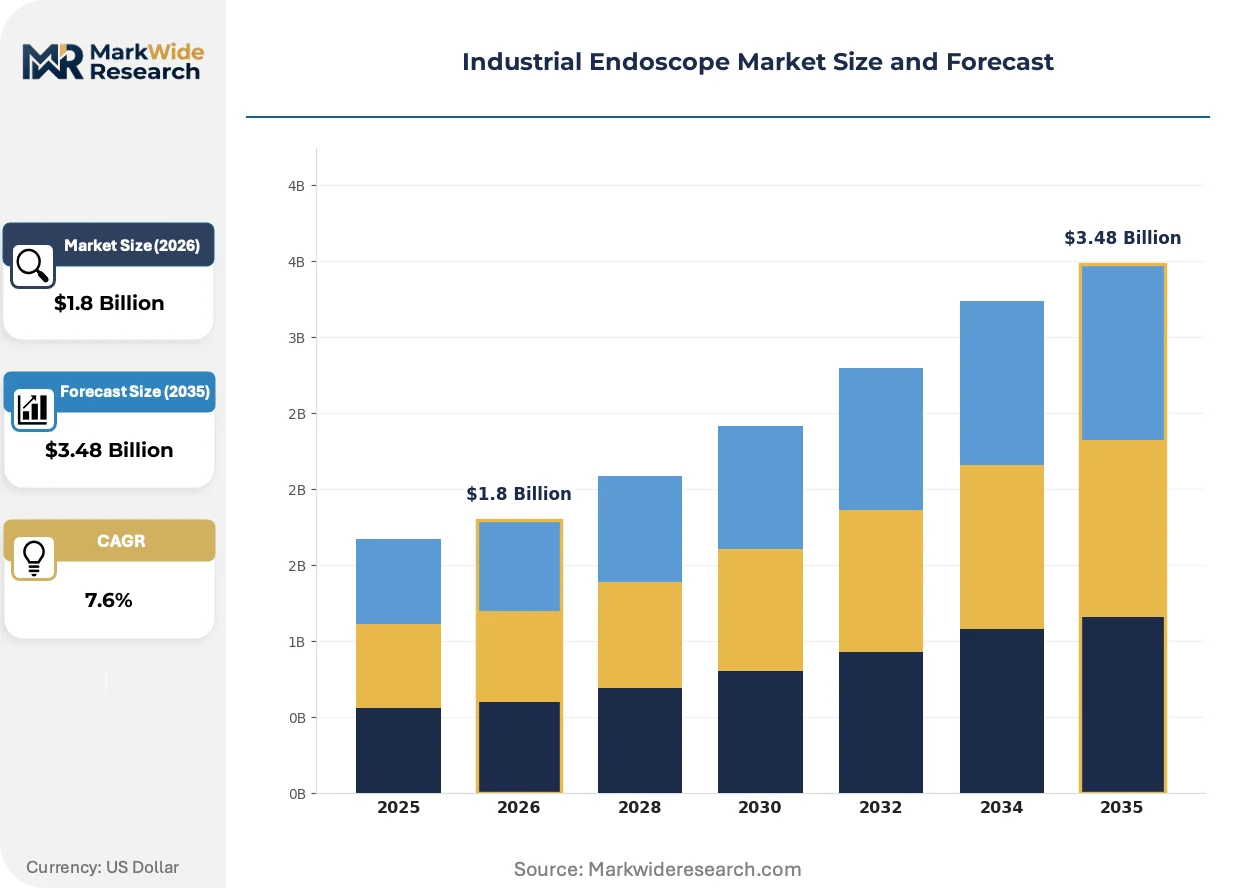
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscope, Rigid Endoscope, Video Endoscope, Accessories Application: Aerospace, Automotive, Manufacturing, Energy Technology: Fiber Optic, CMOS, CCD, Wireless End User: OEMs, Inspection Companies, Maintenance Providers, Field Technicians |
| Companies Covered | FUJIFILM Corporation, HOYA Corporation, Olympus Corporation, Ambu A/S, Medtronic, Karl Storz SE & Co. KG, Stryker Corporation, SUPERTEK, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Endoscope Market Strategic Shifts
Inspection hardware is converging with software analytics, compressing the gap between image capture and actionable maintenance intelligence while reshaping how OEMs and service providers monetize visual data.
High-resolution CMOS arrays with enhanced low-light sensitivity are rendering obsolete CCD-based video platforms in new equipment procurement. Aerospace maintenance operations in Germany and the United States now specify CMOS-native architectures for turbine and airframe inspections. The technology shift compresses sensor module costs while enabling 4K documentation standards that fiber-optic bundles cannot achieve.
EU machinery directives under CE marking requirements now mandate cybersecurity provisions for wireless inspection devices accessing critical infrastructure networks. Manufacturers must embed encryption protocols and access logging capabilities into portable video systems. Energy sector procurement in France and the Netherlands now prioritizes compliant platforms for pipeline and refinery applications.
Maintenance providers increasingly unbundle after-sales service contracts from hardware purchases, preferring per-inspection pricing or software-as-a-service analytics subscriptions. Specialized industrial distributors are capturing this shift by offering certified technician networks and cloud-based image archiving. This pattern concentrates in North American automotive and power generation verticals where capital budgets face pressure.
Industrial Endoscope Market Segmentation
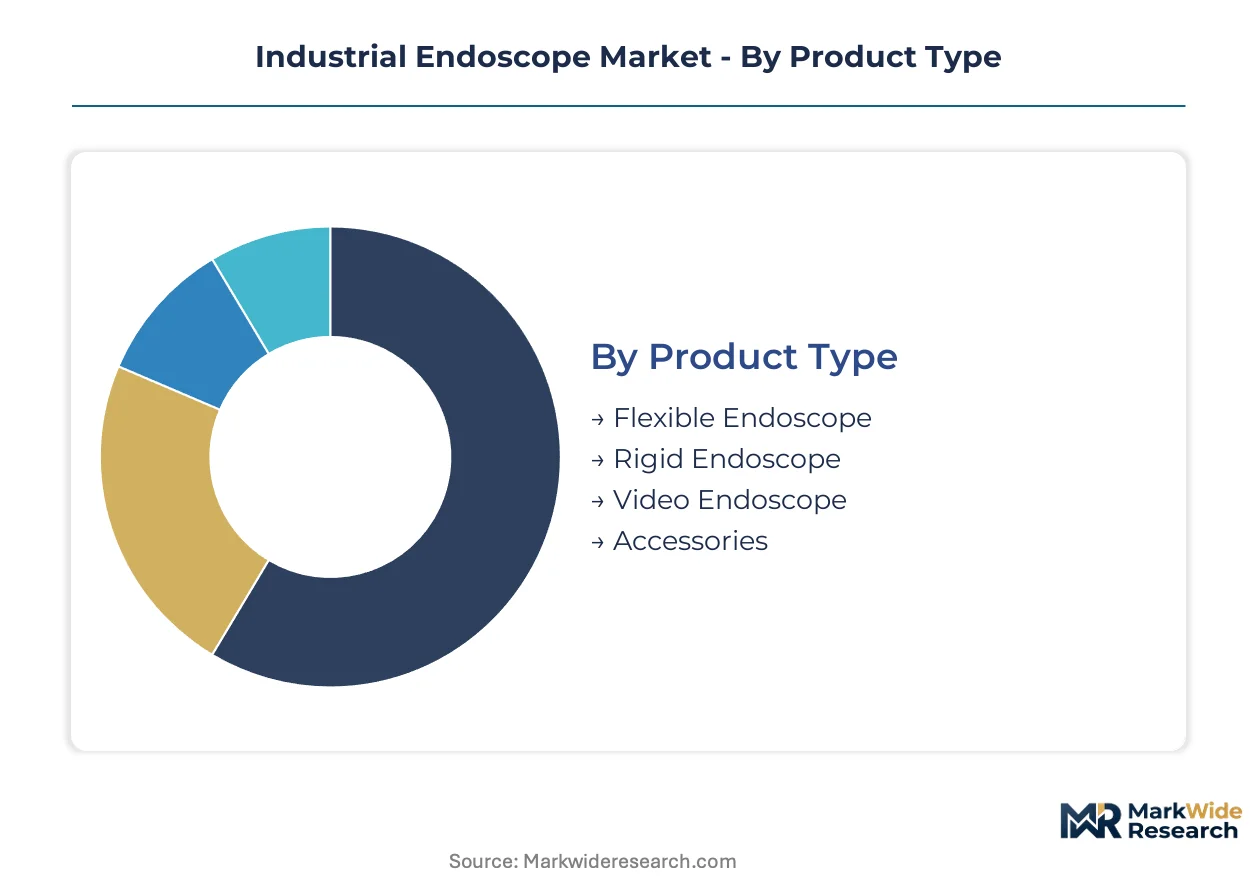
Industrial endoscope procurement patterns diverge sharply across hardware configurations, inspection environments, and operator capabilities. Technology transitions and regulatory documentation requirements reshape how buyers prioritize product specifications across each dimension.
Product Type:
Cost tier differentiation separates capital-intensive video systems from consumable fiber-optic bundles and disposable accessories.
- Flexible Endoscope:Articulating insertion tubes with steerable distal tips navigate curved pathways in turbine housings and pipeline networks. Energy sector maintenance contracts in Germany and the United States specify flexible architectures for combined-cycle power plant inspections where rigid access proves impossible.
- Video Endoscope:Integrated CMOS sensor modules with onboard image processing and digital documentation software command premium positioning. Aerospace OEMs in France mandate video platforms for airframe non-destructive testing protocols requiring traceable inspection records.
- Rigid Endoscope:Straight optical paths through precision lens systems deliver maximum resolution for straight-line bore inspections. Automotive engine block manufacturers in Stuttgart deploy rigid borescopes for cylinder wall quality verification.
- Accessories:Replacement cables, cleaning kits, and protective sheaths sustain equipment lifecycles. Field service depots in Texas maintain accessory inventories to minimize technician downtime.
Video Endoscope holds installed capacity. Flexible Endoscope is rotating up the share rankings.
Application:
Application focus determines resolution requirements, environmental sealing specifications, and documentation compliance burdens.
- Aerospace:Turbine blade cooling hole inspection and airframe structural assessments demand sub-millimeter defect detection. FAA-mandated maintenance programs at MRO facilities in Georgia and Arizona drive recurring video endoscope procurement.
- Automotive:Powertrain component verification and assembly line quality gates require rapid cycle-time inspection protocols. KBA inspection standards propagate through supplier networks near Wolfsburg and Munich.
- Energy:Pipeline corrosion mapping and refinery vessel internal assessments prioritize hazardous environment certifications. OSHA confined-space protocols elevate deployment frequency at Texas and Louisiana petrochemical complexes.
- Manufacturing:Die-cast mold verification and precision machining quality control favor portable battery-powered systems. Electronics contract manufacturers in Shenzhen integrate wireless probes into smart factory workflows.
Automotive maintains volume concentration. Energy is climbing the fastest.
Technology:
Technology maturity curves separate legacy installed bases from replacement-cycle acceleration zones.
- CMOS:Active-pixel sensor arrays with low-noise readout circuits enable 4K documentation at reduced power consumption. New equipment specifications at Boeing and Airbus facilities now exclude CCD alternatives.
- Fiber Optic:Coherent glass bundle image transmission persists in budget-constrained maintenance operations. Stranded inventory risk concentrates among independent inspection contractors in Eastern European markets.
- CCD:Charge-coupled device architectures retain niche presence in legacy medical-adjacent sterilization equipment. FDA-registered facilities in Massachusetts and California maintain CCD systems for process compatibility.
- Wireless:Battery-powered probe-to-tablet transmission eliminates cable management constraints. Field technicians at offshore wind installations in the North Sea prioritize untethered maneuverability.
Fiber Optic carries replacement-cycle vulnerability. CMOS is gaining share fastest.
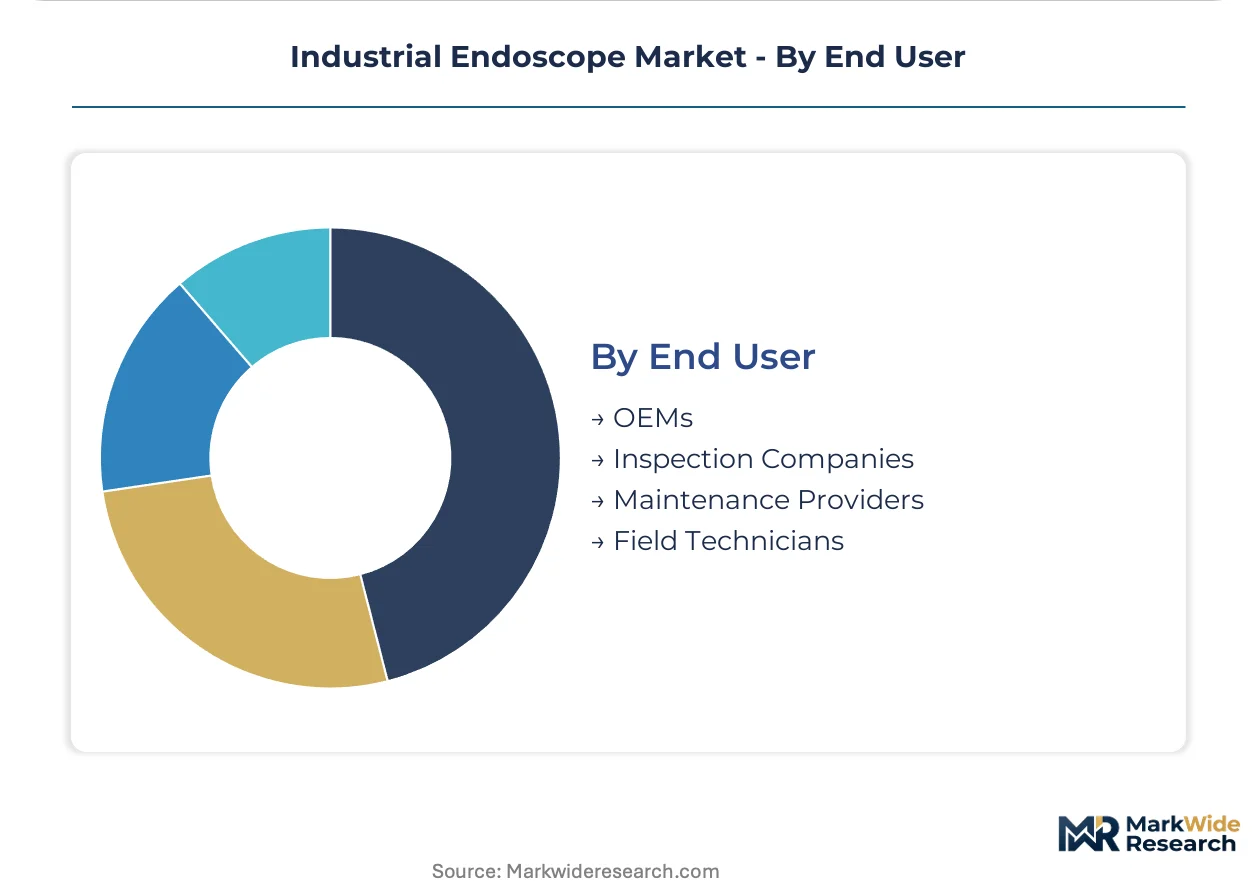
End User:
Customer type shapes procurement authority, budget structure, and service attachment preferences.
- OEMs:Original equipment manufacturers integrate inspection systems into production lines and warranty service networks. Automotive powertrain plants in Bavaria specify vendor-managed inventory arrangements.
- Inspection Companies:Third-party NDT service providers seek equipment mobility and multi-client software compatibility. ASNT-certified contractors in Houston rotate assets across upstream and downstream energy clients.
- Maintenance Providers:In-house facility engineering teams prioritize integration with existing CMMS platforms. Manufacturing conglomerates in the US Midwest standardize on single-vendor video platforms.
- Field Technicians:Individual operators favor lightweight, battery-optimized configurations for elevated or confined-space access. Wind turbine service crews in Denmark and Spain specify sub-kilogram probe systems.
Maintenance Providers anchor recurring revenue. Inspection Companies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA mandates in the United States anchor the dominant geography for industrial endoscope deployment, with inspection frequency requirements cascading through manufacturing and energy maintenance networks worldwide.
United States
Aerospace MRO facilities in Georgia and Arizona drive turbine blade inspection demand under FAA-mandated maintenance programs. OSHA confined-space entry protocols elevate endoscope deployment frequency at Texas and Louisiana petrochemical complexes. Field technicians at offshore wind installations along the Atlantic coast prioritize wireless probe systems for untethered maneuverability.
Germany
Automotive powertrain plants in Bavaria and Stuttgart specify rigid borescopes for cylinder wall quality verification under KBA inspection standards. CE marking requirements under EU machinery directives shape procurement specifications for manufacturing OEMs. Energy sector maintenance contracts in the Ruhr region specify flexible architectures for combined-cycle power plant inspections.
China
Electronics contract manufacturers in Shenzhen integrate wireless probes into smart factory workflows for die-cast mold verification. GB standards and MIIT regulations govern equipment certification for domestic precision machinery markets. Yangtze River Delta industrial clusters drive CMOS-based video platform adoption for manufacturing quality assurance.
Japan
Precision machining quality control operations in the Nagoya industrial corridor favor portable battery-powered inspection systems. METI industrial standards influence equipment specifications for automotive and aerospace component manufacturers. Kansai region maintenance providers unbundle after-sales service contracts in favor of per-inspection pricing models.
India
Domestic manufacturing incentives under the PLI scheme create localized assembly opportunities for precision equipment serving energy infrastructure inspection. CEA regulations shape procurement requirements for power generation facility maintenance programs. Maharashtra and Gujarat industrial corridors concentrate demand from project-based construction and maritime inspection providers.
Industrial Endoscope Market Competitive Environment
Optical heritage conglomerates and precision equipment specialists split the market into distinct capability tiers. Consolidation pressure concentrates around CMOS sensor integration and software analytics attachment. Three archetypes dominate: diversified imaging conglomerates with aerospace channel access, rigid endoscope specialists serving automotive OEM networks, and CMOS-native platform builders targeting manufacturing quality workflows. Competitive moves center on technology licensing partnerships and geographic expansion through specialized industrial distributors.
Within the diversified imaging tier, FUJIFILM Corporation and Olympus Corporation occupy positions anchored by optical technology heritage and aerospace inspection channel relationships. Karl Storz SE & Co. KG exemplifies the rigid endoscope specialist archetype with European automotive and energy sector concentration. These three entities represent the strategic positioning spectrum from premium video platform ecosystems to precision optical instrument specialization.
| Leading Market Players |
|---|
| FUJIFILM Corporation |
| HOYA Corporation |
| Olympus Corporation |
| Ambu A/S |
| Medtronic |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| SUPERTEK |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
East Asian CMOS sensor foundries concentrate upstream capacity for image acquisition modules, anchoring margin capture in downstream video endoscope assembly while compressing cost structures for fiber-optic alternatives. Pricing power accumulates with manufacturers controlling CMOS-native platform roadmaps and integrated software analytics, leaving commodity probe assemblers exposed to component cost volatility.
Pricing Analysis
Price spreads between German-engineered rigid borescopes and Asian-manufactured flexible probes exceed threefold at equivalent optical specifications. Three-tier pricing structure across premium video platforms, standard CMOS systems, and economy fiber-optic bundles reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from CMOS module cost compression as sensor fabrication scales in Taiwan and South Korea. Field technicians and independent inspection contractors exhibit highest price sensitivity, while aerospace MRO facilities prioritize documentation compliance over unit cost.
Supply Chain Analysis
Taiwanese and South Korean foundries hold dominant CMOS sensor fabrication capacity for industrial imaging applications, with Japanese optical houses supplying precision lens systems. Supply chains draw from rare earth elements for sensor substrates, specialized glass for fiber bundles, and lithium-polymer cells for wireless probe power systems. Single-source vulnerability concentrates in advanced CMOS wafer production, where geopolitical disruption risks extend equipment lead times. Distribution runs through specialized industrial distributors serving maintenance providers and OEM procurement teams across fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
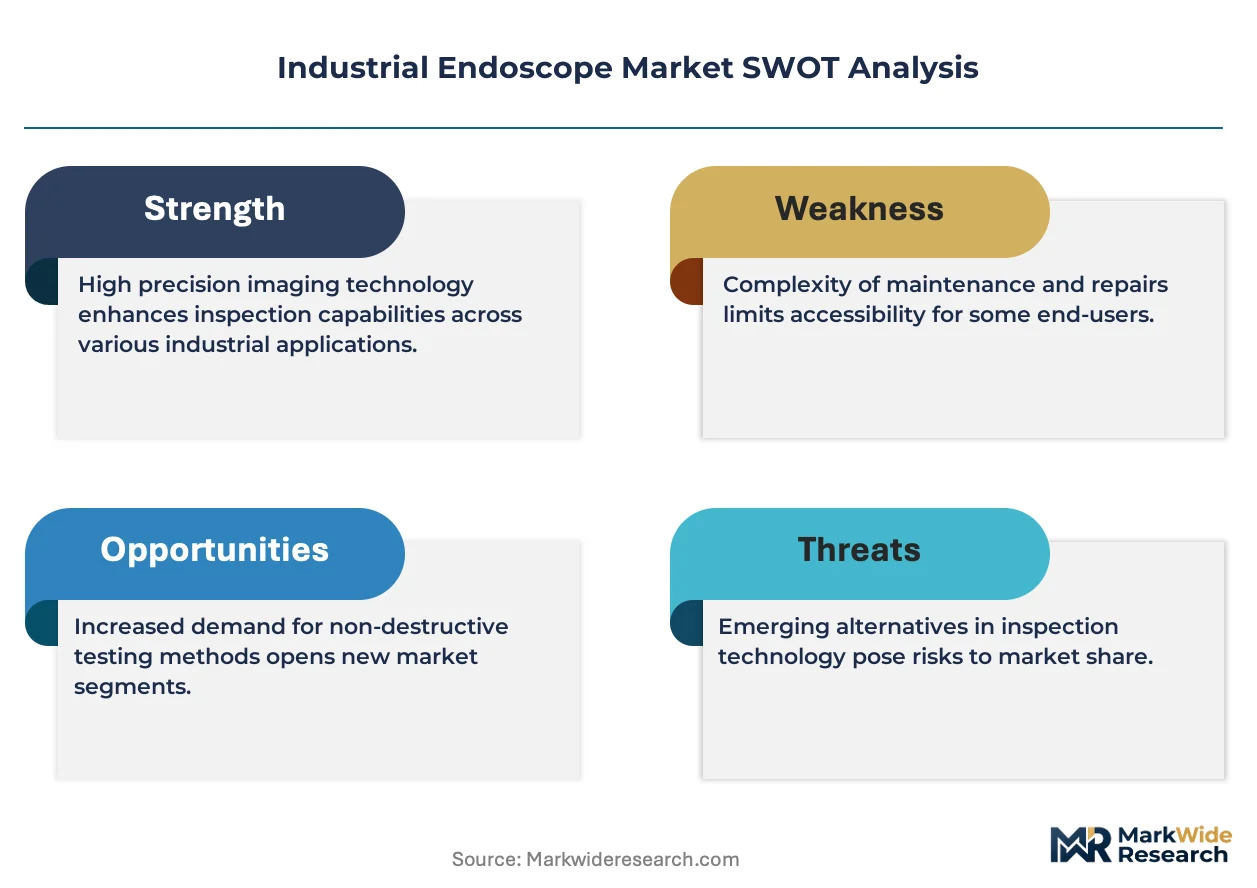
Industrial endoscope incumbents face sustained substitution pressure from machine-vision camera systems and autonomous inspection drones capturing visual data without probe insertion. Defense requires embedding software analytics deeper into hardware platforms to sustain differentiation against non-contact alternatives.
For Market Incumbents: Entrench CMOS-native architectures through backward integration into sensor module design, securing supply continuity against East Asian foundry concentration. Lock aerospace and automotive OEMs into multi-year platform roadmaps with embedded AI defect recognition, raising switching costs against emerging drone-based inspection providers. Prioritize certification investment for CE marking and OSHA compliance documentation to defend premium positioning.
For New Entrants and Emerging Players: Establish a beachhead in India's project-based construction and maritime inspection segments, where PLI scheme incentives reduce landed cost disadvantages against established European and Japanese suppliers. Target wireless probe rental channels serving field technicians in North American offshore wind installations, bypassing capital-intensive OEM direct sales networks. Pursue ASNT-certified technician partnerships to accelerate credibility building among third-party NDT service providers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across CMOS video platform manufacturing as sensor module costs compress, improving cash conversion for assembly-heavy business models. Acquisition targets should display software analytics attachment above hardware margins and established distributor relationships in German automotive or US aerospace channels. Monitor CMOS sensor lead time quotations from Taiwanese foundries as early inflection indicator for supply-constrained pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Sensor Platform Migration | Displaces legacy CCD and fiber-optic systems in Boeing and Airbus procurement specifications. |
| AI Defect Recognition Integration | Compresses analysis time for ASNT-certified technicians at Georgia aerospace MRO facilities. |
| Wireless Probe Certification | Enables OSHA-compliant deployment in Texas petrochemical confined-space entry protocols. |
| Rental Channel Development | Captures operational expenditure preference among North American construction inspection providers. |
| India PLI Scheme Localization | Reduces landed costs for Maharashtra and Gujarat energy infrastructure maintenance contracts. |
Study Parameters
Desk research of trade customs data, SEC filings from optical equipment manufacturers, and EU machinery directive documentation preceded structured interviews with maintenance directors at German automotive plants, ASNT-certified inspection contractors in Houston, and biomedical engineers at FDA-registered Massachusetts facilities. Primary fieldwork with OEM procurement teams and aftermarket service heads was triangulated against bottom-up equipment shipment estimates and top-down maintenance expenditure analysis across aerospace, automotive, and energy verticals.
Forecast assumptions held OSHA inspection mandate enforcement intensity and CE marking cybersecurity provisions fixed at current regulatory trajectories, while CMOS sensor cost curves and wireless adoption rates were varied across sensitivity bands. Segmentation modeling spanned product architecture, application vertical, sensor technology maturity, and end-user procurement authority. CAGRs were derived from equipment replacement cycle compression analysis and documented platform procurement shifts at Airbus and Boeing MRO networks.
Stress conditions across CMOS foundry utilization rates, German KBA inspection standard propagation timing, and US offshore wind deployment cadence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including geopolitical supply disruption and technician certification bottlenecks. Quarterly review of Taiwanese sensor foundry lead times and ASNT qualification program enrollment data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Endoscopy Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Global Disposable Endoscope Market