
 Automated Endoscopy Reprocessor Market | 2026-2036
Automated Endoscopy Reprocessor Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Endoscopy Reprocessor Market Analysis
Ambulatory surgical centers are rotating toward automated endoscopy reprocessors as outpatient procedural volumes expand and same-day discharge protocols tighten turnover requirements. STERIS leverages its installed base in North American hospital systems to sustain service contract renewals. Getinge anchors European demand through centralized sterile supply department partnerships. Olympus Corporation competes by integrating reprocessor hardware with its endoscope portfolios.
An automated endoscopy reprocessor is a closed-cycle medical device that performs high-level disinfection or sterilization of flexible endoscopes using validated thermal, chemical, or combined chemothermal protocols with automated channel flushing and leak testing. Its primary commercial purpose is to eliminate human variability in reprocessing, reduce cross-contamination risk, and document compliance for regulatory audit trails. High-volume systems dominate installed capacity in tertiary hospitals where endoscopy throughput exceeds fifty procedures daily. Chemical disinfection technology leads current revenue contribution due to material compatibility with heat-sensitive endoscope construction. Automated workflow solutions represent the fastest-expanding segment as facilities pursue digitized traceability and reduced technician touch time.
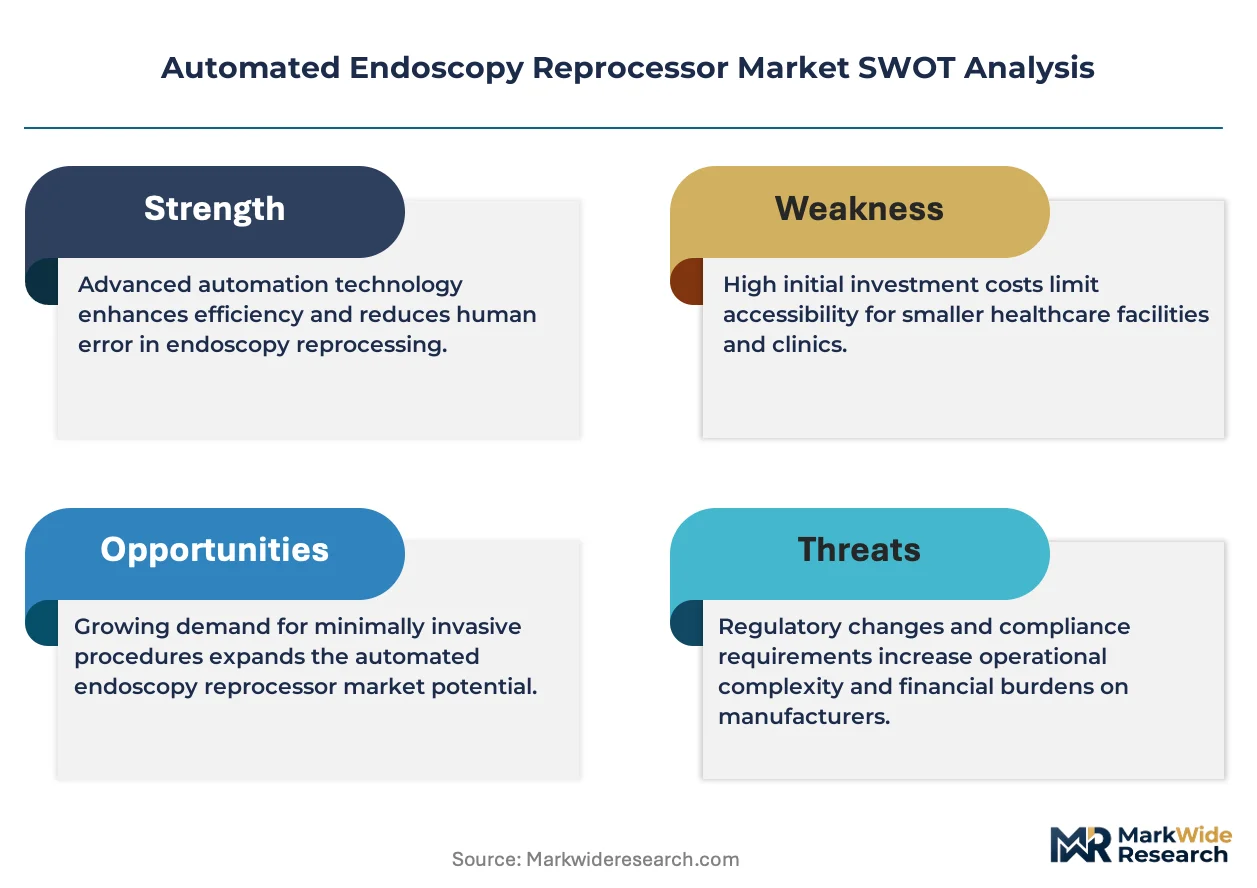
FDA 510(k) clearance requirements and AAMI ST91 standards shape product development timelines and validation costs for manufacturers seeking US market access. EMA medical device regulations and ISO 15883 washer-disinfector standards govern European commercialization and clinical acceptance criteria. Stakeholders must monitor evolving endoscope material innovations and corresponding compatibility claims, as next-generation endoscope designs will force reprocessor manufacturers to recalibrate chemical exposure parameters and thermal profiles without delaying regulatory submissions.
Market Dynamics
Hospital consolidation across Germany and the United States is centralizing sterile processing operations into single high-throughput hubs, forcing reprocessor vendors to engineer systems capable of handling sixty-plus endoscopes daily while maintaining FDA-validated disinfection cycles.
Growth Catalysts
- AAMI ST91 compliance mandates:US ambulatory surgical centers face audit pressure to document high-level disinfection cycles with automated traceability, accelerating replacement of manual reprocessing sinks.
- Heat-sensitive endoscope materials:Advanced polymers in next-generation duodenoscopes and colonoscopes require chemical disinfection protocols that only automated reprocessors can deliver with validated consistency.
- Outpatient procedural volume concentration:Same-day discharge protocols in tertiary hospitals across France and the United Kingdom compress turnover windows to under ninety minutes.
Market Restraints
- Peracetic acid supply volatility:Chemical disinfection reprocessors depend on concentrated peracetic acid formulations whose production concentrates among three European specialty chemical suppliers.
- FDA 510(k) validation timelines:New chemothermal cycle submissions require eighteen-to-twenty-four month review periods that delay product launches and compress commercialization windows.
- Manual reprocessing persistence:Low-volume rural hospitals in India and Southeast Asia continue operating sink-based workflows due to capital constraints and technician availability.
Strategic Opportunities
- Digitized workflow integration:RFID-enabled endoscope tracking combined with automated reprocessor data streams enables predictive maintenance and compliance dashboarding for hospital systems.
- Brazilian hospital privatization:ANVISA's accelerated medical device registration pathways for imported reprocessors open access to a previously import-restricted installed base.
- Single-use endoscope compatibility:Reprocessor manufacturers can capture service revenue from hybrid facilities running both reusable and disposable scope portfolios through dual-protocol engineering.
Industry Challenges
- Certified sterile processing technician scarcity:AAMI-certified professionals capable of operating automated reprocessors and interpreting cycle validation data command salary premiums that strain ASC staffing budgets.
- Legacy endoscope fleet incompatibility:Older Olympus and Pentax scope generations lack standardized connector geometries that automated channel flushing systems require, forcing parallel manual workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Endoscopy Reprocessor Market |
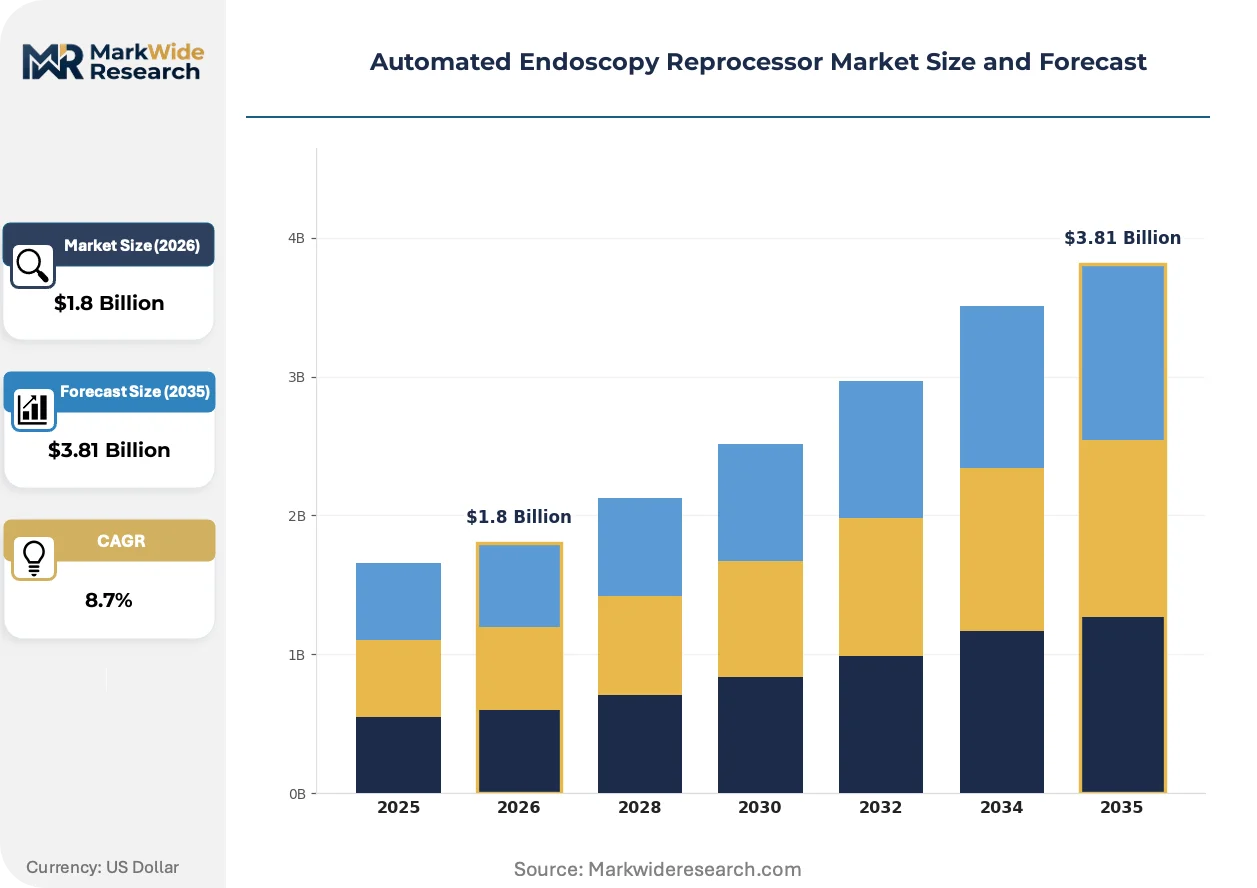
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Volume Systems, Low-Volume Systems, Portable Units, Integrated Solutions End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Laboratories Technology: Thermal Disinfection, Chemical Disinfection, Advanced Ultrasonic Cleaning, Automated Workflow Solutions Service Type: Maintenance Services, Training Services, Repair Services, Consulting Services |
| Companies Covered | STERIS, Getinge, Olympus Corporation, Ecolab, Cantel Medical, Steelco S.p.A., ASP, Belimed, HOYA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Endoscopy Reprocessor Market Emerging Trajectories
Reprocessor architecture is splitting between high-throughput centralized systems and compact point-of-care units as facility footprints and procedural mixes diverge across health systems.
Chemothermal disinfection technology is bifurcating the installed base. Combined peracetic acid and heated rinse protocols achieve sporicidal efficacy without the material degradation risks of pure thermal sterilization. Tertiary hospitals in Germany and the Netherlands are retrofitting existing chemical lines with thermal modules, while greenfield ASCs in Texas and Florida specify native chemothermal systems from commissioning. This dual-capability engineering is compressing the addressable market for single-modality chemical-only reprocessors.
EMA's Medical Device Regulation (MDR) Article 10 post-market surveillance requirements now mandate automated reprocessor manufacturers to submit annual safety and performance reports with traceable cycle data. The regulation forces European vendors to engineer cloud-connected validation logging as a standard feature rather than premium upgrade. French and Italian hospital purchasing committees now weight MDR-compliant documentation capabilities above list price in tender evaluations.
Service contract unbundling is disrupting traditional reprocessor economics. Hospital systems in California and New York now separate hardware procurement from preventive maintenance and consumable supply, sourcing each through competitive bidding. This disintermediation compresses vendor margins on multi-year agreements while opening entry points for third-party service specialists and independent chemical suppliers.
Automated Endoscopy Reprocessor Market Segmentation
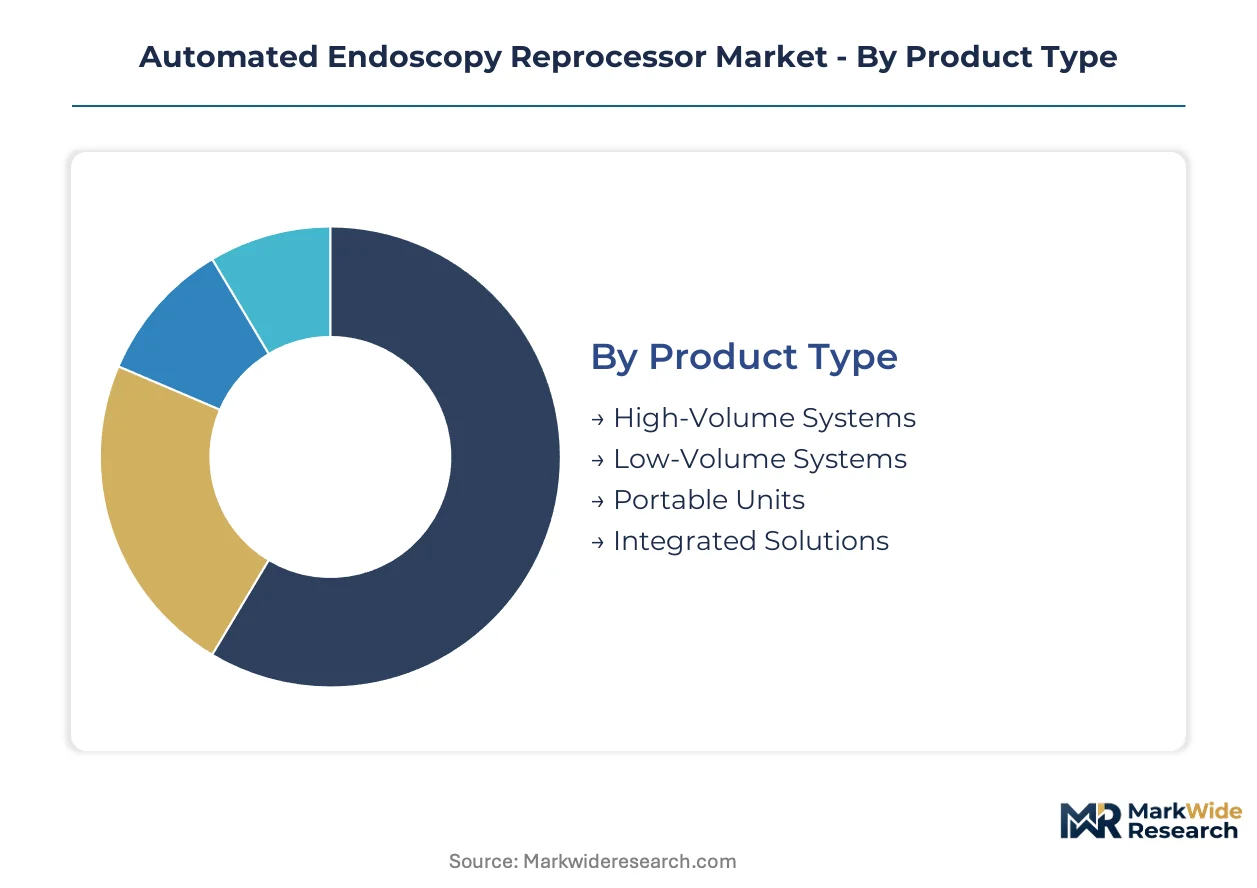
Segmentation in automated endoscopy reprocessors reveals how procurement decisions split between throughput requirements, regulatory compliance burdens, and total cost of ownership models across facility types.
Product Type:
Margin pools concentrate in systems capable of handling forty-plus endoscopes per day with validated FDA disinfection cycles.
- High-Volume Systems:These units process fifty to eighty endoscopes daily through parallel chamber architecture with automated channel flushing and leak detection. German hospital networks undergoing consolidation drive procurement of centralized high-throughput installations to serve merged facility footprints.
- Integrated Solutions:Hardware-software bundles combine reprocessor units with RFID tracking, compliance dashboards, and predictive maintenance modules. Outpatient clinics in France and the United Kingdom specify these configurations to compress turnover windows under ninety minutes for same-day discharge protocols.
- Low-Volume Systems:Compact single-chamber units serve rural hospitals with under fifteen daily procedures.
- Portable Units:Battery-powered or cart-mounted systems enable point-of-care reprocessing in field surgical units.
The dominant share belongs to high-volume systems, while integrated solutions are closing the gap fastest.
End User:
Procurement authority and volume concentration diverge sharply across facility types, with ambulatory settings demanding faster cycle times than tertiary hospitals.
- Ambulatory Surgical Centers:These facilities prioritize compact footprint systems with sub-sixty-minute cycle validation to maintain tight procedural scheduling. Texas and Florida ASCs specify native chemothermal systems from commissioning to meet AAMI ST91 documentation requirements without retrofit costs.
- Hospitals:Tertiary medical centers operate mixed fleets of chemical and chemothermal reprocessors serving endoscopy suites with fifty-plus daily procedures. Centralized sterile processing departments in consolidated US and German health systems negotiate multi-unit service contracts with unbundled maintenance terms.
- Outpatient Clinics:Lower throughput settings favor low-volume systems with simplified technician interfaces.
- Laboratories:Research and veterinary endoscopy facilities require flexible protocol programming for non-standard scope geometries.
Hospitals retain the largest installed base, though ambulatory surgical centers are expanding procurement fastest.
Technology:
Technology selection hinges on material compatibility with heat-sensitive endoscope polymers and sporicidal efficacy requirements.
- Chemical Disinfection:Peracetic acid-based protocols dominate current revenue due to broad material compatibility with advanced duodenoscope and colonoscope polymers. European supply concentration among three specialty chemical manufacturers creates procurement risk for high-volume operators.
- Automated Workflow Solutions:Digitized traceability systems with cloud-connected validation logging address EMA MDR Article 10 post-market surveillance mandates. French and Italian hospital purchasing committees now weight MDR-compliant documentation capabilities above list price in tender evaluations.
- Thermal Disinfection:Pure heat-based sterilization suits metal rigid endoscopes but degrades flexible polymer construction.
- Advanced Ultrasonic Cleaning:Pre-disinfection mechanical removal of bioburden supplements chemical or thermal cycles.
Chemical disinfection holds the dominant technology share, while automated workflow solutions are gaining share fastest.
Service Type:
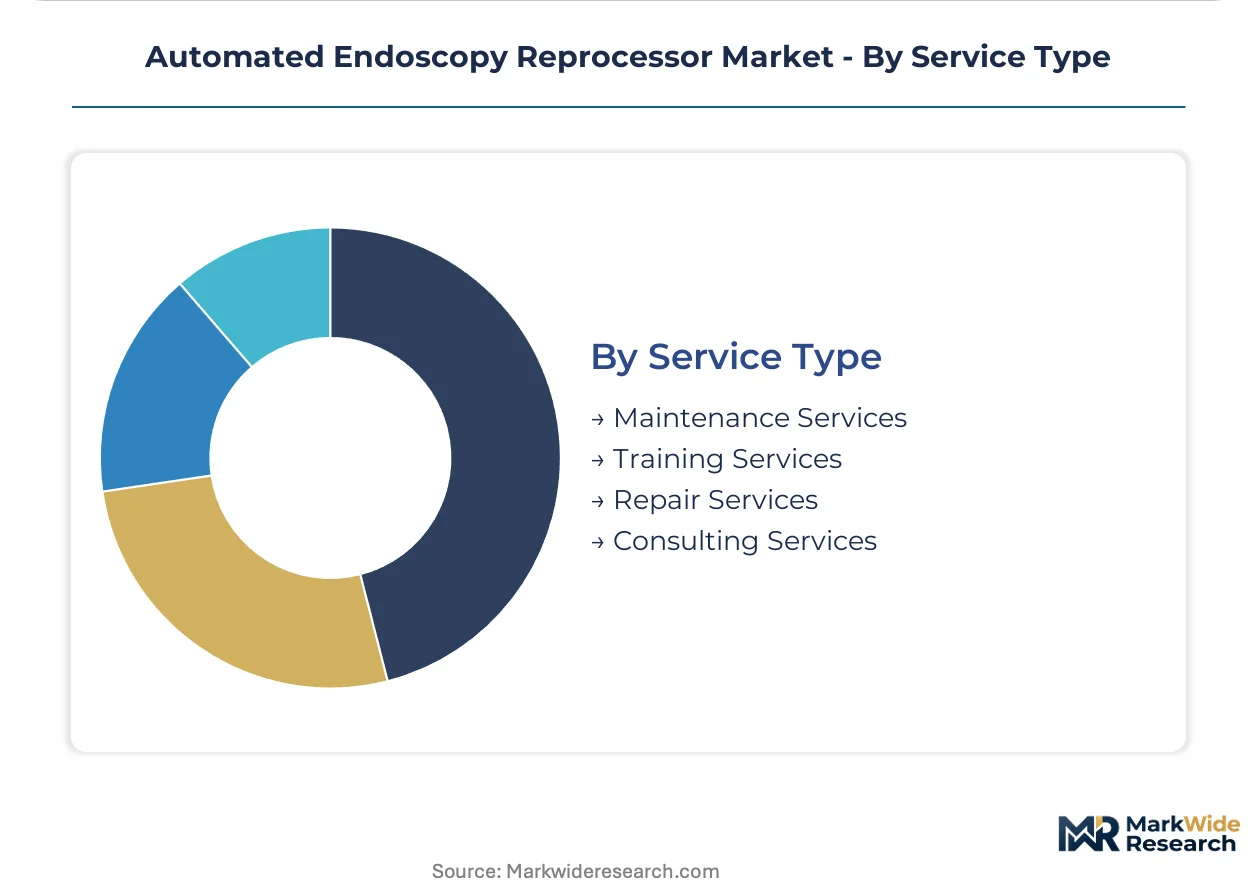
Service revenue streams are unbundling from hardware procurement as hospital systems separate preventive maintenance, consumable supply, and consulting through competitive bidding.
- Maintenance Services:Scheduled preventive maintenance contracts covering chamber calibration, pump replacement, and software updates preserve FDA-validated disinfection cycle integrity. California and New York health systems now source these separately from hardware procurement, compressing vendor margins while opening entry points for third-party specialists.
- Training Services:AAMI-certified technician education programs address scarcity of sterile processing professionals capable of interpreting cycle validation data. ASC staffing budgets strain under salary premiums commanded by certified operators.
- Repair Services:Unplanned breakdown coverage and component replacement outside warranty terms.
- Consulting Services:Workflow optimization and compliance audit preparation for regulatory inspections.
Maintenance services command the largest service revenue share, while training services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German reprocessor manufacturers export centralized high-throughput systems to hospital networks in the United States and the Netherlands as consolidation drives sterile processing hub investments across buyer geographies.
United States
Ambulatory surgical centers in Texas and Florida drive procurement of native chemothermal systems to meet AAMI ST91 documentation requirements without retrofit costs. FDA 510(k) clearance timelines stretch eighteen to twenty-four months for new cycle submissions. Hospital consolidation in California and New York forces vendors to unbundle service contracts from hardware procurement.
Germany
Hospital network mergers centralize sterile processing into single hubs handling sixty-plus endoscopes daily. EMA MDR Article 10 mandates cloud-connected validation logging as standard equipment features. The Ruhr region and Bavaria host retrofit installations adding thermal modules to existing chemical reprocessor lines.
France
Tertiary hospitals compress turnover windows under ninety minutes for same-day discharge protocols. ANSM post-market surveillance requirements align with EMA MDR annual safety reporting obligations. The Île-de-France region concentrates procurement of integrated solutions combining hardware with RFID tracking systems.
United Kingdom
Outpatient clinics specify compact systems with sub-sixty-minute cycle validation to maintain tight procedural scheduling. MHRA medical device regulations enforce traceable disinfection documentation for audit compliance. Greater London health systems negotiate multi-unit service contracts with third-party maintenance specialists.
Brazil
Hospital privatization accelerates demand for imported automated reprocessors previously restricted by regulatory barriers. ANVISA's accelerated registration pathways for imported devices reduce market entry timelines. São Paulo and Rio de Janeiro metro areas concentrate procurement of high-volume systems for consolidated private hospital networks.
Automated Endoscopy Reprocessor Market Vendor Landscape
Player mix skews toward diversified medical technology conglomerates with established sterile processing portfolios. The vendor base concentrates around manufacturers with FDA-validated disinfection cycles and EMA MDR-compliant documentation capabilities. Two strategic archetypes dominate: integrated endoscope-reprocessor bundlers and standalone sterile processing specialists. Competitive moves center on service contract unbundling responses and chemothermal protocol diversification.
Among diversified medical technology conglomerates, STERIS, Getinge, and Olympus Corporation occupy distinct positioning vectors. STERIS exemplifies the North American hospital system anchor archetype through service contract renewal strategies. Getinge represents the European centralized sterile supply partnership model. Olympus Corporation sits within the integrated portfolio tier, bundling reprocessor hardware with proprietary endoscope lines to capture hybrid facility demand.
| Leading Market Players |
|---|
| STERIS |
| Getinge |
| Olympus Corporation |
| Ecolab |
| Cantel Medical |
| Steelco S.p.A. |
| ASP |
| Belimed |
| HOYA Corporation |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance timelines and AAMI ST91 validation requirements gate both supplier qualification and price differentiation in automated endoscopy reprocessors, compressing margins for manufacturers unable to absorb eighteen-to-twenty-four month regulatory delays while allowing validated incumbents to command service contract premiums.
Pricing Analysis
Current-generation chemothermal systems command substantial premiums over prior-generation chemical-only units, while next-gen integrated workflow solutions with cloud-connected validation logging extract further uplifts from EMA MDR-compliant facilities. Pricing stratifies across premium validated systems, standard FDA-cleared configurations, and economy-tier refurbished units, with differentiation driven by cycle throughput capacity and documentation automation depth. Cost compression in the standard tier is intensifying because hospital systems in California and New York now unbundle hardware procurement from maintenance and consumables. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while consolidated German hospital networks prioritize total cost of ownership over list price.
Supply Chain Analysis
Strategic stockpiling of peracetic acid concentrates dominates inventory strategy over just-in-time approaches, given supply concentration among three European specialty chemical manufacturers and vulnerability to production disruptions. Component sourcing draws from Germany for precision pumping systems, the United States for control electronics, and Italy for chamber fabrication, with final assembly concentrated in Western European facilities. Single-source vulnerability in peracetic acid supply creates structural risk for high-volume operators dependent on validated chemical formulations. Distribution runs through direct hospital system contracts in North America and sterile supply department partnerships in Europe, with third-party service specialists capturing unbundled maintenance revenue in fragmented markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated endoscopy reprocessor demand is accelerating through regulatory inflection as EMA MDR Article 10 mandates transform cloud-connected validation logging from premium upgrade to standard requirement, reshaping competitive positioning toward documentation-capable vendors.
For Market Incumbents: Consolidate service contract renewals through predictive maintenance modules and RFID-enabled tracking integration to defend against third-party specialists capturing unbundled maintenance revenue. Deepen backward integration into peracetic acid supply relationships to mitigate European chemical concentration risk. Prioritize chemothermal protocol diversification to capture retrofit demand from German hospitals upgrading existing chemical lines. For New Entrants and Emerging Players: Lead with compact point-of-care units targeting Brazilian private hospital networks benefitting from ANVISA's accelerated registration pathways, the most penetrable geography for imported reprocessors previously restricted by regulatory barriers. Emphasize native chemothermal engineering to avoid retrofit cost disadvantages against established competitors. Pursue GPO contract positioning with ASC-focused group purchasing organizations in Texas and Florida seeking sub-sixty-minute cycle validation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates with underperforming sterile processing divisions, particularly those lacking FDA-validated chemothermal cycles or EMA MDR-compliant documentation capabilities. Long-term viability favors vendors with installed base scale to sustain unbundled service economics and regulatory bandwidth to navigate evolving material compatibility claims. Watch for inflection when next-generation endoscope polymer announcements force reprocessor recalibration of chemical exposure parameters.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Chemothermal Submission | Eighteen-to-twenty-four month validation timelines gate US market access for cycle innovations. |
| EMA MDR Cloud-Connected Logging | Article 10 annual safety reporting mandates transform documentation from premium to standard feature. |
| Hospital System Service Unbundling | California and New York health systems now competitively bid hardware, maintenance, and consumables separately. |
| Peracetic Acid Supply Integration | Backward integration into European specialty chemical sourcing mitigates production concentration risk. |
| Brazilian ANVISA Registration Pathway | Accelerated imported device approvals open previously restricted private hospital network demand. |
Methodological Framework
The analysis maps high-volume systems, integrated solutions, low-volume systems, and portable units, each validated through sterile processing department managers, biomedical engineers, hospital purchasing committee members, and GPO contracts managers, combined with FDA 510(k) filings, EMA MDR submission databases, AAMI standards documentation, and hospital procurement records, with bottom-up facility-level demand modeling triangulated against top-down manufacturer revenue aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling product type, end user facility category, disinfection technology modality, and service unbundling status as segmentation dimensions. CAGRs were derived from procedure volume trajectories, replacement cycle timing, and regulatory compliance-driven upgrade propensity, incorporating endoscope material innovation roadmaps and hospital consolidation patterns as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained outpatient procedural volume expansion and stable regulatory validation timelines would require recalibration. Forecasts reflect documented assumptions regarding technician certification availability and chemical supply continuity. Revision becomes warranted when peracetic acid production concentration or FDA review period volatility crosses thresholds that alter manufacturer commercialization economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Endotherapy Devices Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Global Colonoscopes Market
Endoscopy
AI in Endoscopy Market
Endoscopy
Video Laryngoscope Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Endoscopy Device Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Global Endoscopy Ultrasound Market