
 Europe Cardiac Rhythm Management Devices Market | 2026-2036
Europe Cardiac Rhythm Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cardiac Rhythm Management Devices Market Foresight
A shortage of certified electrophysiologists is rotating investment toward remote monitoring platforms and telemedicine-enabled device follow-up. Medtronic leverages its integrated CareLink network to sustain recurring revenue from device surveillance. Abbott anchors its European position through leadless pacemaker technology that reduces complication rates in elderly populations.
Cardiac rhythm management devices encompass implantable and external systems that detect, monitor, and correct abnormal heart rhythms through electrical stimulation or defibrillation, typically operating at 2.8V battery output with 5-15 year longevity depending on therapy load. These systems serve primarily to reduce sudden cardiac death incidence and manage chronic arrhythmia burden in health systems. Implantable Cardioverter Defibrillators command the deepest margin pools due to complex manufacturing and stringent testing protocols. Wireless Monitoring is expanding fastest as health systems prioritize reduced clinic visit frequency and earlier arrhythmia detection.
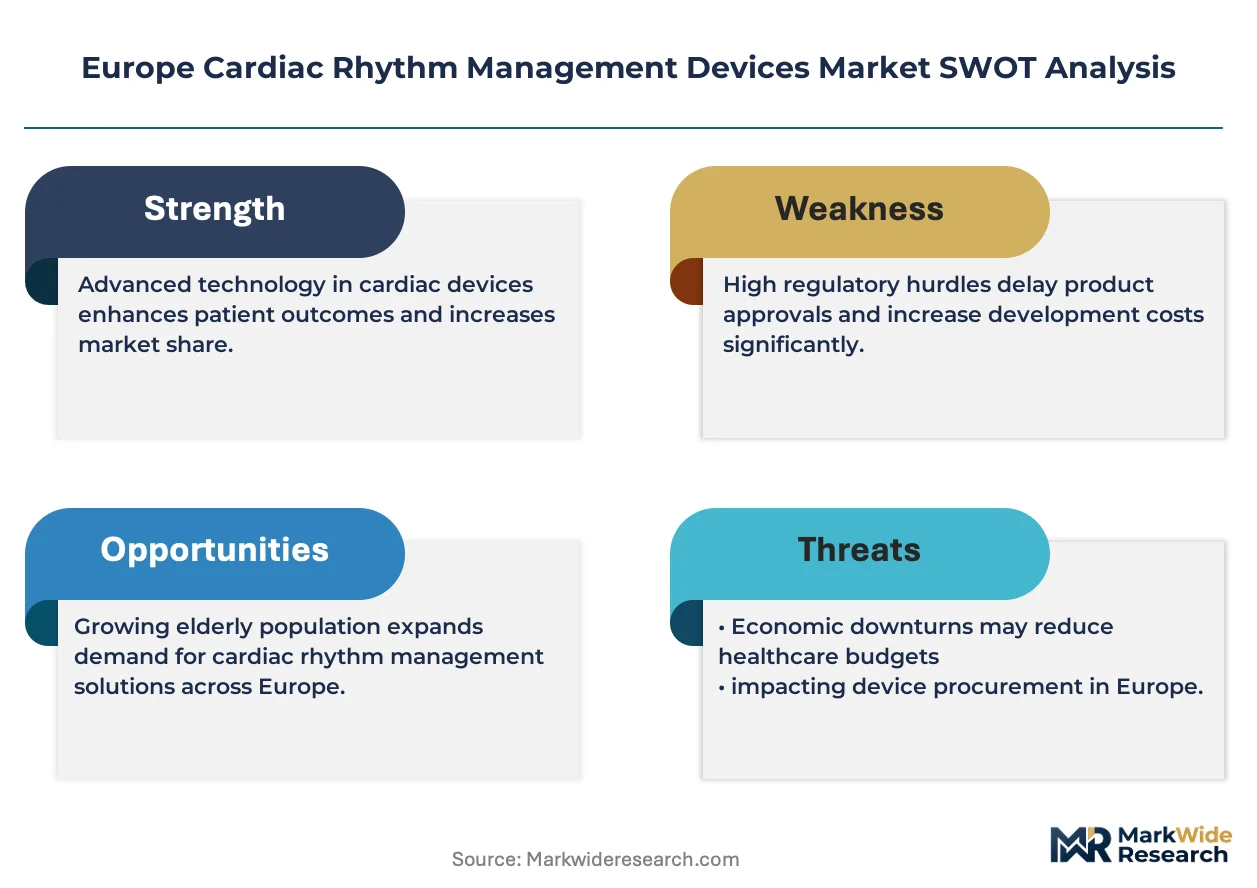
The EU Medical Device Regulation and CE marking framework administered by notified bodies in Germany and the Netherlands are extending clinical trial requirements for novel implantable systems. REACH compliance for device materials and the F-Gas Regulation for sterilization processes add layered compliance costs for manufacturers. Stakeholders must weigh reimbursement velocity against regulatory timeline compression when prioritizing product development portfolios.
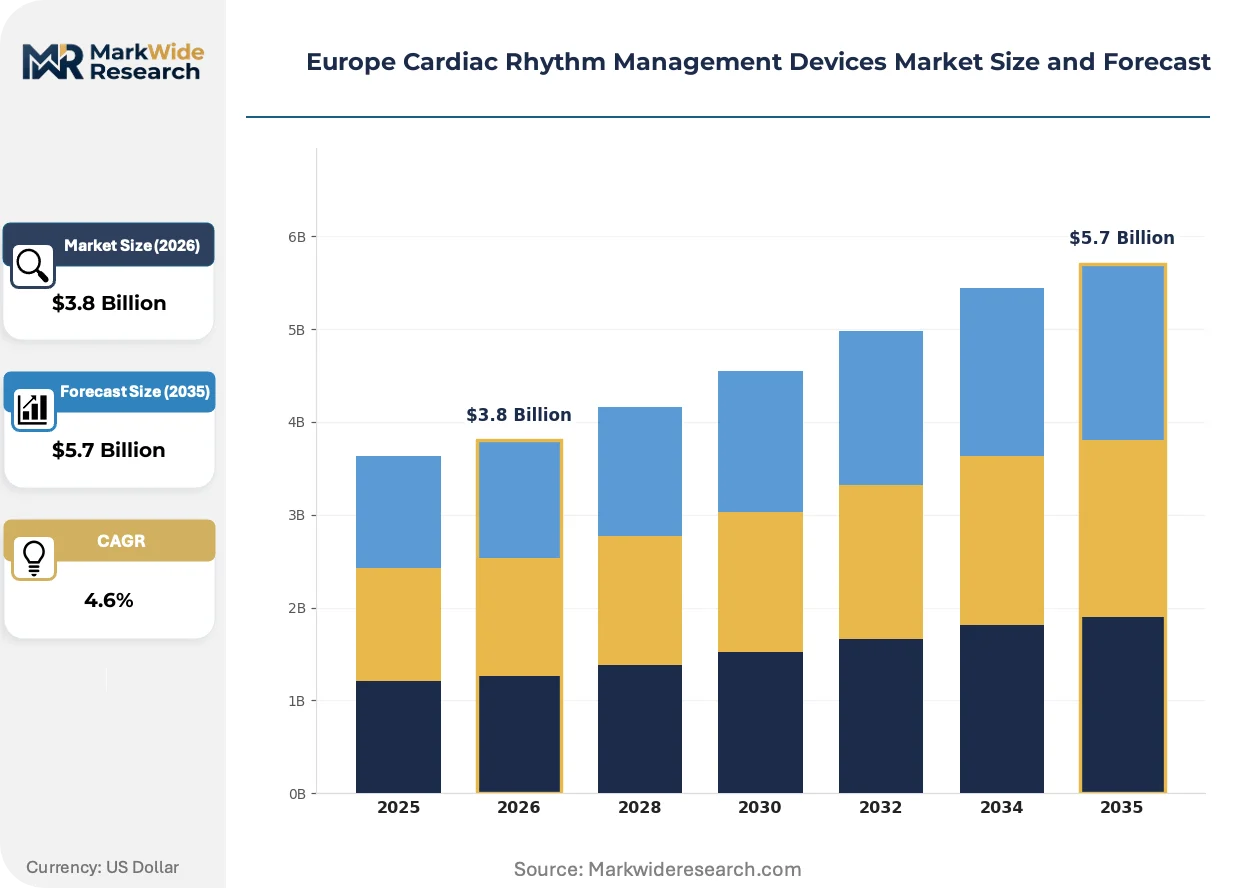
Market Dynamics
EU Medical Device Regulation (MDR) compliance timelines are compressing product development cycles across European cardiac rhythm management manufacturers, forcing portfolio prioritization toward higher-margin implantable systems with clearer clinical evidence pathways.
Growth Catalysts
- Catheter ablation reimbursement:France and Germany have expanded DRG coverage for atrial fibrillation ablation procedures, channeling hospital investment toward electrophysiology lab infrastructure.
- REACH material compliance:Battery chemistry standardization under EU chemical regulations is streamlining supplier qualification, reducing manufacturing variance for implantable pulse generators.
- Telemedicine-enabled follow-up:Remote monitoring reimbursement codes in the Netherlands and Belgium are accelerating adoption of connected cardiac devices.
Market Restraints
- Notified body bottlenecks:CE marking capacity constraints in Germany and the Netherlands are extending time-to-market for novel implantable systems by 12-18 months.
- Lithium iodine cell supply:Concentrated sourcing from Swiss and Japanese battery specialists creates vulnerability for high-energy ICD manufacturing lines.
- Lead extraction complexity:Transvenous lead removal procedures carry mortality risks that limit upgrade pathways for legacy pacemaker patients.
Strategic Opportunities
- Leadless pacemaker penetration:Spain and Italy show underpenetrated uptake of intracardiac pacing devices relative to Northern European adoption curves.
- Subcutaneous ICD expansion:Vascular access complications in elderly populations are creating demand for extravascular defibrillation systems without transvenous leads.
- F-Gas Regulation adaptation:Sterilization process requalification under fluorinated gas restrictions is favoring manufacturers with in-house ethylene oxide capabilities.
Industry Challenges
- Electrophysiologist training pipelines:Fellowship program capacity in France, Germany, and the United Kingdom is insufficient to match procedural volume growth.
- Legacy system integration:Hospital IT infrastructure heterogeneity complicates remote monitoring platform deployment across multi-site health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cardiac Rhythm Management Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Pacemakers, Automated External Defibrillators, Implantable Cardioverter Defibrillators, Cardiac Monitors End User: Cardiology Clinics, Hospitals, Ambulatory Surgical Centers, Home Care Settings Technology: Wireless Monitoring, Biometric Sensors, Telemetry, Software Solutions Application: Heart Failure Management, Arrhythmia Treatment, Cardiac Rehabilitation, Electrophysiology Studies |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, Biotronik SE & Co KG, LivaNova PLC, MicroPort Scientific Corporation, Koninklijke Philips NV, SCHILLER AG, ZOLL Medical Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cardiac Rhythm Management Devices Market Shifts & Advancements
Digital health integration and minimally invasive form factors are converging to redefine cardiac rhythm management value propositions, with connectivity and complication reduction now central to competitive differentiation.
Leadless pacemaker technology is displacing traditional transvenous systems in elderly patient cohorts with vascular access limitations. German and French electrophysiology units are prioritizing these devices for octogenarian populations where lead-related infection risks outweigh upgrade flexibility. The shift is compressing revenue per procedure while expanding addressable patient populations previously excluded from device therapy.
EU MDR clinical evidence requirements are extending post-market surveillance obligations for implantable cardioverter defibrillators. Manufacturers must now submit systematic literature reviews and PMCF study protocols to notified bodies in Germany and the Netherlands. High-energy device segments face the steepest compliance cost escalation, favoring incumbents with established clinical data repositories.
Hospital purchasing consortia in the Netherlands and Belgium are consolidating cardiac device procurement through multi-year framework agreements. Traditional distributor relationships are giving way to direct manufacturer negotiations with regional buying groups. Southern European markets lag this consolidation, preserving fragmented channel structures with higher service intensity requirements.
Europe Cardiac Rhythm Management Devices Market Segmentation
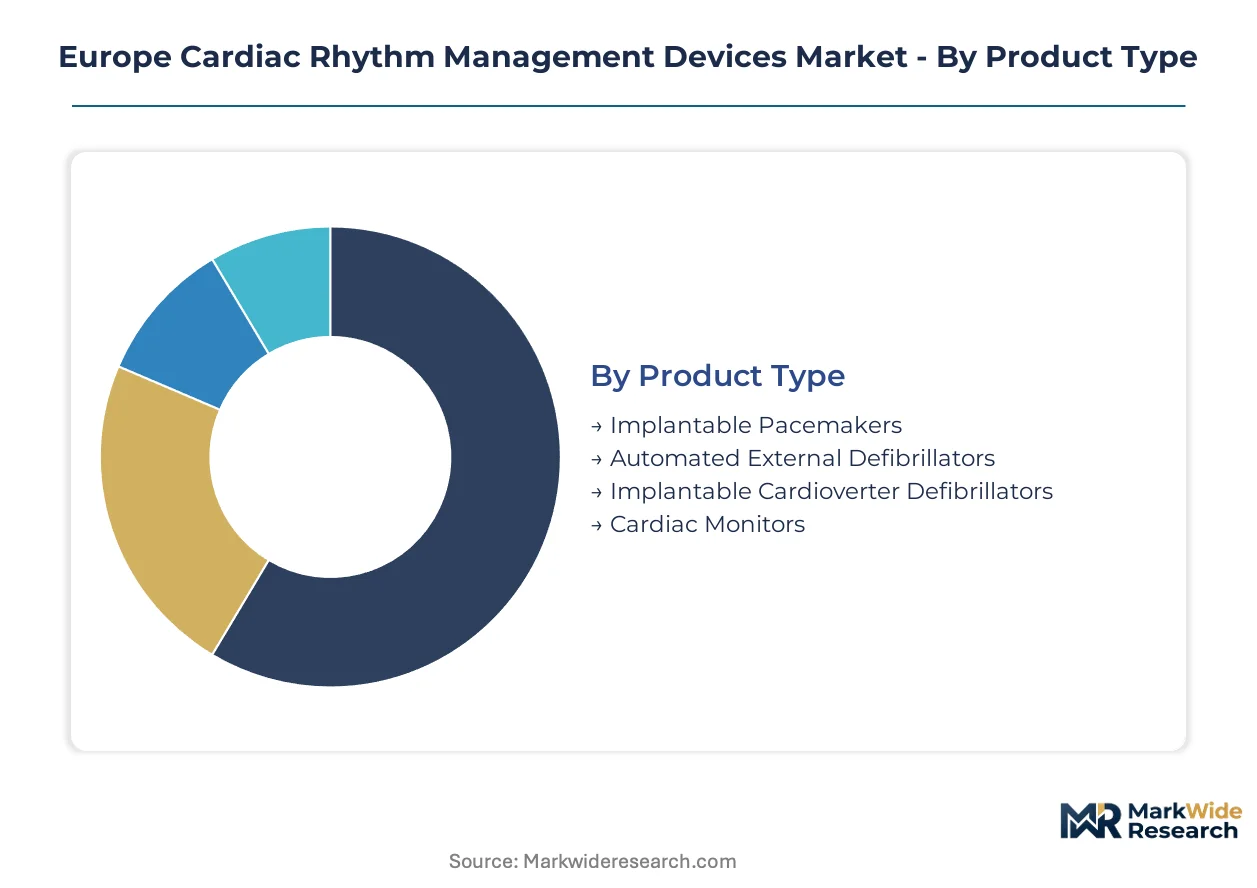
Cardiac rhythm management device segmentation reveals distinct channel economics and reimbursement pathways across European markets. Each dimension carries implications for go-to-market strategy, regulatory burden, and margin structure.
Product Type:
Hospital procurement consortia in the Netherlands and Belgium concentrate volume in ICD and pacemaker categories, while cardiology clinics drive external defibrillator and monitor purchases through distributor networks.
- Implantable Cardioverter Defibrillators:High-energy pulse generators with lithium iodine batteries deliver 30-40J shocks for ventricular arrhythmia termination. German electrophysiology labs generate concentrated demand as DRG reimbursement for complex device implantation expands. EU MDR clinical evidence requirements steepen regulatory barriers for new entrants.
- Implantable Pacemakers:Dual-chamber systems with 2.8V output and 10-15 year longevity manage bradycardia through transvenous or leadless delivery. French hospital systems prioritize leadless variants for elderly cohorts with vascular access complications. REACH battery chemistry compliance is standardizing supplier bases across manufacturing lines.
- Automated External Defibrillators:External shock delivery systems for public access deployment and emergency response. Spanish and Italian municipalities are expanding procurement for transport infrastructure.
- Cardiac Monitors:External and injectable loop recorders for long-term arrhythmia detection. Remote monitoring reimbursement codes in Belgium accelerate ambulatory adoption.
By volume, Implantable Pacemakers lead. By growth pace, Cardiac Monitors are expanding most quickly.
End User:
Cost tier stratification separates acute care investment from outpatient and home-based delivery models, with reimbursement velocity determining site-of-care migration.
- Hospitals:Tertiary centers with electrophysiology labs handle complex ICD implants and lead extractions. German DRG expansion for atrial fibrillation ablation is channeling capital into lab infrastructure.
- Cardiology Clinics:Specialized outpatient facilities manage pacemaker follow-up and device interrogation. French clinic networks are consolidating purchasing through regional frameworks.
- Ambulatory Surgical Centers:Same-day implant procedures for low-complexity pacemaker cases. Dutch reimbursement pathways favor ASC migration for selected patient cohorts.
- Home Care Settings:Remote monitoring platforms and wearable defibrillator systems for post-discharge surveillance. Telemedicine codes in Belgium reduce clinic visit frequency.
By installed base, Hospitals dominate. By volume shift, Home Care Settings are gaining share fastest.
Technology:
Application intensity varies by care setting, with wireless platforms enabling outpatient migration and biometric sensors supporting acute diagnostic precision.
- Wireless Monitoring:Cellular and Bluetooth-enabled transmission of device diagnostics to centralized surveillance platforms. Medtronic's CareLink network exemplifies recurring revenue models built on remote follow-up. Netherlands and Belgium reimbursement codes accelerate health system adoption.
- Biometric Sensors:Integrated accelerometers and impedance sensors for heart failure monitoring and activity tracking. German hospitals embed these in CRT-D systems for hemodynamic optimization.
- Telemetry:Real-time electrocardiographic transmission for inpatient arrhythmia detection. French cardiac wards prioritize these for post-operative surveillance.
- Software Solutions:Cloud-based analytics platforms for predictive arrhythmia detection and population health management. Hospital IT heterogeneity complicates multi-site deployment.
By deployment scale, Telemetry leads. By expansion trajectory, Wireless Monitoring climbs the fastest.
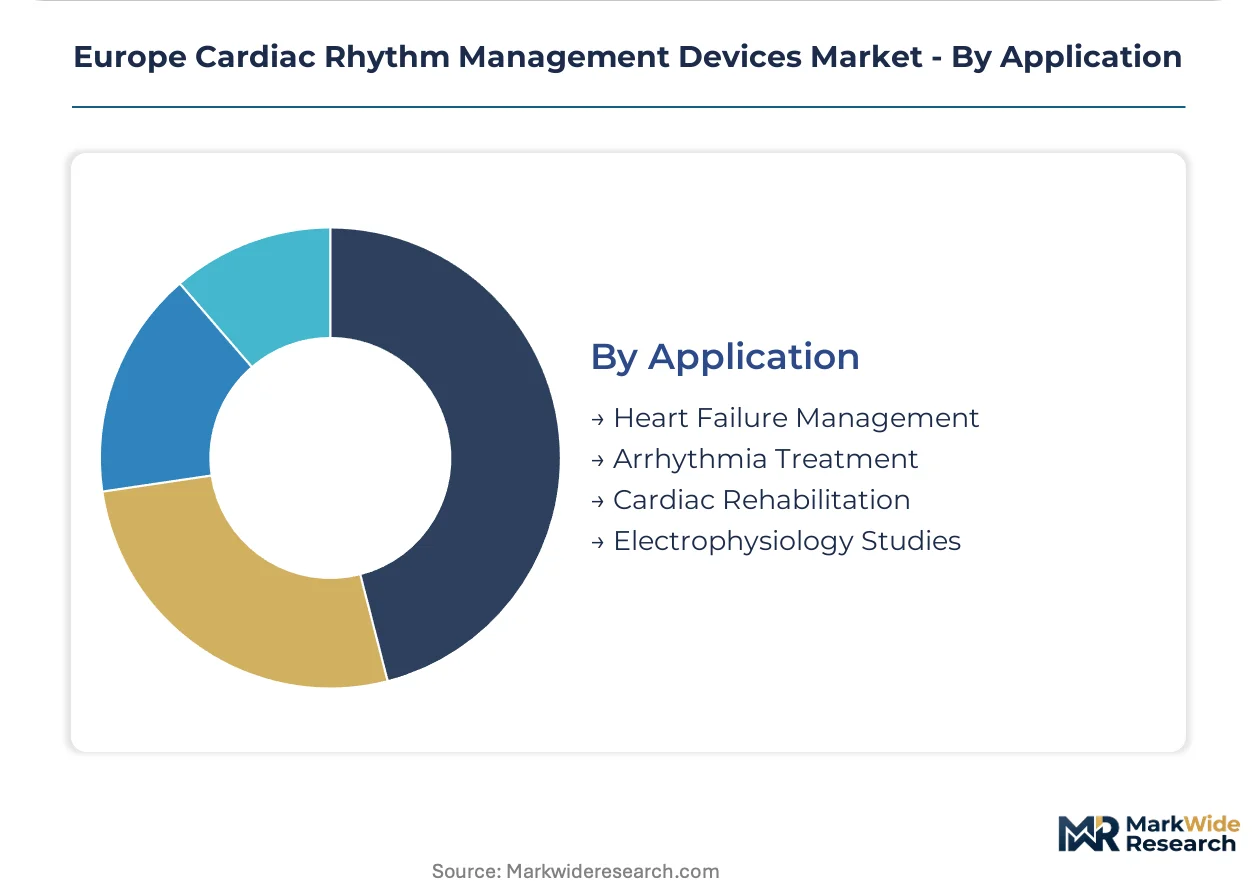
Application:
Volume concentration aligns with procedural reimbursement density, while emerging applications target underserved patient pathways.
- Arrhythmia Treatment:Catheter ablation and device therapy for atrial and ventricular rhythm disorders. France and Germany DRG expansion for AF ablation is driving electrophysiology lab investment.
- Heart Failure Management:Cardiac resynchronization therapy and hemodynamic monitoring for reduced ejection fraction patients. CRT-D systems command premium positioning in German tertiary centers.
- Electrophysiology Studies:Diagnostic catheter mapping for complex arrhythmia substrate characterization. Fellowship program bottlenecks in France and Germany constrain procedural growth.
- Cardiac Rehabilitation:Post-intervention monitoring and exercise programming with device integration. Home-based models are expanding in Netherlands reimbursement frameworks.
By procedure volume, Arrhythmia Treatment leads. By growth pace, Cardiac Rehabilitation is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR compliance timelines administered by German and Dutch notified bodies are compressing product development cycles across European cardiac rhythm management manufacturers. Hospital systems in France and Germany are expanding electrophysiology lab capacity to manage rising arrhythmia caseloads. Demand concentrates in Western European markets with mature reimbursement frameworks for catheter ablation and device therapy.
Germany
DRG reimbursement expansion for atrial fibrillation ablation procedures is channeling hospital investment toward electrophysiology lab infrastructure. The Federal Institute for Drugs and Medical Devices (BfArM) oversees CE marking conformity assessments for novel implantable systems. Berlin and Munich host concentrated electrophysiology research clusters where tertiary centers prioritize leadless pacemaker adoption for elderly cohorts.
France
ANSM regulatory oversight extends post-market surveillance obligations for high-energy implantable cardioverter defibrillators under EU MDR transitional provisions. Hospital purchasing consortia in the Île-de-France region are consolidating cardiac device procurement through multi-year framework agreements. Paris-based electrophysiology units are prioritizing leadless devices for octogenarian populations where lead-related infection risks outweigh upgrade flexibility.
Netherlands
Remote monitoring reimbursement codes are accelerating adoption of connected cardiac devices across Dutch health networks. The Dutch Healthcare Authority (NZa) regulates tariff structures for telemedicine-enabled device follow-up. The Randstad conurbation concentrates hospital purchasing consortia that negotiate directly with manufacturers rather than traditional distributor channels.
Italy
Underpenetrated uptake of intracardiac pacing devices relative to Northern European adoption curves creates expansion opportunities for leadless pacemaker penetration. The Italian Medicines Agency (AIFA) manages reimbursement authorization for novel implantable systems. Milan and Rome cardiac centers are expanding electrophysiology fellowship programs to address procedural volume growth constraints.
Belgium
Telemedicine codes reduce clinic visit frequency for device surveillance, accelerating home care setting migration. The Federal Agency for Medicines and Health Products (FAMHP) coordinates with notified bodies on CE marking assessments. Brussels and Antwerp hospital networks are deploying wireless monitoring platforms across multi-site health systems despite IT infrastructure heterogeneity challenges.
Europe Cardiac Rhythm Management Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European cardiac rhythm management devices. The upper tier commands recurring revenue streams through remote monitoring networks and leadless technology platforms. Specialist manufacturers occupy niches in battery chemistry optimization and sterilization process adaptation. Competitive moves center on portfolio prioritization toward higher-margin implantable systems and direct negotiation with hospital purchasing consortia.
Among the integrated leaders, Medtronic and Abbott exemplify divergent strategic archetypes in connected device ecosystems. Medtronic represents the surveillance-platform model through its CareLink network infrastructure. Abbott anchors the miniaturization vector with leadless pacemaker technology reducing complication rates in elderly populations. Boston Scientific Corporation occupies a position emphasizing subcutaneous defibrillation systems that eliminate transvenous lead complications. These three entities collectively illustrate how scale, connectivity, and form factor innovation define competitive positioning under tightening EU MDR evidence requirements.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Biotronik SE & Co KG |
| LivaNova PLC |
| MicroPort Scientific Corporation |
| Koninklijke Philips NV |
| SCHILLER AG |
| ZOLL Medical Corporation |
| Others |
Supply & Pricing Matrix
Multi-year framework agreements with hospital purchasing consortia in the Netherlands and Belgium lock in supply access for implantable pulse generators while anchoring price visibility across the contract term. These structures insulate manufacturers from spot volatility in lithium iodine cell markets while committing volume to notified body-cleared product lines.
Pricing Analysis
German electrophysiology labs pay 15-25% premiums over Spanish and Italian procurement for identical ICD systems due to consolidated buying power and bundled service contracts. Three-tier pricing structure across premium, standard, and economy levels segments by clinical evidence depth and remote monitoring integration. Pricing pressure stems from DRG rate compression in French hospital systems. Cardiology clinics in Southern Europe exhibit highest price sensitivity; German tertiary centers prioritize complication reduction over unit cost.
Supply Chain Analysis
Six-month safety stock requirements for lithium iodine cells extend inventory cycles beyond typical semiconductor lead times. Manufacturing concentrates in Germany, Switzerland, and the Netherlands for final pulse generator assembly, with cell production drawing from Japanese and Swiss chemical specialists. Single-source vulnerability in high-purity iodine refining creates exposure to REACH compliance disruptions. Distribution runs through direct manufacturer negotiations with regional hospital consortia, bypassing traditional distributor layers in Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrophysiologist training bottlenecks in France, Germany, and the United Kingdom constrain procedural capacity expansion, making automated remote monitoring platforms and simplified implant workflows the scarce capabilities determining competitive outcomes.
For Market Incumbents: Secure exclusive supply agreements with Swiss and Japanese battery specialists to lock in lithium iodine cell allocation ahead of competing manufacturers. Expand in-house ethylene oxide sterilization capacity to capture F-Gas Regulation compliance premiums from competitors dependent on fluorinated gas processes. Remote monitoring platform integration represents the critical lever for recurring revenue defense against leadless pacemaker specialists. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission protocols in the Netherlands offers the most penetrable regulatory pathway for novel subcutaneous ICD systems. Target Italian and Spanish electrophysiology units where leadless pacemaker penetration trails Northern European curves by 40-50%. Lead with complication-rate clinical evidence rather than price positioning to bypass incumbent service relationships. For Investors and Strategic Acquirers: Remote monitoring software specialists with hospital IT integration capabilities present the highest-value acquisition archetype as connectivity becomes the primary differentiation vector. Long-term viability hinges on EU MDR clinical data repository depth rather than manufacturing scale alone. Watch Netherlands and Belgium reimbursement code expansion for telemedicine-enabled follow-up as the signal for platform economics tipping toward surveillance-centric models.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Notified body pre-submission in Germany compresses time-to-market for novel implantable systems by 8-12 months. |
| Hospital System Partnership | Direct negotiations with Dutch purchasing consortia secure multi-year volume commitments and displace distributor relationships. |
| Software Companion Development | Cloud-based analytics platforms for predictive arrhythmia detection create recurring revenue streams beyond device sale. |
| Reimbursement Strategy | Telemedicine code advocacy in Belgium and Netherlands accelerates remote monitoring adoption and clinic visit reduction. |
| Backward Integration | In-house ethylene oxide sterilization captures F-Gas Regulation compliance cost advantages over fluorinated gas-dependent competitors. |
Research Methodology
Cross-validation between electrophysiology lab directors and hospital purchasing committee interviews anchors the qualitative findings on procurement behavior and device selection criteria. Primary fieldwork encompassed biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies in Germany and the Netherlands. Secondary validation drew from hospital procurement databases, GPO contract disclosures, EUDAMED device registration data, and ANSM post-market surveillance reports. Bottom-up volume modeling triangulated against top-down reimbursement expenditure estimates across the analysis window.
Sensitivity analysis tested forecast outputs against alternative scenarios for EU MDR transition timeline delays and electrophysiologist training pipeline expansion rates. The analytical framework segmented by product type, end user site-of-care, connectivity technology, and clinical application intensity across the projection horizon. CAGRs derived from procedure volume growth curves weighted by DRG reimbursement velocity and device replacement cycle assumptions. Forecast inputs incorporated leadless pacemaker adoption elasticity and remote monitoring platform penetration rates by national reimbursement framework.
Decision-makers should treat outputs as directional under assumptions of stable EU MDR enforcement intensity and continued DRG expansion for catheter ablation procedures; material deviation in notified body capacity or reimbursement code authorization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bunion Correction Systems Market
Medical Devices
Smart Bassinet Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Global Mobile C-Arm Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Enteral Stents Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
North America Wheelchair Market
Medical Devices
Illuminating Eye Massagers Market