
 Global Electroceuticals Market | 2026-2036
Global Electroceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electroceuticals Market Foresight
Market Context with Strategic Players
Silicon carbide is consolidating as the preferred substrate material in next-generation implantable pulse generators, displacing legacy titanium housings across cardiac and neurostimulation platforms. Medtronic plc anchors North American manufacturing scale through captive foundry partnerships for hermetic ceramic-to-metal seals. Boston Scientific Corporation differentiates via R&D intensity in injectable electrode arrays for peripheral nerve targeting. Abbott Laboratories leverages vertical integration into battery cell production for its recharge-free implantable portfolio.
Technical Definition and Structural Segments
Electroceuticals are implantable, wearable, or external devices that deliver precisely modulated electrical impulses to neural, cardiac, or muscular tissue to restore physiological function, typically operating at pulse widths of microseconds to milliseconds and frequencies from 1 Hz to 10 kHz depending on therapeutic target. Their primary commercial purpose is to replace or supplement pharmaceutical interventions for chronic conditions through closed-loop bioelectronic feedback systems. Implantable devices command the dominant margin pool due to surgical placement requirements and long-term monitoring service contracts, while wearable devices represent the fastest-expanding delivery mode as ambulatory electrophysiology monitoring gains reimbursement traction. Neurological disorders and cardiovascular conditions together concentrate the majority of therapy-area revenue, with spinal cord stimulators and cardiac pacemakers forming the mature core of product-type shipments.
Regulatory Frame and Forward-Looking Close
FDA's Breakthrough Devices Program, the EU Medical Device Regulation's Class III implantable requirements, and Japan's PMDA Sakigake designation system collectively elevate clinical trial burdens and post-market surveillance obligations for electroceutical manufacturers seeking multi-region approval. These frameworks shape demand by favoring companies with established regulatory affairs infrastructure and penalizing late entrants lacking predicate device pathways or sufficient safety databases. Stakeholders must monitor reimbursement parity decisions between electroceutical interventions and pharmaceutical standard-of-care across major health technology assessment bodies, as these determinations will dictate commercial velocity in the next phase of market development.
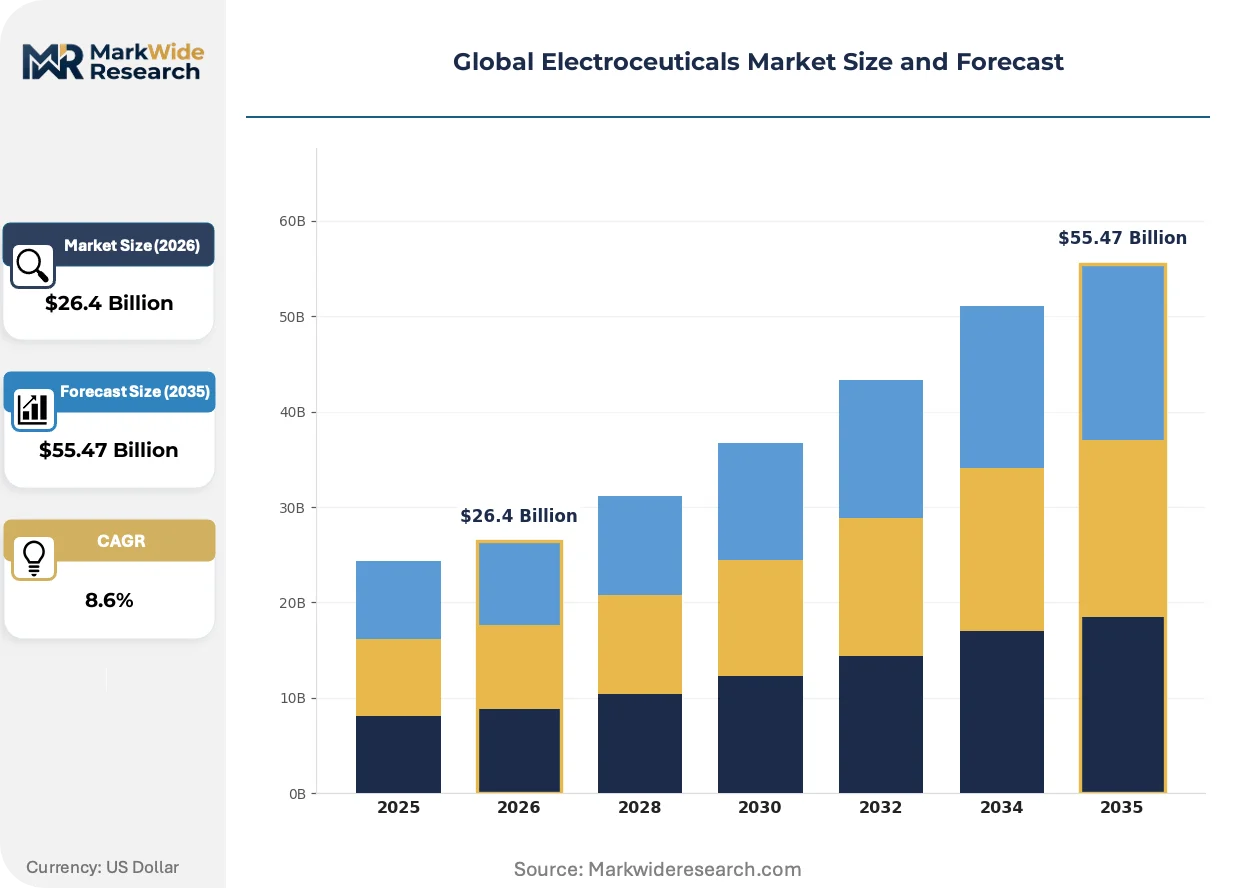
Market Dynamics
Silicon carbide substrate adoption is compressing legacy titanium supply chains while FDA and EU MDR tighten clinical evidence thresholds for neuromodulation approvals, forcing manufacturers to restructure regulatory affairs infrastructure and captive foundry partnerships.
Growth Catalysts
- EU Medical Device Regulation Class III pathways:Stricter implantable requirements are filtering out undercapitalized competitors and concentrating procurement among established manufacturers with predicate device databases.
- Spinal cord stimulation corridors in the United States:Reimbursement parity decisions by major health technology assessment bodies are expanding addressable patient populations for chronic pain interventions.
- Closed-loop bioelectronic feedback systems:Advances in real-time physiological monitoring are enabling adaptive stimulation protocols that reduce physician intervention frequency and improve therapy adherence.
Market Restraints
- Hermetic ceramic-to-metal seal supply concentration:Captive foundry partnerships in Germany and Japan limit second-source availability for next-generation pulse generator housings.
- Platinum-iridium electrode alloy cost volatility:Precious metal price swings compress margins on high-density electrode arrays for peripheral nerve targeting.
- Japan PMDA Sakigake designation timelines:Accelerated approval pathways require pre-negotiated reimbursement contracts that delay commercial launch sequencing.
Strategic Opportunities
- Injectable electrode arrays:Minimally invasive peripheral nerve targeting is opening ambulatory surgical center channels previously blocked by open-surgical implant requirements.
- India's CDSCO medical device rules:Streamlined import licensing for Class B and C devices is reducing time-to-market for wearable electrophysiology monitors.
- Recharge-free battery chemistry convergence:Lithium carbon monofluoride cell integration with low-power ASIC design is eliminating patient compliance barriers from charging protocols.
Industry Challenges
- Neuroelectrophysiology modeling talent scarcity:Computational biologists capable of predicting current field distributions in complex tissue geometries command premium compensation and extended recruitment cycles.
- FDA premarket approval supplement backlog:Firmware updates for closed-loop algorithms require redundant clinical validation, slowing iterative product improvement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electroceuticals Market |
| Market Size in 2026 | $26.4 Billion |
| Market Size in 2035 | $55.47 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulators, Cardiac Pacemakers, Cochlear Implants, Spinal Cord Stimulators, Transcutaneous Electrical Nerve Stimulators, Vagus Nerve Stimulators Therapy Area: Neurological Disorders, Cardiovascular Conditions, Chronic Pain, Hearing Impairment, Gastrointestinal Disorders, Respiratory Issues End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories, Rehabilitation Centers, Home Care Settings Delivery Mode: Implantable Devices, Wearable Devices, Injectable Electrodes, Non-invasive Patches, External Stimulators, Wireless Systems |
| Companies Covered | LivaNova PLC, Cochlear Ltd., Medtronic plc, Nevro Corp., Sonova Holding AG, Boston Scientific Corporation, Biotronik SE & Co. KG, NeuroPace, Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electroceuticals Market Shifts & Advancements
Electroceutical platforms are converging around materials science breakthroughs and regulatory science investments that separate scalable manufacturers from contract-reliant assemblers. Three developments are compressing competitive timelines.
Silicon carbide is consolidating as the dominant substrate for implantable pulse generator hermetic packaging. Cardiac rhythm management and neurostimulation divisions at major hospital procurement groups in Germany and Japan are specifying SiC-to-metal seals in next-generation tenders. This material shift is compressing titanium housing supply chains and forcing legacy metal-forming suppliers into component sub-tier roles.
EU MDR Article 10 clinical evaluation requirements are extending post-market surveillance obligations to fifteen-year follow-up periods for active implantable devices. Manufacturers must now maintain electronic health record integration infrastructure across multiple national systems. Cardiac pacemaker portfolios face the steepest compliance cost escalation, driving consolidation among mid-scale European device sponsors lacking predicate device grandfathering.
Hospital value analysis committees are unbundling device procurement from long-term monitoring service contracts. United States integrated delivery networks now separately negotiate pulse generator acquisition, implantation procedure reimbursement, and remote monitoring subscription fees. This trifurcation is compressing upfront device margins while expanding recurring revenue pools for cloud-connected diagnostic platforms.
Global Electroceuticals Market Segmentation
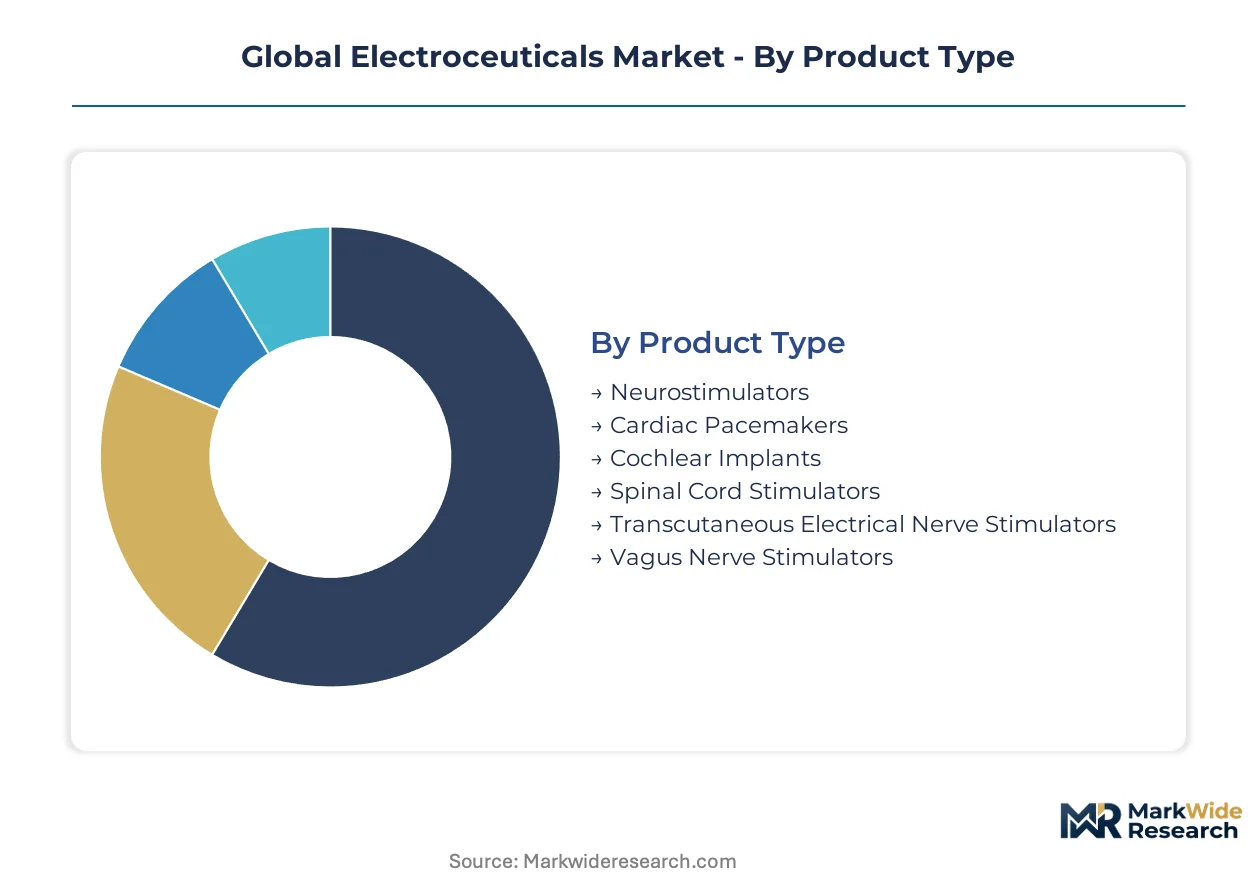
Electroceutical segmentation reveals divergent regulatory pathways and margin architectures across product categories. Each dimension carries distinct FDA premarket approval timelines, EU MDR classification burdens, and reimbursement coding requirements that reshape competitive positioning.
Product Type:
FDA Class III premarket approval requirements and EU MDR Annex IX conformity assessments concentrate on active implantable segments, while external stimulators navigate lighter Class II pathways.
- Neurostimulators:Deep brain and peripheral nerve platforms deliver precisely modulated impulses through multi-contact electrode arrays. Demand clusters in the United States' movement disorder centers and Germany's epilepsy surgery wards as closed-loop adaptive algorithms reduce programming burden.
- Cardiac Pacemakers:Dual-chamber and leadless devices restore sinus rhythm through endocardial or epicardial electrode placement. Procurement concentrates in Japan's cardiac rhythm management clusters where PMDA Sakigake fast-track approvals accelerate next-generation biocompatible lead introductions.
- Cochlear Implants:Multi-channel auditory processors convert sound to electrical stimulation of the cochlear nerve.
- Spinal Cord Stimulators:Dorsal column arrays interrupt pain signal transmission for chronic intractable conditions.
- Transcutaneous Electrical Nerve Stimulators:External skin-surface devices deliver low-voltage pulses for temporary analgesia.
- Vagus Nerve Stimulators:Cervical implantation targets refractory epilepsy and treatment-resistant depression pathways.
Leading the category by volume: Cardiac Pacemakers. Growing fastest: Neurostimulators.
Therapy Area:
Reimbursement parity decisions by CMS and Germany's G-BA separate chronic condition categories into inpatient procedure bundles versus outpatient prescription codes.
- Neurological Disorders:Parkinson's disease, essential tremor, and dystonia interventions command premium device pricing due to irreversible disease progression and absence of curative pharmaceutical alternatives.
- Cardiovascular Conditions:Bradycardia, heart failure, and arrhythmia management form the volume anchor across hospital procurement tenders in the United States, Germany, and Japan.
- Chronic Pain:Failed back surgery syndrome and complex regional pain syndrome drive spinal cord stimulator placements through integrated delivery network value analysis committees.
- Hearing Impairment:Pediatric and adult cochlear implantation benefits from mandated coverage in most OECD national health systems.
- Gastrointestinal Disorders:Gastroparesis and fecal incontinence applications remain underpenetrated due to limited long-term efficacy data.
- Respiratory Issues:Phrenic nerve and hypoglossal stimulation for central sleep apnea represent emerging indications with evolving coverage policies.
Cardiovascular Conditions anchor absolute revenue. Chronic Pain is expanding most quickly as ambulatory surgical center channels broaden access.
End User:
Site-of-care economics dictate device form factor and service contract structures, with hospital purchasing consortiums extracting volume discounts unavailable to smaller settings.
- Hospitals:Academic medical centers and community hospital systems concentrate complex implantable procedures requiring electrophysiology lab infrastructure and 24-hour emergency extraction capabilities.
- Ambulatory Surgical Centers:Minimally invasive peripheral nerve and spinal cord stimulator trials are migrating to freestanding ASCs as reimbursement codes separate facility fees from professional components.
- Specialty Clinics:Pain management and movement disorder centers handle device programming, medication adjustments, and troubleshooting.
- Diagnostic Laboratories:Electrophysiology testing and device interrogation support pre-implant candidacy assessments.
- Rehabilitation Centers:Post-implant functional training and adaptive stimulation protocol optimization occur in inpatient and outpatient rehabilitation settings.
- Home Care Settings:Remote monitoring platforms and patient-controlled external stimulators enable chronic disease management outside institutional walls.
Hospitals retain the dominant procurement volume. Home Care Settings show the steepest expansion trajectory as telehealth reimbursement stabilizes.
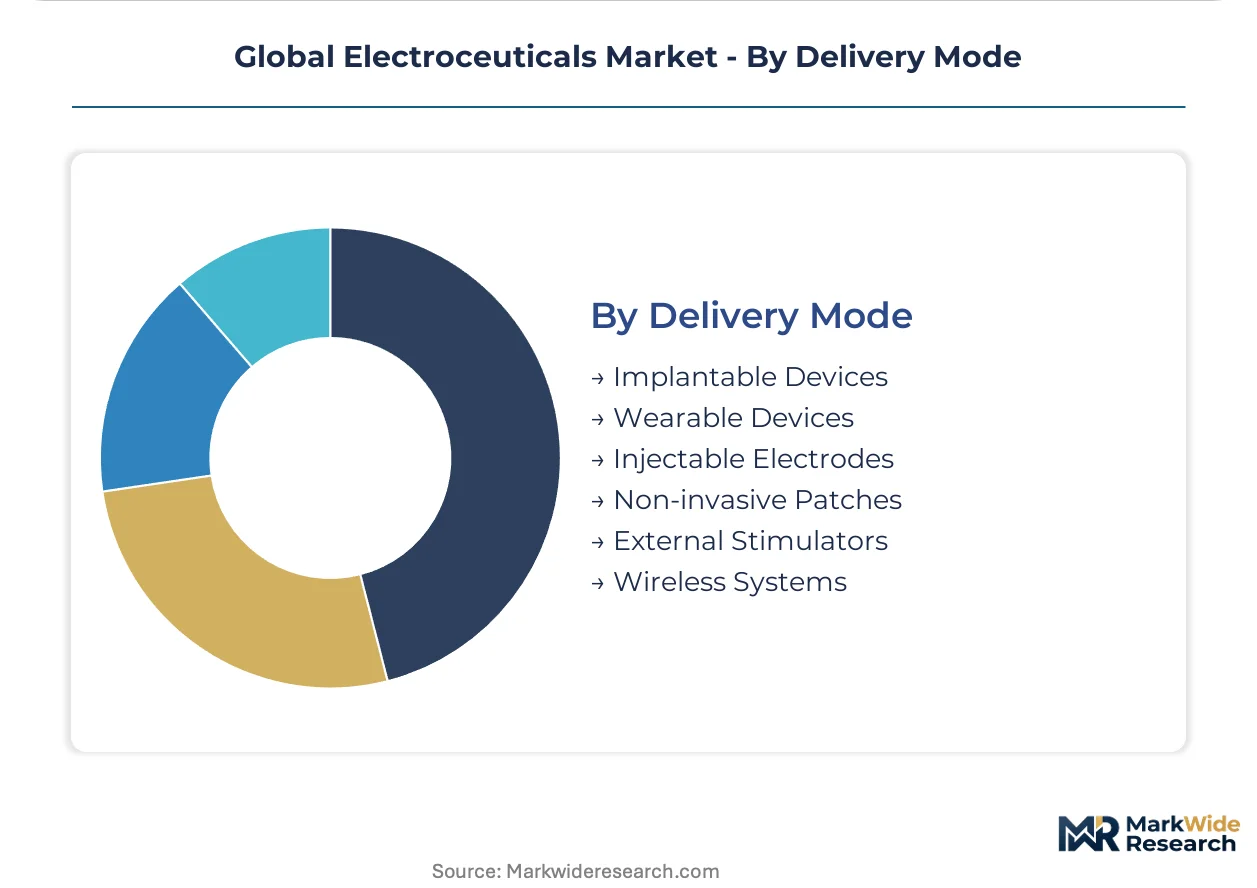
Delivery Mode:
Hermetic packaging requirements and battery longevity specifications separate implantable from external categories, with wireless power transfer and data telemetry now standard across premium tiers.
- Implantable Devices:Fully internal pulse generators with transcutaneous charging or primary cell designs require surgical placement and explant for battery depletion.
- Wearable Devices:Ambulatory electrophysiology monitors and external stimulators clip to clothing or adhere to skin for intermittent or continuous therapy delivery.
- Injectable Electrodes:Minimally invasive needle-delivered arrays target peripheral nerves without open surgical dissection, opening office-based procedure channels.
- Non-invasive Patches:Transdermal electrical delivery systems adhere to skin surface for temporary neuromodulation or diagnostic recording.
- External Stimulators:Handheld or body-worn devices connect to surface electrodes for patient-controlled pain management or muscle rehabilitation.
- Wireless Systems:Leadless cardiac pacemakers and distributed electrode networks eliminate transvenous leads through RF or ultrasonic power and data links.
Implantable Devices dominate revenue concentration. Wearable Devices are gaining share fastest as consumer-facing form factors attract direct-to-patient channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Ireland and Singapore concentrate electroceutical manufacturing through tax-advantaged structures. These jurisdictions attract assembly operations for implantable pulse generators serving hospital procurement networks across three continents.
United States
Spinal cord stimulation corridors in Minnesota and Massachusetts drive neurostimulator demand through integrated delivery networks. FDA Breakthrough Devices Program accelerates closed-loop algorithm approvals for movement disorder centers. The Twin Cities cluster anchors cardiac rhythm management procurement for academic medical centers.
Germany
Cardiac pacemaker tenders from Berlin and Munich hospital purchasing consortiums sustain implantable device volumes. EU MDR Class III requirements filter competitors lacking fifteen-year post-market surveillance infrastructure. The Erlangen medical technology cluster specializes in hermetic ceramic-to-metal seal production for pulse generator housings.
Japan
PMDA Sakigake fast-track designations compress leadless pacemaker approval timelines for Tokyo and Osaka electrophysiology labs. Recharge-free battery chemistry convergence addresses patient compliance barriers in aging demographics. The Kobe biomedical innovation cluster supports next-generation biocompatible lead development.
India
CDSCO streamlined import licensing for Class B and C wearable electrophysiology monitors reduces time-to-market for ambulatory diagnostic platforms. Domestic manufacturing incentives under PLI schemes attract assembly operations for external stimulators. Hyderabad's medical device park concentrates contract manufacturing for neurostimulation peripherals.
Switzerland
Swissmedic expedited review pathways for neuromodulation devices support Geneva and Zurich specialty clinic procurement. Precision engineering capabilities in the Jura Arc sustain microelectrode array production for peripheral nerve targeting. Basel's pharmaceutical-electroceutical convergence cluster drives closed-loop bioelectronic feedback system development.
Global Electroceuticals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with implantable device categories consolidating around captive foundry partnerships while wearable categories fragment among component assemblers. The market structure favors entities with vertical integration into battery cell production and hermetic packaging capabilities. Three archetypes dominate: diversified medical technology conglomerates with full-stack manufacturing, mid-scale neuromodulation specialists with predicate device databases, and emerging injectable electrode developers targeting ambulatory surgical channels. Competitive moves concentrate on regulatory affairs infrastructure expansion and silicon carbide substrate supply security.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories anchor the implantable pulse generator tier through manufacturing scale advantages. Boston Scientific Corporation exemplifies the mid-scale specialist archetype with concentrated R&D intensity in peripheral nerve targeting platforms. These three entities occupy positions shaped by EU MDR compliance infrastructure and FDA premarket approval pathway expertise rather than interchangeable component supply.
| Leading Market Players |
|---|
| LivaNova PLC |
| Cochlear Ltd. |
| Medtronic plc |
| Nevro Corp. |
| Sonova Holding AG |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| NeuroPace, Inc. |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Hospital value analysis committees in the United States are unbundling device procurement from long-term monitoring service contracts, forcing manufacturers to restructure pricing architectures and compress titanium housing supply chains into component sub-tier roles.
Pricing Analysis
Short lead-time premiums for silicon carbide substrate hermetic seals command pricing advantages over legacy titanium spot inventory as cardiac rhythm management tenders accelerate material transitions. Three-tier pricing structure across premium adaptive closed-loop systems, standard programmable generators, and economy fixed-rate devices reflects FDA Breakthrough Device certification tier and battery chemistry sophistication. Cost compression in economy tiers is intensifying due to India's CDSCO import licensing expansion for wearable monitors. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with captive electrophysiology infrastructure show lowest.
Supply Chain Analysis
Explanted pulse generator refurbishment flows are creating secondary material recovery channels for platinum-iridium electrode alloys and lithium carbon monofluoride cells. Manufacturing concentrates in Germany's Erlangen cluster for ceramic-to-metal seals, Japan's Kobe biomedical zone for biocompatible leads, and Ireland's special economic zones for final assembly. Raw material dependencies center on silicon carbide substrates, platinum-group metals for electrode arrays, and hermetic packaging ceramics. Single-source vulnerability in captive foundry partnerships for SiC-to-metal bonding creates structural exposure. Distribution runs through hospital purchasing consortiums and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
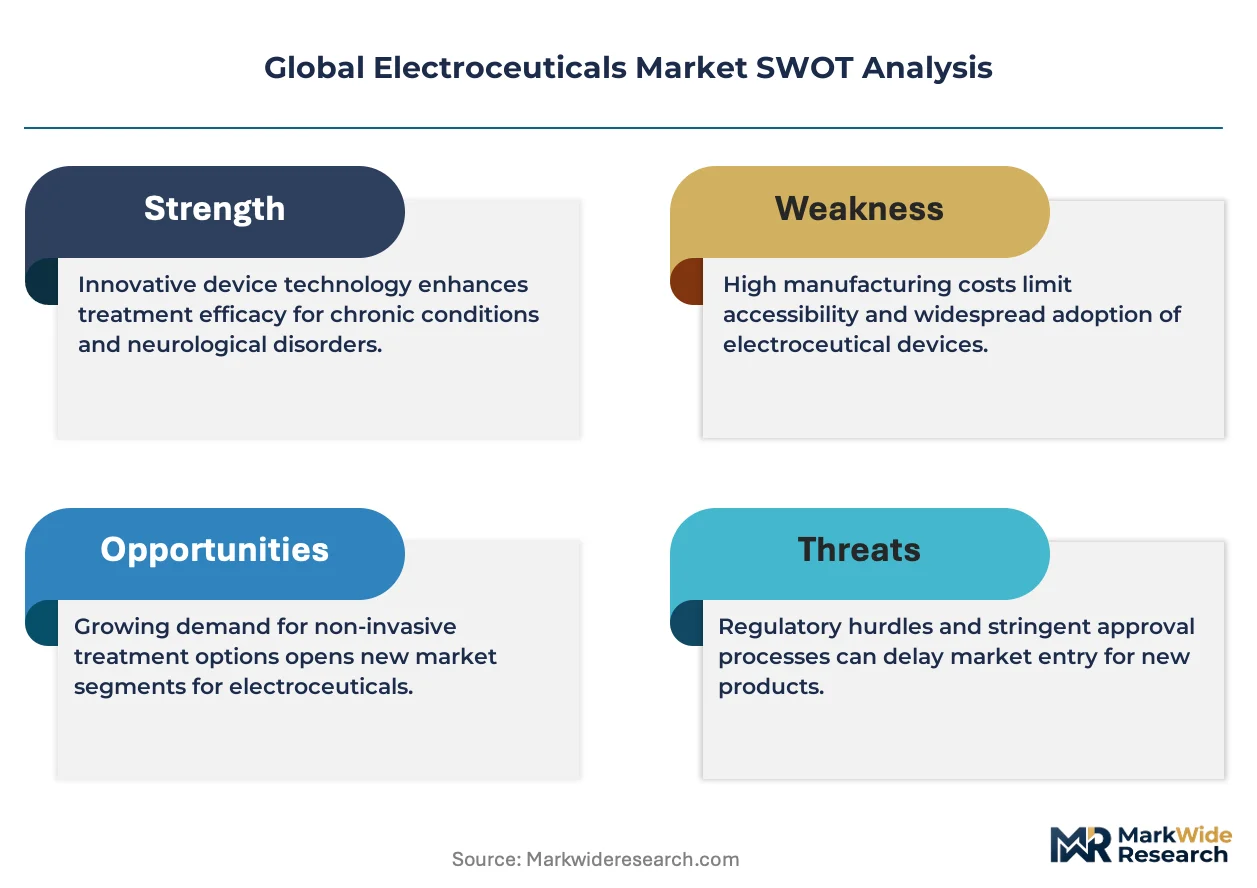
This market is consolidating around regulatory affairs infrastructure scale as EU MDR fifteen-year surveillance obligations and FDA premarket approval backlogs force undercapitalized competitors toward exit.
For Market Incumbents: Deploy predicate device database leverage to accelerate iterative closed-loop algorithm approvals through FDA premarket approval supplement pathways. Secure captive silicon carbide foundry partnerships in Germany and Japan to preempt second-source constraints on next-generation hermetic packaging. The threat of injectable electrode array developers opening ambulatory surgical center channels demands defensive reimbursement strategy investments. For New Entrants and Emerging Players: Launch via India's CDSCO streamlined import licensing for Class B and C wearable electrophysiology monitors to bypass entrenched hospital procurement consortiums. Target gastrointestinal disorder applications for vagus nerve stimulation where long-term efficacy data gaps create white-space opportunity. Pursue direct-to-patient channels for rechargeable external stimulators as telehealth reimbursement stabilizes. For Investors and Strategic Acquirers: The window for entry favors mid-scale neuromodulation specialists with established EU MDR compliance infrastructure and predicate device grandfathering. Long-term viability hinges on vertical integration into battery cell production or hermetic packaging capabilities. Watch FDA premarket approval timeline compression for closed-loop algorithms as the inflection signal distinguishing scalable manufacturers from contract assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates closed-loop algorithm approvals for movement disorder centers in Minnesota and Massachusetts corridors. |
| EU MDR Class III Compliance Infrastructure | Fifteen-year surveillance obligations filter competitors lacking electronic health record integration across German and Swiss national systems. |
| Silicon Carbide Foundry Partnership | Hermetic ceramic-to-metal seal supply security anchors procurement tenders from Berlin and Munich hospital consortiums. |
| Injectable Electrode Array Development | Minimally invasive peripheral nerve targeting opens ambulatory surgical center channels previously blocked by open-surgical requirements. |
| Recharge-Free Battery Chemistry Convergence | Lithium carbon monofluoride cell integration eliminates patient compliance barriers in Japan's aging demographic. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, biomedical engineers at academic medical centers, and regulatory affairs leads at active implantable device sponsors underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA premarket approval databases, EU MDR notified body conformity assessments, CMS reimbursement coding decisions, and hospital procurement tender records. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across product type, therapy area, and delivery mode dimensions.
Comparable historical reference periods spanning cardiac rhythm management and neurostimulation platform lifecycles anchored the forecast window across the analysis window. The analytical framework modeled implantable versus wearable delivery modes, neurological versus cardiovascular therapy areas, and closed-loop versus open-loop stimulation architectures. CAGRs derived from procedure volume trends, replacement cycle dynamics, and reimbursement parity evolution. Industry-specific inputs included PMDA Sakigake approval velocity and EU MDR transition timeline compliance rates.
Regulatory approval delays, reimbursement coding fragmentation, and silicon carbide substrate supply concentration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding predicate device pathway availability and health technology assessment body electroceutical-pharmaceutical parity decisions. Practitioners should monitor FDA premarket approval supplement backlog duration and EU MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Liposuction Devices Market
Medical Devices
Global Transradial Access Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
Cervical Fusion Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Injection Pen Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
3D Printed Implants Market