
 Global Hysteroscope Market | 2026-2036
Global Hysteroscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hysteroscope Market Foresight
Hospital procurement of hysteroscopic equipment is tilting toward bundled service contracts that include maintenance and training. KARL STORZ SE & Co. KG leverages its integrated endoscopy tower systems to anchor premium placements in university hospitals across Germany and Japan. Olympus Corporation competes through proprietary imaging processors that enhance visual resolution during operative hysteroscopy. Stryker sustains its position by extending capital financing programs that lower upfront acquisition costs for mid-sized gynecology practices.
A hysteroscope is a slender, illuminated optical instrument inserted through the cervix to visualize the uterine cavity, typically employing rigid rod-lens systems with 2.9 mm to 4.0 mm outer diameters or flexible fiberoptic designs for office-based diagnostic screening. Its primary purpose is to enable direct visualization for identifying endometrial pathology, guiding tissue resection, and performing sterilization or fertility-preserving interventions without abdominal incision. Rigid hysteroscopes dominate capital equipment budgets due to superior optical clarity and instrument channel capacity, while disposable hysteroscopes represent the fastest-expanding segment as facilities seek to eliminate reprocessing liability and cross-contamination risk. Diagnostic procedures constitute the volume base, though operative interventions command higher per-procedure revenue and drive replacement cycles for electrosurgical-compatible sheath systems.
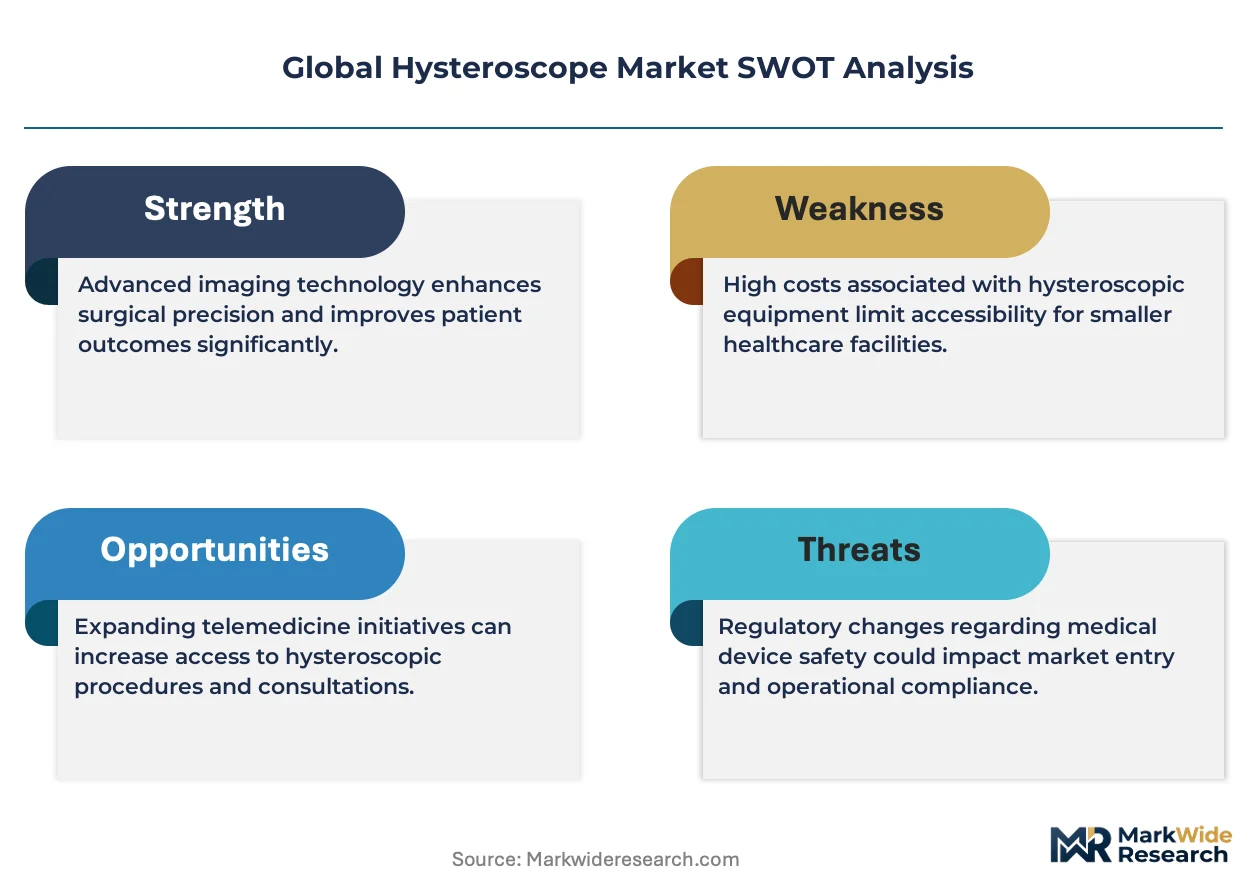
FDA premarket notification requirements under 21 CFR Part 884 govern hysteroscope safety and biocompatibility, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for reusable and single-use variants alike. ISO 13485 quality management certification shapes supplier qualification for original equipment manufacturers sourcing optical assemblies from Asian contract manufacturers. Stakeholders must monitor reimbursement parity between office-based and facility-based hysteroscopy codes, as payment differentials increasingly dictate site-of-service migration and equipment procurement specifications.
Market Dynamics
The migration from reusable to single-use hysteroscope systems is compressing capital equipment cycles and redistributing value capture toward disposable manufacturers across hospital and ambulatory settings.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's abbreviated pathway for predicate-based single-use hysteroscope submissions accelerates commercialization timelines for disposable designs targeting outpatient clinics.
- Office-based procedural expansion:Ambulatory surgical centers in the United States deploy miniaturized flexible hysteroscopes to capture same-day diagnostic volumes previously routed to hospital operating rooms.
- Reprocessing liability elimination:Cross-contamination risk mitigation drives substitution of sterilization-dependent rigid systems with sterile-packaged disposables in fertility clinics and community hospitals.
Market Restraints
- Optical component supply concentration:German and Japanese precision optics suppliers control rod-lens assembly production, creating single-source vulnerability for rigid hysteroscope manufacturers.
- EU MDR clinical evidence requirements:The European Medical Device Regulation mandates costly post-market surveillance studies for reusable hysteroscope variants, extending recertification timelines.
- Capital equipment lock-in effects:Integrated endoscopy tower investments by university hospitals create switching costs that delay single-use adoption despite per-procedure cost advantages.
Strategic Opportunities
- India outpatient gynecology infrastructure:Government hospital modernization programs create first-mover advantage for portable hysteroscope systems targeting district-level maternal health screening.
- Artificial intelligence imaging convergence:Machine learning algorithms paired with 4K hysteroscope cameras enable real-time polyp detection, differentiating premium equipment tiers.
- Japan's aging fertility patient base:METI-supported precision medicine initiatives subsidize diagnostic hysteroscopy adoption for recurrent implantation failure protocols.
Industry Challenges
- Electrosurgical compatibility engineering:Bipolar resection sheath integration with monopolar legacy generators requires redesign cycles that fragment R&D resources across incompatible energy platforms.
- ISO 13485 certification bottlenecks:Asian contract manufacturers face extended audit backlogs, delaying component qualification for hysteroscope OEMs restructuring supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hysteroscope Market |
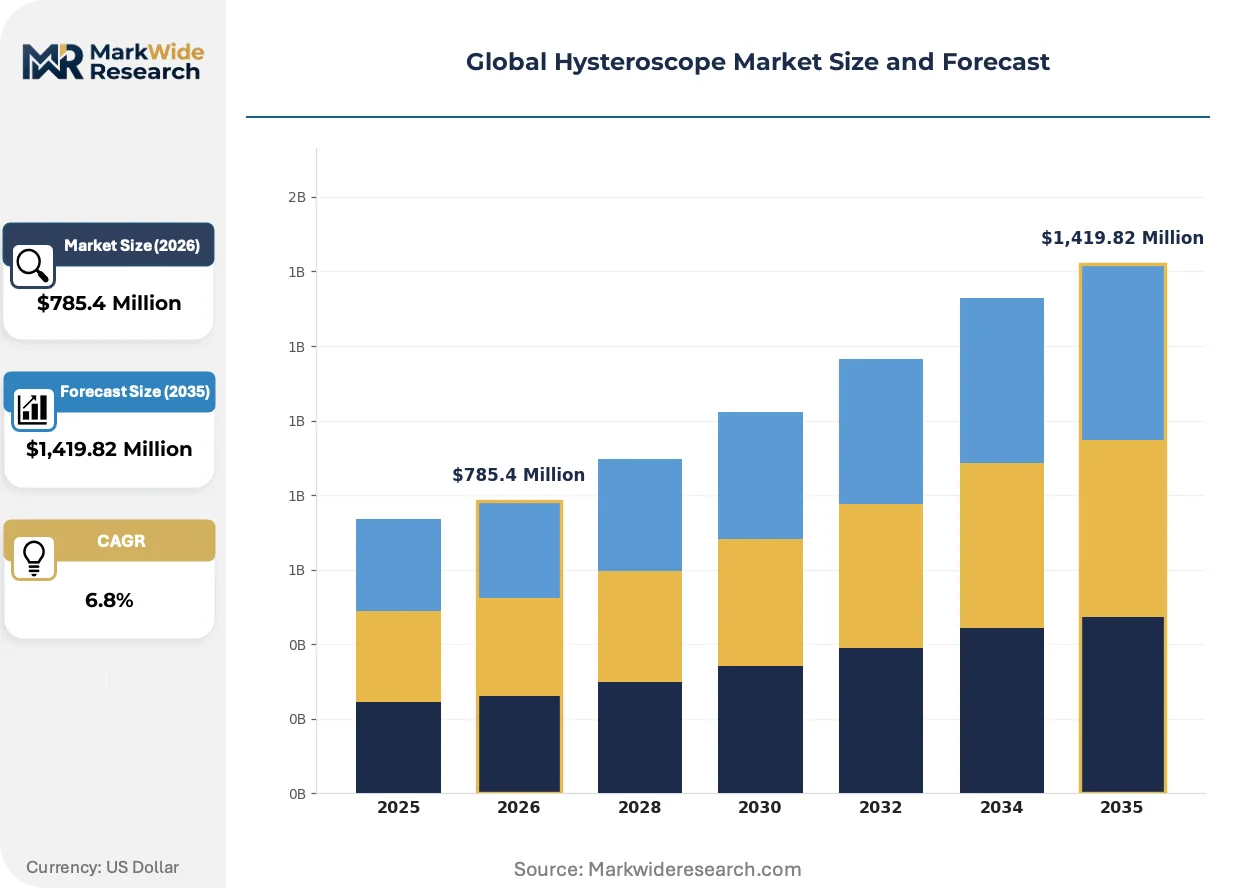
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,419.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Hysteroscopes, Flexible Hysteroscopes, Semi-Rigid Hysteroscopes, Disposable Hysteroscopes Application: Diagnostic Procedures, Operative Interventions, Fibroid Removal, Endometrial Ablation, Adhesiolysis End User: Specialty Clinics, Ambulatory Surgical Centers, Gynecology Departments, Fertility Clinics Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Retail Pharmacies |
| Companies Covered | KARL STORZ SE & Co. KG, Olympus Corporation, Richard Wolf GmbH, Stryker, Hologic Inc., Medtronic, Boston Scientific Corporation, B. Braun Melsungen AG, CooperSurgical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hysteroscope Market Shifts & Advancements
Digital imaging architectures and disposable platform economics are simultaneously elevating visual performance standards and collapsing traditional equipment financing models across gynecological endoscopy.
4K resolution sensors with HDR processing are digitizing operative hysteroscopy by enabling submillimeter endometrial visualization previously requiring histopathological confirmation. Academic medical centers in Germany and Japan deploy these systems for complex adhesiolysis and septum resection procedures. The technology is digitizing surgical decision-making by compressing the diagnostic-to-therapeutic interval from separate visits to single-session interventions.
The EU Medical Device Regulation's Unique Device Identification mandate forces hysteroscope manufacturers to implement serialized traceability across reusable and single-use product lines. This requirement accelerates cloud-based fleet management platform adoption by hospitals seeking automated reprocessing cycle tracking. European university hospitals now prioritize suppliers with integrated compliance dashboards, shifting procurement evaluation criteria toward data infrastructure capabilities.
Service unbundling from capital sales is restructuring vendor-hospital relationships as facilities reject bundled maintenance contracts in favor of per-procedure disposable economics. Independent service organizations capture preventive maintenance revenue from aging rigid hysteroscope installed bases. This pattern concentrates in the United States, where ambulatory surgery center chains negotiate direct manufacturer relationships that bypass traditional distributor markups.
Global Hysteroscope Market Segmentation
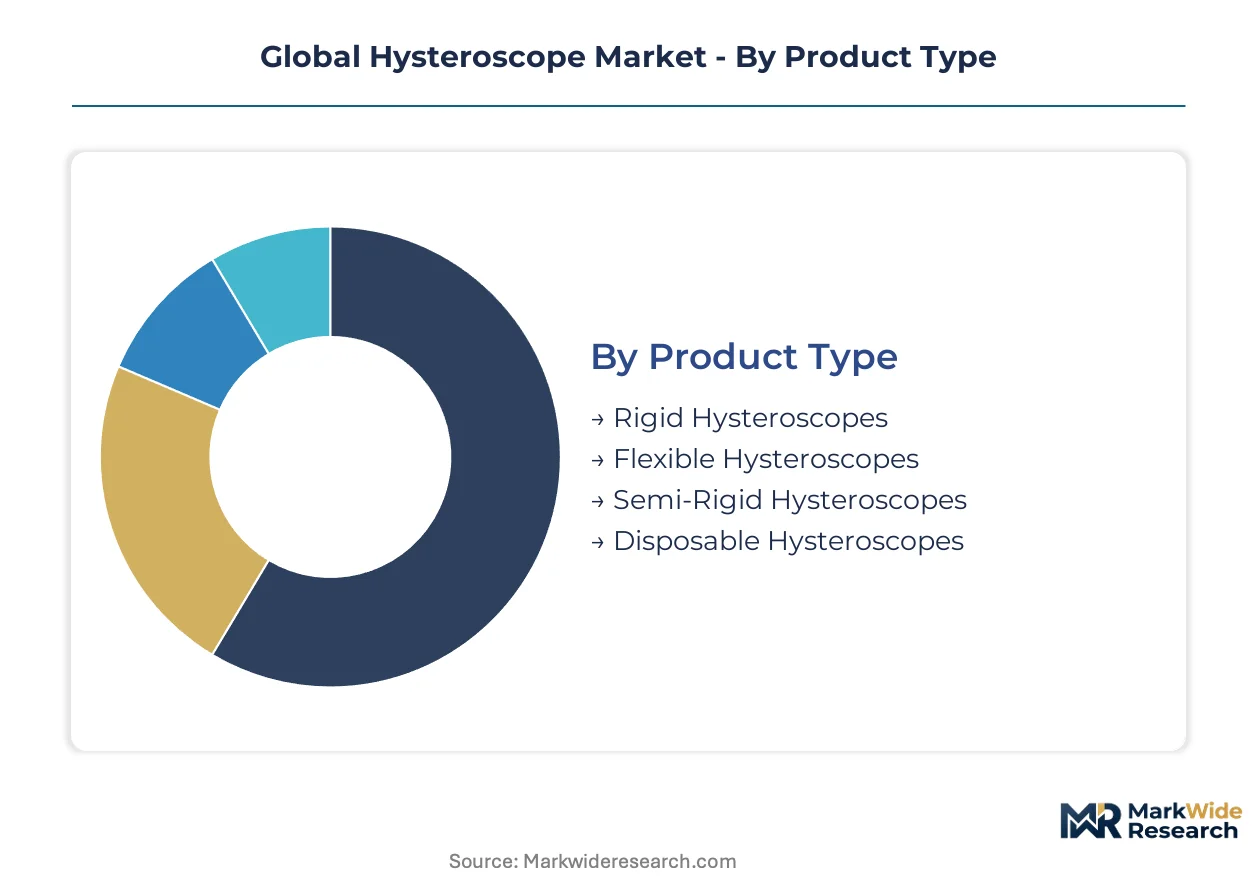
Hysteroscope procurement patterns diverge sharply across product architectures, clinical applications, and care delivery settings. Understanding these segment boundaries illuminates where capital equipment budgets concentrate versus where disposable economics are displacing traditional ownership models.
Product Type:
Mature optical technologies anchor hospital capital budgets while emerging disposable platforms reshape outpatient economics.
- Rigid Hysteroscopes:Rod-lens optical systems with 2.9 mm to 4.0 mm outer diameters deliver superior resolution and instrument channel capacity for operative procedures. German and Japanese university hospitals prioritize these systems for complex septum resection and adhesiolysis, though reprocessing liability and sterilization infrastructure costs constrain community hospital adoption.
- Disposable Hysteroscopes:Single-use sterile-packaged designs eliminate cross-contamination risk and reprocessing overhead. Fertility clinics in the United States and ambulatory surgical centers in Germany are converting diagnostic volumes to these platforms, compressing capital cycles and redistributing value capture toward consumable manufacturers.
- Flexible Hysteroscopes:Fiberoptic designs enable office-based diagnostic screening without anesthesia. Miniaturized variants target same-day procedures in United States outpatient clinics seeking to capture hospital-diverted volumes.
- Semi-Rigid Hysteroscopes:Hybrid architectures balance optical performance with navigational flexibility. These systems occupy a narrowing middle tier as facilities polarize toward premium rigid towers or disposable convenience.
Rigid hysteroscopes retain volume leadership; disposable hysteroscopes hold the steepest expansion curve.
Application:
Procedure reimbursement differentials concentrate investment toward therapeutic interventions while diagnostic screening sustains baseline utilization.
- Diagnostic Procedures:Visual assessment of endometrial pathology without concurrent intervention constitutes the volume foundation. Office-based diagnostic hysteroscopy in United States ambulatory settings is expanding as facilities deploy miniaturized flexible systems to capture same-day volumes.
- Operative Interventions:Concurrent visualization and therapeutic manipulation command premium per-procedure revenue and drive replacement cycles for electrosurgical-compatible sheath systems. Academic medical centers in Japan and Germany prioritize 4K-enabled rigid platforms for complex resections.
- Fibroid Removal:Hysteroscopically guided myomectomy preserves fertility while avoiding abdominal incision. Fertility clinics in the United States and Japan are expanding subspecialty capacity for this indication.
- Endometrial Ablation:Destruction of endometrial lining for abnormal uterine bleeding management. Hospital-based gynecology departments in Germany favor integrated resection-ablation systems under bundled service contracts.
- Adhesiolysis:Lysis of intrauterine adhesions restoring cavity architecture. Japanese university hospitals deploy precision optics for recurrent implantation failure protocols under METI-supported initiatives.
Diagnostic procedures anchor utilization volume; operative interventions concentrate revenue and equipment investment.
End User:
Site-of-service economics are fragmenting procurement authority between integrated health systems and independent outpatient operators.
- Ambulatory Surgical Centers:Same-day procedure specialists in the United States are outpacing hospital-based hysteroscopy volumes. These facilities negotiate direct manufacturer relationships that bypass traditional distributor markups and prioritize disposable platforms to eliminate reprocessing infrastructure.
- Fertility Clinics:Specialized reproductive medicine operators require diagnostic precision for implantation failure workups. Japanese fertility centers leverage government subsidies for precision medicine diagnostics, while United States clinics convert to single-use systems for liability mitigation.
- Gynecology Departments:Hospital-based specialists maintain capital-intensive rigid tower installations. German university hospitals anchor premium placements through integrated endoscopy system commitments with maintenance bundling.
- Specialty Clinics:Independent gynecology practices in urban United States markets balance patient throughput against capital constraints. Stryker's financing programs target this segment with lowered upfront acquisition thresholds.
Ambulatory surgical centers are gaining share fastest; gynecology departments retain installed base dominance.
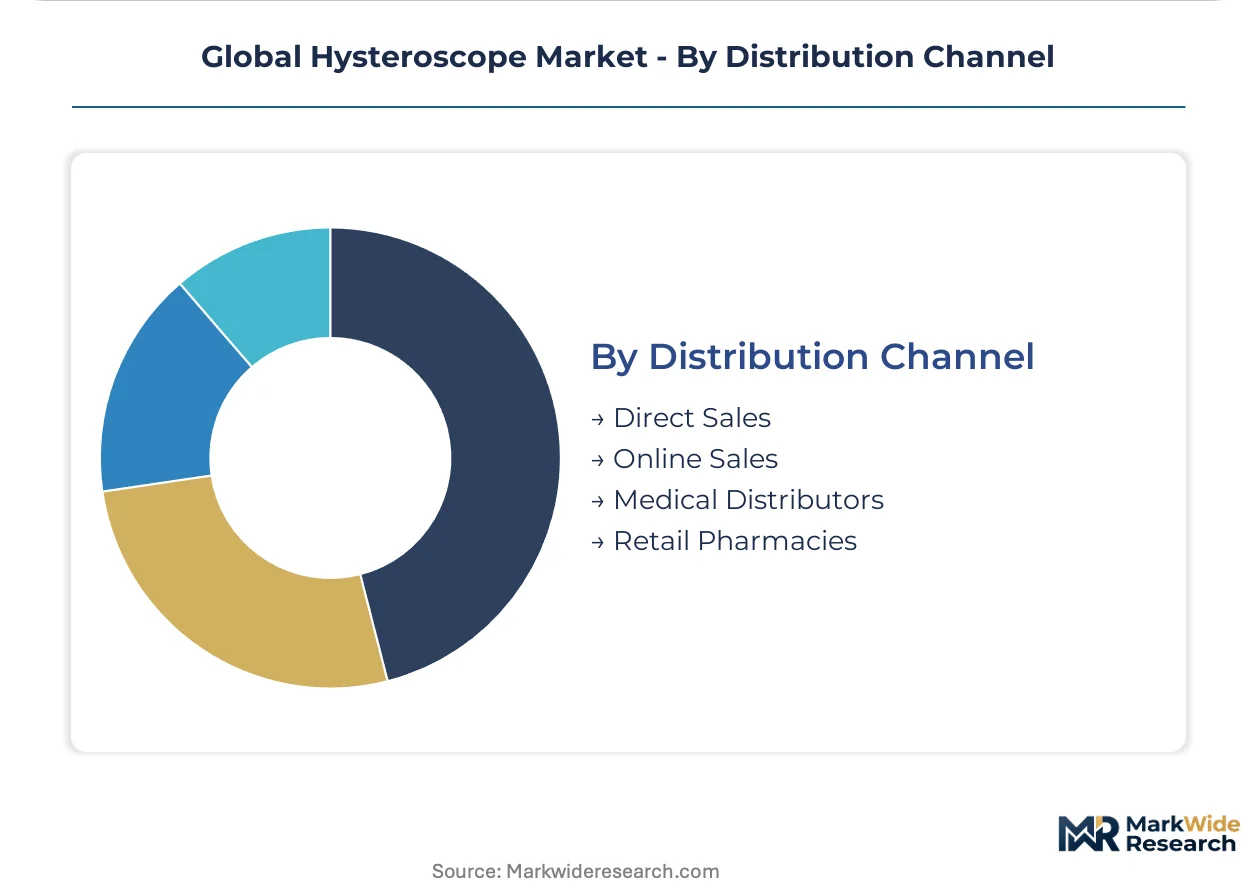
Distribution Channel:
Channel economics are restructuring as procurement centralization and disintermediation pressures collide.
- Direct Sales:Manufacturer-to-facility relationships concentrate in United States ambulatory surgery center chains and German university hospital networks. KARL STORZ and Olympus deploy field clinical specialists to anchor premium tower placements through direct engagement.
- Medical Distributors:Traditional intermediaries retain relevance for mid-sized United States gynecology practices and community hospitals requiring localized inventory and technical service. Regional distributors in Germany maintain relationships with municipal hospital procurement consortiums.
- Online Sales:E-commerce platforms capture consumable replenishment and replacement component orders. United States fertility clinics increasingly source disposable hysteroscopes through specialized medical supply marketplaces.
- Retail Pharmacies:Minimal hysteroscope penetration; limited to peripheral consumables in markets with pharmacy-delivered medical device regulatory frameworks.
Medical distributors retain volume leadership; direct sales channels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German university hospitals while United States ambulatory surgical centers compress margins through disposable procurement. Japanese precision medicine subsidies sustain premium equipment absorption. Indian district hospital modernization creates volume opportunity at economy tier.
United States
Ambulatory surgical centers now exceed hospital-based hysteroscopy volumes through same-day procedure capture. FDA 510(k) clearance streamlining accelerates single-use disposable commercialization for outpatient clinics. Fertility clinics in California and New York Metro convert rapidly to sterile-packaged designs for liability mitigation.
Germany
University hospitals in Bavaria and Baden-Württemberg anchor premium rigid tower placements through integrated endoscopy system commitments. EU MDR clinical evidence requirements extend recertification timelines for reusable variants, favoring established manufacturers with surveillance infrastructure. The Tübingen-Stuttgart medical technology cluster concentrates optical assembly engineering talent.
Japan
METI-supported precision medicine initiatives subsidize diagnostic hysteroscopy adoption for recurrent implantation failure protocols. PMDA regulatory frameworks align with global harmonization efforts, reducing duplication for multinational manufacturers. Tokyo and Osaka academic medical centers deploy 4K-enabled systems for complex adhesiolysis procedures.
India
Government hospital modernization programs under Ayushman Bharat create first-mover advantage for portable hysteroscope systems targeting district-level maternal health screening. CDSCO regulatory pathways for medical devices are streamlining import substitution incentives. The Maharashtra-Gujarat pharmaceutical manufacturing corridor extends into diagnostic equipment assembly.
China
NMPA regulatory harmonization with international standards accelerates market access for multinational endoscopy manufacturers. Domestic production incentives under the 14th Five-Year Plan support local optical component fabrication. The Yangtze River Delta medical device cluster concentrates contract manufacturing for hysteroscope OEMs restructuring supply chains.
Global Hysteroscope Market Competitive Landscape
Integrated system specialists and disposable platform innovators split the market between capital-intensive tower economics and per-procedure consumable models. The vendor base concentrates among German and Japanese precision optics houses with endoscopy heritage, plus diversified medical technology conglomerates with gynecology portfolios. Two archetypes dominate: optical engineering specialists leveraging rod-lens assembly expertise, and diversified strategists extending anesthesia and energy platform compatibility. Competitive moves center on M&A for imaging processor technology and direct sales force expansion into ambulatory surgery center chains.
Within the optical engineering tier, KARL STORZ SE & Co. KG and Olympus Corporation exemplify integrated system positioning through endoscopy tower anchoring. Stryker occupies a position bridging capital equipment financing with disposable portfolio extension. These three entities represent distinct strategic postures: German precision manufacturing heritage, Japanese imaging processor specialization, and United States-based diversified medical technology scale.
| Leading Market Players |
|---|
| KARL STORZ SE & Co. KG |
| Olympus Corporation |
| Richard Wolf GmbH |
| Stryker |
| Hologic Inc. |
| Medtronic |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| CooperSurgical Inc. |
| Others |
Supply & Pricing Matrix
German and Japanese precision optics suppliers control rod-lens assembly production for rigid hysteroscopes, concentrating margin capture upstream while disposable manufacturers downstream compete on per-procedure unit economics. This supply concentration forces OEMs to absorb optical component premiums or cede margin to contract manufacturers with captive lens sourcing.
Pricing Analysis
Configured-to-order rigid hysteroscope towers command substantial premiums over standard disposable platforms due to customization depth and integrated imaging processor bundling. Three-tier pricing structure across premium, standard, and economy levels separates university hospital capital commitments from ambulatory surgical center disposable procurement and fertility clinic mid-tier flexible systems. Price differentiation hinges on optical resolution grade and FDA 510(k) clearance tier for single-use variants. Pricing pressure stems from ambulatory surgical center chains negotiating direct manufacturer relationships that bypass distributor markups. Fertility clinics exhibit highest price sensitivity due to per-procedure margin compression, while German university hospitals absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Optical glass feedstock for rod-lens assemblies draws from specialized German and Japanese precision manufacturers, with secondary sourcing emerging from Chinese component fabricators under domestic production incentives. Raw material dependencies center on high-index optical glass, sapphire lens elements, and medical-grade polymer sheathing. Supply chain risk concentrates in single-source vulnerability for 4K sensor modules and specialized fiberoptic bundles. Distribution runs through direct sales forces for premium tower placements, medical distributors for mid-sized practices, and specialized e-commerce platforms for disposable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of precision optical engineering talent and sterilization-validated manufacturing capacity constrains expansion for new entrants while rewarding incumbents with captive assembly expertise. This capability gap intensifies as EU MDR surveillance requirements and FDA clearance pathways demand simultaneous regulatory sophistication.
For Market Incumbents: Entrench position through backward integration into optical component production, securing captive supply of rod-lens assemblies against German and Japanese supplier concentration. Deepen hospital system partnerships with cloud-based fleet management platforms that automate reprocessing cycle tracking, addressing EU MDR Unique Device Identification mandates while creating switching cost barriers against disposable competitors. For New Entrants and Emerging Players: Establish a beachhead in India's district-level maternal health screening infrastructure under Ayushman Bharat modernization programs, where portable hysteroscope demand outpaces established supply. Target fertility clinics in the United States with sterile-packaged disposable designs emphasizing liability mitigation and elimination of reprocessing infrastructure. Pursue go-to-market alignment with specialized medical supply marketplaces capturing consumable replenishment orders from independent clinics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use hysteroscope manufacturing as automated assembly lines displace hand-finished optical alignment, compressing break-even thresholds for emerging players. Long-term viability favors acquisition targets with dual capabilities in precision optics and disposable platform engineering, positioned to serve both hospital capital cycles and ambulatory consumable economics. Monitor FDA 510(k) clearance velocity for single-use predicates as the inflection signal for disposable platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Abbreviated predicate-based submissions accelerate disposable hysteroscope commercialization for outpatient clinics. |
| Hospital System Partnership | Integrated endoscopy tower commitments with maintenance bundling anchor premium placements in German university hospitals. |
| Backward Integration | Captive rod-lens assembly production mitigates single-source dependency on German and Japanese optical suppliers. |
| Software Companion Development | Machine learning algorithms paired with 4K cameras enable real-time polyp detection differentiating premium tiers. |
| Reimbursement Strategy | Parity between office-based and facility-based hysteroscopy codes dictates site-of-service migration and procurement specifications. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation, and hospital procurement contract filings preceded structured interviews with gynecology department heads, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers. Secondary validation incorporated SEC filings from listed medical device manufacturers, CMS Medicare reimbursement data, and Japanese METI precision medicine initiative disclosures. Bottom-up demand modeling from procedure volumes and equipment replacement cycles was triangulated against top-down market sizing from manufacturer revenue disclosures.
Assumptions held fixed include regulatory pathway timelines for predicate-based submissions and reimbursement code stability across site-of-service settings, while variables included ambulatory surgical center expansion rates and single-use adoption curves. Segmentation dimensions spanned product architecture, application type, end-user setting, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical equipment replacement cycles and procedural volume trajectories. Forecast inputs incorporated optical component supply constraints and EU MDR recertification timeline extensions.
Sensitivities concentrate around FDA clearance velocity for novel disposable designs, EU MDR surveillance study cost burdens, and reimbursement parity shifts between office-based and facility-based settings. Forecasts reflect assumptions regarding sterilization infrastructure investment patterns and liability-driven substitution toward single-use platforms. Cross-checking against hospital capital expenditure surveys and ambulatory surgery center chain procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Medical Devices Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Global Nebulizers Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Smart Lenses Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Indian Laparoscopy Devices Market