
 Endometrial Ablation Devices Market | 2026-2036
Endometrial Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Endometrial Ablation Devices Market Intelligence
The rise of device leasing and pay-per-procedure models for capital equipment is fragmenting the competitive landscape for smaller clinics. This allows specialized providers to compete without large upfront capital investment. Hologic, Inc. leverages its established brand and extensive service network to offer such flexible acquisition options. Meanwhile, Boston Scientific Corporation differentiates through its focus on clinical data and training programs for new users.
Endometrial ablation devices are medical instruments designed to remove or destroy the endometrium, the lining of the uterus. These devices operate using various energy modalities, such as radiofrequency energy delivered at a controlled temperature and duration, to achieve therapeutic effect for abnormal uterine bleeding. Radiofrequency ablation represents the dominant product type due to its high efficacy and short procedure times. Ambulatory surgery centers are the fastest-growing end-user segment, driven by reimbursement shifts favoring outpatient procedures for menstrual disorders.
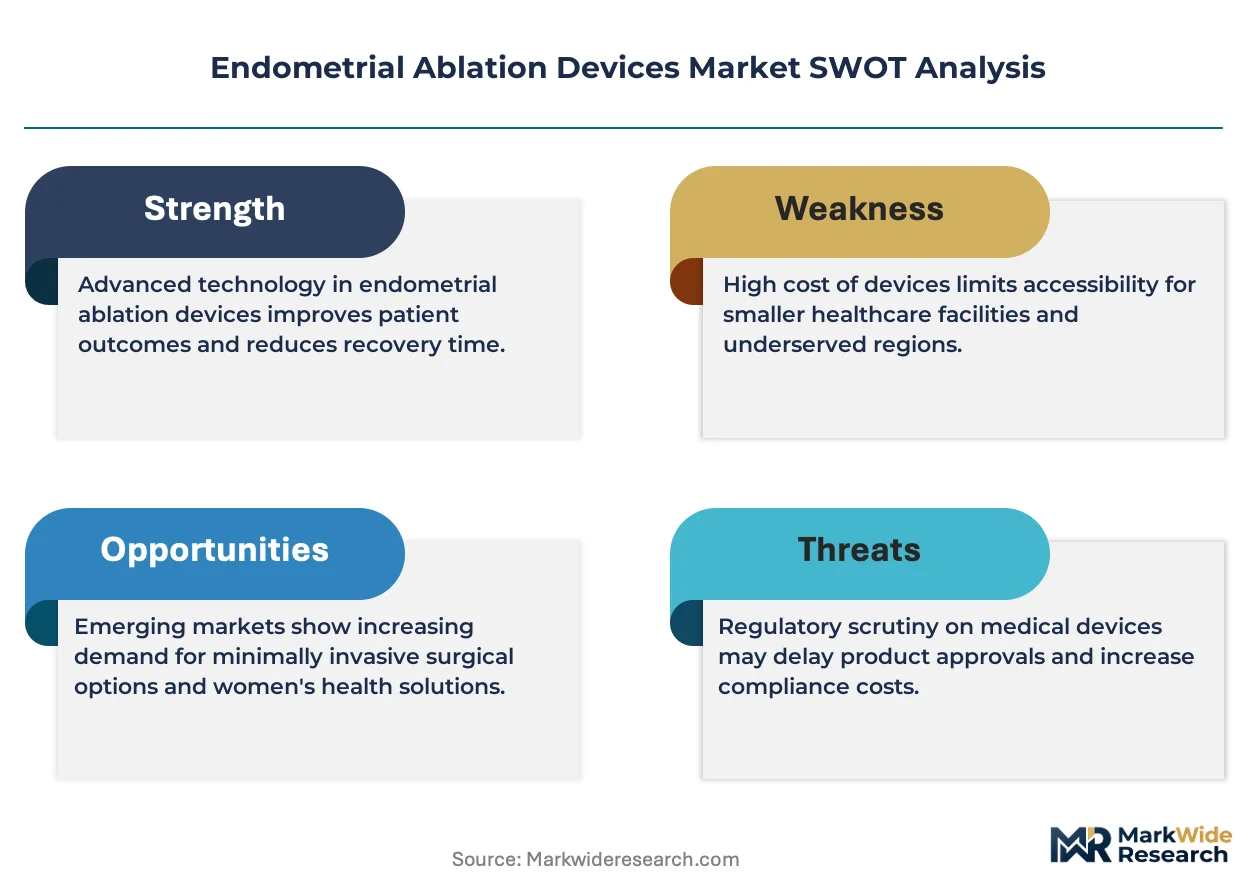
Device approval pathways are stringent, with manufacturers needing clearance from bodies like the US FDA and conformity assessments for CE marking in Europe. These regulations mandate extensive clinical trials and post-market surveillance to ensure patient safety and device efficacy. Future market access will depend on demonstrating superior long-term patient outcomes and cost-effectiveness compared to alternative treatments like hysterectomy.
Market Dynamics
The decentralization of care from inpatient hospital settings to outpatient ambulatory surgery centers is the central force shaping the endometrial ablation devices market. This transition is enabled by next-generation technologies that shorten procedure times and improve safety profiles, aligning with reimbursement models favoring cost-effective, minimally invasive treatments.
Growth Catalysts
- Next-Generation Ablation Technology:The development of second- and third-generation devices, particularly radiofrequency systems with automated temperature and time controls, offers higher efficacy and shorter recovery periods, encouraging adoption by both physicians and patients.
- Favorable Reimbursement Policies:In healthcare systems like the United States, shifts in reimbursement codes and payment structures increasingly favor performing procedures like endometrial ablation in lower-cost ambulatory surgery centers over traditional hospitals.
- Minimally Invasive Procedure Preference:A strong patient and provider preference for minimally invasive treatments for abnormal uterine bleeding in developed countries, including Germany and the United Kingdom, supports procedural volume growth over more invasive options like hysterectomy.
Market Restraints
- Alternative Treatments:The availability of long-term hormonal therapies and the continued use of hysterectomy as a definitive surgical solution for abnormal uterine bleeding present significant substitution threats that cap the market's potential patient pool.
- Stringent Regulatory Hurdles:Obtaining market access requires navigating complex and lengthy approval pathways, such as the US FDA's Premarket Approval (PMA) process and conformity assessments for CE marking under the EU's MDR, which act as high barriers for new entrants.
- Desire for Future Fertility:Endometrial ablation is a sterilization procedure, making it unsuitable for patients who wish to preserve their fertility. This clinical contraindication inherently limits the eligible patient population for the treatment.
Strategic Opportunities
- Expansion in Emerging Economies:Untapped markets in Latin America, such as Brazil, and parts of Asia-Pacific offer significant growth potential as healthcare infrastructure improves and awareness of minimally invasive gynecological procedures increases among middle-class populations.
- Integration of Smart Technologies:Incorporating real-time feedback mechanisms, artificial intelligence for treatment planning, or enhanced visualization tools into ablation devices can create new value propositions centered on improved precision and patient outcomes.
- Flexible Acquisition Models:The expansion of pay-per-procedure and leasing models for capital equipment lowers the financial barrier for smaller clinics and ambulatory surgery centers, opening a new customer segment beyond large hospital networks.
Industry Challenges
- Specialized Physician Training:The effective and safe use of advanced radiofrequency and microwave ablation devices requires specific training and expertise, creating a skills gap that can slow the rate of technology adoption among gynecologists. *Post-Market Surveillance Burden: Complying with rigorous post-market surveillance and clinical follow-up studies, as mandated by regulators like the FDA and under the EU MDR, demands significant and ongoing resource investment from device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endometrial Ablation Devices Market |
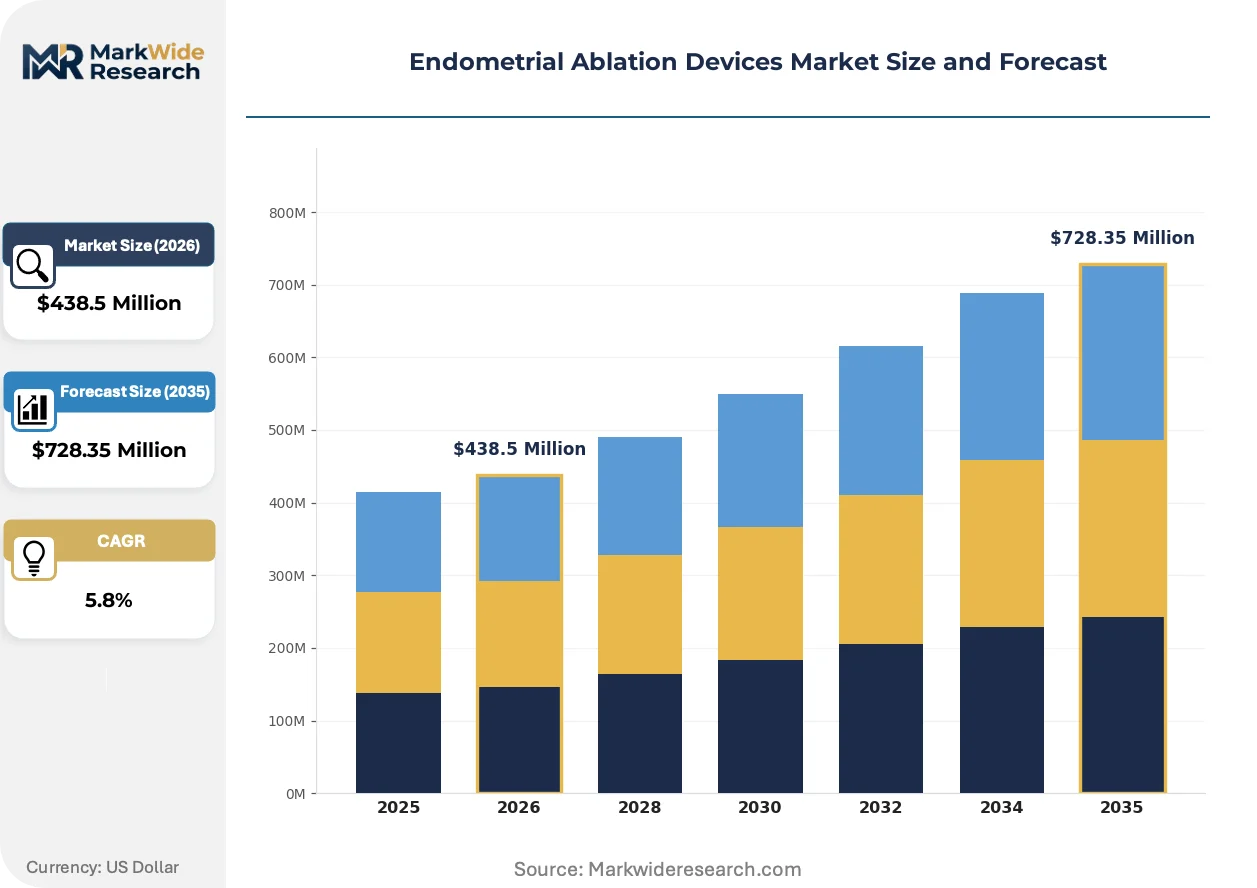
| Market Size in 2026 | $438.5 Million |
| Market Size in 2035 | $728.35 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Microwave Ablation, Cryoablation, Hydraulic Ablation Application: Menstrual Disorders, Uterine Hemorrhage, Fibroids, Endometriosis End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Laboratories Delivery Method: Hysteroscopy, Laparoscopy, Transcervical, Vaginal |
| Companies Covered | Hologic, Inc., Boston Scientific Corporation, Olympus Corporation, Medtronic plc, Minerva Surgical, Inc., CooperSurgical, Inc., Johnson & Johnson, The Cooper Companies, Inc., Idoman Teoranta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endometrial Ablation Devices Market Strategic Shifts & Innovations
Technological advancements are simultaneously improving clinical efficiency and expanding economic access for endometrial ablation procedures. The market's evolution is defined by a push toward devices that support the migration of care to outpatient settings, driven by both regulatory pressures on evidence generation and new procurement behaviors among providers.
Next-generation radiofrequency ablation technology provides automated, temperature-controlled energy delivery to the uterine lining. Specialized gynecology clinics and ambulatory surgery centers are the primary adopters of these advanced systems due to their efficiency. This technology is collapsing the procedural time and recovery period, making office-based treatments a viable alternative to more intensive hospital-based surgeries.
The European Union’s Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and lifecycle traceability on all medical devices. This regulation forces manufacturers to generate more robust data on long-term safety and performance. The high-risk device segment, which includes endometrial ablation systems, is most affected, compelling companies to invest heavily in post-market clinical follow-up to maintain CE marking and market access in Europe.
A distinct shift away from large, one-time capital equipment purchases toward flexible, opex-based acquisition models is evident. This trend favors device leasing and pay-per-procedure contracts, disrupting traditional sales channels that targeted large hospital procurement departments. This demand-side change is most visible in the United States, where the proliferation of independent ambulatory surgery centers creates a customer base that values financial flexibility.
Endometrial Ablation Devices Market Segmentation
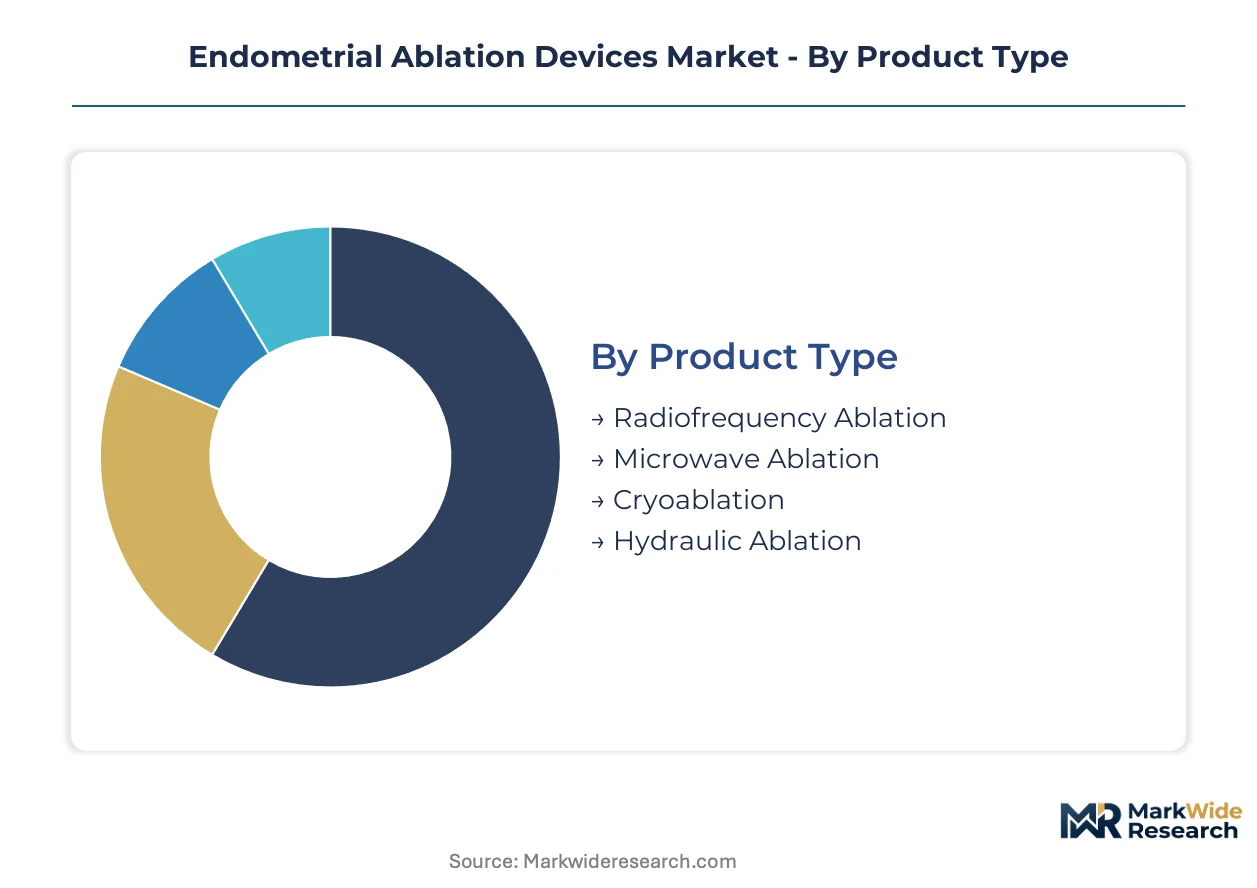
The endometrial ablation devices market segments across product types, application areas, end-user facilities, and delivery methods. Understanding these distinctions clarifies the current landscape and future growth vectors for manufacturers. This granular analysis highlights where technological innovation and procedural shifts are concentrating.
Product Type:
Product type differentiation distinguishes the various energy modalities employed for endometrial ablation procedures.
- Radiofrequency Ablation:This technology uses controlled radiofrequency energy to ablate the uterine lining, offering high efficacy for abnormal uterine bleeding. Demand concentrates in both hospital and ambulatory settings due to its short procedure times and established safety profile.
- Microwave Ablation:Microwave ablation devices deliver electromagnetic energy to destroy endometrial tissue, providing another efficient option for uterine lining removal. Adoption is expanding in specialized gynecology clinics seeking rapid and effective treatment solutions.
- Cryoablation:Cryoablation employs extreme cold to destroy endometrial tissue, offering a distinct mechanism of action for specific patient profiles.
- Hydraulic Ablation:Hydraulic ablation uses heated saline to uniformly ablate the endometrium, providing a non-energy-based approach.
Radiofrequency Ablation commands the established base. The steepest expansion runs through Microwave Ablation.
Application:
The primary clinical conditions treated by endometrial ablation devices define the application segments.
- Menstrual Disorders:Endometrial ablation is a primary treatment for abnormal uterine bleeding, offering a less invasive alternative to hysterectomy. This application drives the largest volume of procedures in developed healthcare systems like Germany.
- Uterine Hemorrhage:Devices are deployed to manage severe uterine bleeding, often in acute settings, providing a critical intervention for patient stabilization. Hospitals represent a key end-user segment for this life-saving application.
- Fibroids:Ablation devices can address symptoms related to uterine fibroids, particularly heavy menstrual bleeding, for patients seeking fertility-sparing options.
- Endometriosis:While not a primary treatment for endometriosis, ablation can alleviate associated abnormal bleeding symptoms in some cases.
Menstrual Disorders account for the largest procedural volume. Uterine Hemorrhage treatment is gaining share quickly.
End User:
Variations in healthcare infrastructure and reimbursement policies influence the end-user segments for these devices.
- Ambulatory Surgery Centers:These facilities are experiencing rapid growth as preferred sites for endometrial ablation due to cost-effectiveness and favorable reimbursement shifts. The transition to outpatient settings is a central force shaping this market.
- Hospitals:Hospitals remain a significant end-user segment, particularly for complex cases or where inpatient care is required. They continue to represent a foundational demand base for capital equipment and procedures.
- Specialty Clinics:Gynecology-focused specialty clinics increasingly adopt ablation devices, providing focused care in more accessible environments.
- Research Laboratories:A smaller segment, research laboratories utilize these devices for studying endometrial tissue responses and developing new treatment protocols.
Hospitals maintain a substantial installed base. Ambulatory Surgery Centers are expanding most quickly.
Delivery Method:
The anatomical access and procedural approach dictate the specific delivery method for endometrial ablation.
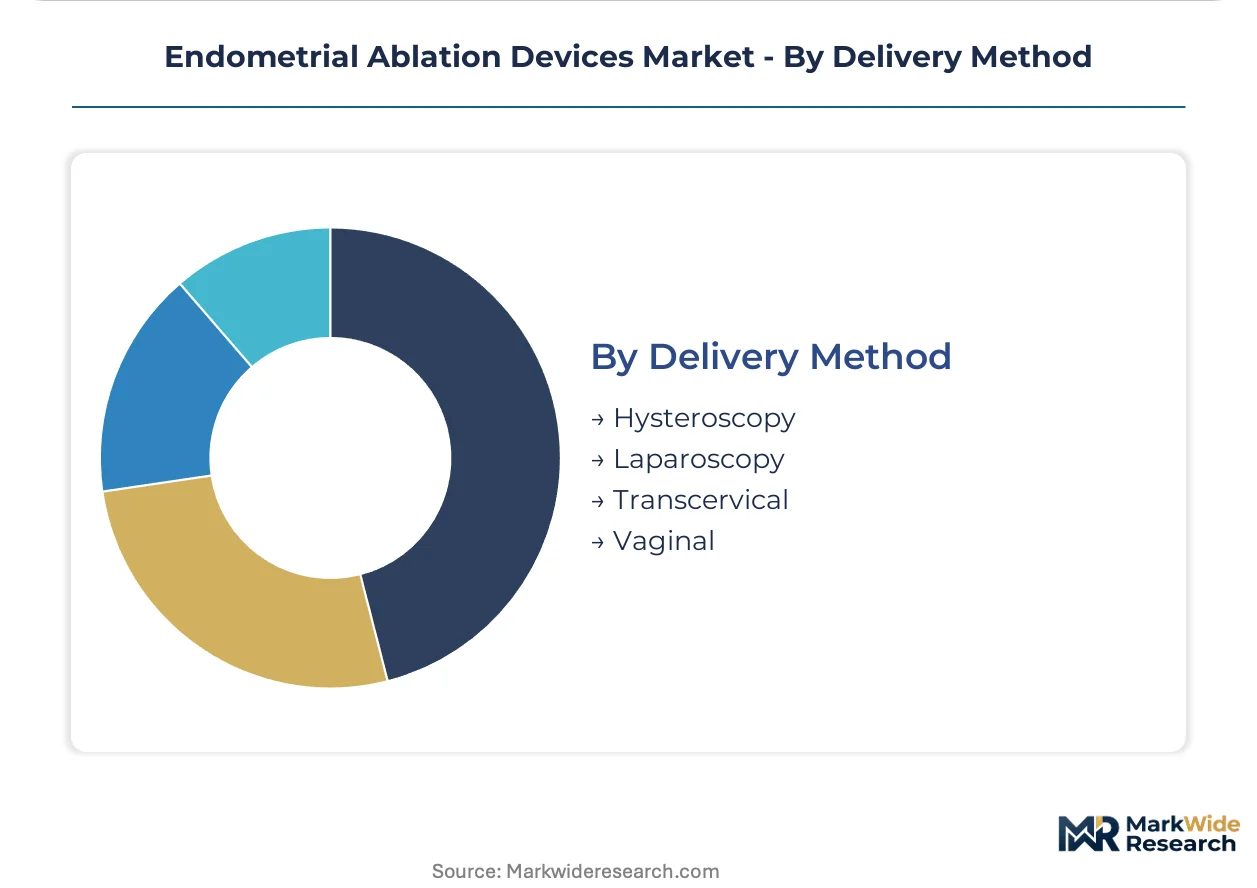
- Hysteroscopy:Hysteroscopy involves direct visualization of the uterine cavity to guide device placement and ensure accurate ablation. This method offers precision and is widely used across various clinical settings.
- Transcervical:Transcervical delivery methods allow for device insertion through the cervix without abdominal incisions, supporting minimally invasive outpatient procedures. This approach aligns with the preference for reduced recovery times.
- Laparoscopy:Laparoscopy, while more invasive, might be used in conjunction with ablation for patients requiring other concurrent pelvic procedures.
- Vaginal:Vaginal delivery methods offer a less invasive route for certain ablation systems, contributing to shorter recovery and reduced patient discomfort.
Hysteroscopy-guided procedures constitute a significant portion of current practice. Transcervical approaches are seeing accelerated adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global endometrial ablation devices market exhibits varied regional demand and supply dynamics. Developed economies often drive innovation and adoption, while emerging markets present future expansion opportunities. Trade flows of advanced medical devices frequently balance local manufacturing capabilities with import reliance.
United States
Demand for endometrial ablation devices in the United States is spurred by favorable reimbursement policies and a strong preference for outpatient procedures. Shifts in payment structures increasingly support ambulatory surgery centers for menstrual disorder treatments. The Boston metropolitan area remains a hub for medical device innovation, fostering new product development and clinical trials.
Germany
Germany demonstrates high demand for minimally invasive treatments, including endometrial ablation, due to its advanced healthcare infrastructure and patient preferences. Strict CE marking requirements under the EU MDR ensure device safety and efficacy across the European market. Munich and Berlin host significant medical technology clusters, contributing to research and specialized gynecological care.
Brazil
Healthcare infrastructure improvements and increasing awareness among middle-class populations drive procedural volume growth in Brazil. ANVISA regulations govern medical device approval, ensuring product quality and patient safety within the country. São Paulo serves as a major medical hub, concentrating specialized clinics and device distribution networks for Latin America.
Japan
A rapidly aging population and a focus on reducing hospital stays contribute to the demand for efficient, less invasive procedures like endometrial ablation. PMDA regulations ensure stringent oversight of medical device market entry and post-market surveillance. Tokyo’s medical technology sector actively integrates smart technologies into new device designs for precision outcomes.
China
Expanding healthcare access and a rising prevalence of abnormal uterine bleeding conditions fuel the market for endometrial ablation devices. NMPA clearance is essential for manufacturers seeking to distribute products within China's vast domestic market. The Yangtze River Delta region is a key manufacturing base for medical equipment, including components for ablation systems.
Endometrial Ablation Devices Market Key Industry Players
On the supply side, the industry is moderately consolidated, with a few large multinational medical device manufacturers holding significant market share alongside specialized gynecology device companies. Strategic archetypes include diversified conglomerates leveraging extensive product portfolios, niche innovators focusing on next-generation ablation technologies, and regional players addressing specific local market needs. Portfolio diversification through technology acquisition and strategic partnerships with rapidly expanding ambulatory surgery centers are dominant competitive moves.
Specialists in women's health and minimally invasive surgery solutions exemplify the market's competitive dynamics. Hologic, Inc. occupies a position as a well-established brand, leveraging its extensive service network and flexible acquisition models to maintain market presence among diverse healthcare providers. Boston Scientific Corporation, known for its broad medical device offerings, differentiates through robust clinical data generation and comprehensive training programs for new users, reinforcing its commitment to physician education. Medtronic plc, a global medical technology leader, also sits within this landscape, contributing to the development of advanced surgical instruments and expanding their reach into outpatient settings.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Boston Scientific Corporation |
| Olympus Corporation |
| Medtronic plc |
| Minerva Surgical, Inc. |
| CooperSurgical, Inc. |
| Johnson & Johnson |
| The Cooper Companies, Inc. |
| Idoman Teoranta |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's concentration in medical equipment component manufacturing directly influences margin pools for endometrial ablation device manufacturers. This regional specialization creates pricing leverage for upstream suppliers.
Pricing Analysis
Industrial OEM buyers anchor hybrid acquisition models in the endometrial ablation devices market. Pricing stratifies across premium, standard, and economy tiers based on clinical data packages, after-sales service, and brand reputation. Cost compression in ambulatory settings is intensifying due to reimbursement shifts favoring outpatient care. Ambulatory Surgery Centers exhibit higher price sensitivity compared to large hospital networks.
Supply Chain Analysis
Specialized contract manufacturers in China and Germany hold significant capacity for critical endometrial ablation device components. The supply chain draws from highly specialized inputs like radiofrequency generators and precision-machined device housings. Regulatory restrictions, particularly under the EU MDR and US FDA, present a structural risk by mandating extensive post-market surveillance. Distribution runs through direct sales forces and established service networks targeting hospitals and Ambulatory Surgery Centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endometrial ablation devices market presents a defensive-moat story for established players. Regulatory entrenchment, driven by stringent approval pathways like the US FDA and EU MDR, creates a significant barrier to entry.
For Market Incumbents: Build a clinical evidence moat by continuously generating robust long-term patient outcome data for existing and next-generation devices. Reinforce channel control through flexible acquisition models and comprehensive training programs for new users. This counters the threat from alternative treatments and specialized niche innovators. Investment in post-market surveillance ensures ongoing regulatory compliance.
For New Entrants and Emerging Players: Pursue strategic partnerships with rapidly expanding Ambulatory Surgery Centers to gain market access in cost-sensitive outpatient settings. Target untapped markets in Latin America, particularly Brazil, where healthcare infrastructure improvements are increasing awareness. Develop devices integrating smart technologies for enhanced precision and patient outcomes, differentiating from established product lines. Emphasize simplified training and rapid procedure times as a go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized gynecology device companies focusing on niche ablation technologies or regional market penetration. The market's long-term viability hinges on the continued decentralization of care to outpatient settings and ongoing technological advancements. Target acquisition archetypes include innovators with strong clinical data for next-generation radiofrequency or microwave systems. Watch for shifts in reimbursement policies as a key inflection indicator for procedural volume growth.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Secures market access and long-term sales in the highly regulated European Union. |
| Ambulatory Surgery Center Partnerships | Expands device adoption by aligning with cost-effective outpatient care trends. |
| Next-Generation RF Technology R&D | Drives product differentiation and improved patient outcomes in competitive segments. |
| Clinical Training Program Expansion | Accelerates technology adoption by addressing the specialized physician skills gap. |
| Flexible Acquisition Model Rollout | Lowers capital barriers for smaller clinics, expanding the customer base beyond hospitals. |
Research Approach
Initial hypotheses were tested against primary input from gynecologists, hospital procurement managers, and ambulatory surgery center administrators and refined through iterative discussions. This primary research was triangulated with extensive secondary data from US FDA filings, EU MDR conformity assessments, and medical device industry publications. A rigorous bottom-up and top-down approach ensured comprehensive market sizing and validation.
Demand-supply balance underpins the analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type, application, end-user facility, delivery method, and regional healthcare expenditure. Compound Annual Growth Rates were derived from historical data, identified growth catalysts, and expert consensus. Key industry-specific forecast inputs included procedure volumes by outpatient setting and new device approval timelines.
Macroeconomic conditions sit as an overlay; deviation in healthcare spending or regulatory policy would shift the trajectory. Forecasts reflect current assumptions regarding technological adoption and competitive intensity. Quarterly review of reimbursement policy updates and clinical trial outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Global Bone Cement Market
Medical Devices
Transport Chairs Market
Medical Devices
Endodontic Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Ultrasound Probe Market