
 Microneedle Flu Vaccine Market | 2026-2036
Microneedle Flu Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Microneedle Flu Vaccine Market Foresight
The capital-intensity divergence between manufacturing-scale incumbents and specialized technology developers is redrawing competitive boundaries in microneedle flu vaccines. Sanofi S.A. leverages its established influenza antigen production infrastructure to anchor downstream delivery innovation. Becton, Dickinson and Company sustains dominance in precision injection systems while navigating microneedle format transitions. Vaxxas differentiates through its high-density microarray patch platform, occupying a distinct position in thermostable vaccine delivery.
Microneedle flu vaccines employ arrays of microscopic projections, typically 25–2000 micrometers in length, to breach the stratum corneum and deposit antigen into the epidermis or upper dermis without reaching pain-signaling nerve fibers, thereby enabling self-administration and cold-chain reduction. Dissolving microneedles represent the fastest-expanding product category as polymer matrices eliminate sharps waste and enable unit-dose stability. Intradermal delivery mode captures concentrated margin pools due to its demonstrated dose-sparing efficacy with influenza antigens, while transdermal formats compete for pharmacy and retail channels where patient compliance drives repeat purchase behavior.
The FDA's Center for Biologics Evaluation and Research evaluates microneedle flu vaccines under the biologics license application pathway, with breakthrough therapy designations accelerating review for pandemic preparedness candidates. The EMA's Committee for Medicinal Products for Human Use applies the EU's Vaccines Antigen Master File framework to streamline multi-country authorization for patch-based formats. Stakeholders must monitor how WHO prequalification criteria evolve for thermostable microneedle presentations, as this status determines access to Gavi and UNICEF procurement channels for low-resource settings.
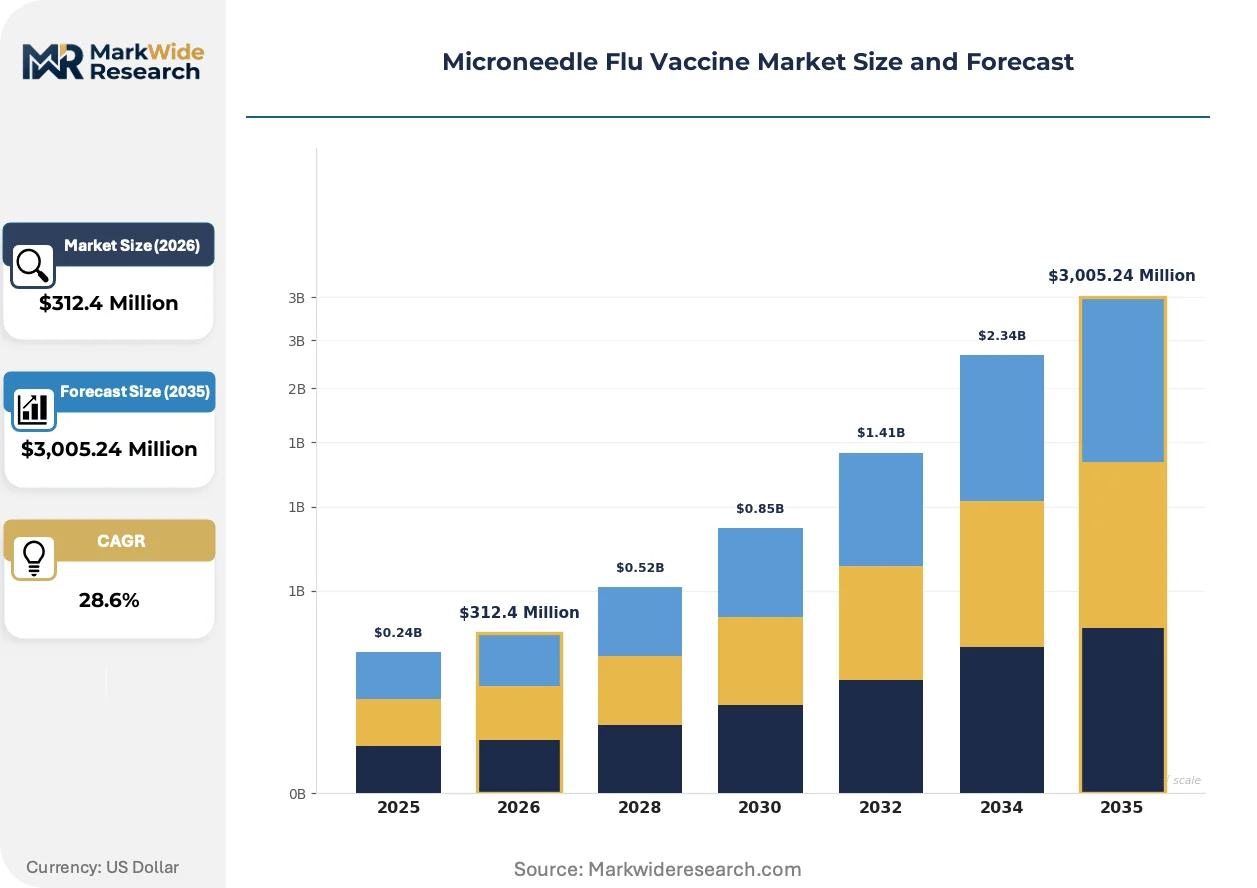
Market Dynamics
The microneedle flu vaccine sector pivots on cold-chain elimination economics, where polymer stabilization and room-temperature distribution infrastructure compress cost structures and expand addressable populations beyond traditional refrigerated supply networks.
Growth Catalysts
- Pandemic Preparedness Stockpiling:National biodefense agencies in the United States maintain strategic reserves of dissolving microneedle formats for rapid deployment during influenza pandemics, creating sustained procurement commitments independent of seasonal demand cycles.
- WHO Prequalification Pathway:The World Health Organization's evolving standards for thermostable vaccine presentations enable developing-country access through Gavi and UNICEF procurement channels, unlocking volume commitments from low-resource health systems.
- Polymer Matrix Advances:Biodegradable carbohydrate and synthetic polymer formulations now achieve 24-month stability at 40°C, eliminating sharps disposal requirements and enabling pharmacy retail distribution without medical supervision.
Market Restraints
- Precision Manufacturing Concentration:Micro-molding and laser-dicing equipment for microneedle arrays concentrates among German and Japanese capital goods suppliers, creating equipment lead-time bottlenecks that constrain capacity scaling.
- Antigen Compatibility Constraints:Not all influenza strains maintain immunogenicity through the drying and reconstitution processes required for dissolving matrix integration, limiting product portfolio breadth relative to liquid formulations.
- Reimbursement Coding Fragmentation:The Centers for Medicare & Medicaid Services has not established distinct procedural codes for microneedle administration, forcing providers to bill under legacy intradermal injection categories that compress reimbursement rates.
Strategic Opportunities
- Retail Pharmacy Self-Administration:CVS Health and Walgreens pilot programs for consumer-applied microneedle patches during fall vaccination seasons bypass clinical infrastructure constraints and capture margin from convenience premiums.
- Combination Respiratory Vaccines:Microneedle platforms enable co-formulation of influenza and COVID-19 antigens in single-patch presentations, addressing patient preference for simplified annual immunization schedules.
- EMA Adaptive Pathway Expansion:The European Medicines Agency's rolling review mechanisms for novel delivery platforms compress development timelines for patch-based candidates targeting seasonal strain updates.
Industry Challenges
- Microfabrication Talent Scarcity:The intersection of pharmaceutical formulation science and semiconductor-derived manufacturing processes requires hybrid skill sets that remain concentrated in Boston-Cambridge and Basel biotech clusters.
- Batch Release Testing Complexity:Each microneedle lot requires mechanical integrity testing, antigen potency verification, and sterility confirmation, extending quality control timelines relative to conventional injectable vaccines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microneedle Flu Vaccine Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $3,005.24 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Microneedles, Hollow Microneedles, Dissolving Microneedles, Coated Microneedles Delivery Mode: Transdermal, Intradermal, Subcutaneous, Intramuscular End User: Healthcare Providers, Pharmacies, Hospitals, Research Institutions Application: Immunization, Disease Prevention, Clinical Trials, Patient Compliance |
| Companies Covered | Sanofi S.A., Becton, Dickinson and Company, Debiotech S.A., NanoPass Technologies, FluGen, Inc., Vaxess Technologies, Micron Biomedical, 3M Company, Vaxxas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microneedle Flu Vaccine Market Shifts & Advancements
Active materials science and regulatory science advances are converging to reposition microneedle delivery from experimental platform to standard-of-care alternative, with manufacturing scale and clinical evidence accumulation now outpacing earlier-generation transdermal technologies.
Silicon and metal microneedle arrays are fragmenting into application-specific formats as coating technologies enable controlled-release kinetics matched to influenza antigen presentation requirements. Vaccine developers at academic medical centers in Maryland and Queensland are adopting dissolving polymer variants for phase II trials, displacing earlier hollow-needle designs that required complex filling processes. This fragmentation is compressing equipment amortization timelines as manufacturers retool for shorter production runs across multiple patch configurations.
The FDA's breakthrough therapy designation pathway for pandemic influenza candidates accelerates review timelines for microneedle presentations demonstrating dose-sparing efficacy. This regulatory flexibility compresses commercialization schedules for developers with established antigen partnerships. Pediatric and geriatric segments respond most aggressively, as needle-free administration addresses compliance barriers in these historically under-immunized populations.
Pharmacy chains now capture vaccination episodes previously concentrated in physician offices and occupational health clinics, with self-administered patch formats enabling this channel migration. Retail buyers negotiate direct supply agreements with platform developers, displacing traditional distributor intermediaries and capturing margin from convenience positioning. This behavioral shift concentrates most visibly in United States suburban markets where pharmacy density and insurance coverage for preventive services overlap.
Microneedle Flu Vaccine Market Segmentation
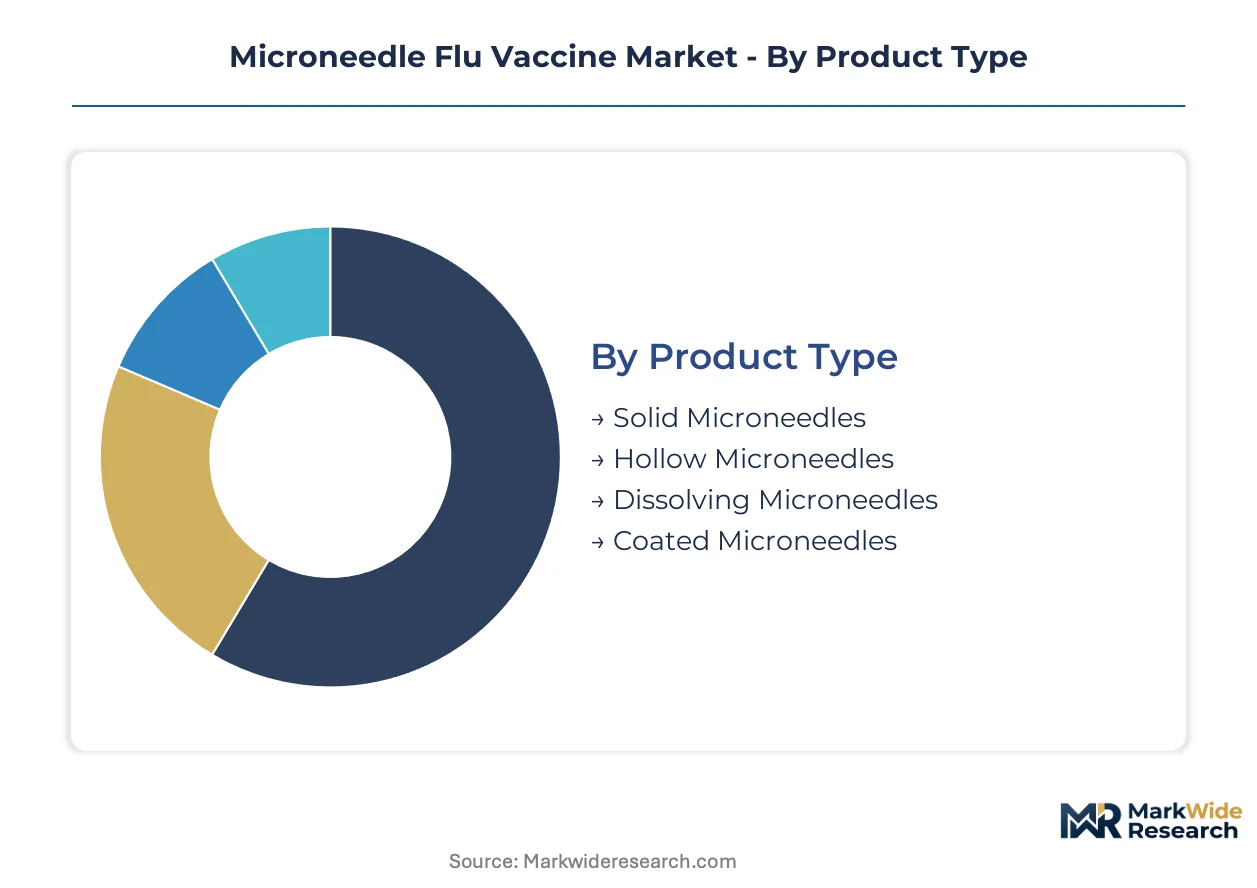
Microneedle flu vaccine segmentation reveals how formulation chemistry, anatomical targeting, and procurement channel economics create distinct margin pools. Each dimension carries implications for manufacturing scale, regulatory pathway selection, and distribution infrastructure requirements.
Product Type:
Geographic demand concentration varies sharply across microneedle formats, with polymer-based designs scaling through export-oriented production hubs while coated metal arrays serve domestic specialty markets.
- Solid Microneedles:Silicon or metal arrays penetrate the stratum corneum mechanically before external antigen application. Demand concentrates in German and Japanese research hospital networks where precision dermatology applications justify premium procurement.
- Hollow Microneedles:Internal lumens enable controlled liquid antigen infusion through microscale channels. Export-led manufacturing in Massachusetts and Basel supplies clinical trial sponsors requiring dose-flexibility for pandemic strain adaptation.
- Dissolving Microneedles:Biodegradable carbohydrate matrices eliminate retrieval requirements and enable room-temperature stability. Domestic demand dominates in US pharmacy retail pilots where self-administration drives compliance.
- Coated Microneedles:Surface-deposited antigen layers release upon skin insertion. Australian and UK biodefense agencies procure for stockpiling programs requiring extended shelf life without cold-chain dependency.
Dissolving microneedles hold the largest share; momentum sits with hollow formats for combination respiratory vaccine development.
Delivery Mode:
Cost tier differentiation separates premium intradermal applications from economy transdermal retail formats, with reimbursement coding determining viable channel economics.
- Transdermal:Antigen diffusion across the full epidermis suits low-dose maintenance regimens. Pharmacy chains in suburban US markets capture volume through consumer-applied patches bypassing clinical overhead.
- Intradermal:Direct deposition into the dermal layer exploits dense immune cell populations for dose-sparing efficacy. Research institutions in Maryland and Queensland concentrate procurement for pediatric and geriatric trials where needle avoidance improves recruitment.
- Subcutaneous:Micro-needle penetration to adipose tissue layers accommodates higher antigen loads. Hospital systems utilize for immunocompromised patients requiring enhanced immunogenicity profiles.
- Intramuscular:Extended-length microneedle arrays reach muscle tissue for conventional immune response kinetics. Healthcare providers in rural markets deploy where cold-chain infrastructure supports traditional supply models.
Intradermal commands premium pricing; transdermal is climbing the fastest through retail channel expansion.
End User:
Customer type fragmentation creates divergent procurement specifications, with institutional buyers prioritizing batch documentation and retail channels emphasizing unit-dose convenience.
- Healthcare Providers:Physician offices and occupational health clinics administer in supervised settings. US Medicare reimbursement constraints under legacy intradermal codes compress margins despite clinical preference for precision delivery.
- Pharmacies:CVS Health and Walgreens pilot programs negotiate direct supply agreements with platform developers. Self-administered formats capture convenience premiums in fall vaccination seasons.
- Hospitals:Inpatient and emergency departments require sterile single-use packaging with full chain-of-custody documentation. EMA adaptive pathway approvals accelerate procurement for seasonal strain updates.
- Research Institutions:Academic medical centers in Boston-Cambridge and Basel clusters drive phase II trial demand. FDA breakthrough therapy designations for pandemic candidates concentrate sponsor investment.
Healthcare providers retain volume leadership; pharmacies show steepest expansion trajectory through channel migration.
Application:
Maturity stage separates established immunization programs from emerging compliance-focused formats, with clinical trial applications occupying intermediate development risk.
- Immunization:Seasonal influenza campaigns and pandemic response programs constitute core demand. US national stockpiling requirements sustain procurement independent of commercial seasonality.
- Disease Prevention:Pre-exposure prophylaxis for high-risk populations extends addressable populations. WHO prequalification pathways unlock Gavi and UNICEF procurement for low-resource settings.
- Clinical Trials:Novel antigen-adjuvant combinations utilize microneedle platforms for pharmacokinetic comparison. Polymer matrix advances achieving 24-month stability at 40°C reduce protocol complexity.
- Patient Compliance:Needle-free administration addresses historically under-immunized pediatric and geriatric segments. Pharmacy retail density in US suburban markets enables this behavioral shift.
Immunization dominates current value; disease prevention is gaining share fastest through developing-country access programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States buyers prioritize pharmacy retail self-administration, while German and Australian procurement concentrates on biodefense stockpiling with extended stability requirements.
United States
Seasonal immunization campaigns and national biodefense reserves drive dual procurement streams. FDA breakthrough therapy designations compress review timelines for pandemic-ready microneedle candidates. Boston-Cambridge biotech clusters anchor phase II trial activity for pediatric and geriatric needle-free formats.
Germany
Precision manufacturing equipment suppliers concentrate near Stuttgart and Munich, creating equipment lead-time bottlenecks for microneedle array production. EMA adaptive pathway mechanisms accelerate rolling reviews for patch-based seasonal strain updates. Research hospital networks in Heidelberg and Berlin procure solid silicon arrays for dermatology applications.
Australia
Biodefense agencies maintain strategic reserves of thermostable formats for rapid pandemic deployment without cold-chain dependency. TGA evaluates microneedle presentations under biologics registration frameworks aligned with WHO prequalification criteria. Queensland academic medical centers drive dissolving polymer trials for tropical stability requirements.
Japan
PMDA streamlines novel delivery platform approvals through sakigake designation pathways for influenza vaccines. METI funding programs support microfabrication talent development at Osaka and Nagoya technical institutes. Domestic demand concentrates in research hospital procurement for precision intradermal applications.
United Kingdom
MHRA applies EU-legacy Vaccines Antigen Master File frameworks to multi-country authorization for patch-based formats. NHS pharmacy retail pilots explore self-administered seasonal vaccination in suburban London and Manchester markets. Oxford and Cambridge research clusters advance combination respiratory vaccine platforms.
Microneedle Flu Vaccine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in microneedle flu vaccine development. Sanofi S.A. leverages captive influenza antigen production to anchor downstream delivery innovation, while Becton, Dickinson and Company sustains dominance in precision injection systems. Three archetypes define competitive positioning: pharmaceutical incumbents with antigen infrastructure, medical device specialists with microfabrication capabilities, and platform-focused biotechs with novel polymer science. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms address equipment lead-time constraints.
Within the integrated pharmaceutical tier, Sanofi S.A. exemplifies backward integration from antigen production into delivery format development. Among device specialists, Becton, Dickinson and Company occupies a position bridging legacy injection systems and microneedle transitions. Platform-focused developers include Vaxxas, which represents the high-density microarray patch archetype for thermostable vaccine delivery. These three anchors illustrate how competitive boundaries redraw around manufacturing scale versus specialized technology development.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Becton, Dickinson and Company |
| Debiotech S.A. |
| NanoPass Technologies |
| FluGen, Inc. |
| Vaxess Technologies |
| Micron Biomedical |
| 3M Company |
| Vaxxas |
| Others |
Supply & Pricing Matrix
Capacity reservation agreements with German and Japanese micro-molding equipment suppliers lock in manufacturing slots and price visibility for microneedle array producers, insulating procurement costs from spot-market volatility in precision capital goods. These multi-year contracts tether unit economics to equipment amortization schedules while compressing margin exposure for scale-up candidates.
Pricing Analysis
After-sales service contracts covering batch release testing and sterility verification drive lifetime value for microneedle platform developers. Pricing stratifies across premium intradermal formats, standard dissolving polymer patches, and economy transdermal retail units. Cost compression in standard-tier products is intensifying because polymer matrix suppliers compete for pharmacy chain procurement slots. Pediatric and geriatric segments show least price sensitivity due to needle-avoidance compliance premiums.
Supply Chain Analysis
Germany and Japan anchor precision micro-molding and laser-dicing equipment fabrication for microneedle array production. Biodegradable carbohydrate polymers draw from agricultural feedstock suppliers in the United States and Brazil. Single-source vulnerability concentrates in photolithography equipment tethered to Dutch and Japanese vendors. Distribution runs through cold-chain-independent logistics networks serving pharmacy retail and biodefense stockpiling channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microneedle flu vaccine market fragmentation creates entry niches as procurement splits between institutional biodefense stockpiling and retail pharmacy self-administration channels.
For Market Incumbents: Shield antigen supply relationships through captive polymer matrix production or exclusive offtake agreements with carbohydrate formulation specialists. Expand capacity reservations with Stuttgart and Munich equipment suppliers before lead-time bottlenecks worsen. Lock in reimbursement coding advocacy with CMS to defend margin position against legacy intradermal injection categories. For New Entrants and Emerging Players: Differentiate on thermostable tropical stability profiles targeting WHO prequalification pathways for Gavi and UNICEF procurement. Penetrate Australian and Queensland biodefense agencies seeking extended shelf-life formats without cold-chain dependency. Pursue direct supply agreements with CVS Health and Walgreens pilot programs as the go-to-market anchor. For Investors and Strategic Acquirers: Capital is best deployed toward platform-focused biotechs with novel polymer science and established phase II trial data. Five-to-ten-year viability hinges on FDA breakthrough therapy designation accumulation and EMA adaptive pathway approvals. Watch for WHO prequalification status attainment as the inflection signal unlocking developing-country volume commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands capacity with German micro-molding equipment to address pharmacy retail procurement timelines. |
| Regulatory Approval Pathway | Accelerates FDA breakthrough therapy designation for pandemic preparedness candidates. |
| Strategic Partnership | Links polymer matrix developers with influenza antigen producers for integrated patch supply. |
| Reimbursement Strategy | Secures distinct CMS procedural codes for microneedle administration beyond legacy categories. |
| Geographic Expansion | Establishes WHO prequalification-compliant production for Gavi and UNICEF procurement channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with vaccine development executives, regulatory affairs leads at FDA and EMA, hospital procurement managers, and pharmacy chain formulary directors; and secondary validation against FDA biologics license application filings, EMA adaptive pathway submissions, ClinicalTrials.gov entries, and CMS reimbursement coding databases. Bottom-up demand modeling triangulated with top-down market sizing across polymer chemistry, delivery mode, and procurement channel dimensions.
Across the analysis window, forecasts incorporate segmentation by product type, delivery mode, end user, and regional regulatory cluster. CAGRs were derived from growth rate convergence modeling applied to historical procurement data and projected stockpiling commitments. Antigen compatibility constraints and equipment lead-time bottlenecks served as industry-specific forecast inputs.
Material uncertainties — antigen immunogenicity degradation through polymer integration, reimbursement coding delays, and microfabrication talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway timelines and cold-chain elimination economics. Recalibration cycles align with material shifts in WHO prequalification criteria and FDA breakthrough therapy designation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spine Surgery Robots Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Disposable Lancets Market
Medical Devices
Dermal Allograft Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Bone Densitometer Devices Market