
 Homecare Medical Devices Market | 2026-2036
Homecare Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Homecare Medical Devices Market Analysis
The EU MDR and FDA's digital health pre-certification framework is realigning how manufacturers validate connected respiratory and cardiac monitors for home use. ResMed leverages its cloud-connected sleep apnea platform to sustain recurring revenue streams across North American and European reimbursement channels. Philips Healthcare anchors its competitive position through in-house production of ventilators and oxygen concentrators, while Abbott Laboratories differentiates via wearable glucose monitoring systems that bypass traditional clinic-based testing workflows.
Homecare medical devices encompass portable, user-operated equipment designed for diagnostic monitoring, therapeutic intervention, or mobility assistance outside clinical facilities, typically operating on battery or low-voltage power with simplified interfaces for non-professional operators. These devices serve the primary purpose of reducing hospital readmission rates while maintaining clinical efficacy through remote data transmission and automated alerts. Monitoring devices dominate current revenue pools due to widespread hypertension and diabetes prevalence, though wearable technologies within the technology dimension represent the fastest-expanding segment as biosensor miniaturization enables continuous cardiac and metabolic tracking. Telehealth integration is maturing rapidly among home health agencies seeking to consolidate patient data streams, while therapeutic devices retain concentrated margins in oxygen delivery and negative pressure wound therapy where reimbursement codes remain favorable.
FDA 510(k) clearances and EU MDR conformity assessments shape market access timelines for connected inhalers and automated insulin delivery systems, with ISO 13485 quality management serving as the baseline operational standard across manufacturing facilities. Japan's PMDA imposes additional clinical data requirements for software-as-a-medical-device classifications, creating a multi-layered compliance architecture for companies pursuing simultaneous US, European, and Asian registrations. Stakeholders must weigh the capital requirements of dual FDA-EU regulatory submissions against the revenue risk of single-market dependency as payor contracts increasingly mandate cross-border interoperability standards.
Market Dynamics
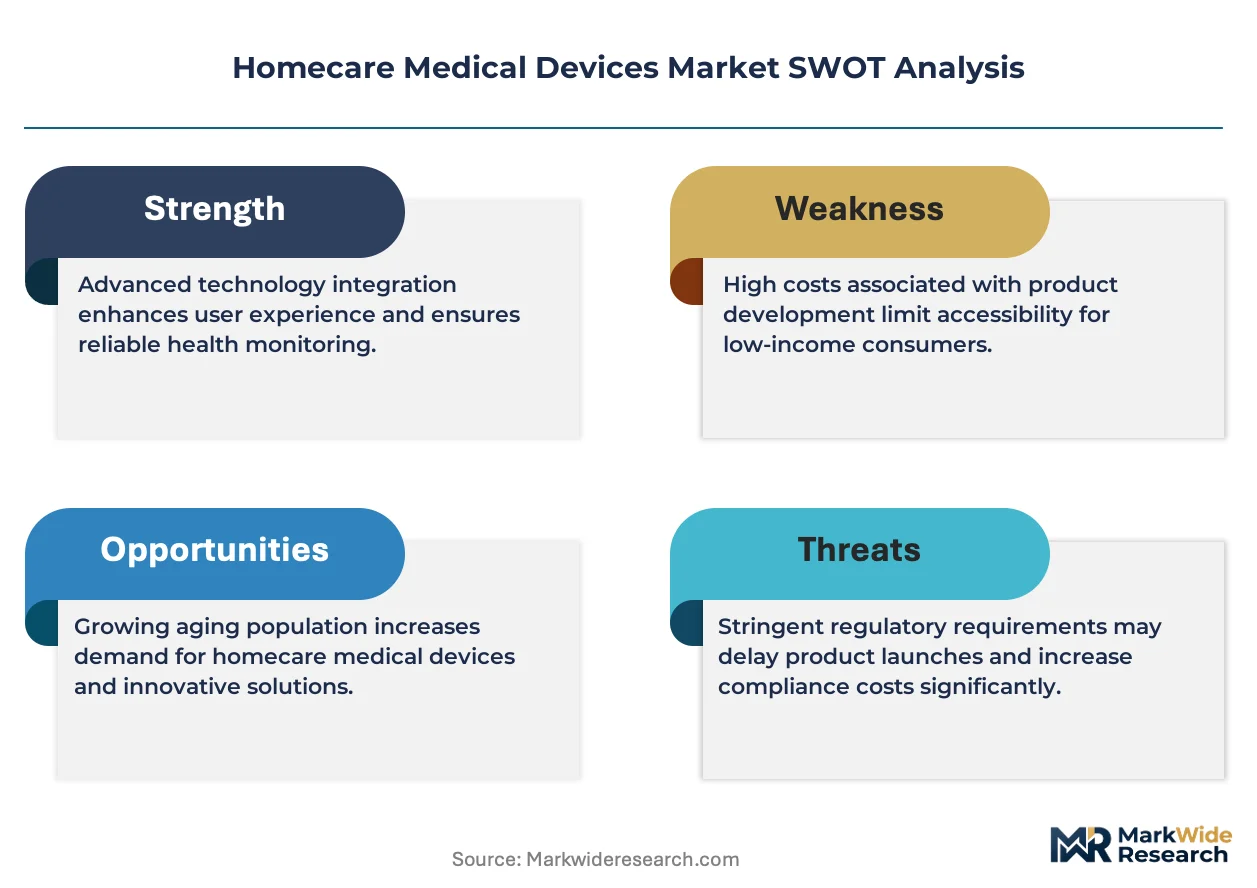
The convergence of FDA's digital health pre-certification pathway with EU MDR's post-market surveillance mandates is compressing development timelines while elevating validation costs for connected respiratory and cardiac monitors.
Growth Catalysts
- Reimbursement Framework Evolution:CMS expanded remote patient monitoring billing codes in the United States, enabling home health agencies to bill for continuous glucose and blood pressure data transmission. This policy shift accelerates provider adoption of cloud-connected diagnostic platforms.
- Biosensor Miniaturization:Wearable patch technologies now enable multi-day cardiac rhythm monitoring without clinic visits. Elderly patients managing atrial fibrillation drive volume expansion for these disposable sensor formats.
- Japan's Super-Aged Society:METI's healthcare robotics subsidies and PMDA's streamlined software-as-a-medical-device pathway position Japanese homecare device demand as the fastest-expanding within OECD markets.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries fabricate over 70% of medical-grade microcontrollers. Geopolitical friction or capacity constraints disrupt ventilator and insulin pump production schedules.
- EU MDR Clinical Data Requirements:Legacy devices previously cleared under MDD directives require renewed conformity assessments with expanded clinical evidence. This regulatory friction delays market re-entry for mid-tier manufacturers.
- Lithium-Ion Battery Cost Volatility:Portable oxygen concentrators and motorized mobility aids depend on cobalt and nickel supply chains concentrated in the Democratic Republic of Congo and Indonesia. Price swings compress hardware margins.
Strategic Opportunities
- Rural India Penetration:Ayushman Bharat's health and wellness center network creates distribution infrastructure for low-cost pulse oximeters and nebulizers in previously unreachable districts. CDSCO's streamlined Class A/B device registration accelerates entry.
- AI-Enabled Predictive Alerts:Machine learning algorithms analyzing continuous vital sign streams can forecast COPD exacerbations 48-72 hours pre-hospitalization. This convergence of biosensors and predictive analytics opens subscription revenue models.
- Germany's DiGA Fast-Track:The BfArM's digital health applications approval pathway reimburses prescribed apps that integrate with prescribed homecare hardware, creating a regulatory tailwind for connected inhaler and insulin pen ecosystems.
Industry Challenges
- Cybersecurity Validation Burden:FDA's 2023 guidance on premarket submissions for interconnected devices requires documented threat modeling and penetration testing. This extends 510(k) clearance timelines by 4-6 months for first-time connected product entrants.
- Interoperability Standard Fragmentation:HL7 FHIR, IEEE 11073, and proprietary cloud protocols create integration complexity with hospital EHR systems. Device manufacturers must maintain multiple data exchange interfaces, elevating software maintenance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homecare Medical Devices Market |
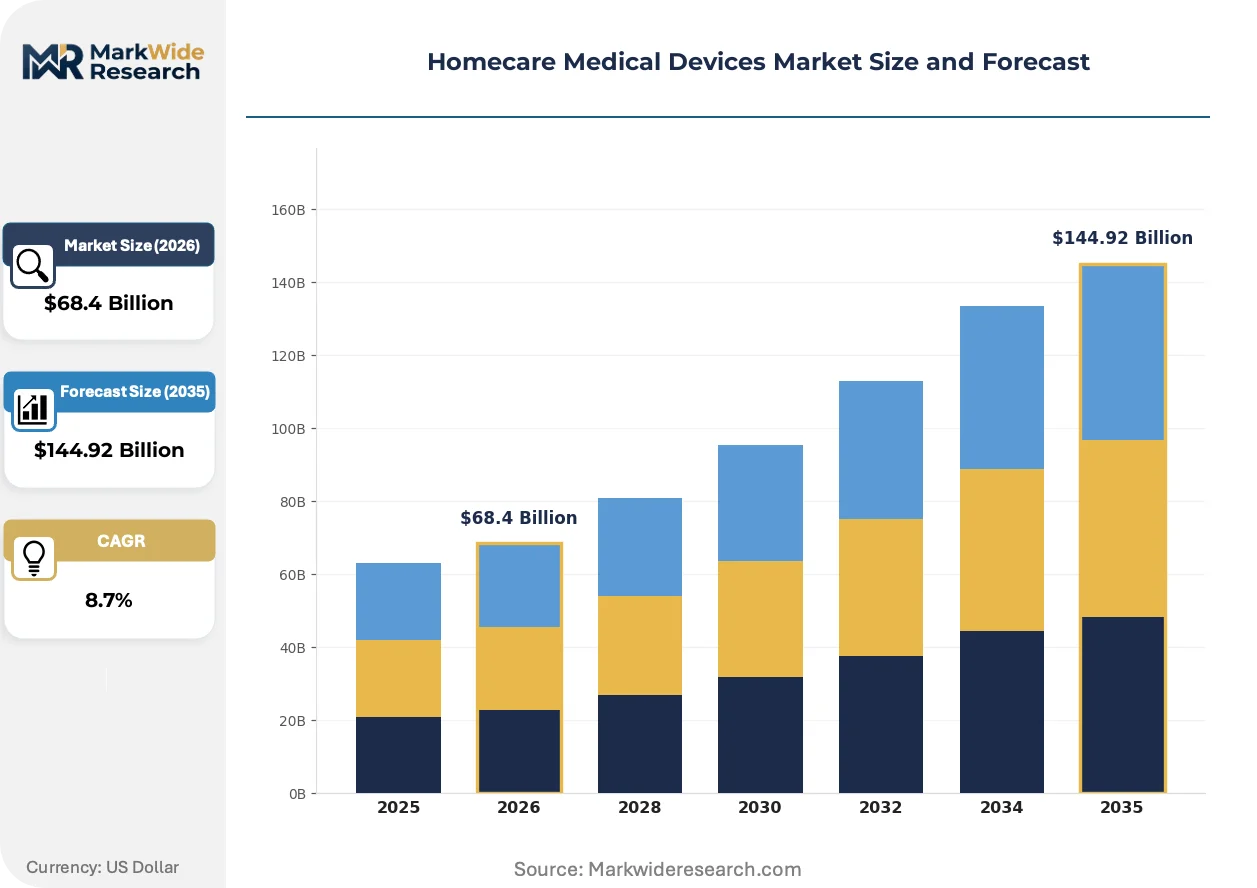
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Monitoring Devices, Therapeutic Devices, Mobility Aids, Diagnostic Equipment End User: Patients, Caregivers, Home Health Agencies, Long-Term Care Facilities Technology: Telehealth, Wearable Technologies, IoT-enabled Devices, Automated Systems Application: Chronic Disease Management, Rehabilitation, Wellness Monitoring, Emergency Response |
| Companies Covered | ResMed, Philips Healthcare, Abbott Laboratories, Medtronic, GE Healthcare, Omron Healthcare, Invacare Corporation, Medline Industries, Fresenius Medical Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homecare Medical Devices Market Emerging Trajectories
Telehealth platform maturation is dissolving the boundary between acute hospital monitoring and residential care, forcing device manufacturers to architect for continuous data streaming rather than episodic measurement.
Solid-state battery chemistry is electrifying the power architecture of portable oxygen concentrators and ventilators. Home health agencies in Germany and Japan are replacing legacy lead-acid and lithium-polymer inventories with silicon-anode cells that halve weight while doubling runtime between charges. This energy density leap is enabling same-day hospital discharge for patients previously requiring institutional oxygen infrastructure.
The EU AI Act's risk classification framework for medical device software is reshaping development roadmaps for algorithm-enabled diagnostic tools. Manufacturers must now document training data provenance and algorithmic transparency before CE marking, with high-risk respiratory and cardiac monitoring applications facing conformity assessment body scrutiny. Dutch and Swedish notified bodies are establishing specialized AI review capacities to manage application volume.
Hospital-at-home programs are unbundling traditional equipment rental contracts into modular service tiers. US health systems now procure pulse oximetry, medication adherence sensors, and virtual nursing separately rather than through bundled durable medical equipment vendors. This procurement fragmentation favors specialized device manufacturers with direct EHR integration capabilities over legacy rental intermediaries.
Homecare Medical Devices Market Segmentation
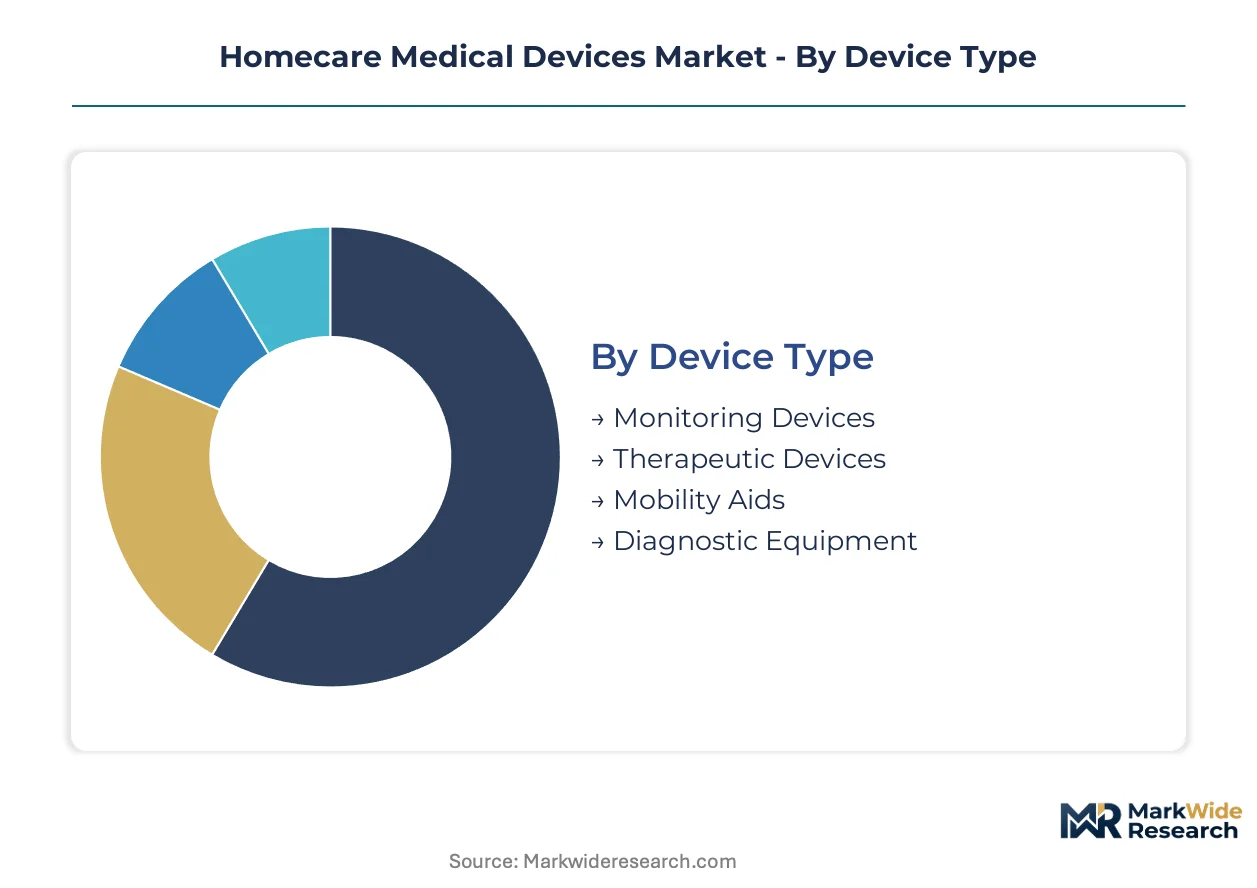
Homecare medical devices fragment across four intersecting dimensions that determine reimbursement eligibility, regulatory pathway, and procurement channel. Device type and technology selections dictate whether products qualify for CMS remote patient monitoring codes or require institutional dispensing licenses.
Device Type:
Standalone bedside units operate independently of hospital networks, while embedded diagnostic modules transmit data through cloud-connected platforms requiring FDA 510(k) clearance for software-as-medical-device functionality.
- Monitoring Devices:Continuous glucose monitors, pulse oximeters, and blood pressure cuffs with Bluetooth telemetry dominate current revenue pools. Elderly patients managing hypertension in the United States drive replacement demand for cellular-enabled models that bypass smartphone pairing requirements.
- Therapeutic Devices:Portable oxygen concentrators, nebulizers, and negative pressure wound therapy systems deliver clinical-grade intervention outside acute settings. German home health agencies favor lightweight concentrators with 8-hour battery runtime for same-day hospital discharge protocols.
- Mobility Aids:Motorized wheelchairs and patient lifts with obstacle-avoidance sensors. Japan's METI healthcare robotics subsidies accelerate adoption of semi-autonomous transfer devices in super-aged households.
- Diagnostic Equipment:Handheld ECG monitors and spirometers with algorithmic interpretation. CDSCO's streamlined Class A/B registration in India enables low-cost manufacture for rural clinic networks.
Volume placements concentrate in Monitoring Devices; the faster expansion belongs to Therapeutic Devices as hospital-at-home programs unbundle oxygen and wound care from institutional contracts.
End User:
Procurement authority varies sharply across this dimension, with institutional buyers negotiating enterprise EHR integration while individual patients prioritize out-of-pocket affordability and simplified interfaces.
- Patients:Direct consumers purchasing retail glucose meters and blood pressure cuffs. Medicare Advantage plans in the United States increasingly subsidize connected models that demonstrate readmission reduction.
- Caregivers:Family members acquiring medication dispensers and fall detection sensors for aging relatives. Japanese long-term care insurance reimburses 90% of rental costs for GPS-enabled wandering prevention devices.
- Home Health Agencies:Skilled nursing providers procuring multi-parameter monitoring kits under bundled payment arrangements. CMS expanded billing codes now cover 16 days of continuous data transmission per episode.
- Long-Term Care Facilities:Assisted living operators deploying centralized nurse call systems with wearable panic buttons. EU MDR post-market surveillance requirements elevate documentation burdens for multi-site deployments.
Revenue concentrates with Home Health Agencies; Caregivers represent the steepest expansion trajectory as informal care networks professionalize through reimbursed remote monitoring.
Technology:
Integration maturity separates legacy episodic measurement from continuous streaming architectures that enable predictive analytics and automated clinical alerts.
- Telehealth:Video consultation platforms with peripheral device integration. German DiGA fast-track approvals reimburse prescribed apps that synchronize with home spirometers and pulse oximeters.
- Wearable Technologies:Skin-patch biosensors and smartwatch form factors enabling multi-day cardiac rhythm monitoring. FDA's 2023 cybersecurity guidance extends 510(k) timelines for Bluetooth-connected patch manufacturers.
- IoT-enabled Devices:Cellular-connected inhalers and insulin pens tracking adherence through cloud dashboards. PMDA's software-as-medical-device pathway in Japan imposes additional clinical evidence requirements for algorithm-enabled dose recommendations.
- Automated Systems:Closed-loop insulin delivery and adaptive servo-ventilation with minimal user intervention. Semiconductor supply concentration in Taiwan disrupts production schedules for microcontroller-dependent pumps.
Installed base concentrates in Telehealth; Wearable Technologies gain share fastest as biosensor miniaturization enables disposable multi-day monitoring formats.
Application:
Clinical acuity determines regulatory classification, with emergency response applications facing stricter validation than wellness tracking while rehabilitation sits in intermediate risk tiers.
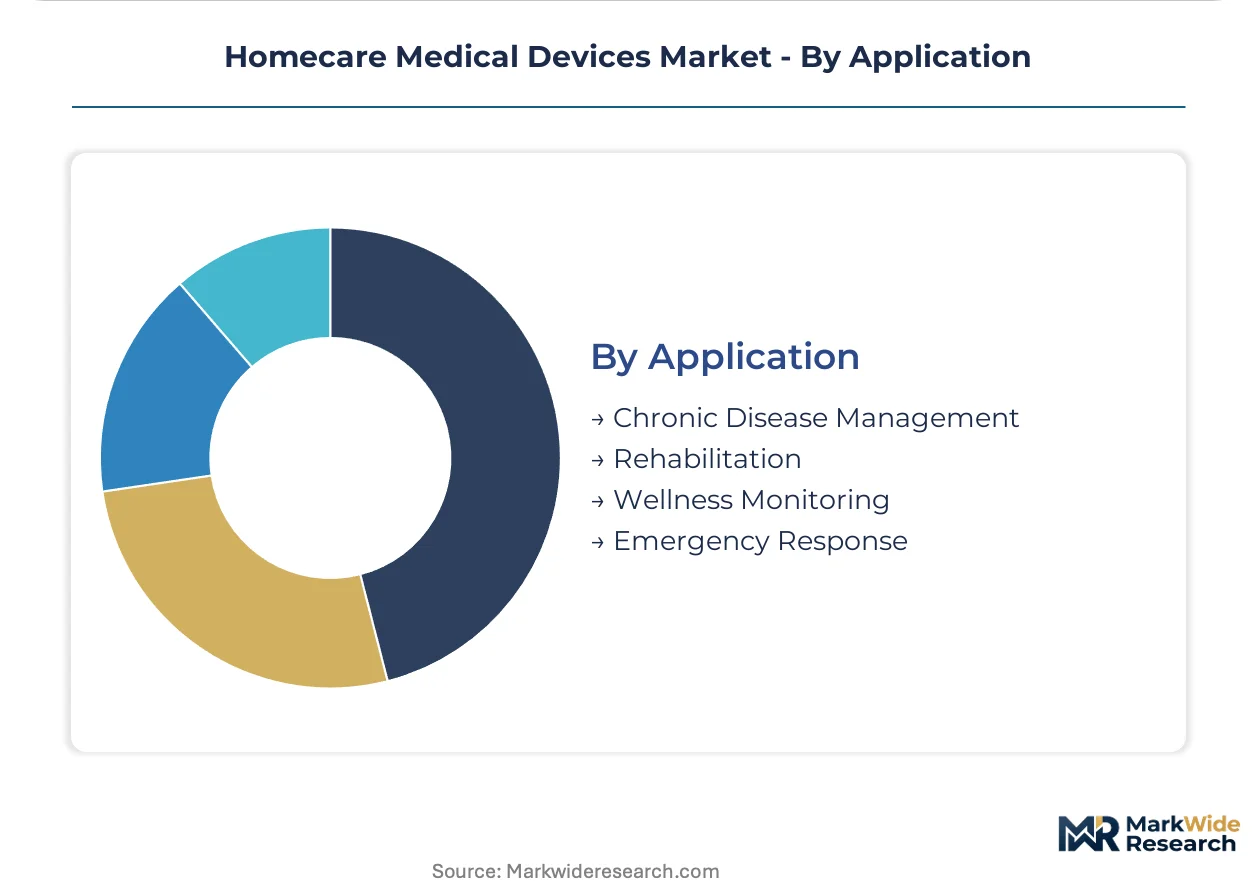
- Chronic Disease Management:Diabetes, COPD, and heart failure monitoring protocols dominating prescription volumes. United States reimbursement frameworks favor continuous glucose monitoring over fingerstick testing for Type 1 patients.
- Rehabilitation:Post-surgical mobility restoration and stroke recovery devices with gamified exercise tracking. German statutory health insurance covers 30 sessions of sensor-guided home physiotherapy annually.
- Wellness Monitoring:Consumer-grade sleep and activity tracking without diagnostic claims. EU AI Act risk classification exempts general wellness applications from medical device conformity assessment.
- Emergency Response:Fall detection, automated external defibrillators, and medication overdose alerts. Japan's Fire and Disaster Management Agency certifies cellular panic buttons for direct dispatch integration.
Patient volumes concentrate in Chronic Disease Management; Emergency Response climbs fastest as aging-in-place policies shift acute event handling from EMS to preemptive home intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of homecare medical devices clusters in Germany, the United States, and Japan, while consumption growth concentrates where aging demographics intersect with reimbursement reform. Production capacity for connected respiratory monitors and portable oxygen systems outpaces demand in established markets, forcing manufacturers to seek volume in emerging care economies.
United States
Medicare Advantage plans and CMS remote patient monitoring billing codes drive procurement of cellular-enabled glucose monitors and blood pressure cuffs. FDA's digital health pre-certification pathway accelerates 510(k) clearances for cloud-connected cardiac devices. The Minneapolis-St. Paul corridor anchors concentrator manufacturing, with Boston and San Diego clusters specializing in algorithm-enabled diagnostic tools.
Germany
Statutory health insurance coverage for hospital-at-home programs and the BfArM DiGA fast-track create reimbursement tailwinds for connected inhalers and insulin delivery systems. EU MDR post-market surveillance requirements elevate documentation burdens for multi-site deployments. The Rhine-Ruhr industrial belt concentrates ventilator and oxygen concentrator production, with Baden-Württemberg hosting precision sensor fabrication for wearable cardiac monitors.
Japan
METI healthcare robotics subsidies and PMDA's streamlined software-as-medical-device pathway position Japanese demand as the fastest-expanding within OECD markets. Super-aged household demographics accelerate adoption of semi-autonomous transfer devices and GPS-enabled wandering prevention systems. The Kanto region around Tokyo hosts the densest cluster of homecare device R&D facilities, with Osaka-Kobe specializing in portable diagnostic equipment.
India
Ayushman Bharat's health and wellness center network creates distribution infrastructure for low-cost pulse oximeters and nebulizers in previously unreachable districts. CDSCO's streamlined Class A/B device registration accelerates market entry for foreign manufacturers. Gujarat and Maharashtra industrial corridors concentrate contract manufacturing for export-oriented glucose meter production, with Bangalore emerging as a hub for telehealth platform integration.
United Kingdom
NHS long-term plan commitments to hospital-at-home and virtual ward programs expand procurement of multi-parameter monitoring kits for post-acute care. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UK-specific device registrations. The Oxford-Cambridge arc anchors connected diagnostic startups, with Greater Manchester hosting distribution centers serving Northern England's aging population clusters.
Homecare Medical Devices Market Vendor Landscape
The competitive structure tilts toward diversified health technology conglomerates with established reimbursement relationships and captive cloud infrastructure. Three to five integrated players capture disproportionate share in connected respiratory and cardiac monitoring, while mid-tier specialists compete on price in portable oxygen and mobility aids. Archetypes include: full-stack platform operators integrating hardware, software, and data analytics; component-focused manufacturers supplying white-label devices to home health agencies; and regional assemblers serving price-sensitive emerging markets. Dominant competitive moves center on backward integration into sensor fabrication and strategic partnerships with telehealth platform operators.
Among North American and European platform operators, ResMed, Philips Healthcare, and Abbott Laboratories exemplify the integrated archetype. ResMed occupies a position anchored in cloud-connected sleep apnea management with recurring revenue streams across reimbursement channels. Philips Healthcare sits within the therapeutic device tier through in-house production of ventilators and oxygen concentrators. Abbott Laboratories represents the wearable diagnostics vector, with positioning built on continuous glucose monitoring systems that bypass traditional clinic-based workflows. These three anchors demonstrate how regulatory pre-clearance and payor contract depth create defensive moats against component-focused challengers.
| Leading Market Players |
|---|
| ResMed |
| Philips Healthcare |
| Abbott Laboratories |
| Medtronic |
| GE Healthcare |
| Omron Healthcare |
| Invacare Corporation |
| Medline Industries |
| Fresenius Medical Care |
| Others |
Supply Flow & Price Mechanics
EU MDR's post-market surveillance mandates and FDA's cybersecurity guidance for connected devices gate qualified supply access and premium-tier pricing power, as manufacturers absorbing compliance validation costs pass through elevated price floors while mid-tier competitors face margin compression from renewed conformity assessments.
Pricing Analysis
Value-based pricing tied to hospital readmission reduction outcomes anchors CMS reimbursement frameworks for cellular-enabled glucose monitors and blood pressure cuffs. Pricing stratifies across FDA 510(k) cleared, CE-marked, and uncertified economy tiers, with brand premium and ISO 13485 certification level driving spreads. Cost compression in economy-grade pulse oximeters is intensifying because of India's CDSCO streamlined registration attracting low-cost manufacturers. Home health agencies demonstrate lowest price sensitivity due to bundled billing codes, while direct retail patients exhibit highest elasticity.
Supply Chain Analysis
India's PLI scheme for medical electronics and local-content preferences in government procurement are reshaping sourcing patterns for contract manufacturers serving export markets. Semiconductor fabrication concentrates in Taiwan, sensor production in Germany and Japan, and final assembly in China and Mexico. Raw material dependencies span cobalt and nickel for lithium-ion batteries, medical-grade silicon wafers, and precision polymers for disposable biosensors. Single-source vulnerability around Taiwan-based microcontroller foundries disrupts insulin pump and ventilator production schedules. Distribution runs through hospital purchasing committees, GPO contracts, and direct-to-patient retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The homecare medical devices sector sits in a technology-transition phase where solid-state battery chemistry displaces legacy lead-acid and lithium-polymer power architectures, halving device weight while doubling runtime and enabling same-day hospital discharge protocols previously requiring institutional oxygen infrastructure.
For Market Incumbents: Anticipate semiconductor supply concentration risks by securing alternative microcontroller sources outside Taiwan and deepening backward integration into sensor fabrication. Prioritize FDA pre-certification pathway investment to compress 510(k) timelines against emerging connected-device entrants. Defensive moats rest on captive cloud infrastructure and established payor contract depth. For New Entrants and Emerging Players: Germany's DiGA fast-track opens a window for software companion apps integrating with prescribed inhalers and insulin pens, creating reimbursable digital health ecosystems. Target rural India penetration through Ayushman Bharat's health and wellness center network for low-cost nebulizers and pulse oximeters. White-space exists in AI-enabled predictive alert subscriptions forecasting COPD exacerbations. Go-to-market leverage direct EHR integration capabilities over legacy rental intermediaries. For Investors and Strategic Acquirers: CMS expansion of remote patient monitoring billing codes is the leading indicator that cloud-connected diagnostic platforms will capture disproportionate reimbursement share over the coming decade. Acquisition focus: mid-tier specialists with FDA-cleared software-as-medical-device platforms and direct hospital system partnerships. Watch for EU AI Act conformity assessment body capacity constraints as signal for algorithm-enabled diagnostic tool validation bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for connected cardiac monitors under digital health pre-certification pathway. |
| CE Marking Pathway | EU MDR clinical evidence requirements delay re-entry for legacy devices previously cleared under MDD directives. |
| Hospital System Partnership | Direct EHR integration capabilities unbundle traditional equipment rental contracts into modular service tiers. |
| Software Companion Development | Germany's BfArM DiGA fast-track reimburses prescribed apps synchronizing with home spirometers. |
| Reimbursement Strategy | CMS expanded billing codes now cover continuous data transmission for home health agency episodes. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, EU MDR conformity assessment volumes, and CMS reimbursement code expansions anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and home health agency procurement leads. Secondary validation drew from FDA filings, EMA submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation cross-checked volume estimates.
Segment-weighting across device type, technology architecture, application acuity, and end-user procurement authority structured the analytical framework. CAGR derivation incorporated biosensor miniaturization adoption curves, telehealth platform maturation rates, and aging demographic penetration by geography. Forecast inputs included semiconductor supply capacity constraints, lithium-ion battery cost volatility, and regulatory pathway evolution across FDA, EU MDR, and PMDA jurisdictions.
Caveats apply where Taiwan semiconductor supply disruptions, EU MDR notified body capacity constraints, or cobalt-nickel commodity price spikes could materially shift the outlook. Forecasts embed assumptions around reimbursement code stability and cybersecurity validation burden trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Contact Thermometer Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Europe C-Arms Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Extremities Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Anorectal Manometry Systems Market