
 Endodontic Devices Market | 2026-2036
Endodontic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Endodontic Devices Market Intelligence
German instrument manufacturers is broadening supply capacity for precision nickel-titanium files. Dentsply Sirona leverages vertical integration across file production and obturation systems to control quality benchmarks. Danaher sustains R&D intensity in ultrasonic activation technologies for canal disinfection. Envista anchors its position through specialized distribution networks serving academic dental hospitals.
Endodontic devices comprise precision-engineered instruments and materials designed to access, shape, clean, and seal the internal root canal system, with nickel-titanium alloys providing superelasticity for curved canal navigation. These tools serve the primary purpose of eliminating pulpal infection while preserving natural dentition. Rotary files lead product type revenue due to procedural efficiency gains in general dental practice, while laser technology captures premium positioning despite higher capital requirements. Dental clinics represent the fastest-growing end user segment as group practice models consolidate purchasing power.
The FDA's 510(k) framework governs premarket notification for endodontic files and obturation devices, while ISO 3630-1 standards define dimensional and functional requirements for endodontic instruments. The EU Medical Device Regulation (MDR) intensifies clinical evidence requirements for reusable endodontic equipment, reshaping manufacturer compliance investments. Stakeholders must monitor reimbursement shifts in key markets and the pace of nickel-titanium recycling infrastructure development.
Market Dynamics
Nickel-titanium rotary systems are compressing procedural timeframes while the EU MDR intensifies clinical evidence burdens for reusable instrument portfolios. German dental reimbursement frameworks reward advanced endodontic outcomes, redirecting capital toward precision file manufacturing.
Growth Catalysts
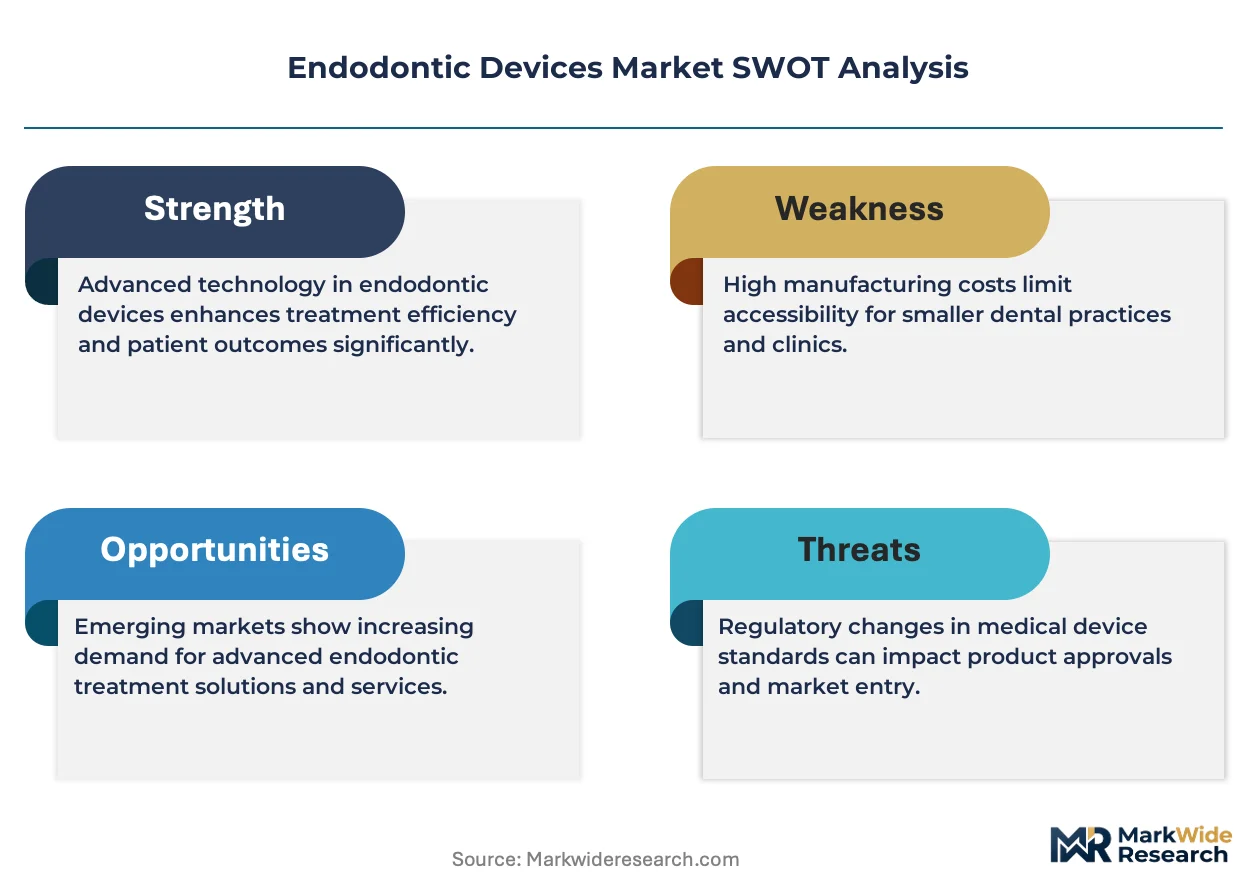
- FDA 510(k) Pathway:The streamlined premarket notification process accelerates endodontic file and obturation device entry timelines, reducing regulatory lag for novel alloys.
- Dental Clinic Consolidation:Group practice models across the United States concentrate purchasing power, enabling bulk procurement of integrated rotary and obturation systems.
- Nickel-Titanium Superelasticity:The alloy's shape-memory properties enable navigation of curved canal anatomies, expanding treatable case complexity in general practice settings.
Market Restraints
- Titanium Sponge Volatility:Raw material price swings for nickel-titanium feedstock compress margin predictability for precision file manufacturers.
- German Supply Concentration:Precision grinding and heat-treatment capabilities for rotary instruments cluster in Baden-Württemberg and Bavaria, creating geographic single-point vulnerability.
- EU MDR Clinical Evidence:The intensified documentation requirements for reusable endodontic equipment extend compliance timelines and inflate regulatory overhead.
Strategic Opportunities
- Indian Dental Infrastructure:Underpenetrated endodontic service capacity in tier-2 and tier-3 cities creates whitespace for portable obturation systems and single-use file kits.
- Ultrasonic-Laser Convergence:Canal disinfection protocols combining ultrasonic activation with diode laser adjuncts open premium positioning in academic hospital channels.
- PLI Scheme Alignment:India's production-linked incentive framework for medical devices offers capital subsidy pathways for domestic nickel-titanium file manufacturing.
Industry Challenges
- Endodontic Microsurgery Training:The specialized skillset for apical microsurgical procedures remains concentrated in university hospital settings, limiting generalist adoption.
- Legacy Hand File Integration:Hybrid workflows combining rotary and manual instrumentation create inventory complexity and sterilization protocol fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endodontic Devices Market |
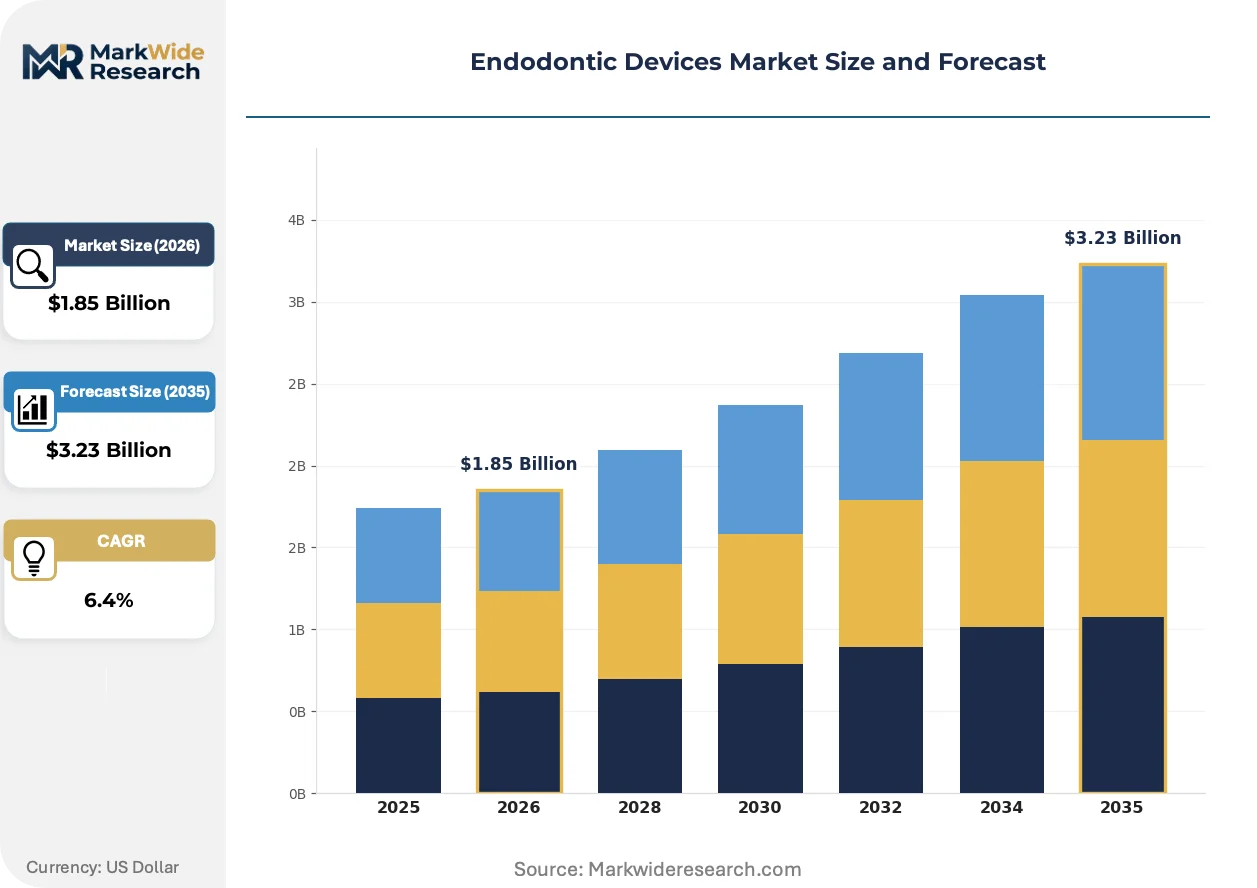
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endodontic Shapers, Rotary Files, Irrigation Devices, Obturation Materials Technology: Nickel-Titanium, Ultrasonic, Manual, Laser End User: Dentists, Dental Clinics, Hospitals, Academic Institutions Treatment Type: Root Canal Therapy, Retreatment, Apexification, Pulp Therapy |
| Companies Covered | Dentsply Sirona, Danaher, Envista, FKG Dentaire, Ivoclar Vivadent, Septodont, Ultradent Products, COLTENE, Brasseler USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endodontic Devices Market Strategic Shifts & Innovations
Digital canal mapping and single-use file economics are restructuring procurement calculus across dental practice archetypes. Material science advances in heat-treated nickel-titanium alloys compress instrument fatigue thresholds.
Heat-treated nickel-titanium rotary files deliver enhanced cyclic fatigue resistance for complex canal anatomies. Dental clinics in Germany and the United States are adopting these alloys at accelerating replacement cycles. The technology is converging with 3D-printed file handle geometries to enable patient-specific canal navigation protocols.
The EU Medical Device Regulation's clinical evidence requirements for reusable endodontic equipment entered full enforcement across member states. Manufacturers must now submit post-market surveillance data for file retrieval systems and electronic apex locators. German notified bodies are processing MDR certifications for obturation devices at extended timelines, compressing product refresh rates.
Group purchasing organizations now dominate capital equipment acquisition for multi-site dental clinics in the United States. Traditional distributor relationships are yielding to direct manufacturer contracts with standardized service level agreements. This consolidation is most visible in Florida and Texas, where dental service organizations command regional purchasing leverage over file and obturation system vendors.
Endodontic Devices Market Segmentation
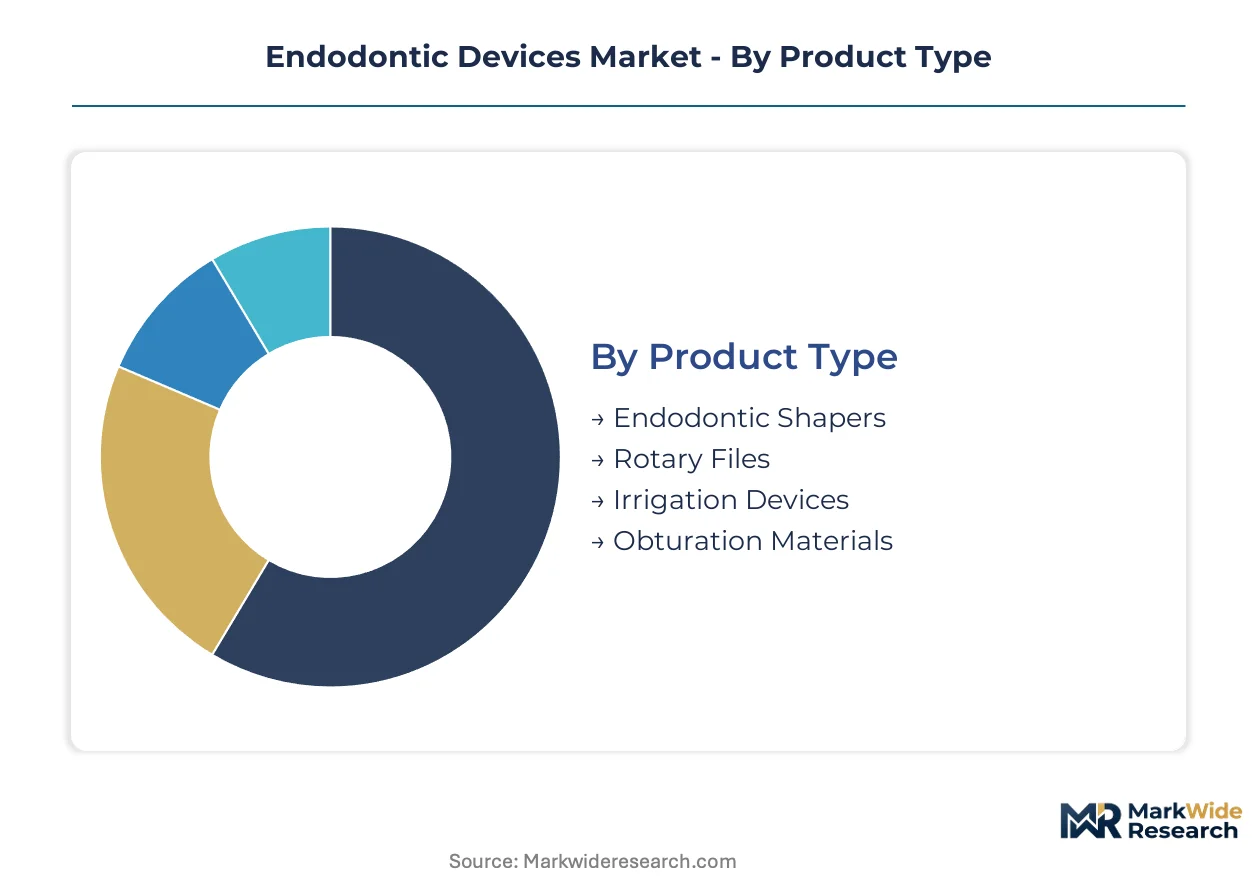
Endodontic device procurement varies sharply by clinical setting and procedural complexity. Upgrade cycles for nickel-titanium rotary systems differ fundamentally from capital-intensive laser platforms. Understanding segment-level replacement dynamics enables precise inventory forecasting across dental supply chains.
Product Type:
Replacement velocity separates commodity consumables from durable equipment categories in endodontic portfolios.
- Rotary Files:Nickel-titanium alloys deliver superelastic navigation of curved canal anatomies. German dental clinics are compressing replacement cycles for heat-treated variants as cyclic fatigue thresholds improve.
- Obturation Materials:Thermoplasticized gutta-percha systems seal disinfected canal systems against bacterial re-entry. United States group practices are consolidating procurement of integrated obturation units with standardized warm vertical compaction protocols.
- Endodontic Shapers:Orifice-opening instruments establish canal path patency before rotary instrumentation. These stainless steel or nickel-titanium tools experience lower wear rates than finishing files.
- Irrigation Devices:Ultrasonic and sonic activation systems enhance irrigant penetration into lateral canal branches. Academic hospitals in Germany are piloting negative-pressure delivery configurations.
Rotary files sit at the top of the volume ranking, with obturation materials climbing the fastest.
Technology:
Capital intensity and clinical training requirements stratify adoption curves across technology tiers.
- Nickel-Titanium:Heat-treated alloys with controlled austenite finish temperatures enable single-file shaping protocols. United States general practices are displacing multi-file sequences as confidence in reciprocating kinematics builds.
- Manual:Stainless steel hand files retain utility for initial canal negotiation and retreatment cases. Developing markets with price-sensitive procurement maintain higher manual instrument ratios.
- Ultrasonic:Piezoelectric activation enhances irrigant agitation and facilitates post removal. The technology requires dedicated generator units that extend payback periods for solo practitioners.
- Laser:Diode and erbium laser adjuncts target canal disinfection through photothermal effects. German university hospitals are the primary adoption channel given capital requirements and technique sensitivity.
Nickel-titanium commands the highest shipment volumes, while ultrasonic applications are gaining share fastest among academic channels.
End User:
Purchasing consolidation patterns diverge between institutional buyers and independent operators.
- Dental Clinics:Multi-site dental service organizations in Florida and Texas leverage standardized rotary and obturation system contracts. These entities negotiate direct manufacturer relationships that bypass traditional distribution markups.
- Dentists:Solo and small-group practices maintain flexible procurement across multiple file brands. Their inventory management prioritizes case-by-case instrument selection over bulk standardization.
- Hospitals:Integrated health systems incorporate endodontic services within broader oral surgery departments. Their capital budgets accommodate premium laser and ultrasonic platforms.
- Academic Institutions:Dental schools and university hospitals drive protocol standardization through curriculum design. These settings function as technology validation gates before commercial diffusion.
Dental clinics lead volume concentration, with hospitals showing the steepest expansion trajectory in capital equipment categories.
Treatment Type:
Procedural reimbursement levels and case complexity determine instrument utilization intensity.
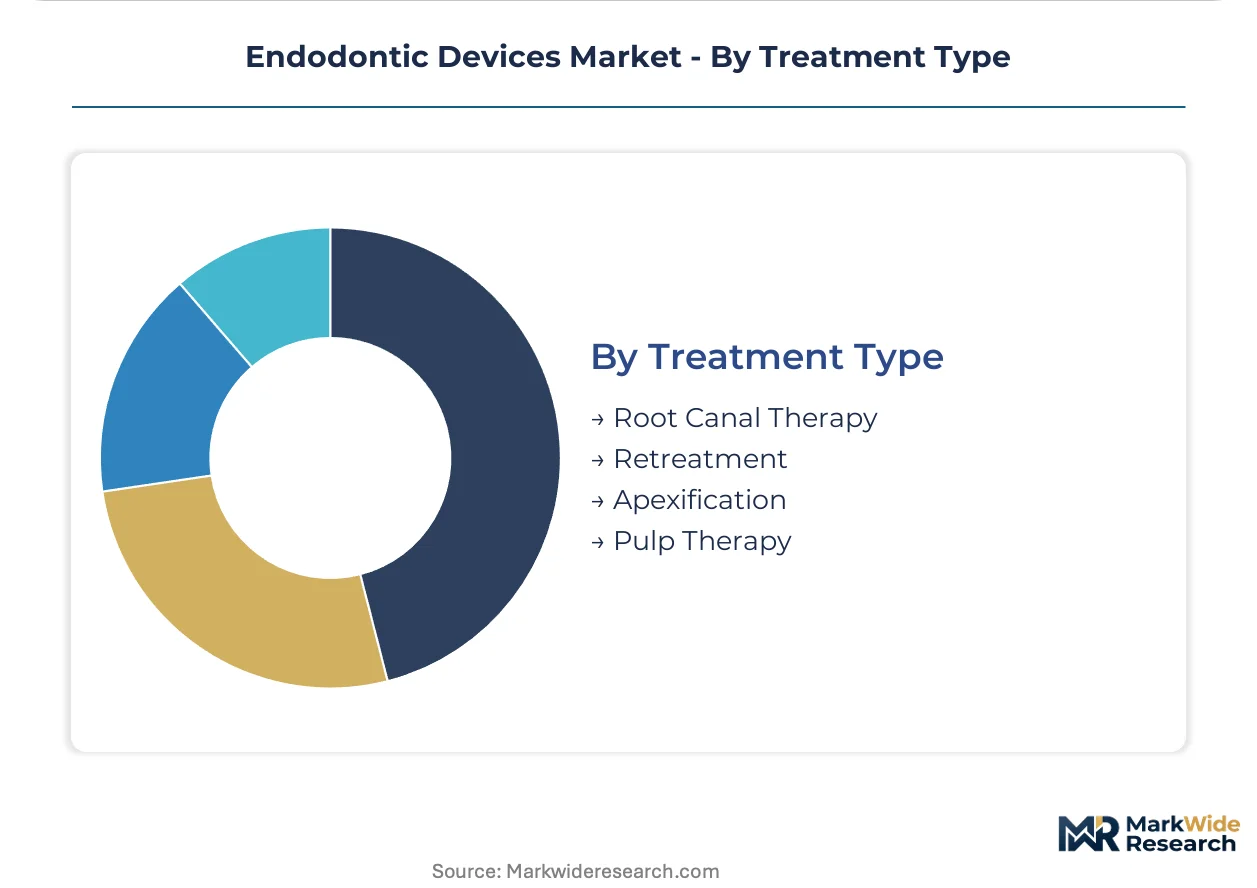
- Root Canal Therapy:Primary endodontic intervention generates the baseline demand for shapers, rotary files, and obturation materials. German reimbursement frameworks reward biological outcome preservation over extraction-replacement alternatives.
- Retreatment:Failed initial therapy requires specialized removal systems for gutta-percha and post extraction. These cases consume more instrument time and specialized armamentarium per procedure.
- Pulp Therapy:Vital pulp preservation procedures in pediatric and young adult dentitions employ biocompatible capping materials. The segment emphasizes minimally invasive approaches distinct from conventional root canal protocols.
- Apexification:Immature permanent teeth with open apices require induction of calcific barrier formation. MTA and bioceramic materials dominate this niche application.
Root canal therapy anchors volume rankings, with retreatment applications expanding most quickly as aging initial treatments require intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting endodontic device manufacturing toward jurisdictions with streamlined premarket pathways and favorable reimbursement architectures. Production capacity is migrating from high-compliance-cost environments to regions offering faster FDA 510(k) equivalence recognition or production-linked incentive frameworks.
United States
Dental service organizations in Florida and Texas are consolidating procurement of integrated rotary-obturation systems through direct manufacturer contracts. The FDA's 510(k) premarket notification pathway accelerates entry timelines for novel nickel-titanium alloys and electronic apex locators. Precision file manufacturing clusters concentrate in Minneapolis-St. Paul and Southern California, where heat-treatment facilities serve domestic and export demand.
Germany
Statutory dental insurance frameworks reward biological outcome preservation, redirecting patient volume toward advanced endodontic procedures over extraction-replacement alternatives. The EU Medical Device Regulation's intensified clinical evidence requirements for reusable instruments extend certification timelines through notified bodies in Baden-Württemberg. Stuttgart and Munich anchor precision grinding capabilities for rotary instruments, with Bavarian facilities expanding nickel-titanium recycling infrastructure.
India
Tier-2 and tier-3 cities present whitespace for portable obturation systems as dental clinic penetration deepens beyond metropolitan cores. The Production-Linked Incentive scheme for medical devices offers capital subsidy pathways for domestic nickel-titanium file manufacturing. Gujarat and Maharashtra are attracting precision machining investments through dedicated medical device parks with shared heat-treatment infrastructure.
China
Domestic dental chains in Shanghai and Guangzhou are standardizing on reciprocating single-file systems to compress chair time and improve throughput. The National Medical Products Administration's streamlined Class II device registration supports local manufacturing of electronic apex locators and obturation guns. Yangtze River Delta clusters in Jiangsu province are scaling CNC grinding capacity for export-oriented file production.
Japan
Academic dental hospitals in Tokyo and Osaka function as validation gates for ultrasonic-laser convergence protocols before commercial diffusion. The Ministry of Economy, Trade and Industry's medical device promotion programs support domestic development of canal disinfection technologies. Kansai-region manufacturers specialize in piezoelectric ultrasonic generators for irrigant activation in complex retreatment cases.
Endodontic Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital workflow integration and single-use economics. The vendor base stratifies across three tiers: multinational conglomerates with captive alloy supply, mid-scale specialists with regional distribution density, and technology-focused entrants betting on 3D-printed file geometries. Archetypes include vertically integrated materials-to-devices operators, precision grinding subcontractors with brand-forward positioning, and software-hardware convergents. Dominant competitive moves span backward integration into nickel-titanium feedstock and strategic partnerships with dental service organizations for exclusive supply contracts.
Among diversified dental conglomerates, Dentsply Sirona and Danaher exemplify the materials-to-devices archetype through captive control over file production and obturation system integration. Envista occupies a position within the specialist distribution tier, anchoring academic hospital channels through dedicated service networks. FKG Dentaire represents the precision-specialist archetype, with Swiss-based manufacturing heritage signaling quality positioning in European markets.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Danaher |
| Envista |
| FKG Dentaire |
| Ivoclar Vivadent |
| Septodont |
| Ultradent Products |
| COLTENE |
| Brasseler USA |
| Others |
Cost & Logistics Intelligence
Titanium sponge price volatility cascades through nickel-titanium file manufacturing into three-tier pricing structures across premium, standard, and economy levels. German precision grinding clusters and Chinese CNC capacity shape tier boundaries through feedstock cost pass-through and heat-treatment capability scarcity.
Pricing Analysis
Distributor margins of 25-35% compress at the dental clinic consolidation tier where direct manufacturer contracts displace traditional channels. Pricing stratifies across premium, standard, and economy tiers based on heat-treatment certification grade and volume scale procurement. Cost compression in the standard tier intensifies because Chinese feedstock integration undercuts European manufacturing. Group purchasing organizations exhibit lowest price sensitivity; solo practitioners remain most price-responsive.
Supply Chain Analysis
Direct-to-dental-service-organization channels handle hyperscale buyer demand in Florida and Texas, bypassing traditional distribution markups. Precision grinding capacity concentrates in Germany, China, and the United States; nickel-titanium feedstock draws from Chinese sponge producers and Ukrainian ore processors. Single-source vulnerability clusters in Baden-Württemberg heat-treatment facilities. Distribution runs through manufacturer-direct contracts for consolidated clinics and dental distributors for independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endodontic devices market represents a late-cycle quality story as German reimbursement frameworks redirect patient volume toward biological outcome preservation over extraction alternatives.
For Market Incumbents: To counter titanium sponge price volatility, secure captive nickel-titanium feedstock through backward integration into Chinese or Ukrainian ore supply. Expand heat-treatment capacity in Bavaria to reduce geographic single-point vulnerability. Certification investment for EU MDR compliance functions as the defensive priority lever against extended timelines compressing product refresh rates. For New Entrants and Emerging Players: E-commerce platforms serving tier-2 Indian dental clinics offer the lowest customer acquisition cost route into whitespace markets. Portable obturation systems for underpenetrated tier-3 cities present immediate addressable demand. Single-use file kit subscription models bypass capital equipment barriers for price-sensitive procurement committees. For Investors and Strategic Acquirers: Consolidation pressure builds where precision grinding capabilities cluster in Stuttgart and Munich with limited second-source alternatives. Five-to-ten year viability favors acquisition targets with proprietary heat-treatment IP and established notified body relationships. The signal to watch is nickel-titanium recycling infrastructure development as margin protection against feedstock volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Titanium Feedstock | Captive sponge supply insulates Dentsply Sirona and Danaher from titanium price volatility compressing file margins. |
| EU MDR Certification Pathway Acceleration | German notified body relationships compress certification timelines for reusable instrument portfolios against compliance overhead. |
| Dental Service Organization Partnership | Direct contracts with Florida and Texas group practices displace distributor markups and lock in volume commitments. |
| Single-Use File Kit Development | Disposable economics align with Indian tier-2 clinic procurement constraints and reduce sterilization protocol fragmentation. |
| Ultrasonic-Laser Convergence Platform | Integrated canal disinfection systems capture premium positioning in German academic hospital validation channels. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged endodontic instrument product managers, dental clinic procurement directors, GPO contracts managers, and biomedical engineers at academic hospitals. Secondary validation drew from FDA 510(k) filings, ISO 3630-1 technical standards, EU MDR notified body databases, and German statutory insurance reimbursement schedules. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segment-weighting applied technology tier, end-user archetype, and treatment complexity dimensions throughout the modeling period. CAGRs derived from replacement cycle compression rates for heat-treated nickel-titanium files and expansion trajectories for ultrasonic activation platforms. Forecast inputs incorporated dental clinic consolidation velocity in the United States and PLI scheme uptake for Indian domestic manufacturing.
Regulatory timeline slippage, titanium sponge supply disruption, and reimbursement framework revision are the dominant revision risks to projection accuracy. Forecasts reflect base-case assumptions regarding EU MDR enforcement consistency and nickel-titanium alloy innovation cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Photomedicine Technology Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Biliary Catheters Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Otoscope Devices Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Blood Thawing System Market
Medical Devices
Medical Manifolds Market
Medical Devices
Global Liposuction Surgery Devices Market