
 Global Lichen Nitidus Treatment Market | 2026-2036
Global Lichen Nitidus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lichen Nitidus Treatment Market Foresight
Dermatology clinic demand is shifting toward combination therapy protocols for refractory lichen nitidus cases. Pfizer leverages its immunology pipeline breadth to compete across systemic and biologic modalities. AbbVie anchors its position through R&D intensity in T-cell mediated skin disease pathways. Novartis differentiates via phototherapy device partnerships with specialized skin centers in North America and Western Europe.
Lichen nitidus treatment encompasses pharmacological and device-based interventions targeting asymptomatic papular eruptions, with topical corticosteroids and calcineurin inhibitors serving as first-line anti-inflammatory agents that modulate local immune responses. Phototherapy devices utilizing narrowband UVB deliver targeted immunosuppression for recalcitrant presentations across outpatient facilities. Topical corticosteroids occupy the largest revenue share due to established prescribing habits and formulary inclusion, while calcineurin inhibitors represent the fastest-expanding category as steroid-sparing protocols gain traction in pediatric and facial applications. Systemic agents concentrate margin pools where biologic eligibility criteria restrict competition.
The FDA regulates topical corticosteroid potency classifications and labeling requirements that directly influence prescribing patterns in dermatology clinics. The EMA's MDR framework demands enhanced clinical evidence for phototherapy devices, elevating compliance costs for manufacturers seeking CE marking access. Japan's PMDA maintains distinct pharmacovigilance reporting thresholds for rare skin disease therapies. Stakeholders must monitor evolving reimbursement criteria for combination therapy protocols across national health technology assessment bodies.
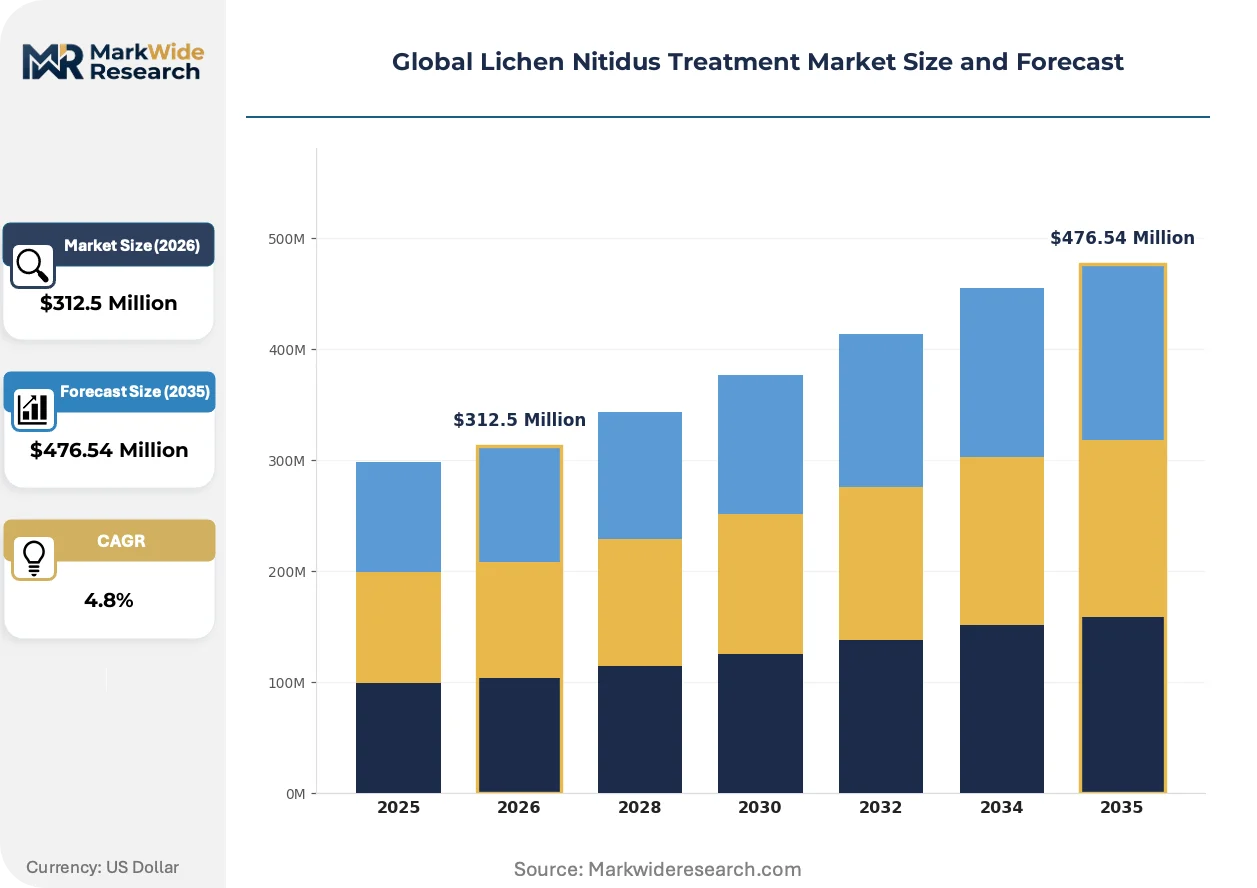
Market Dynamics
The EU MDR's tightened clinical evidence requirements are forcing phototherapy device manufacturers to rebuild technical documentation portfolios, compressing margins for mid-tier suppliers while elevating compliance costs across European distribution channels.
Growth Catalysts
- FDA orphan drug incentives:The program accelerates development timelines for rare dermatologic conditions, attracting biologic sponsors into previously neglected autoimmune skin disease pathways.
- Pediatric dermatology expansion:Specialized clinics in Germany and Japan are building dedicated service lines for papular eruption disorders, creating pull-through demand for steroid-sparing protocols.
- Narrowband UVB device miniaturization:Portable phototherapy units are enabling home-based treatment adherence, extending therapy access beyond traditional outpatient facility constraints.
Market Restraints
- High-purity excipient cost volatility:Supply chain disruptions for pharmaceutical-grade hydrocarbon bases are squeezing topical corticosteroid formulation economics.
- Phototherapy device supply concentration:Three German and Dutch OEMs control critical lamp assembly capacity, creating single-source vulnerability for CE-marked equipment.
- Biologic eligibility restriction:Narrow payer criteria for systemic immunomodulators limit addressable populations to refractory cases with documented failure on two prior drug classes.
Strategic Opportunities
- India's underserved dermatology infrastructure:Tier-2 and tier-3 cities lack specialized autoimmune skin disease diagnosis capacity, creating first-mover advantage for telemedicine-integrated topical therapy distribution.
- Calcineurin inhibitor pediatric facial applications:Regulatory acceptance of tacrolimus and pimecrolimus for sensitive anatomical zones is expanding addressable case mix beyond traditional steroid-responsive presentations.
- Combination therapy protocol reimbursement:Germany's G-BA and Japan's Chuikyo are evaluating bundled payment models for sequential topical-phototherapy interventions.
Industry Challenges
- Phototherapy technician certification bottlenecks:EU MDR Annex XIV training requirements are extending staff onboarding timelines by four to six months in outpatient dermatology settings.
- Legacy electronic health record integration:Specialized lesion documentation modules for papular eruption tracking remain incompatible with dominant hospital information system architectures in North American academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lichen Nitidus Treatment Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Corticosteroids, Calcineurin Inhibitors, Antihistamines, Phototherapy, Systemic Agents Therapy Area: Dermatology, Autoimmune Disorders, Inflammatory Conditions, Allergic Reactions, Rare Skin Diseases End User: Dermatology Clinics, Specialized Skin Centers, Outpatient Facilities, Research Institutes, Private Practices Delivery Mode: Topical Application, Oral Administration, Injectable Solutions, Phototherapy Devices, Combination Therapy |
| Companies Covered | Merck & Co., GlaxoSmithKline, Pfizer, AbbVie, AstraZeneca, Novartis, Sanofi, Amgen, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lichen Nitidus Treatment Market Shifts & Advancements
Phototherapy device connectivity and topical formulation advances are converging to reshape how refractory lichen nitidus cases are managed across ambulatory care settings.
Home-use narrowband UVB systems with integrated dose-tracking sensors are decentralizing treatment delivery from hospital-based phototherapy suites to patient-controlled environments. Dermatology clinics in the United States and Germany are piloting remote monitoring protocols that transmit treatment adherence data to centralized care teams. This shift is compressing capital expenditure requirements for outpatient facilities while expanding geographic reach into rural and underserved catchment areas.
The EU MDR's post-market surveillance obligations are mandating systematic clinical follow-up for CE-marked phototherapy equipment, forcing manufacturers to establish patient registries or risk Notified Body suspension. Device sponsors must now collect real-world evidence on treatment outcomes across diverse skin phototypes. This regulatory architecture disproportionately burdens smaller OEMs lacking dedicated pharmacovigilance infrastructure, accelerating consolidation toward vertically integrated dermatology device conglomerates.
Patients with facial and intertriginous lichen nitidus presentations are increasingly rejecting high-potency topical corticosteroids due to atrophy risk awareness propagated through dermatology social media channels. This preference compression is redirecting prescribing patterns toward calcineurin inhibitors and off-label topical JAK inhibitors in United States and Japanese outpatient settings. Payer formularies have not fully adapted to this behavioral shift, creating prior authorization friction that delays therapy initiation by two to three weeks in managed care populations.
Global Lichen Nitidus Treatment Market Segmentation
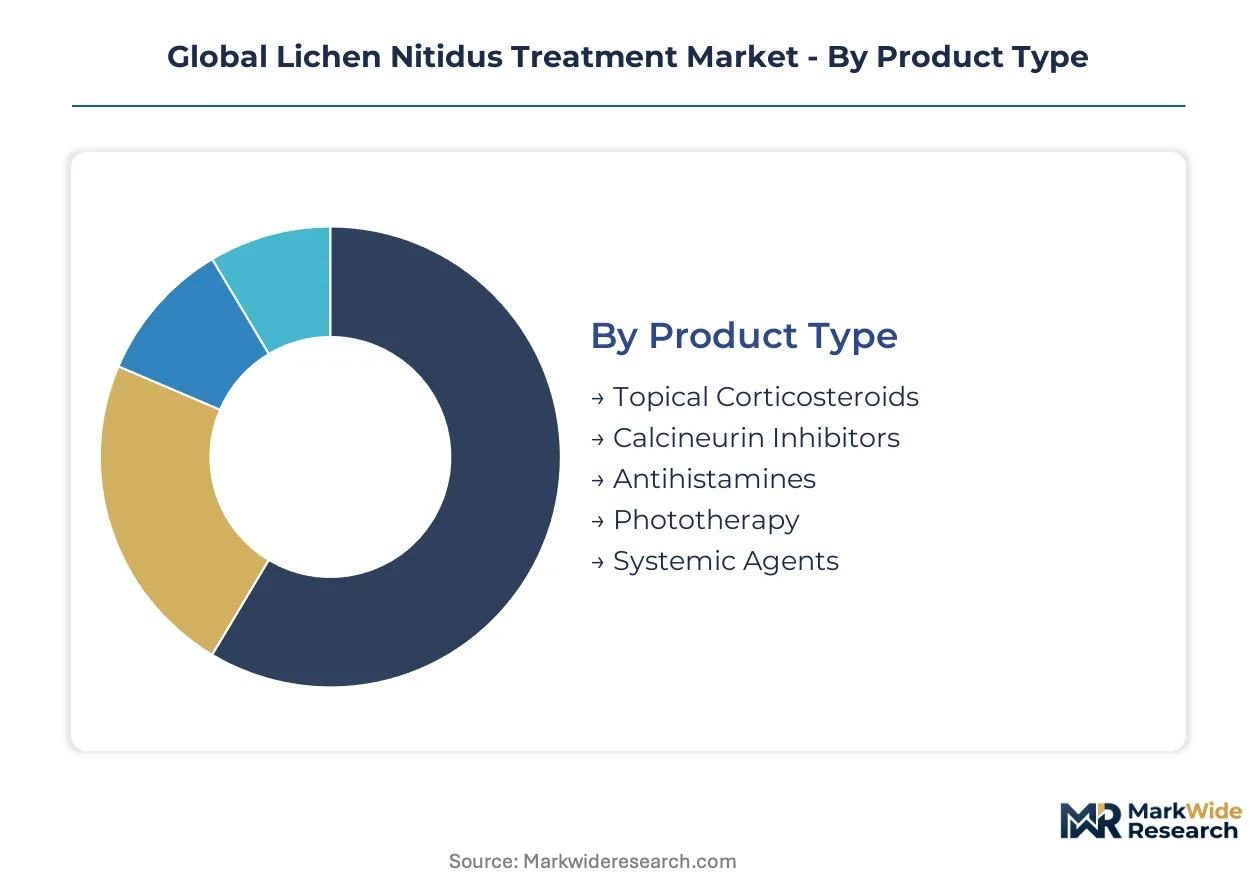
Treatment modality selection for lichen nitidus follows distinct clinical pathways shaped by lesion distribution, patient age, and anatomical sensitivity. Segmentation reveals how supply concentration in phototherapy device manufacturing and calcineurin inhibitor formulation creates divergent margin structures across therapeutic categories.
Product Type:
Supply concentration in active pharmaceutical ingredient synthesis and phototherapy lamp assembly dictates competitive intensity across therapeutic categories.
- Topical Corticosteroids:Hydrocortisone, triamcinolone, and clobetasol formulations modulate local immune responses through glucocorticoid receptor agonism. Dermatology clinics in the United States and Germany prescribe these agents for trunk and extremity lesions, though atrophy risk limits facial application. High-purity excipient supply volatility from European hydrocarbon base manufacturers is compressing formulation economics.
- Calcineurin Inhibitors:Tacrolimus and pimecrolimus ointments provide steroid-sparing immunosuppression via calcineurin-NFAT pathway inhibition. Pediatric dermatology expansion in Japan and Germany is accelerating demand for facial and intertriginous applications where corticosteroid atrophy is unacceptable. Payer formulary adaptation lags behind prescriber preference shifts.
- Antihistamines:Oral and topical formulations target pruritus modulation in symptomatic presentations.
- Phototherapy:Narrowband UVB devices deliver targeted immunosuppression through T-cell apoptosis induction.
- Systemic Agents:Biologic and small-molecule immunomodulators address refractory cases failing topical protocols.
Topical corticosteroids absorb the bulk of installed capacity; calcineurin inhibitors are expanding most quickly.
Therapy Area:
Reimbursement coding alignment with disease classification systems determines addressable revenue pools across therapeutic indications.
- Dermatology:General dermatology practices manage uncomplicated papular eruptions through first-line topical protocols. Outpatient facilities in the United States leverage established evaluation and management coding for lesion-directed therapy. Narrow payer criteria for advanced modalities restrict escalation pathways.
- Autoimmune Disorders:T-cell mediated pathway research is repositioning lichen nitidus within broader autoimmune skin disease frameworks. Specialized skin centers in Germany are building cross-referral networks with rheumatology departments. This diagnostic recoding is expanding biologic eligibility review pools.
- Inflammatory Conditions:Anti-inflammatory mechanism targeting aligns with broader dermatitis management protocols.
- Allergic Reactions:Histamine-mediated symptom control addresses pruritic subpopulations.
- Rare Skin Diseases:Orphan drug incentive qualification is attracting biologic sponsors into previously neglected indications.
Dermatology captures the dominant share of procedure volume; autoimmune disorder recoding is climbing the fastest.
End User:
Capital intensity and technical certification requirements fragment service delivery across facility types.
- Dermatology Clinics:Dedicated autoimmune skin disease service lines in the United States and Japan concentrate advanced therapy prescription authority. EU MDR Annex XIV phototherapy technician certification requirements are extending staff onboarding timelines. This regulatory burden favors larger clinic networks with dedicated training infrastructure.
- Specialized Skin Centers:Academic medical center-affiliated facilities in Germany and Japan pilot combination therapy protocols and remote phototherapy monitoring. Research integration enables early access to device miniaturization trials. Bundled payment evaluation by Germany's G-BA is reshaping referral patterns.
- Outpatient Facilities:Community-based settings provide first-line topical therapy access.
- Research Institutes:Clinical trial execution and real-world evidence generation support regulatory submissions.
- Private Practices:Solo and small-group dermatology practices dominate initial diagnosis volume.
Dermatology clinics command the largest share of advanced therapy delivery; specialized skin centers are gaining share fastest.
Delivery Mode:
Patient adherence economics and reimbursement bundling are reshaping modality selection across care settings.
- Topical Application:Patient-controlled administration of corticosteroid and calcineurin inhibitor formulations minimizes facility dependency. Social media-propagated atrophy risk awareness in the United States and Japan is redirecting preference toward steroid-sparing options. Prior authorization friction delays therapy initiation in managed care populations.
- Oral Administration:Systemic antihistamine and immunomodulator delivery addresses widespread or refractory disease.
- Injectable Solutions:Biologic administration requires specialized infusion infrastructure.
- Phototherapy Devices:Home-use narrowband UVB miniaturization is decentralizing treatment from hospital-based suites. Portable units with dose-tracking sensors enable rural and underserved catchment area access. EU MDR post-market surveillance obligations mandate systematic clinical follow-up, elevating compliance costs.
- Combination Therapy:Sequential topical-phototherapy protocols are undergoing reimbursement evaluation by Germany's G-BA and Japan's Chuikyo.
Topical application retains the dominant patient volume; combination therapy is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for biomedical innovation in Singapore and Massachusetts are concentrating phototherapy device R&D and dermatology clinical trial infrastructure, redirecting investment flows toward Asia-Pacific and North American hubs.
United States
Academic medical centers in Boston and Philadelphia are expanding dedicated autoimmune skin disease service lines, creating pull-through demand for biologic eligibility reviews. FDA orphan drug incentives accelerate development timelines for rare dermatologic conditions. Dermatology clinics in California and Texas are piloting remote phototherapy monitoring protocols that transmit adherence data to centralized care teams.
Germany
Specialized skin centers in Munich and Heidelberg are building cross-referral networks with rheumatology departments, repositioning lichen nitidus within broader autoimmune frameworks. The EU MDR's tightened clinical evidence requirements are elevating compliance costs for phototherapy device manufacturers seeking CE marking. G-BA bundled payment evaluation for combination therapy protocols is reshaping referral patterns across Baden-Württemberg and North Rhine-Westphalia.
Japan
Pediatric dermatology expansion in Tokyo and Osaka is accelerating demand for steroid-sparing calcineurin inhibitor protocols in facial applications. PMDA maintains distinct pharmacovigilance reporting thresholds for rare skin disease therapies. Chuikyo reimbursement evaluation for sequential topical-phototherapy interventions is creating pricing pressure on device manufacturers in the Kansai region.
India
Tier-2 and tier-3 cities lack specialized autoimmune skin disease diagnosis capacity, creating first-mover advantage for telemedicine-integrated topical therapy distribution. The country's national pharmaceutical regulator emphasizes local clinical trial data for imported dermatology products. Mumbai and Bangalore are emerging as hubs for generic topical corticosteroid formulation manufacturing serving domestic and export markets.
United Kingdom
NHS England specialized commissioning frameworks are narrowing biologic eligibility criteria to refractory cases with documented failure on two prior drug classes. The MHRA's post-Brexit regulatory autonomy is diverging from EU MDR timelines for phototherapy device approvals. London and Manchester dermatology networks are consolidating procurement for narrowband UVB equipment to extract volume discounts from concentrated German and Dutch OEM suppliers.
Global Lichen Nitidus Treatment Market Competitive Landscape
Top-tier vendors anchor the biologic and systemic immunomodulator segments, while mid-tier specialists concentrate topical formulation and phototherapy device manufacturing. Market structure reflects pharmaceutical conglomerate dominance in high-margin systemic agents alongside fragmented dermatology device fabrication. Three strategic archetypes emerge: vertically integrated immunology pipeline operators, steroid-sparing topical formulation specialists, and phototherapy equipment OEMs with CE-marking expertise. Competitive moves center on M&A for autoimmune skin disease pathway assets and strategic partnerships for home-use device miniaturization.
Among US-based pharmaceutical conglomerates, Pfizer, AbbVie, and Novartis occupy positions that exemplify distinct competitive vectors. Pfizer represents the immunology pipeline breadth archetype, leveraging cross-modal capabilities across systemic and biologic treatment categories. AbbVie anchors the T-cell mediated pathway research specialization, with R&D intensity concentrated on skin disease mechanisms. Novartis exemplifies the device-pharmaceutical partnership model, with strategic positioning in phototherapy distribution networks across North American and Western European specialized skin centers.
| Leading Market Players |
|---|
| Merck & Co. |
| GlaxoSmithKline |
| Pfizer |
| AbbVie |
| AstraZeneca |
| Novartis |
| Sanofi |
| Amgen |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
European hydrocarbon base index volatility cascades through topical corticosteroid formulation economics, compressing margins for mid-tier manufacturers while concentrating pricing power among vertically integrated pharmaceutical conglomerates with captive excipient supply.
Pricing Analysis
Short lead-time premiums command pricing separation in phototherapy device procurement, with German and Dutch OEMs extracting margin advantages from hospital systems facing EU MDR compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking tier and bundled service intensity. Pricing pressure stems from G-BA bundled payment evaluation for combination protocols, compressing device reimbursement ceilings. Academic medical centers exhibit lowest price sensitivity due to research integration requirements, while community outpatient facilities in India and tier-2 United States markets prioritize spot inventory discounts.
Supply Chain Analysis
Reverse-logistics flows for phototherapy lamp refurbishment concentrate in German OEM facilities, extending equipment lifecycle economics for specialized skin centers. Active pharmaceutical ingredient synthesis for calcineurin inhibitors centers on India and Switzerland, with high-purity hydrocarbon bases drawing from German and Belgian petrochemical complexes. Single-source vulnerability pervades narrowband UVB lamp assembly, where three Dutch and German manufacturers control critical capacity. Distribution runs through dermatology GPOs in North America and hospital procurement consortia in Germany, with regulatory documentation burden favoring larger clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lichen Nitidus Treatment Market operates as a cost-of-compliance story, where EU MDR post-market surveillance obligations erect barrier-to-entry moats that favor incumbent device manufacturers with dedicated pharmacovigilance infrastructure.
For Market Incumbents: Lock in phototherapy technician certification pipelines through exclusive training partnerships with German dermatology networks, insulating against EU MDR Annex XIV onboarding bottlenecks. Deepen backward integration into high-purity hydrocarbon base supply through offtake agreements with Belgian petrochemical producers, defending formulation margin against excipient cost volatility. Prioritize calcineurin inhibitor pediatric facial indication expansion to capture prescriber preference shifts away from corticosteroid atrophy risk. For New Entrants and Emerging Players: Home-use narrowband UVB connectivity platforms offer the most penetrable wedge, targeting rural United States catchment areas and tier-2 Indian cities lacking specialized dermatology infrastructure. Telemedicine-integrated topical therapy distribution in underserved Japanese prefectures presents adjacent white-space, with Chuikyo reimbursement evaluation creating favorable policy tailwinds. Pursue strategic device partnerships with academic medical center phototherapy suites to generate real-world evidence for regulatory submissions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier topical formulation specialists in India facing CDSCO local clinical trial data requirements, where Mumbai and Bangalore manufacturing assets trade at compressed multiples. Long-term viability hinges on autoimmune skin disease diagnostic recoding expanding biologic eligibility review pools. Monitor FDA orphan drug incentive program participation rates as inflection indicator for pipeline prioritization shifts among immunology conglomerates.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Rebuild | Phototherapy device manufacturers must reconstruct clinical evidence portfolios to retain CE marking access across European distribution channels. |
| Pediatric Facial Indication Expansion | Regulatory acceptance of tacrolimus and pimecrolimus for sensitive anatomical zones broadens addressable case mix beyond traditional steroid-responsive presentations. |
| Home-Use Device Miniaturization | Portable narrowband UVB units with dose-tracking sensors enable patient-controlled treatment adherence beyond hospital-based phototherapy suite constraints. |
| Telemedicine-Integrated Distribution | Remote monitoring protocols transmit treatment adherence data to centralized care teams, extending geographic reach into underserved catchment areas. |
| Combination Therapy Reimbursement Strategy | Germany's G-BA and Japan's Chuikyo bundled payment evaluation reshapes referral patterns toward sequential topical-phototherapy protocols. |
Research Methodology
Independent corroboration across dermatology clinic procurement managers, pharmaceutical regulatory affairs leads, phototherapy device biomedical engineers, and payer access specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EMA MDR technical documentation databases, ClinicalTrials.gov intervention records, and Germany's G-BA benefit assessment archives. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored segmentation-level estimates.
Rate-of-change decomposition across treatment modality adoption curves, reimbursement policy evolution timelines, and regulatory compliance cost trajectories structured the analytical framework. Segmentation dimensions encompassed product type, therapy area classification, end-user facility tier, and delivery mode complexity. CAGRs derived from fitted adoption curves and elasticity-adjusted price trajectory assumptions, with inputs including EU MDR implementation phase transitions and pediatric dermatology service line expansion rates across German and Japanese academic medical centers.
Several conditions sit outside the modeled scope, including novel biologic mechanism approvals outside T-cell mediated pathways and disruptive phototherapy technology platforms bypassing narrowband UVB wavelengths. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory timeline adherence. Practitioners should monitor FDA orphan drug designation velocity, EU MDR Notified Body suspension events, and Chuikyo pricing resolution outcomes for early signals of trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market