
 Dental Caries and Endodontic Market | 2026-2036
Dental Caries and Endodontic Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Caries and Endodontic Market Analysis
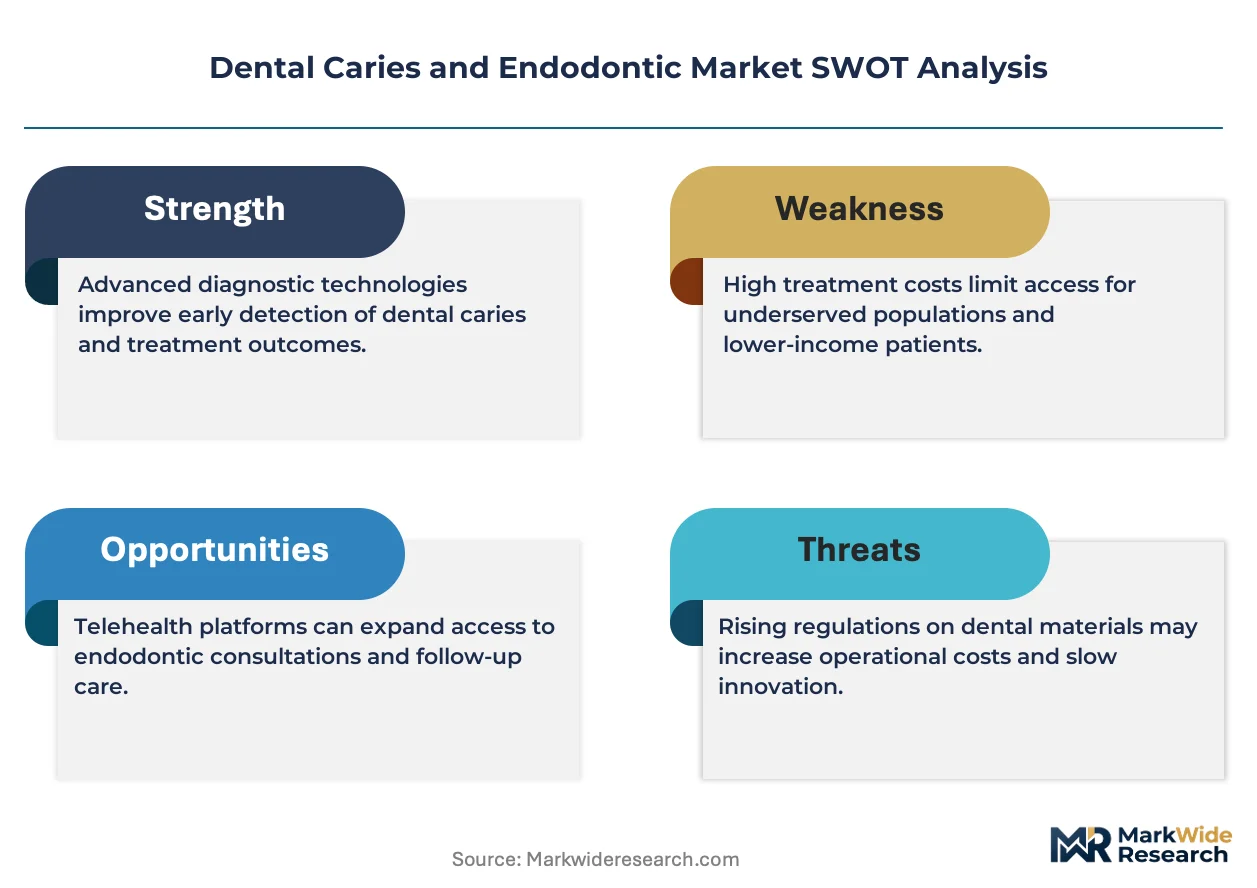
Bioceramic sealer specifications are reorganizing competitive dynamics across endodontic supply chains. Dentsply Sirona leverages integrated manufacturing scale across rotary file and obturation systems. Henry Schein anchors distribution control through direct clinic procurement platforms in North America. Envista differentiates via specialized endodontic imaging and navigation technologies.
Dental caries and endodontics encompasses the diagnosis, prevention, and treatment of tooth decay and pulp disease, employing materials such as mineral trioxide aggregate with sealing ability below 1 millipascal and nickel-titanium rotary instruments with controlled memory alloys for canal shaping. The primary commercial purpose centers on preserving natural dentition while preventing periapical pathology. Composite resin materials lead product type revenue pools due to aesthetic demand and direct restoration volume, while root canal procedures concentrate margin capture through file system disposables and obturation consumables. Glass ionomer occupies a stable niche in pediatric and geriatric applications where moisture tolerance outweighs cosmetic requirements.
FDA 510(k) pathways for endodontic devices intersect with EPA amalgam disposal rules and EU MDR biocompatibility testing expansion under CE marking renewal deadlines. These frameworks elevate compliance costs for sealant and filling manufacturers while creating barriers for uncertified market entrants. Stakeholders must monitor reimbursement code revisions from CMS and analogous national health authorities, as procedure classification shifts directly alter clinician adoption rates for preventive versus surgical interventions.
Market Dynamics
Bioceramic sealer chemistry is compressing obturation timelines while elevating biocompatibility thresholds, forcing manufacturers to reconfigure R&D pipelines and quality assurance protocols around mineral trioxide aggregate specifications.
Growth Catalysts
- Minimally Invasive Techniques:Rotary nickel-titanium systems with controlled memory alloys are replacing manual filing in dental clinics across the United States and Germany, accelerating procedure throughput and patient acceptance.
- EMA Biocompatibility Standards:Tightened CE marking renewal deadlines under EU MDR are filtering out uncertified sealant manufacturers, concentrating procurement among validated suppliers in European dental networks.
- Preventive Reimbursement Frameworks:Japan's national health insurance expansion for early caries intervention is redirecting patient flow from surgical extraction toward pulp-preserving endodontic procedures.
Market Restraints
- EPA Amalgam Disposal Compliance:Separator installation mandates and waste handling protocols are elevating fixed costs for US dental practices still utilizing silver amalgam restorations.
- Raw Material Concentration:High-purity zirconia and yttria supply chains concentrate among Chinese refractory producers, exposing sealer manufacturers to input volatility and export licensing friction.
- Bioceramic Setting Sensitivity:Moisture-controlled application requirements limit chairside adoption in high-humidity climates and resource-constrained clinic environments.
Strategic Opportunities
- India Preventive Expansion:CDSCO streamlined 510(k)-equivalent pathways for endodontic devices coincide with rising private dental clinic density in Mumbai and Bangalore corridors.
- Pediatric Glass Ionomer Positioning:Moisture-tolerant formulations for primary dentition represent an underserved segment where fluoride release properties outweigh aesthetic limitations.
- Direct Clinic Procurement Platforms:North American distributors are consolidating purchasing power through integrated inventory management systems that bypass traditional dental dealer networks.
Industry Challenges
- Endodontic Microscopy Training Gap:Surgical microscope proficiency requirements for complex canal anatomy exceed current residency curriculum coverage, constraining specialist supply.
- FDA 510(k) Documentation Burden:Predicate device substantiation for novel file geometries demands extended clinical validation timelines, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Caries and Endodontic Market |
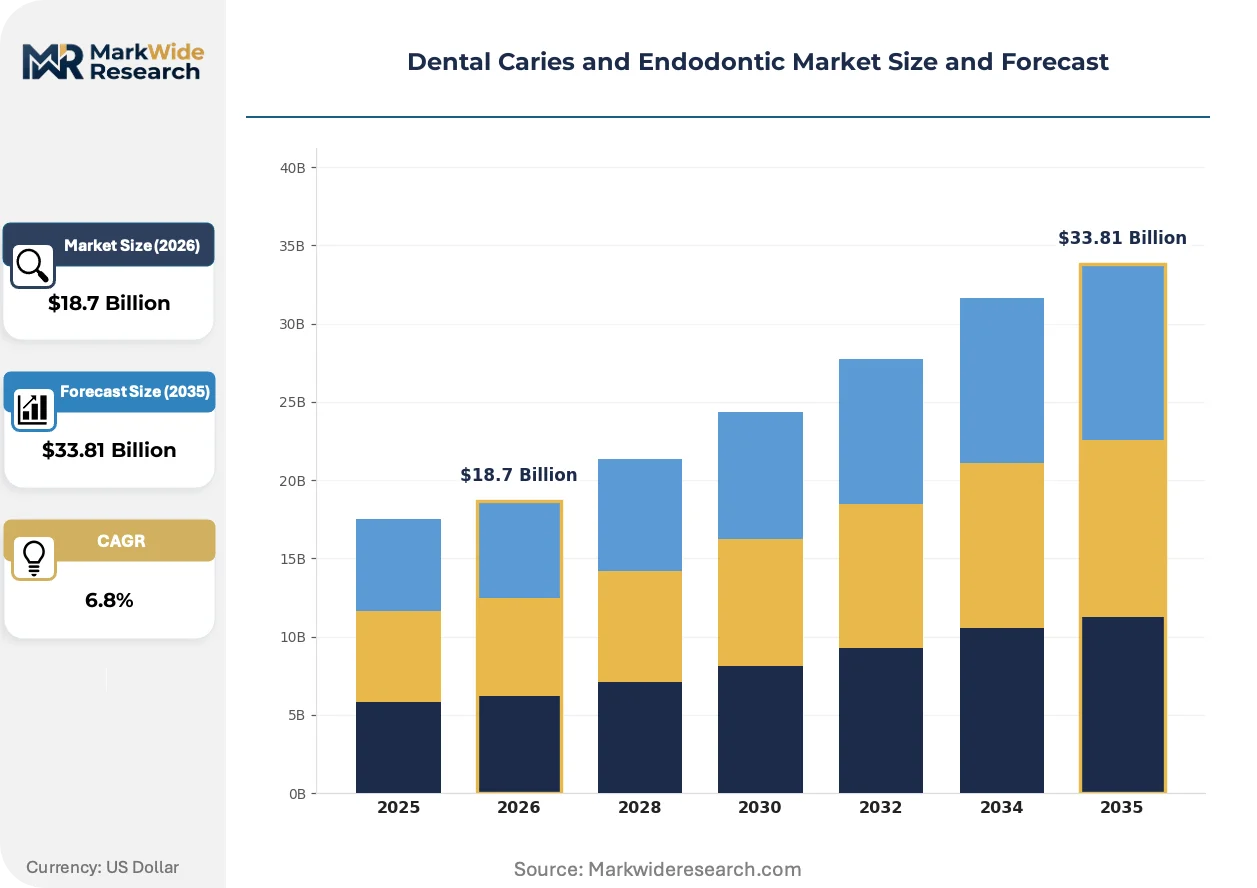
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillings, Crowns, Root Canals, Sealants End User: Dentists, Dental Clinics, Hospitals, Research Institutions Procedure Type: Orthodontics, Periodontics, Conservative Dentistry, Prosthodontics Material: Composite Resin, Amalgam, Glass Ionomer, Ceramics |
| Companies Covered | Dentsply Sirona, Henry Schein, Envista, Colgate-Palmolive, Coltene Group, Septodont Holding, Ultradent Products, Ivoclar Vivadent, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Caries and Endodontic Market Emerging Trajectories
Digital navigation systems and advanced imaging modalities are compressing the diagnostic-to-treatment interval while elevating precision thresholds for canal negotiation and periapical assessment.
WaveOne Gold and similar single-file reciprocating systems are miniaturizing mechanical footprint while maintaining cutting efficiency. General practitioners in suburban US markets are adopting these systems at twice the rate of multi-file sequences, compressing inventory requirements and sterilization cycles while enabling same-visit completion rates that reshape clinic scheduling economics.
EU MDR biocompatibility testing expansion is elevating documentation requirements for obturation materials seeking CE marking renewal. Manufacturers must now submit extended cytotoxicity and sensitization data, compressing margins for mid-tier sealant producers while creating compliance moats for established bioceramic specialists serving German and French dental networks.
Consolidated buying groups are displacing individual practice procurement across North American metropolitan corridors. Dental service organizations in Texas and Florida markets now negotiate enterprise pricing for file systems and obturation consumables, compressing distributor margins while shifting volume toward direct manufacturer relationships that bypass traditional dealer infrastructure.
Dental Caries and Endodontic Market Segmentation
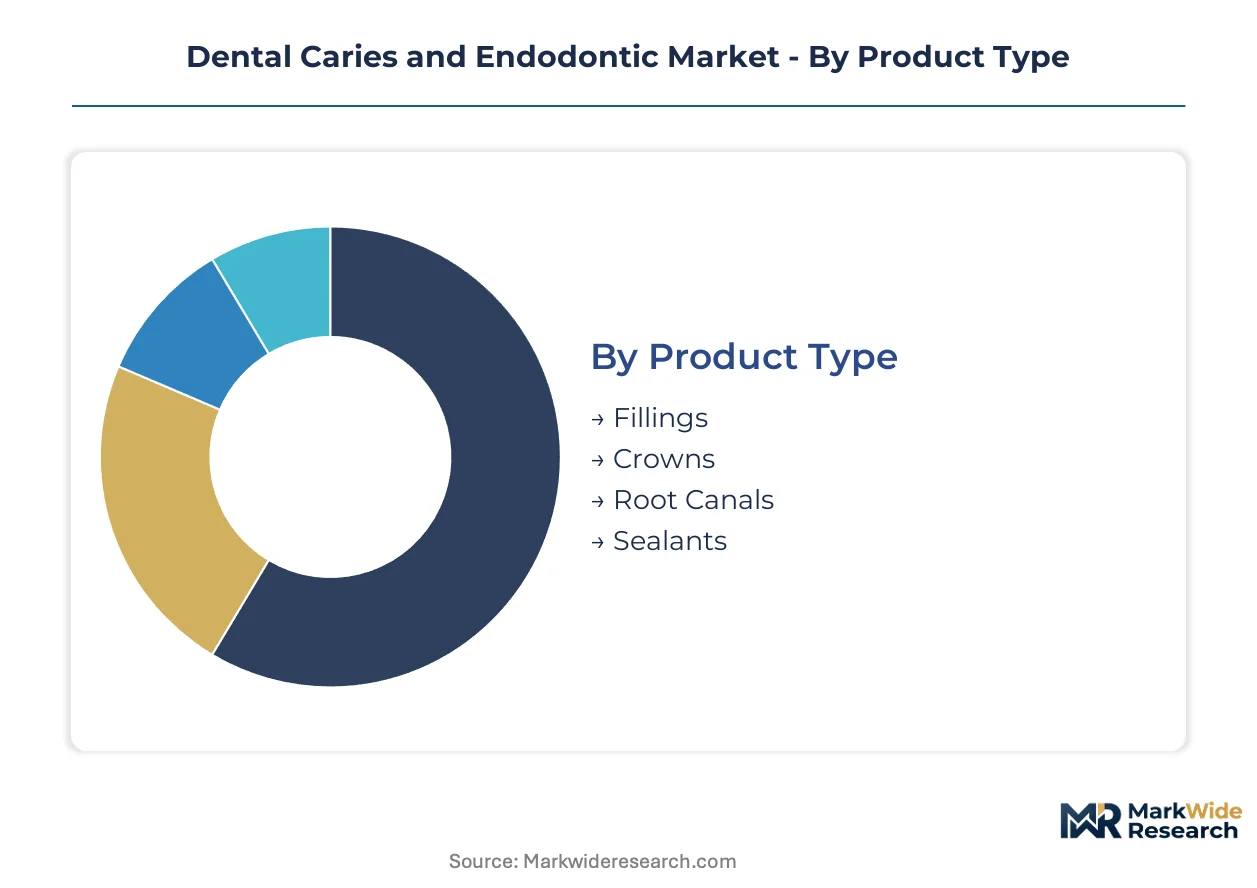
Segmentation in dental caries and endodontics reveals how regulatory pathways, reimbursement codes, and clinical workflows fragment procurement patterns across materials and settings. Understanding these divisions exposes where margin concentrates and where volume shifts threaten incumbent positioning.
Product Type:
FDA 510(k) clearance timelines and EPA amalgam disposal rules create divergent compliance burdens across restorative categories, reshaping manufacturer R&D prioritization and clinic inventory decisions.
- Fillings:Direct restorations employing composite resin or amalgam dominate procedure volume in United States and German dental networks. CMS reimbursement codes for preventive resin restoration favor adhesive systems over traditional cavity preparation, redirecting clinician preference toward minimal intervention techniques.
- Root Canals:Endodontic therapy utilizing nickel-titanium rotary instruments and bioceramic sealers commands premium pricing through file system disposables. Japanese national health insurance expansion for pulp-preserving procedures is accelerating adoption of single-visit obturation protocols in Tokyo and Osaka clinic clusters.
- Crowns:Indirect restorations fabricated via CAD/CAM milling or sintered zirconia occupy the prosthodontic tier where laboratory outsourcing competes with chairside production.
- Sealants:Pit-and-fissure applications in pediatric dentistry leverage moisture-tolerant glass ionomer chemistry where fluoride release properties satisfy caries prevention protocols.
Established volume favors fillings; emerging adoption favors root canals.
End User:
Procurement scale and regulatory exposure concentrate differently across practice types, with dental service organizations extracting enterprise pricing that individual practitioners cannot match.
- Dentists:Solo and small-group practitioners in suburban United States markets drive demand for single-file reciprocating systems that compress inventory and sterilization overhead. Direct clinic procurement platforms are displacing traditional dealer relationships in Texas and Florida metropolitan corridors.
- Dental Clinics:Multi-chair facilities in Mumbai and Bangalore benefit from CDSCO streamlined pathways for endodontic device registration. Consolidated buying groups negotiate manufacturer-direct contracts that bypass distributor markups.
- Hospitals:Academic medical centers in Germany and France anchor training demand for surgical microscopy and digital navigation systems.
- Research Institutions:University-based dental schools in Japan and the United States validate novel bioceramic formulations through extended cytotoxicity protocols.
Volume concentrates in dental clinics; margin capture concentrates in hospital-affiliated specialist networks.
Procedure Type:
Reimbursement classification and residency curriculum coverage determine where specialist supply constrains market expansion versus where general practitioner adoption accelerates.
- Conservative Dentistry:Caries removal and direct restoration procedures generate the highest procedure frequency across German and Japanese reimbursement frameworks. EU MDR biocompatibility testing expansion for filling materials elevates documentation requirements for manufacturers seeking CE marking renewal.
- Prosthodontics:Crown, bridge, and implant restoration workflows integrate CAD/CAM and 3D printing technologies where digital impression systems compress laboratory turnaround.
- Orthodontics:Tooth movement therapies occupy adjacent demand where clear aligner manufacturing scales separately from endodontic supply chains.
- Periodontics:Gingival and supporting tissue procedures overlap with caries prevention in comprehensive care protocols.
Procedure frequency peaks in conservative dentistry; technology integration advances fastest in prosthodontics.
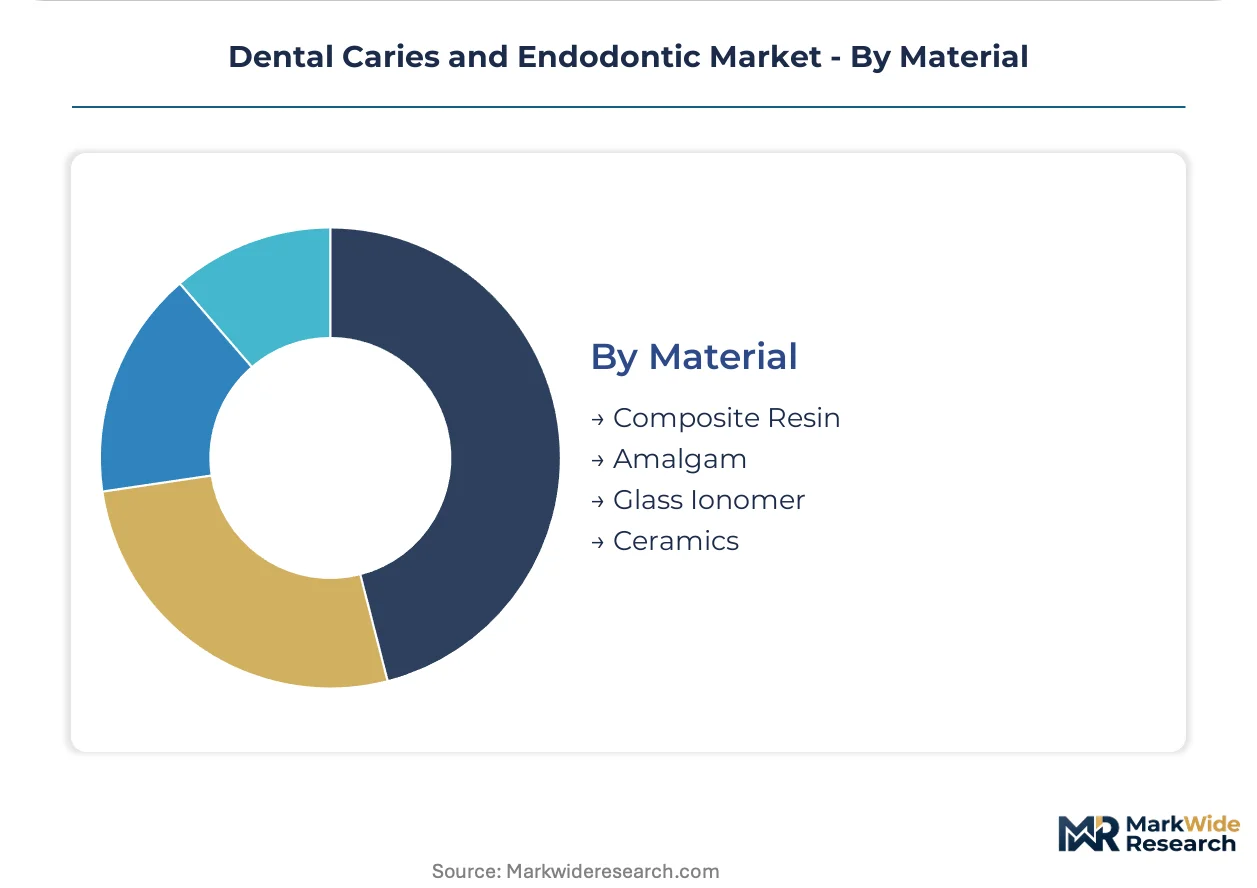
Material:
Raw material concentration and biocompatibility certification tiers stratify pricing power across restorative chemistry families.
- Composite Resin:Methacrylate-based formulations with nanofiller loading dominate aesthetic restoration demand in United States and German private practice. EPA amalgam disposal compliance costs are redirecting residual demand toward resin-modified glass ionomer alternatives in pediatric applications.
- Glass Ionomer:Acid-base reaction cements with fluoride release properties satisfy moisture-tolerant requirements in primary dentition and geriatric care. Formulations optimized for high-humidity climates are gaining adoption in Indian and Southeast Asian clinic environments.
- Amalgam:Silver-mercury alloys face regulatory phase-out pressure through EPA separator mandates and EU environmental restrictions.
- Ceramics:Zirconia and lithium disilicate blocks for CAD/CAM milling concentrate supply risk among Chinese refractory producers.
Revenue concentration favors composite resin; supply security concerns favor glass ionomer diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bioceramic sealers flow into French and Dutch dental networks under EU MDR harmonized standards, while Japanese manufacturers supply mineral trioxide aggregate formulations across Southeast Asian clinic corridors.
United States
CMS reimbursement code revisions favor preventive resin restorations over surgical extractions. EPA amalgam separator mandates elevate compliance costs for practices in Texas and Florida metropolitan corridors. Dental service organizations in Dallas and Miami negotiate enterprise pricing for file systems and obturation consumables.
Germany
EMA biocompatibility standards under EU MDR filter uncertified sealant manufacturers from procurement networks. CE marking renewal deadlines compress margins for mid-tier producers while validating established bioceramic specialists. Academic medical centers in Munich and Frankfurt anchor training demand for surgical microscopy systems.
Japan
METI-guided national health insurance expansion redirects patient flow toward pulp-preserving endodontic procedures. PMDA streamlined pathways accelerate device registration for mineral trioxide aggregate formulations. Tokyo and Osaka clinic clusters adopt single-visit obturation protocols at accelerating rates.
India
CDSCO streamlined 510(k)-equivalent pathways coincide with rising private dental clinic density. BIS standards for dental materials create certification tiers that stratify import competition. Mumbai and Bangalore corridors concentrate demand for moisture-tolerant glass ionomer formulations in high-humidity environments.
China
NMPA biocompatibility documentation requirements for dental materials intensify under GB standards harmonization. High-purity zirconia and yttria supply chains concentrate among domestic refractory producers. Shanghai and Shenzhen manufacturing clusters face export licensing friction for sealer raw materials.
Dental Caries and Endodontic Market Vendor Landscape
Listed leaders compete with private specialists across integrated manufacturing versus distribution control dimensions. The vendor base stratifies into three tiers: diversified dental conglomerates with full-spectrum portfolios, specialized endodontic device manufacturers with focused R&D pipelines, and regional distribution platforms with clinic procurement dominance. Strategic moves concentrate on direct clinic procurement platform expansion and bioceramic formulation patent positioning.
Within the diversified conglomerate tier, Dentsply Sirona and 3M Company exemplify integrated manufacturing scale across rotary file and obturation systems. Among specialized endodontic specialists, Envista occupies a position anchored in imaging and navigation technologies for canal negotiation. These three entities represent the dominant archetypes: manufacturing-integrated, distribution-controlled, and technology-specialized competitive positioning.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Henry Schein |
| Envista |
| Colgate-Palmolive |
| Coltene Group |
| Septodont Holding |
| Ultradent Products |
| Ivoclar Vivadent |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance tiers and EU MDR biocompatibility certifications gate both supplier qualification and price stratification across endodontic materials, compressing margin pools for uncertified manufacturers while validating premium positioning for validated bioceramic specialists serving German and Japanese clinic networks.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in rotary file and obturation systems. Price differentiation rests on CE marking tier and volume scale, with dental service organizations extracting enterprise discounts unavailable to solo practitioners. Pricing pressure stems from consolidated buying group expansion across Texas and Florida metropolitan corridors. Solo practitioners in suburban United States markets exhibit highest price sensitivity, while hospital-affiliated specialist networks absorb premium tiers for surgical microscopy integration.
Supply Chain Analysis
Strategic stockpiling of high-purity zirconia and yttria dominates over just-in-time preferences among bioceramic sealer manufacturers confronting export licensing friction. Raw material sourcing concentrates in Chinese refractory producers, South Korean precision alloy foundries, and German ceramic processing facilities. Supply chain risk centers on single-source vulnerability for nickel-titanium controlled memory alloys. Distribution runs through direct clinic procurement platforms that displace traditional dental dealer networks in North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against dental implant surgical extraction protocols that threaten pulp-preservation procedure volumes. Market positioning requires navigating reimbursement code shifts that redirect patient flow toward preventive versus surgical interventions.
For Market Incumbents: Consolidate manufacturing scale across rotary file and obturation system portfolios to match Dentsply Sirona's integrated production footprint. Deepen backward integration into nickel-titanium alloy supply through captive relationships with controlled memory alloy specialists. Prioritize bioceramic formulation patent positioning before EU MDR renewal deadlines filter mid-tier competitors from German and French procurement networks.
For New Entrants and Emerging Players: Anchor in moisture-tolerant glass ionomer formulations for pediatric and high-humidity climate applications where fluoride release properties outweigh aesthetic limitations. Target Mumbai and Bangalore clinic corridors where CDSCO streamlined pathways reduce registration barriers for endodontic device entrants. Pursue direct clinic procurement platform partnerships that bypass established dealer infrastructure in Texas and Florida dental service organization markets.
For Investors and Strategic Acquirers: EU MDR biocompatibility testing expansion reshapes the acquisition landscape by elevating compliance moats around validated bioceramic specialists. Long-term viability favors manufacturers with vertically integrated sealer chemistry and file system disposables portfolios. Monitor CMS reimbursement code revisions for preventive resin restorations as the inflection signal for procedure volume shifts between conservative dentistry and surgical extraction alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioceramic Formulation Patent Positioning | EU MDR renewal deadlines validate mineral trioxide aggregate specifications for CE marking retention. |
| Direct Clinic Procurement Platform Expansion | Henry Schein's distribution control model compresses traditional dealer margins across North American metropolitan corridors. |
| Controlled Memory Alloy Supply Integration | Backward integration into nickel-titanium sourcing mitigates single-source vulnerability for rotary instrument manufacturers. |
| Moisture-Tolerant Glass Ionomer Development | Pediatric and geriatric applications in Indian high-humidity environments represent underserved segment expansion. |
| Surgical Microscopy Training Program Investment | Academic medical centers in Munich and Frankfurt anchor specialist supply for complex canal anatomy procedures. |
Methodological Framework
The analysis maps bioceramic sealer chemistry, nickel-titanium rotary systems, and glass ionomer formulation sub-sectors, each validated through endodontic device product managers, dental clinic procurement officers, GPO contracts managers, and regulatory affairs specialists at manufacturers seeking FDA 510(k) clearance. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, CMS reimbursement code revisions, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including customs data for zirconia and yttria trade flows, dental school residency curriculum coverage for specialist supply constraints, and reimbursement code utilization rates from national health insurance databases. Segmentation modeling incorporated product type, end user, procedure category, and material chemistry dimensions throughout the forecast period. CAGRs derived from procedure frequency projections weighted by reimbursement framework shifts and technology adoption curves for single-file reciprocating systems.
Material uncertainties — regulatory timeline delays, raw material export licensing disruptions, and reimbursement code reclassification — sit outside the modeled envelope. Forecasts reflect assumptions around EU MDR renewal compliance rates and CDSCO pathway efficiency without guaranteeing execution timelines. Revision becomes warranted when CMS preventive resin restoration reimbursement thresholds cross utilization rate inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Impression Tray Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Dental Dam Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Dental Regeneration Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Electric Dental Handpieces Market