
 Bionic Devices Market | 2026-2036
Bionic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bionic Devices Market Analysis
The gap between experimental neuroprosthetics and clinically deployable systems is narrowing as microelectrode array fabrication migrates from academic clean rooms to semiconductor foundries. Medtronic plc leverages its deep brain stimulation infrastructure to anchor neural interface development across North American and European clinical trial networks. Boston Scientific Corporation competes in cardiac rhythm management while extending sensor capabilities toward closed-loop bionic control architectures. Abbott Laboratories sustains diversified R&D intensity across diabetes care and neuromodulation platforms that feed adjacent bionic device pipelines.
Bionic devices integrate electromechanical systems with biological tissue to restore or augment motor, sensory, or cognitive functions, typically employing biocompatible titanium housings, platinum-iridium electrode contacts, and hermetic sealing rated for multi-year implantation. Their primary commercial purpose centers on restoring lost physiological capability in amputees, paralyzed patients, and sensory-impaired populations while reducing lifetime healthcare costs versus conventional assistive alternatives. Prosthetic limbs retain the largest installed base and reimbursement footprint, though exoskeletons represent the fastest-expanding segment as workplace injury prevention and spinal cord rehabilitation protocols broaden addressable demand. Neural interfaces command premium margin pools due to manufacturing complexity and regulatory scarcity, while bionic eyes remain constrained by limited retinal surgeon training infrastructure and narrow payer coverage.
FDA breakthrough device designations and premarket approval pathways shape competitive timelines for US market entry, while EMA medical device regulation and notified body conformity assessments govern European commercialization. Japan's PMDA and METI coordinate reimbursement listings with technical standards that influence regional product configuration requirements. Stakeholders must monitor how FDA draft guidance on brain-computer interfaces and EU AI Act risk classifications for autonomous bionic control systems will reshape clinical evidence requirements and go-to-market economics.
Market Dynamics
Semiconductor foundries are absorbing microelectrode array fabrication from academic clean rooms, collapsing production bottlenecks that previously constrained neural interface commercialization and compressing development cycles for implantable bionic systems.
Growth Catalysts
- Veterans Affairs procurement expansion:US federal healthcare systems are mandating advanced myoelectric prosthetic coverage for wounded service members, creating guaranteed demand pools that stabilize manufacturer revenue forecasting.
- German statutory health insurance reform:Bundestag-mandated reimbursement expansion now covers myoelectric prosthetics for broader amputee populations, removing prior authorization barriers that suppressed device penetration.
- FDA breakthrough device designation:Accelerated review pathways for neural interface developers are compressing premarket approval timelines and reducing regulatory capital requirements for first-mover entrants.
Market Restraints
- Platinum-iridium electrode cost volatility:Precious metal supply concentration in South African mining operations creates input price instability that compresses gross margins on high-channel-count neural implants.
- Retinal surgeon training infrastructure scarcity:Limited fellowship programs and surgical simulation capacity constrain bionic eye deployment regardless of device availability or payer coverage expansion.
- EMA Medical Device Regulation conformity assessment backlog:Notified body capacity shortages in Germany and the Netherlands are extending European commercialization timelines for novel bionic systems.
Strategic Opportunities
- Workplace injury prevention exoskeletons:Logistics and manufacturing employers in Japan are piloting lumbar-support exoskeletons for aging workforces, opening industrial reimbursement channels beyond clinical rehabilitation.
- EU AI Act autonomous bionic control:Risk classification frameworks for closed-loop neural interfaces will create regulatory clarity that attracts institutional investment toward next-generation motor prosthetics.
- Closed-loop diabetes-bionic convergence:Continuous glucose monitoring algorithms are integrating with insulin pump actuators to create artificial pancreas systems that expand addressable populations beyond traditional amputee markets.
Industry Challenges
- Microelectrode array yield engineering:Semiconductor foundries lack process expertise for biocompatible thin-film deposition, requiring multi-year co-development partnerships that delay volume manufacturing readiness.
- Hermetic sealing certification timelines:Multi-year implantation reliability testing for titanium housing integrity extends product development cycles and defers revenue recognition.
- Cross-platform neural signal standardization:Proprietary decoding algorithms across Medtronic, Boston Scientific, and Abbott systems prevent interoperability and fragment clinician training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bionic Devices Market |
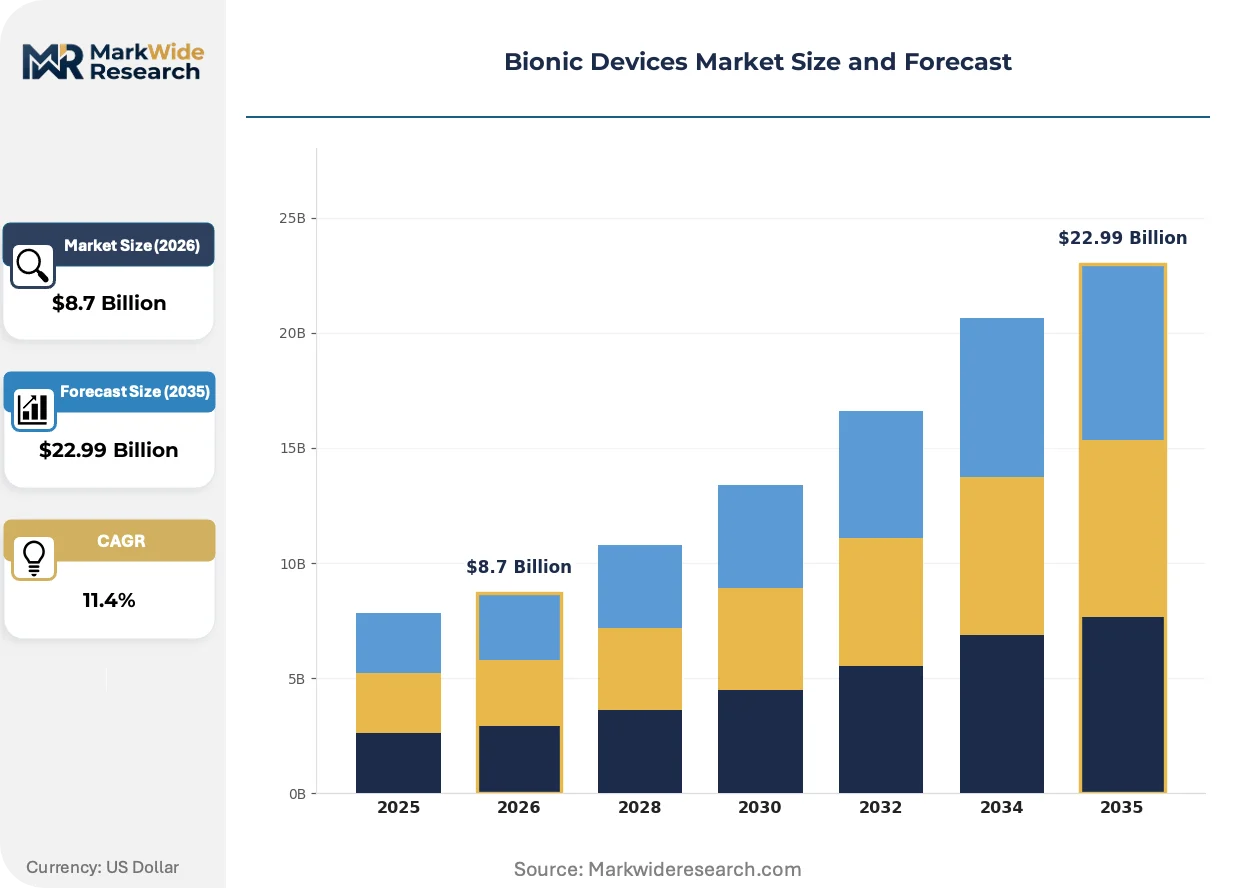
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetic Limbs, Exoskeletons, Neural Interfaces, Bionic Eyes End User: Veterans, Athletes, Amputees, Healthcare Providers Technology: Artificial Intelligence, Robotics, Biofeedback, Sensory Integration Application: Rehabilitation, Assistive Devices, Military Applications, Sports Enhancements |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Cochlear Ltd, Ekso Bionics Holdings Inc., Ossur, Sonova, Zimmer Biomet Holdings Inc., Edwards Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bionic Devices Market Emerging Trajectories
Digital twin architectures are virtualizing preclinical validation workflows, compressing development timelines while regulatory frameworks adapt to algorithmic device modifications that previously required full resubmission.
Machine learning-based neural signal decoding is virtualizing the functional mapping process that historically required months of patient calibration. Veterans Affairs rehabilitation centers are deploying these adaptive algorithms for upper-limb prosthetic control, reducing fitting sessions from twelve weeks to under four. The technology is virtualizing clinical workflow economics and expanding the addressable patient pool beyond metropolitan tertiary centers.
EMA Medical Device Regulation Annex XVI expansion is capturing active implantable devices under enhanced post-market surveillance requirements. Manufacturers must now maintain clinical evidence registries for neural interfaces across their entire commercial lifecycle, not just premarket phases. European notified bodies in Germany and Ireland are prioritizing audit capacity for bionic eye and cochlear implant categories, delaying neuroprosthetic submissions by six to nine months.
Hospital procurement departments are unbundling device acquisition from surgical training and long-term rehabilitation services. German statutory health insurance funds now reimburse myoelectric prosthetics through separate technical and therapeutic budget lines, enabling specialized orthotic clinics to compete with academic medical centers. This purchasing fragmentation is most visible in Bavaria and Baden-Württemberg, where regional device consortia aggregate demand across multiple payer networks.
Bionic Devices Market Segmentation
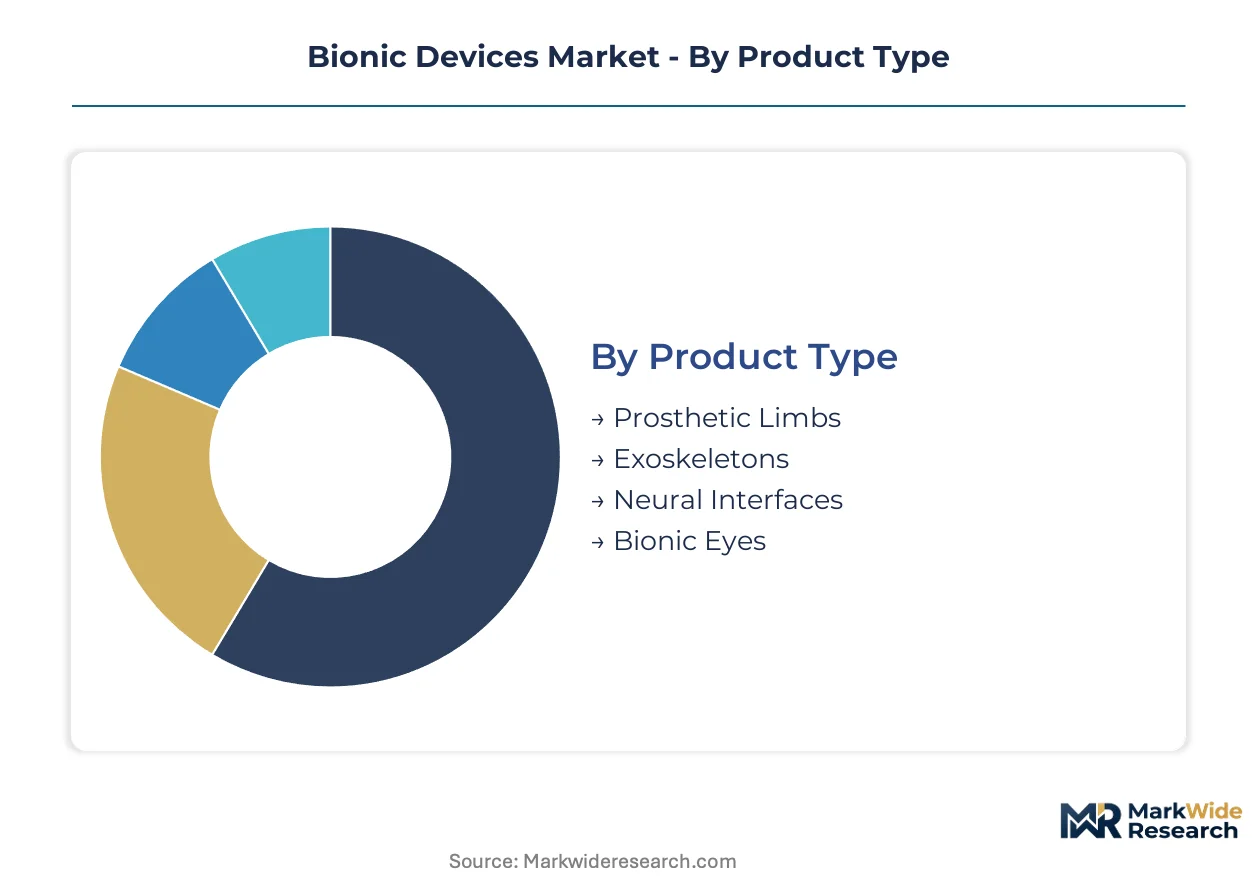
Segmentation in bionic devices reveals divergent service intensity requirements across implantable versus wearable categories. Prosthetic limbs demand decade-long rehabilitation support while neural interfaces require algorithmic recalibration services that reshape vendor economics.
Product Type:
After-sales service intensity varies dramatically across product categories, with implantable systems requiring surgical revision protocols and external devices demanding hardware upgrade cycles.
- Prosthetic Limbs:Myoelectric and body-powered configurations employ carbon fiber sockets and silicone liners rated for 3-5 year replacement cycles. Veterans Affairs procurement in the United States concentrates demand for advanced upper-limb systems, with socket refitting services generating recurring revenue streams that exceed initial device margins.
- Neural Interfaces:Brain-computer and peripheral nerve implants utilize platinum-iridium electrode arrays with hermetic titanium housings designed for multi-year implantation. German statutory health insurance reforms are expanding reimbursement for deep brain stimulation systems, creating predictable demand pools that stabilize manufacturer forecasting.
- Exoskeletons:Powered and passive wearable frames for spinal cord injury and workplace support.
- Bionic Eyes:Retinal and cortical implants constrained by surgical training infrastructure scarcity.
Prosthetic limbs hold the largest share; momentum sits with exoskeletons as workplace injury prevention protocols broaden addressable demand.
End User:
Cost tier stratification separates federally guaranteed demand pools from discretionary athletic enhancement markets with divergent price elasticity.
- Veterans:US federal healthcare systems mandate advanced prosthetic coverage for wounded service members through Veterans Affairs networks, creating stabilized revenue forecasting with multi-year procurement contracts.
- Amputees:Statutory insurance populations in Germany and trauma-related cases drive volume demand for myoelectric systems.
- Athletes:Performance-focused segments seeking competitive advantage through biomechanical augmentation.
- Healthcare Providers:Hospital systems and rehabilitation centers acquiring devices for patient service line expansion.
Veterans represent the most concentrated demand tier; amputee populations are expanding most quickly through reimbursement reform.
Technology:
Application specificity determines technology adoption patterns, with closed-loop control architectures commanding development priority.
- Artificial Intelligence:Machine learning algorithms for neural signal decoding and adaptive prosthetic control are virtualizing clinical workflows. FDA breakthrough device designations are accelerating review timelines for AI-enabled neural interfaces.
- Robotics:Actuated joints and powered exoskeleton frames with position and force feedback.
- Biofeedback:Electromyography and neural signal monitoring for patient training protocols.
- Sensory Integration:Haptic and proprioceptive feedback systems restoring closed-loop motor control.
Artificial intelligence holds the largest development investment; sensory integration is gaining share fastest through prosthetic embodiment research.
Application:
Volume concentration in rehabilitation contrasts with margin premiums in military and athletic segments.
- Rehabilitation:Post-stroke and spinal cord injury protocols in tertiary medical centers.
- Assistive Devices:Daily living support for sensory and motor impairment populations.
- Military Applications:Durable battlefield prosthetics and load-bearing exoskeletons for combat support.
- Sports Enhancements:Biomechanical augmentation for competitive and recreational athletic performance.
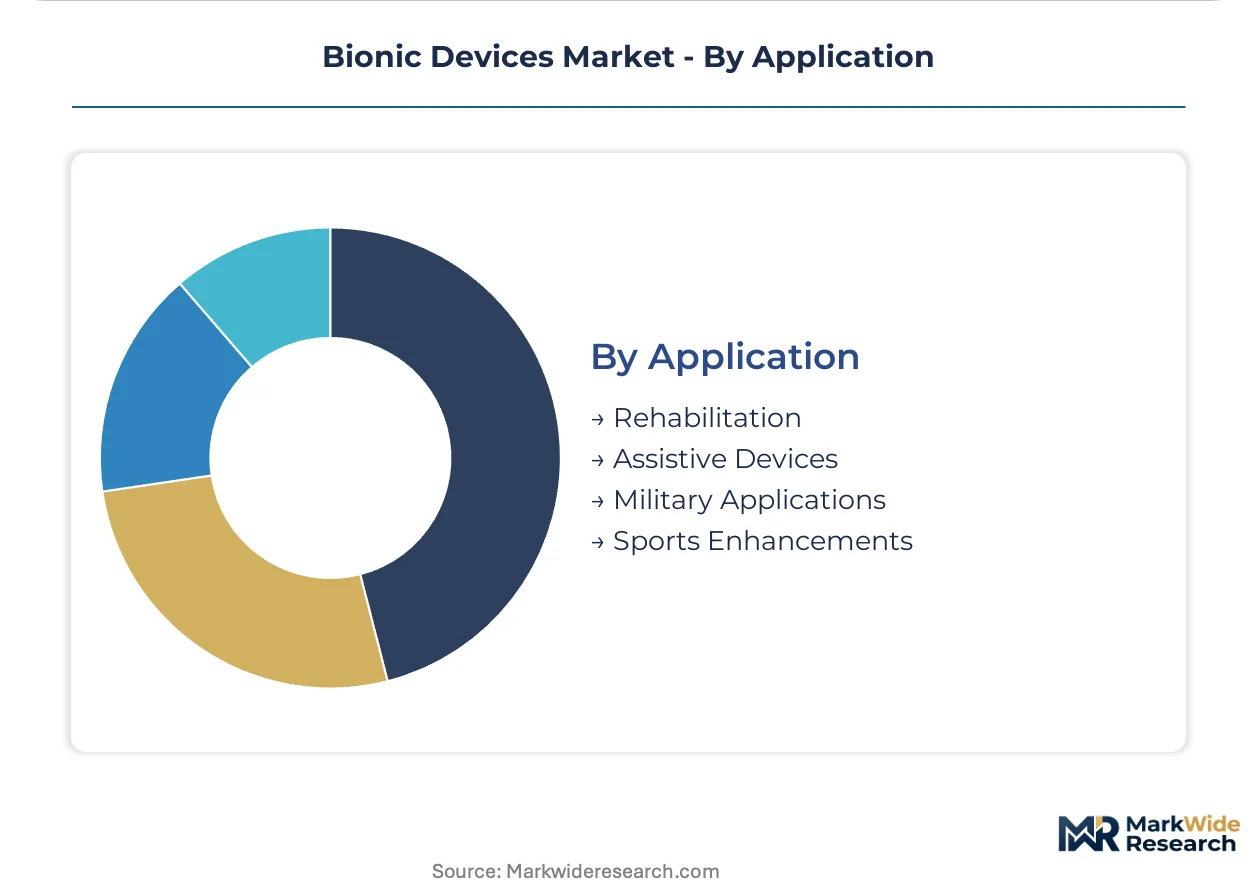
Rehabilitation holds the largest share; sports enhancements are climbing the fastest as regulatory frameworks adapt to elective augmentation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export myoelectric prosthetic systems to Veterans Affairs networks across the United States, establishing a transatlantic trade corridor that concentrates high-value bionic device flows between these two demand centers.
United States
Veterans Affairs healthcare systems mandate advanced prosthetic coverage for wounded service members, creating federally guaranteed demand pools. FDA breakthrough device designations compress premarket approval timelines for neural interface developers. Minneapolis and Boston anchor clinical trial networks where Medtronic plc leverages deep brain stimulation infrastructure.
Germany
Bundestag-mandated statutory health insurance reforms now cover myoelectric prosthetics for broader amputee populations, removing prior authorization barriers. EMA Medical Device Regulation conformity assessments govern European commercialization through notified bodies in Berlin and Munich. Bavaria and Baden-Württemberg host regional device consortia that aggregate demand across multiple payer networks.
Japan
METI and PMDA coordinate reimbursement listings with technical standards that influence regional product configuration requirements for neural interfaces. Logistics and manufacturing employers pilot lumbar-support exoskeletons for aging workforces, opening industrial reimbursement channels. Tokyo and Osaka concentrate rehabilitation protocol development for closed-loop bionic control systems.
Switzerland
Swissmedic regulates active implantable devices under enhanced post-market surveillance requirements that align with EMA frameworks. Precision manufacturing clusters in Zurich and Basel supply hermetic titanium housings and platinum-iridium electrode contacts for multi-year implantation. The country's semiconductor foundry partnerships absorb microelectrode array fabrication from academic clean rooms.
United Kingdom
NHS England procurement frameworks concentrate demand for cochlear and retinal implant systems, though retinal surgeon training infrastructure scarcity constrains bionic eye deployment. The Medicines and Healthcare products Regulatory Agency oversees transitional arrangements post-EU withdrawal. London and Cambridge anchor neural signal decoding algorithm development for adaptive prosthetic control.
Bionic Devices Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement, reimbursement, and technology licensing dimensions. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with neuromodulation infrastructure, pure-play neural interface developers with FDA breakthrough designations, and orthopedic device specialists with socket fabrication expertise. Dominant competitive moves include strategic partnerships with semiconductor foundries for microelectrode array manufacturing and geographic expansion through statutory insurance reimbursement capture.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corporation occupy positions that exemplify channel control through deep brain stimulation infrastructure and cardiac rhythm management platforms respectively. Abbott Laboratories anchors a position across diabetes care and neuromodulation pipelines that feed adjacent bionic device development. These three players represent the scale-driven end of competitive positioning, leveraging existing clinical trial networks and regulatory relationships to compress time-to-market for neural interface commercialization.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Cochlear Ltd |
| Ekso Bionics Holdings Inc. |
| Ossur |
| Sonova |
| Zimmer Biomet Holdings Inc. |
| Edwards Lifesciences Corporation |
| Others |
Supply Flow & Price Mechanics
Zurich precision manufacturing clusters supply hermetic titanium housings and platinum-iridium electrode contacts that command premium input pricing, translating into downstream margin pressure for neural interface developers competing on multi-year implantation reliability.
Pricing Analysis
Next-generation closed-loop neural interfaces price at substantial premiums over first-generation myoelectric prosthetics and economy-tier body-powered alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, ISO 14155 clinical trial certification tier, and bundled after-sales service intensity. Pricing pressure stems from platinum-iridium electrode cost volatility as South African mining concentration creates input instability. Veterans Affairs procurement contracts exhibit lowest price sensitivity due to federally guaranteed demand pools, while German statutory insurance reimbursement channels show moderate elasticity as regional device consortia aggregate bargaining power.
Supply Chain Analysis
Export-control regimes restricting semiconductor manufacturing equipment flows to certain jurisdictions are compressing microelectrode array fabrication capacity expansion timelines. Taiwan, South Korea, and Switzerland anchor high-density electrode production, drawing from biocompatible thin-film deposition expertise, hermetic sealing certification infrastructure, and precision machining capabilities. Single-source vulnerability concentrates in South African platinum-iridium supply. Distribution runs through specialized orthopedic clinics and academic medical center procurement departments that unbundle device acquisition from surgical training services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Veterans Affairs centralized procurement and German regional device consortia, fragmenting pricing leverage away from individual manufacturers.
For Market Incumbents: Pre-empt algorithmic obsolescence by acquiring machine learning neural signal decoding capabilities before pure-play developers achieve FDA breakthrough status. Anchor capacity expansion in Swiss semiconductor foundry partnerships to secure microelectrode array yield engineering expertise. Defensive consolidation should prioritize backward integration into platinum-iridium electrode contact manufacturing to buffer South African supply concentration risk. For New Entrants and Emerging Players: Pursue workplace injury prevention exoskeletons in Japanese logistics corridors where METI reimbursement pilot programs create regulatory clarity ahead of competitive saturation. Target German statutory insurance reform channels for myoelectric prosthetic penetration, exploiting unbundled procurement that enables specialized orthotic clinic competition. Deploy direct-to-clinic sales models bypassing academic medical center gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a reimbursement-regulation arbitrage play because statutory insurance expansion and FDA breakthrough pathways create predictable demand visibility exceeding typical medical device volatility. Acquisition targets should display semiconductor foundry partnerships or proprietary neural decoding algorithms. Watch FDA draft guidance finalization on brain-computer interfaces as the signal indicating regulatory capital requirement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress premarket approval capital requirements for neural interface developers. |
| CE Marking Pathway under MDR | Notified body conformity assessments in Berlin govern European commercialization access for active implantables. |
| Semiconductor Foundry Partnership | Co-development agreements migrate microelectrode array fabrication from academic clean rooms to volume manufacturing. |
| Hospital System Procurement Alliance | Veterans Affairs multi-year contracts stabilize revenue forecasting for advanced myoelectric prosthetic suppliers. |
| Reimbursement Strategy Expansion | German statutory health insurance reform removes prior authorization barriers for broader amputee populations. |
Methodological Framework
Operator-level perspectives from prosthetists, neural interface biomedical engineers, Veterans Affairs procurement officers, and German statutory health insurance fund administrators anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) and PMA filings, EMA medical device regulation submissions, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across product type, end user, technology, and application segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed optimistic, baseline, and conservative trajectories across the analysis window. Segmentation dimensions modeled included implantable versus wearable form factor, federally guaranteed versus discretionary reimbursement channels, and closed-loop versus open-loop control architecture. CAGRs derived from fitted growth curves incorporating Veterans Affairs procurement expansion rates, German Bundestag-mandated reimbursement reform implementation timelines, and semiconductor foundry capacity absorption curves for microelectrode array production.
Macroeconomic conditions sit as an overlay; deviation in precious metal commodity indices, euro-dollar exchange rate volatility, or South African mining output would shift the trajectory. Forecasts reflect documented assumptions regarding FDA breakthrough designation throughput rates and EMA notified body audit capacity expansion. Material shifts in EU AI Act risk classification finalization for autonomous bionic control systems would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Myopia Management Lenses Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Organ Preservation Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market