
 Sphincterotomes Market | 2026-2036
Sphincterotomes Market Size, Share, and Industry Trends Forecast 2026-2036
Sphincterotomes Market Analytics
Hospital procurement departments are unwinding their historical preference for reusable sphincterotomes as infection control protocols tighten and total cost-of-ownership models favor single-use alternatives. Boston Scientific Corporation leverages its integrated endoscopy portfolio to control catheter delivery channels across North American health systems. Cook Medical anchors its position through deep specialization in biliary access devices and sustained R&D investment in electrocautery wire configurations. Medi-Globe GmbH competes on European home-market proximity, offering rapid customization for regional physician preferences.
A sphincterotome is an endoscopic accessory device comprising a catheter body with an exposed cutting wire at the distal tip, typically manufactured from biocompatible polymers and stainless steel alloys, designed to incise the sphincter of Oddi during endoscopic retrograde cholangiopancreatography. The device delivers controlled electrosurgical current through its wire element to achieve precise tissue transection while maintaining luminal access for stone extraction or stent placement. Single-use sphincterotomes now dominate volume shipments as healthcare facilities prioritize elimination of reprocessing variability and cross-contamination liability. Electrosurgical technology leads value generation given its integration with advanced generator systems and premium pricing tied to controlled impedance feedback, while hybrid platforms represent the fastest-growing configuration by combining manual tactile control with automated energy modulation.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for manufacturers seeking commercial distribution. ISO 13485 quality management certification serves as a baseline predicate for regulatory submissions across both jurisdictions, with notified body capacity constraints in Europe extending conformity assessment durations. Stakeholders must monitor evolving FDA guidance on reprocessing validation for any reusable device lines and assess whether MDR clinical evidence expectations will accelerate consolidation among smaller catheter manufacturers.
Market Dynamics
Hospital procurement departments are unwinding their historical preference for reusable sphincterotomes as infection control protocols tighten and total cost-of-ownership models favor single-use alternatives. Boston Scientific Corporation leverages its integrated endoscopy portfolio to control catheter delivery channels across North American health systems. Cook Medical anchors its position through deep specialization in biliary access devices and sustained R&D investment in electrocautery wire configurations. Medi-Globe GmbH competes on European home-market proximity, offering rapid customization for regional physician preferences.
Growth Catalysts
- Outpatient ERCP expansion:Ambulatory surgical centers in the United States are expanding their purchasing of these devices as procedural volumes migrate from inpatient settings.
- EU MDR conformity pathways:Tightened quality benchmarks for electrosurgical components are accelerating manufacturer investment in clinical evidence generation.
- Aging demographics:Sustained procedural volumes in Germany and Japan are concentrating demand among elderly populations requiring biliary intervention.
Market Restraints
- Nitinol alloy cost volatility:Electrocautery wire configurations depend on nickel-titanium supply chains concentrated in Chinese raw material processing.
- Notified body capacity constraints:EU MDR technical documentation obligations are extending conformity assessment durations for catheter manufacturers.
- Reusable device substitution:Some cost-constrained health systems in Eastern Europe continue reprocessing legacy sphincterotomes despite liability exposure.
Strategic Opportunities
- Hybrid platform convergence:Combining manual tactile control with automated energy modulation represents the fastest-growing configuration segment.
- Japanese reimbursement pathways:METI and PMDA streamlined approval processes for novel electrosurgical accessories create entry advantages.
- Direct-to-ASC distribution:Bypassing traditional hospital supply chain intermediaries allows manufacturers to capture margin in ambulatory settings.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for polymer catheter suppliers are creating six-to-nine month delays in component sourcing.
- Legacy generator incompatibility:Electrosurgical wire impedance feedback systems require integration with installed base equipment from multiple OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sphincterotomes Market |
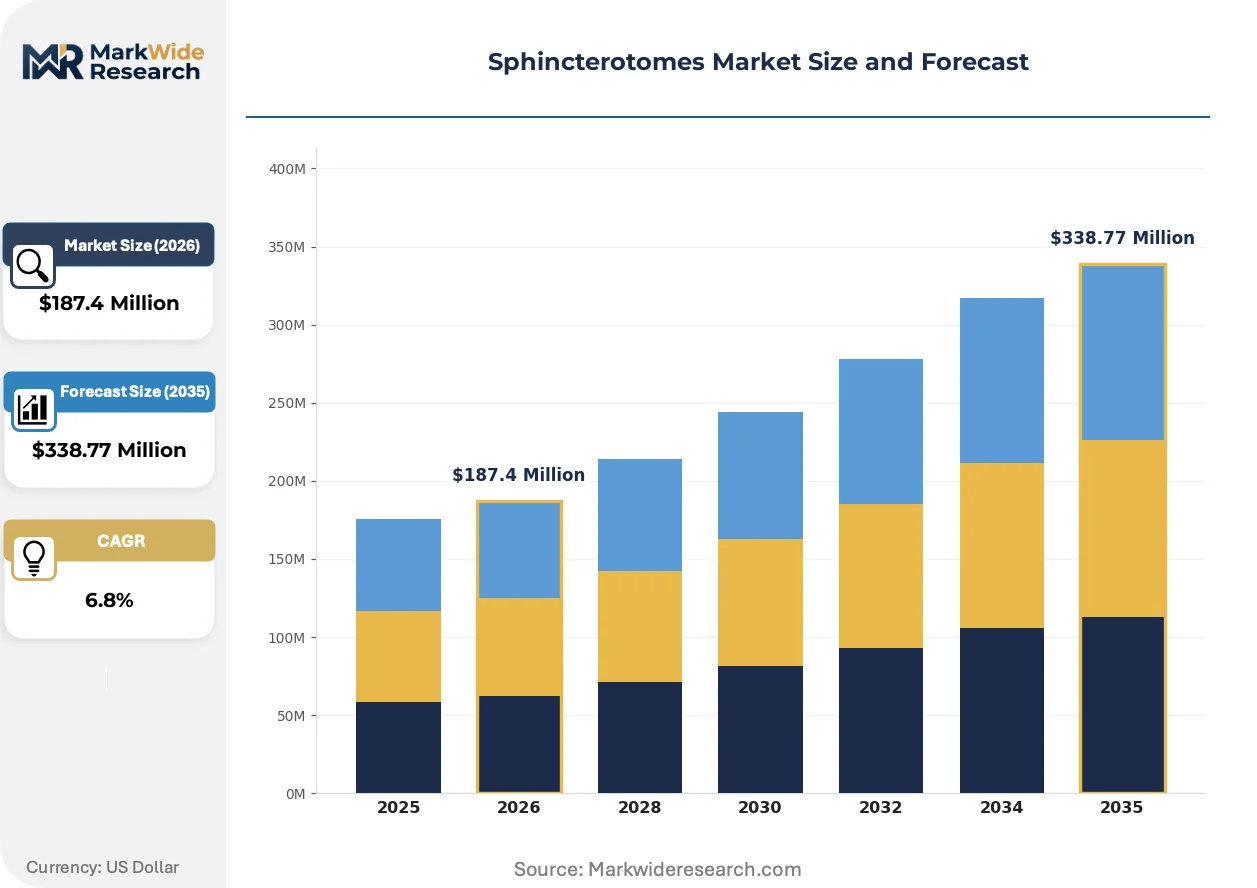
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Sphincterotomes, Reusable Sphincterotomes, Electrosurgical Sphincterotomes, Balloon-Expandable Sphincterotomes End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Electro-Cautery, Manual, Hybrid, Laser Application: Biliary Procedures, Gastrointestinal Procedures, Urological Procedures, Surgical Interventions |
| Companies Covered | Boston Scientific Corporation, Medi-Globe GmbH, CONMED Corporation, Olympus America, Cook Medical, ENDO-FLEX GmbH, Shaili Endoscopy, Advin Health Care, Micro-Tech (Nanjing) Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sphincterotomes Market Evolving Landscape
Electrosurgical technology is fragmenting competitive positioning across the sphincterotome value chain as manufacturers differentiate through energy delivery sophistication rather than catheter mechanics alone. Three distinct developments are reshaping product roadmaps and procurement criteria.
Controlled impedance feedback systems are fragmenting the premium tier of the market. These platforms integrate real-time tissue resistance monitoring with automated power modulation, enabling precise sphincter transection. Academic medical centers in the United States are adopting these configurations fastest, compressing margins for conventional wire-based alternatives that lack closed-loop energy control.
FDA 510(k) clearance requirements are reshaping development timelines for electrosurgical accessories. The agency's evolving guidance on reprocessing validation creates documentation burdens for any reusable device lines. Manufacturers targeting the United States market are responding by accelerating single-use platform development to bypass reprocessing scrutiny entirely.
Hospital supply chain rationalization is consolidating vendor relationships around integrated endoscopy portfolios. Purchasing departments now bundle sphincterotome procurement with duodenoscope and generator contracts, displacing standalone catheter suppliers. This concentration is most visible in German hospital networks, where GPOs negotiate system-wide agreements favoring full-line vendors.
Sphincterotomes Market Segmentation
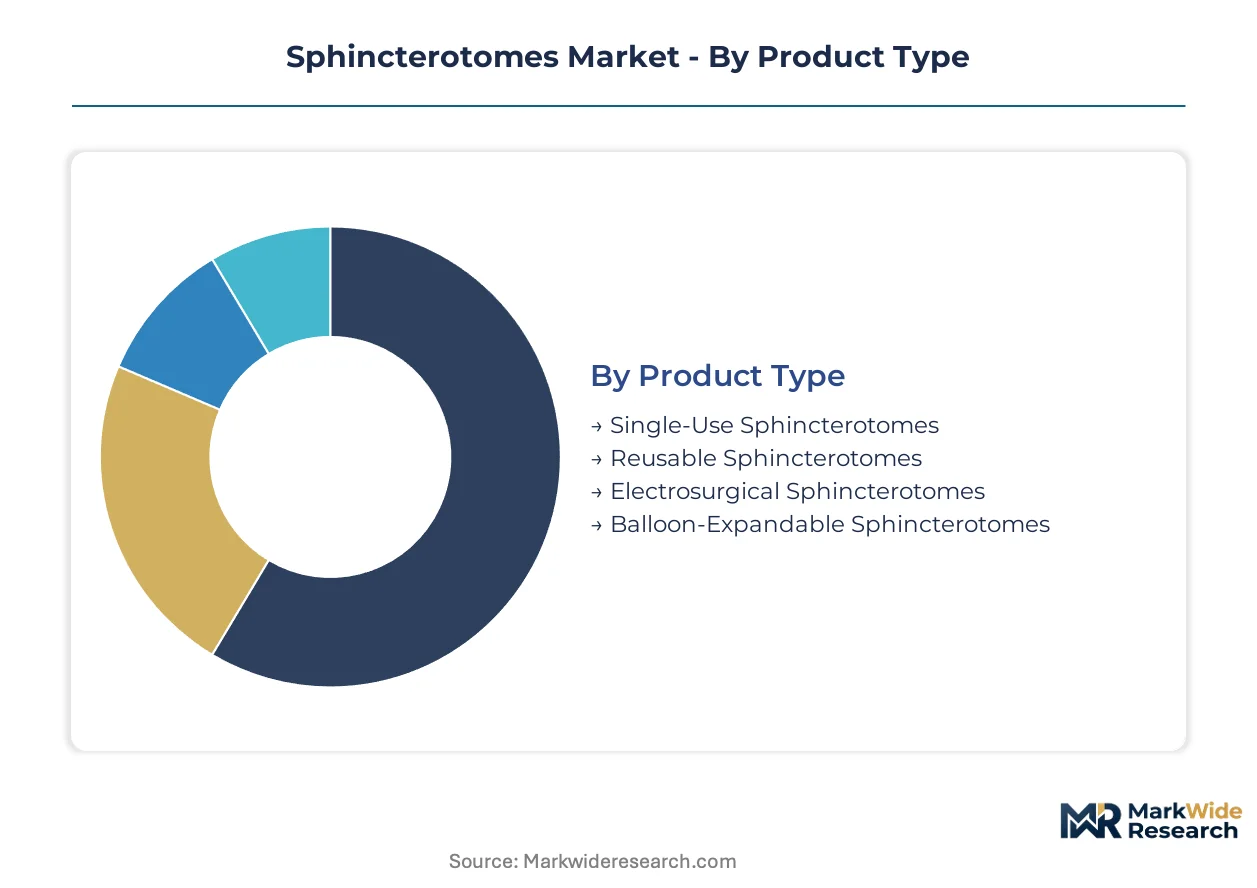
Sphincterotome procurement patterns diverge sharply across clinical settings and technological platforms. Understanding these segment boundaries reveals where pricing power concentrates and which configurations face substitution pressure from adjacent device categories.
Product Type:
Domestic manufacturing clusters in the United States and Germany supply electrosurgical variants to regional hospital networks, while single-use platforms increasingly flow through centralized distribution hubs serving multiple countries.
- Single-Use Sphincterotomes:Polymer catheter bodies with pre-sterilized cutting wires eliminate reprocessing liability. United States ambulatory surgical centers are converting volume fastest as liability insurers mandate disposable protocols for outpatient ERCP.
- Electrosurgical Sphincterotomes:Integrated impedance feedback systems enable automated power modulation during sphincter transection. Japanese academic medical centers are adopting these configurations for complex biliary interventions, compressing margins for conventional wire alternatives.
- Reusable Sphincterotomes:Stainless steel alloy construction supports multiple sterilization cycles. Eastern European health systems with constrained capital budgets continue procurement despite tightening EU MDR reprocessing documentation obligations.
- Balloon-Expandable Sphincterotomes:Combination dilation-incision platforms for stricture management. Niche adoption in German tertiary centers for difficult cannulation scenarios.
Single-use platforms hold the largest share; momentum sits with electrosurgical configurations.
End User:
Procurement authority is fragmenting as purchasing decisions migrate from hospital central supply to specialized gastroenterology service lines with distinct technical requirements.
- Hospitals:Inpatient ERCP volumes sustain bulk contracting for integrated endoscopy systems. German hospital networks are consolidating vendor relationships around full-line suppliers capable of duodenoscope-sphincterotome-generator bundles.
- Ambulatory Surgical Centers:Streamlined supply chains favor direct manufacturer relationships bypassing traditional distribution intermediaries. United States ASCs are expanding device purchasing fastest as procedural volumes migrate from inpatient settings.
- Specialty Clinics:Gastroenterology-focused facilities with limited procedure volumes. Preference for single-use platforms to eliminate reprocessing infrastructure investment.
- Research Institutions:Academic medical centers evaluating novel energy modalities. Japanese university hospitals are piloting hybrid control systems under streamlined PMDA approval pathways.
Hospitals dominate absolute volume; ambulatory surgical centers are climbing the fastest.
Technology:
Energy delivery sophistication now determines competitive positioning more than catheter mechanical design, with reimbursement pathways favoring platforms demonstrating measurable outcome differentiation.
- Electro-Cautery:Controlled radiofrequency current through exposed wire elements. Mature installed base across United States health systems with established generator compatibility requirements.
- Hybrid:Combines manual tactile feedback with automated energy modulation. Fastest-expanding configuration as manufacturers integrate real-time tissue resistance monitoring.
- Manual:Mechanical incision without electrosurgical energy. Declining share concentrated in cost-constrained markets with legacy equipment installed base.
- Laser:Photonic energy delivery for precise tissue ablation. Experimental adoption in Japanese research institutions for select stricture interventions.
Electro-cautery retains the largest installed base; hybrid platforms show the steepest expansion trajectory.
Application:
Procedure-specific device requirements are driving specialization in tip configurations and wire exposure lengths, with biliary interventions setting the technical benchmark for other anatomical targets.
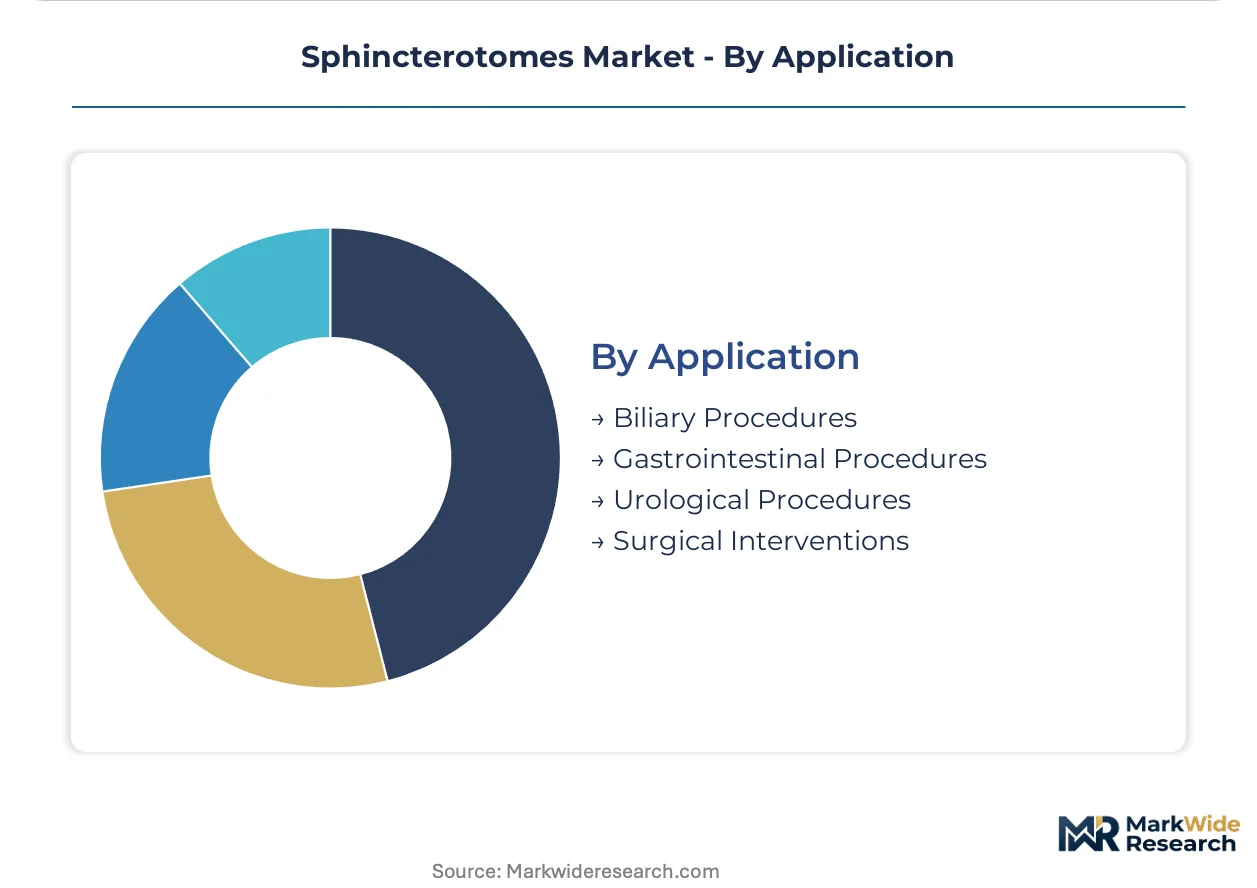
- Biliary Procedures:Sphincter of Oddi incision for stone extraction and stent placement. German and Japanese procedural volumes sustain demand for premium electrosurgical configurations with controlled impedance feedback.
- Gastrointestinal Procedures:Pancreatic duct cannulation and sphincterotomy. United States academic centers are adopting hybrid platforms for difficult cannulation scenarios.
- Urological Procedures:Sphincterotomy for bladder outlet obstruction. Niche application with limited dedicated device development.
- Surgical Interventions:Open and laparoscopic biliary access. Declining share as percutaneous and endoscopic techniques displace surgical approaches.
Biliary applications command the largest share; gastrointestinal procedures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for electrosurgical catheter components, while Los Angeles International Airport facilitates just-in-time delivery to United States ambulatory surgical centers. These logistics nodes concentrate procurement authority for sphincterotome manufacturers seeking regional market access.
United States
Ambulatory surgical centers in Texas and Florida are expanding ERCP volumes fastest as procedural migration accelerates from inpatient settings. FDA 510(k) clearance pathways for electrosurgical accessories tightened documentation requirements for reprocessing validation in 2023. The Minneapolis medical device cluster houses catheter manufacturing operations serving North American health system GPOs.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are consolidating vendor relationships around integrated endoscopy system bundles. EU MDR conformity assessment obligations from notified bodies in TÜV SÜD and BSI extend technical documentation timelines for electrocautery wire configurations. The Tuttlingen surgical instrument cluster specializes in precision metal components for reusable device lines.
Japan
Academic medical centers in Tokyo and Osaka are piloting hybrid control platforms under streamlined PMDA approval pathways established by METI. Aging demographics in Kansai and Chubu regions sustain procedural volumes for biliary interventions requiring premium electrosurgical configurations. The Nagoya medical device corridor hosts R&D facilities for impedance feedback system integration.
China
Tertiary hospitals in Shanghai and Beijing are adopting single-use platforms as infection control protocols tighten in public health systems. NMPA registration requirements for Class III medical devices extended review timelines for imported electrosurgical accessories in 2024. The Suzhou industrial park concentrates polymer catheter extrusion capacity serving domestic manufacturers.
India
Specialty gastroenterology clinics in Maharashtra and Karnataka are converting to disposable sphincterotomes to eliminate reprocessing infrastructure investment. CDSCO medical device rules under the Drugs and Cosmetics Act mandate registration for electrosurgical accessories imported from established manufacturing jurisdictions. The Hyderabad medical technology cluster hosts contract manufacturing for catheter delivery systems.
Sphincterotomes Market Competitive Landscape
Concentration sits with diversified endoscopy portfolio holders and specialized biliary access device manufacturers. The vendor base organizes around three strategic archetypes: integrated system suppliers controlling generator-catheter compatibility, standalone catheter specialists competing on customization velocity, and emerging Asia-Pacific fabricators leveraging polymer extrusion scale. Dominant competitive moves include backward integration into electrocautery wire production and geographic expansion through direct-to-ASC distribution channels bypassing traditional hospital supply intermediaries.
Among United States-based diversified manufacturers, Boston Scientific Corporation and Cook Medical occupy positions at opposite ends of the specialization spectrum. Boston Scientific exemplifies the integrated system archetype through its control of duodenoscope and generator portfolios that anchor hospital GPO negotiations. Cook Medical represents deep specialization in biliary access, with its Indiana headquarters supporting sustained R&D investment in wire configurations. ENDO-FLEX GmbH anchors the European customization tier, with its German GmbH structure enabling rapid response to regional physician preference variations.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medi-Globe GmbH |
| CONMED Corporation |
| Olympus America |
| Cook Medical |
| ENDO-FLEX GmbH |
| Shaili Endoscopy |
| Advin Health Care |
| Micro-Tech (Nanjing) Co., Ltd |
| Others |
Value Network & Pricing Analysis
ISO 13485 certification gates both supplier qualification and price differentiation in sphincterotome procurement, with notified body audit backlogs creating six-to-nine month delays that compress margins for uncertified polymer catheter vendors while amplifying premiums for electrosurgical configurations with validated quality management systems.
Pricing Analysis
Volume-discount tiering structures dominate hospital GPO negotiations, with three-tier pricing stratifying across premium electrosurgical platforms with impedance feedback, standard single-use alternatives, and economy reusable lines for cost-constrained systems. Price differentiation rests on FDA 510(k) clearance status and ISO 13485 certification tier, with academic medical centers showing lowest sensitivity and Eastern European health systems exhibiting acute price consciousness. Cost compression in the standard tier is intensifying as Chinese catheter manufacturers expand polymer extrusion capacity.
Supply Chain Analysis
Nitinol wire drawing capacity in the United States and Germany anchors electrocautery element production, while Chinese raw material processing concentrates nickel-titanium alloy feedstock. Component sourcing draws from Japanese precision metalworking for impedance sensors and Italian polymer extrusion for catheter bodies. Single-source vulnerability in Chinese nitinol supply creates exposure to export restriction risk. Distribution runs through regional medical device distributors serving hospital networks and direct-to-ASC channels bypassing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic sphincter augmentation and endoscopic ultrasound-guided interventions pose substitution threats that incumbent sphincterotome manufacturers must navigate through portfolio extension and outcome demonstration.
For Market Incumbents: Fortify generator-catheter compatibility lock-in by deepening backward integration into electrocautery wire production and securing exclusive duodenoscope-sphincterotome bundle contracts with United States GPOs. Magnetic sphincter augmentation devices threaten biliary procedure volumes; counter by accelerating hybrid platform R&D with automated energy modulation capabilities. For New Entrants and Emerging Players: Anchor in ambulatory surgical center direct distribution to bypass entrenched hospital supply chain intermediaries controlled by Boston Scientific and Cook Medical. United States ASCs represent the most penetrable segment given procedural volume migration and liability-driven single-use conversion. Pursue ISO 13485 certification early to qualify for GPO vendor panels. For Investors and Strategic Acquirers: EU MDR conformity assessment backlogs reshape the acquisition landscape by stranding smaller catheter manufacturers without notified body relationships, creating distressed asset opportunities. Five-to-ten year viability favors specialists with captive electrocautery wire production and established FDA 510(k) predicate libraries. Monitor notified body capacity expansion as the inflection signal for M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitinol Wire Production | Captive supply of electrocautery elements insulates margin from Chinese raw material volatility. |
| Direct-to-ASC Distribution Channel Establishment | Bypassing traditional hospital supply intermediaries captures margin in fastest-growing outpatient ERCP settings. |
| Hybrid Platform R&D Investment | Combining manual tactile control with automated energy modulation addresses academic center preference shifts. |
| EU MDR Notified Body Relationship Securement | BSI or TÜV SÜD designation accelerates conformity assessment for electrosurgical catheter configurations. |
| Japanese PMDA Approval Pathway Navigation | METI streamlined processes for novel electrosurgical accessories create entry advantages in aging demographic markets. |
Research Methodology
The analysis maps electrosurgical sphincterotome, single-use disposable, reusable, and balloon-expandable configurations, each validated through interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and interventional gastroenterologists. Secondary sources include FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, hospital procurement contract repositories, and CMS outpatient procedure volume records. Bottom-up shipment estimates triangulate against top-down market sizing from installed base generator counts and ERCP procedural frequency data.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user facility category, energy delivery technology, and application target. CAGRs derive from procedure volume elasticity to aging demographic penetration, technology substitution curves for hybrid platforms, and reimbursement pathway evolution for outpatient ERCP. Industry-specific inputs incorporate nitinol alloy price indices, notified body audit queue lengths, and ambulatory surgical center construction permitting data.
Decision-makers should treat outputs as directional under assumptions of sustained outpatient procedural migration and stable EU MDR implementation timelines; material deviation in reimbursement policy or notified body capacity would warrant model refresh. Practitioners should keep alternative scenarios live as magnetic sphincter augmentation clinical trial readouts and Chinese nitinol export policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Pectus Bar Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Global Smart Implants Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Neurotech Devices Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Embryo Transfer Catheters Market