
 Global Photobiostimulation Market | 2026-2036
Global Photobiostimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photobiostimulation Market Foresight
Software-defined treatment protocols is realigning how photobiostimulation devices generate recurring revenue beyond hardware sales. Erchonia Corporation leverages its proprietary wavelength configurations to sustain premium positioning in pain management applications. Vielight Inc. specializes in neurostimulation headsets that anchor its presence in home-use neurological segments. THOR Photomedicine Ltd. dominates professional-grade laser therapy through direct clinical channel control across European and North American markets.
Photobiostimulation employs low-level light therapy at specific wavelengths, typically between 600 and 1,000 nanometers, to stimulate cellular mitochondrial activity and modulate inflammatory cascades without thermal tissue damage. The technology serves therapeutic applications spanning tissue repair, pain modulation, and neurological function restoration in clinical and consumer settings. Laser therapy equipment commands the highest margin pool due to precision dosing requirements and physician-directed purchasing, while portable units represent the fastest-growing deployment category as patients seek home-based musculoskeletal recovery options. LED devices occupy the largest installed base across wellness spas and sports centers where treatment breadth outweighs clinical specificity.
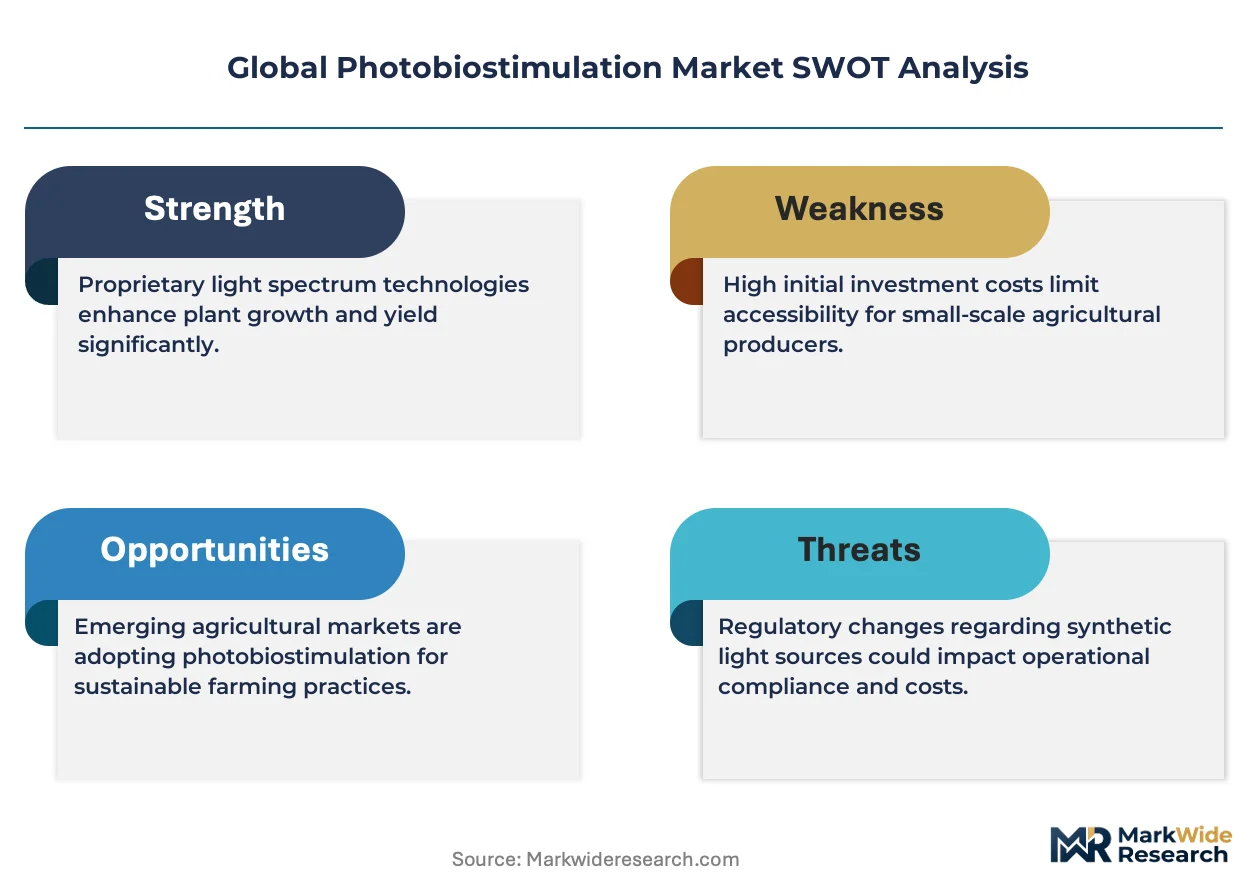
FDA 510(k) clearance pathways govern market entry for therapeutic claims in the United States, while CE marking under the EU MDR and Health Canada licensing shape parallel access requirements in Europe and Canada. ISO 13485 quality management standards and IEC 60601-1 electrical safety benchmarks further constrain supplier qualification and OEM partnerships. Stakeholders must monitor evolving reimbursement codes from CMS and Germany's KBA-aligned health technology assessment bodies, as coverage decisions will determine whether clinical adoption accelerates or remains confined to out-of-pocket wellness spending.
Market Dynamics
Software-defined treatment protocols are compressing hardware replacement cycles while locking clinics into recurring subscription revenue streams. Erchonia Corporation and THOR Photomedicine Ltd. compete through proprietary wavelength configurations that resist commoditization in professional pain management settings.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined pathways for low-risk laser therapy devices reduce time-to-market for musculoskeletal applications, enabling faster commercialization of LED-based systems in US physiotherapy chains.
- Germany's KBA-aligned health technology assessment:Emerging reimbursement coverage for photobiostimulation in outpatient rehabilitation is converting out-of-pocket wellness spending into billable clinical procedures.
- Home-use neurostimulation demand:Consumer adoption of transcranial photobiomodulation headsets for cognitive enhancement is creating parallel revenue streams beyond traditional clinical channels.
Market Restraints
- Precision optics supply concentration:German and Japanese suppliers dominate high-grade laser diode manufacturing, exposing device makers to input cost volatility and extended lead times.
- EU MDR compliance burden:Stricter clinical evidence requirements for CE marking under the 2017/745 regulation are extending product development timelines and inflating regulatory submission costs.
- Topical analgesic substitution:Over-the-counter lidocaine patches and CBD formulations compete for outpatient pain management budgets, particularly in wellness spa segments.
Strategic Opportunities
- India's outpatient physiotherapy expansion:Underpenetrated urban clinic networks present first-mover advantages for portable LED systems targeting post-surgical recovery protocols.
- Wavelength-AI convergence:Machine learning algorithms optimizing dose parameters in real-time are enabling personalized treatment protocols that differentiate premium device tiers.
- Direct-to-consumer subscription models:Monthly protocol access fees for home-use headsets are displacing one-time hardware transactions in neurological wellness segments.
Industry Challenges
- Photonics engineering talent scarcity:Specialized expertise in biocompatible wavelength calibration and thermal management remains concentrated among legacy laser manufacturers.
- Multi-jurisdiction certification complexity:Simultaneous FDA 510(k), EU MDR, and Health Canada licensing requires parallel clinical study designs that strain smaller device developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photobiostimulation Market |
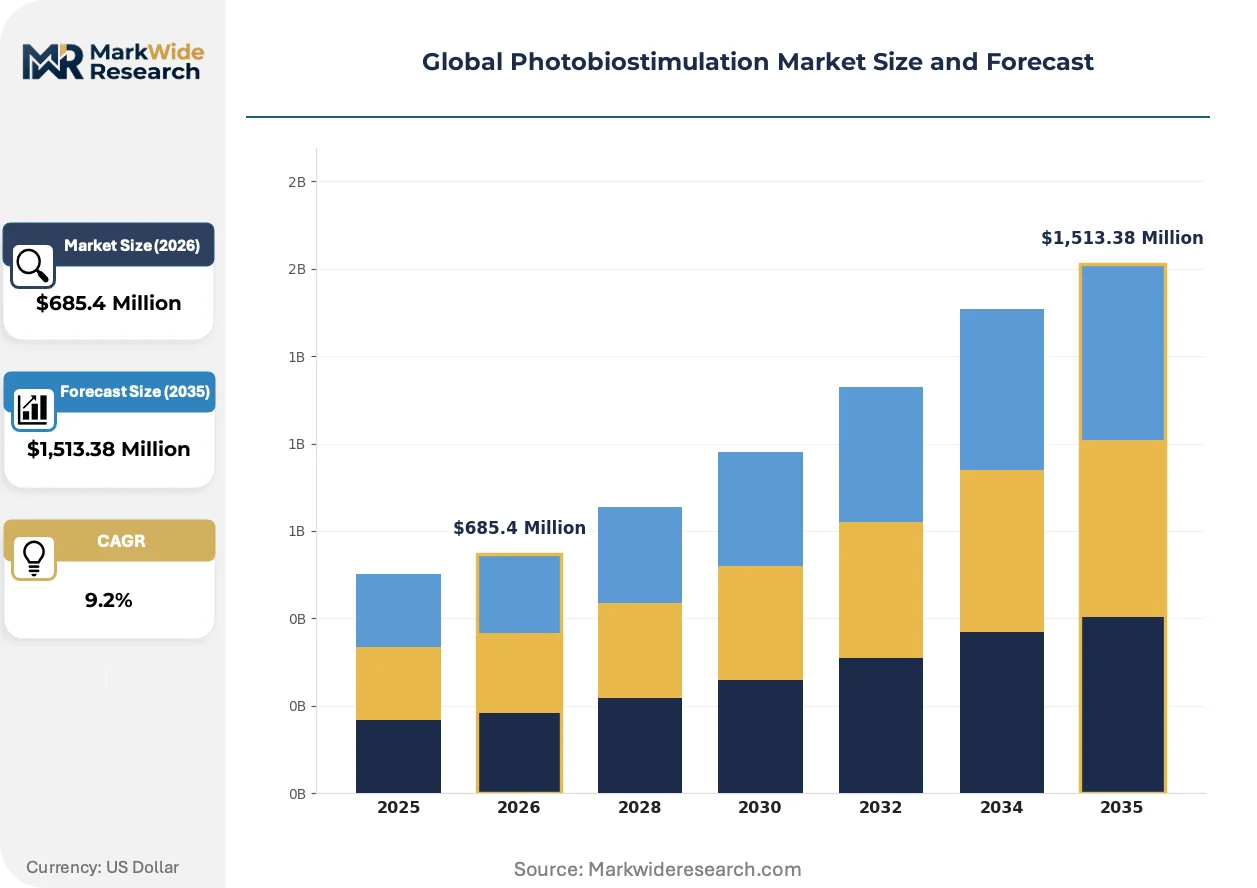
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Devices, Laser Therapy Equipment, Infrared Light Systems, Combination Devices Application: Wound Healing, Pain Management, Neurological Disorders, Musculoskeletal Recovery, Dermatological Treatments End User: Physiotherapy Clinics, Rehabilitation Centers, Sports Centers, Pain Management Clinics, Wellness Spas Deployment: Standalone Devices, Integrated Therapy Systems, Portable Units, Wearable Technology |
| Companies Covered | Erchonia Corporation, Vielight Inc., THOR Photomedicine Ltd., BioFlex Laser Therapy, TheraDome Inc., BioLight Technologies LLC, Apira Science Inc., Lexington International, Ingeneus Pty. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photobiostimulation Market Shifts & Advancements
Photobiostimulation is bifurcating into precision clinical systems and algorithm-guided consumer devices, with software capabilities now determining margin capture more than hardware specifications.
Multi-wavelength LED arrays with integrated photon dosimetry sensors are expanding into sports medicine facilities and corporate wellness centers. Professional athletic trainers in North American leagues are adopting these systems for accelerated soft-tissue repair. The technology is expanding into subscription-based service models that bundle hardware with protocol libraries, compressing capital expenditure barriers for mid-sized clinic chains.
CE marking under the EU MDR is forcing manufacturers to generate clinical evidence through randomized controlled trials rather than predicate device equivalency. German notified bodies are demanding extended follow-up data for neurological indication claims. European professional-grade laser manufacturers are responding by sponsoring investigator-initiated studies at university hospitals to preempt reimbursement scrutiny.
After-sales service unbundling is disrupting traditional device distribution in Japanese and South Korean aesthetic medicine channels. Clinics now purchase hardware through third-party financiers while subscribing directly to manufacturers for treatment protocol updates. This pattern is most visible in Tokyo and Seoul metro areas, where device utilization rates determine subscription tier pricing.
Global Photobiostimulation Market Segmentation
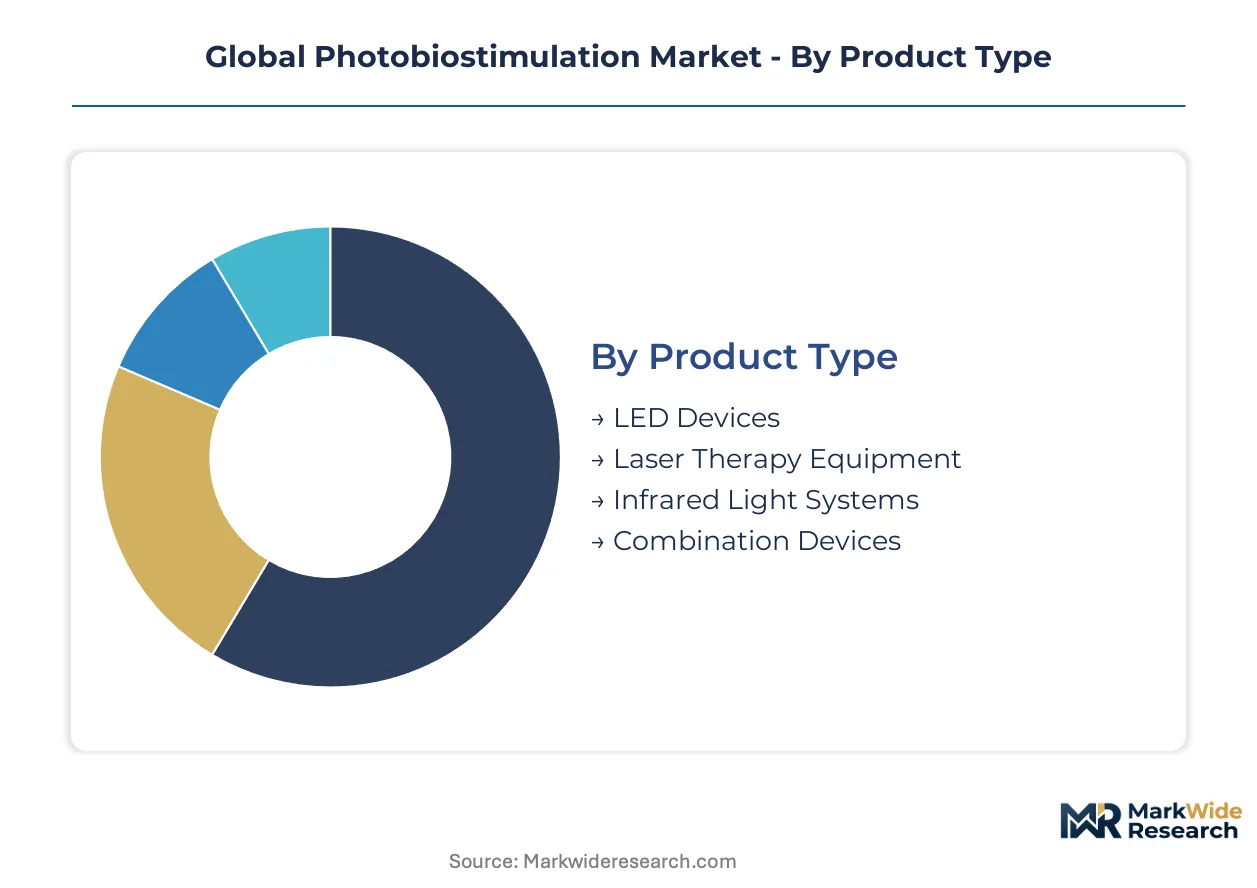
Photobiostimulation market segmentation reveals divergent capital requirements and margin profiles across hardware categories. Treatment specificity, regulatory pathway complexity, and channel control dynamics vary substantially by product architecture and end-use setting.
Product Type:
Laser therapy equipment demands the highest upfront capital commitment due to precision optics sourcing and FDA 510(k) clinical validation requirements.
- Laser Therapy Equipment:Precision diode arrays operating at 600-1,000 nanometers with calibrated power density controls. German and Japanese photonics suppliers dominate component sourcing, constraining margin flexibility for device assemblers targeting US physiotherapy chains and European rehabilitation networks.
- LED Devices:Multi-wavelength arrays with broader beam dispersion and lower thermal management complexity. Wellness spas in Seoul and Tokyo metro areas drive volume procurement for these systems where treatment breadth outweighs clinical specificity.
- Infrared Light Systems:Deep-tissue penetration modules targeting musculoskeletal recovery protocols in sports medicine facilities.
- Combination Devices:Hybrid LED-laser architectures enabling protocol flexibility across pain management and dermatological applications.
LED devices absorb the bulk of installed capacity; portable laser systems are expanding most quickly through home-use neurological segments.
Application:
Pain management commands the steepest regulatory investment due to FDA therapeutic claim substantiation and CMS reimbursement code alignment.
- Pain Management:Low-level laser therapy targeting inflammatory cascade modulation and nociceptor desensitization. German KBA-aligned health technology assessment bodies are converting out-of-pocket wellness spending into billable procedures at outpatient rehabilitation centers.
- Neurological Disorders:Transcranial photobiomodulation for cognitive function and neurodegenerative symptom management. Home-use headset demand in North American and Japanese consumer channels is creating parallel revenue streams beyond clinical procurement.
- Wound Healing:Cellular mitochondrial stimulation for tissue repair acceleration in post-surgical recovery settings.
- Musculoskeletal Recovery:Soft-tissue repair protocols adopted by professional athletic trainers in North American sports leagues.
- Dermatological Treatments:Collagen induction and inflammatory skin condition management in aesthetic medicine channels.
Pain management retains the largest revenue pool; neurological applications are gaining share fastest through direct-to-consumer subscription models.
End User:
Physiotherapy clinics require the most sophisticated procurement infrastructure due to multi-jurisdiction certification and outcome-based reimbursement alignment.
- Physiotherapy Clinics:Professional-grade systems with software-defined protocol libraries and subscription-based service bundling. Mid-sized clinic chains in the United States and Germany are compressing capital expenditure barriers through hardware-financing arrangements.
- Wellness Spas:Consumer-facing LED installations prioritizing treatment breadth over clinical precision. Tokyo and Seoul aesthetic medicine channels are pioneering after-sales service unbundling where device utilization rates determine subscription tier pricing.
- Rehabilitation Centers:Integrated therapy systems for post-surgical recovery and chronic condition management.
- Sports Centers:Portable units and multi-wavelength arrays for accelerated soft-tissue repair in athletic training environments.
- Pain Management Clinics:Specialized laser equipment for physician-directed therapeutic interventions.
Physiotherapy clinics anchor professional-grade procurement volume; wellness spas are scaling fastest through LED device standardization.
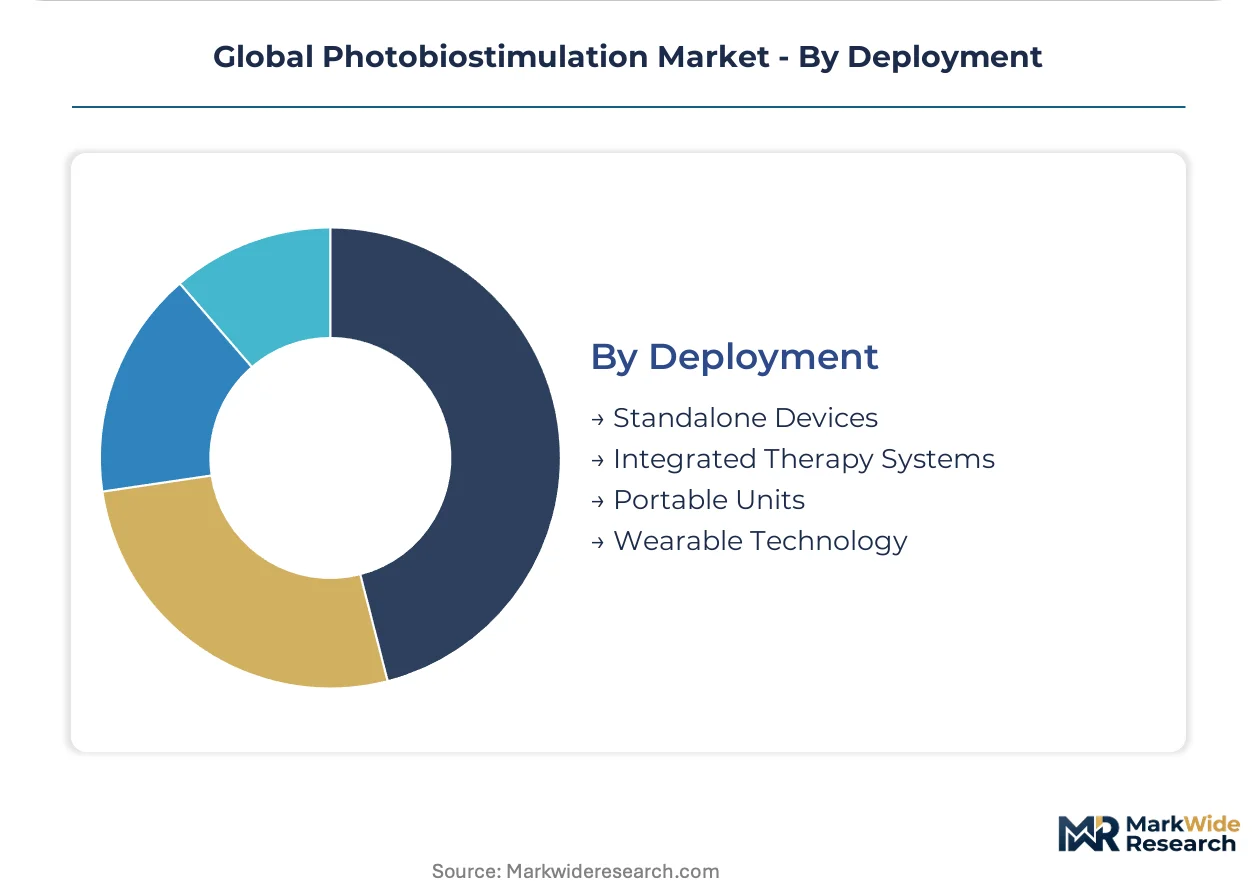
Deployment:
Integrated therapy systems impose the heaviest capital burden due to EMR connectivity, photon dosimetry sensors, and facility retrofit requirements.
- Portable Units:Battery-operated devices enabling home-based musculoskeletal recovery and patient compliance outside clinical settings. Demand concentrates in North American physiotherapy chains offering remote treatment protocols.
- Wearable Technology:Transcranial headsets and patch-based systems for neurological wellness and cognitive enhancement. Vielight Inc. anchors this segment through neurostimulation specialization.
- Standalone Devices:Fixed-installation systems for clinic-based treatment delivery with minimal integration requirements.
- Integrated Therapy Systems:Facility-embedded architectures with real-time dose optimization and electronic health record synchronization.
Standalone devices retain the largest installed base; wearable technology is climbing the fastest through algorithm-guided consumer adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of precision laser diodes concentrates in Germany and Japan, while clinical adoption and consumer demand distribute across physiotherapy networks in the United States, wellness chains in South Korea, and rehabilitation centers in Australia.
United States
Physiotherapy chains in Texas and Florida are expanding LED device procurement for musculoskeletal recovery protocols. FDA 510(k) clearance pathways govern therapeutic claims for pain management applications, compressing time-to-market for low-risk laser systems. The Greater Boston corridor hosts neurostimulation headset developers targeting home-use cognitive enhancement segments.
Germany
Outpatient rehabilitation centers in Bavaria and North Rhine-Westphalia are converting wellness spending into billable procedures through KBA-aligned health technology assessments. CE marking under the EU MDR demands extended clinical evidence for neurological indication claims, extending product development timelines. Stuttgart's photonics cluster supplies precision optics to domestic device manufacturers.
Japan
Wellness spas in Tokyo and Osaka metro areas are pioneering after-sales service unbundling for LED installations. METI standards guide electrical safety benchmarks for home-use devices entering consumer channels. Nagoya's industrial corridor concentrates thermal management engineering expertise for portable unit manufacturers.
South Korea
Aesthetic medicine channels in Seoul and Busan are driving volume procurement of multi-wavelength LED arrays where treatment breadth outweighs clinical specificity. MFDS licensing shapes market entry requirements for therapeutic claims in dermatological applications. The Pangyo Techno Valley cluster anchors algorithm-guided consumer device development.
Australia
Sports medicine facilities in New South Wales and Victoria are adopting portable laser systems for accelerated soft-tissue repair in professional athletic training. TGA registration requirements parallel FDA pathways for therapeutic device classification. Melbourne's medical technology precinct hosts clinical validation studies for wound healing applications.
Global Photobiostimulation Market Competitive Landscape
Top-tier vendors anchor professional-grade laser therapy through direct clinical channel control, while mid-tier specialists compete on wavelength configuration differentiation and subscription-based protocol libraries. The vendor base stratifies across precision photonics manufacturers, LED array assemblers, and algorithm-guided consumer headset developers. Three archetypes dominate: German-Japanese precision optics suppliers, North American clinical channel controllers, and Asian wellness-focused LED deployers. Competitive moves concentrate on strategic partnerships with physiotherapy chains and technology licensing for wavelength-AI convergence.
Within the clinical-grade laser tier, Erchonia Corporation and THOR Photomedicine Ltd. occupy positions defined by proprietary wavelength configurations and direct rehabilitation network relationships. Vielight Inc. exemplifies the neurostimulation specialization archetype, anchoring consumer-facing transcranial headset development through algorithm-guided protocol delivery. These three entities represent distinct competitive vectors: precision photonics manufacturing, clinical channel dominance, and direct-to-consumer neurological wellness.
| Leading Market Players |
|---|
| Erchonia Corporation |
| Vielight Inc. |
| THOR Photomedicine Ltd. |
| BioFlex Laser Therapy |
| TheraDome Inc. |
| BioLight Technologies LLC |
| Apira Science Inc. |
| Lexington International |
| Ingeneus Pty. Ltd. |
| Others |
Supply & Pricing Matrix
Gallium arsenide wafer price indices cascade through photobiostimulation device manufacturing, compressing margins in LED array assembly while amplifying pricing power for precision laser diode manufacturers in Germany and Japan. Supply concentration in photonics-grade substrates forces device assemblers into long-term offtake contracts or spot market exposure, stratifying procurement costs across premium clinical systems and economy wellness installations.
Pricing Analysis
Margin tightening in professional-grade laser equipment reflects precision optics sourcing bottlenecks and extended FDA 510(k) validation timelines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared therapeutic systems from CE-marked clinical devices and unregulated wellness LED arrays. Cost-down pressure on portable home-use units accelerates because consumer channels prioritize algorithm subscription fees over hardware margins. Wellness spas exhibit highest price sensitivity; pain management clinics demonstrate lowest sensitivity due to reimbursement capture.
Supply Chain Analysis
Direct-to-clinic channels handle professional-grade laser procurement, while distributor networks serve wellness LED volume demand. German and Japanese suppliers dominate high-grade laser diode manufacturing; Chinese assemblers anchor LED array production. Component sourcing draws from gallium arsenide substrates, precision optics, and thermal management systems. Single-source vulnerability concentrates in wavelength-specific diode architectures. Distribution runs through specialized medical device distributors in North America and direct manufacturer relationships in European rehabilitation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around software-defined protocol capabilities, with EU MDR compliance costs and FDA clinical evidence requirements forcing sub-scale device developers toward acquisition or exit.
For Market Incumbents: To counter algorithm-guided consumer entrants from Asian wellness technology clusters, THOR Photomedicine Ltd. and Erchonia Corporation should deepen backward integration into wavelength-specific diode manufacturing and secure exclusive rehabilitation network partnerships. Certification investment in simultaneous FDA 510(k) and EU MDR submissions preserves channel control against mid-tier competitors. For New Entrants and Emerging Players: Enter via India's underpenetrated outpatient physiotherapy networks, where portable LED systems for post-surgical recovery face minimal incumbent saturation. Target subscription-based service bundling to compress capital expenditure barriers for mid-sized clinic chains seeking hardware financing alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor wavelength-AI convergence specialists in South Korea's Pangyo Techno Valley, where algorithm development costs exceed standalone revenue generation. Long-term viability hinges on reimbursement code alignment in Germany's KBA-aligned assessment framework and CMS coverage decisions. Monitor FDA 510(k) clearance acceleration rates as inflection signal for clinical adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Software Protocol Subscription Launch | Recurring revenue from physiotherapy chains locks clinics into manufacturer ecosystems beyond hardware replacement cycles. |
| EU MDR Clinical Evidence Investment | Randomized controlled trials at German university hospitals preempt reimbursement scrutiny from KBA-aligned assessors. |
| Precision Optics Backward Integration | Captive supply of wavelength-specific diodes insulates margin pressure from German and Japanese component suppliers. |
| Direct-to-Consumer Neurostimulation Platform | Transcranial headset algorithms penetrate North American cognitive enhancement segments outside clinical procurement channels. |
| India Rehabilitation Network Partnership | First-mover portable LED deployment captures post-surgical recovery demand in underpenetrated urban clinic networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biomedical engineers, physiotherapy clinic directors, GPO contracts managers, and photonics procurement leads at device manufacturers. FDA 510(k) clearance databases, EU MDR notified body submissions, Health Canada licensing records, and German KBA health technology assessment documentation provided regulatory trajectory validation. Bottom-up installation counts across physiotherapy chains and wellness networks triangulated against top-down photonics component trade flows.
Granularity-level modeling distinguished laser therapy equipment, LED devices, infrared systems, and combination architectures at the product tier; pain management, neurological, wound healing, musculoskeletal, and dermatological applications; and portable, wearable, standalone, and integrated therapy deployment modes. CAGRs derived from weighted scenario analysis across reimbursement expansion, regulatory pathway acceleration, and consumer adoption curves. Wavelength-AI convergence adoption rates and subscription service penetration supplied industry-specific forecast inputs across the projection horizon.
Revisions become necessary when FDA 510(k) clearance timelines extend, EU MDR notified body capacity constraints intensify, or CMS reimbursement code exclusions materialize for photobiostimulation indications. Forecasts reflect assumptions of continued KBA-aligned assessment expansion in Germany and stable gallium arsenide substrate pricing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Cyclotron Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Global Medical Composite Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Global Photomedicine Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market