
 Neuro Medical Devices Market | 2026-2036
Neuro Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro Medical Devices Market Insights
Platform licensing revenue is reconfiguring margin pools away from pure hardware sales toward software-enabled neurostimulation ecosystems. Medtronic leverages its proprietary programming platforms to sustain recurring revenue streams across implantable pulse generator portfolios. Boston Scientific anchors its competitive stance through differentiated closed-loop neurostimulation algorithms that reduce patient programming burdens. Stryker competes by extending its surgical navigation hardware into integrated monitoring systems for cranial procedures.
Neuro medical devices encompass implantable and non-implantable instruments engineered to modulate, monitor, or restore neurological function through electrical, chemical, or mechanical intervention, typically operating at signal frequencies between 2 and 180 Hz for stimulation applications and requiring biocompatible titanium or platinum-iridium electrode compositions. These systems serve primary commercial purposes in managing therapy-resistant movement disorders, chronic neuropathic pain, and epilepsy through programmed neural interface protocols. Neurostimulation devices command the deepest margin pools due to long-term implant lifecycles and proprietary programming ecosystems, while monitoring systems represent the fastest-expanding segment as ambulatory electroencephalography and intracranial pressure sensing migrate toward wireless, cloud-integrated architectures. Surgical instruments retain mature, price-competitive dynamics where commoditized neurolysis catheters and disposables face procurement consolidation from hospital networks.
FDA premarket approval pathways and EMA Medical Device Regulation (MDR) conformity assessments impose escalating clinical evidence thresholds on novel neurostimulation systems, directly shaping trial investment requirements and market access timelines for manufacturers. The European F-Gas Regulation and REACH substance restrictions further constrain insulation and sealing material choices in implantable device housings, compelling supply chain redesigns for vendors serving EU member states. Stakeholders must monitor evolving reimbursement coding for closed-loop adaptive neurostimulation and decide whether to build in-house algorithm development capabilities or license from specialized software firms.
Market Dynamics
Closed-loop adaptive neurostimulation is compressing programming visit frequency while extending implant lifecycle economics, forcing manufacturers to rebuild revenue models around algorithm licensing rather than hardware replacement cycles.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States face expanding Parkinson's disease and epilepsy caseloads as median ages rise above 45 years, sustaining procedural volume for deep brain stimulation implants.
- REACH substance restrictions:ECHA constraints on fluorinated compounds and heavy metals in implantable housings are accelerating biocompatible polymer substitution, creating first-mover advantages for compliant material suppliers.
- Ambulatory EEG migration:Wireless cloud-integrated monitoring architectures are displacing wired inpatient systems, opening reimbursement pathways for home-based seizure detection and intracranial pressure surveillance.
Market Restraints
- Platinum-iridium electrode volatility:Precious metal supply concentration in South African and Russian mining operations exposes implantable pulse generator manufacturers to input cost swings exceeding 15% annually.
- FDA premarket approval timelines:Novel neurostimulation systems face 18-36 month review cycles with escalating clinical evidence thresholds, compressing effective patent life and delaying commercialization.
- Non-invasive neuromodulation substitution:Transcranial magnetic stimulation and focused ultrasound systems are capturing therapy-resistant depression cases previously routed to implantable vagus nerve stimulation.
Strategic Opportunities
- India's underserved epilepsy population:CDSCO streamlined medical device registration and expanding private hospital networks in Mumbai and Bangalore create entry points for ambulatory monitoring systems.
- AI-enabled closed-loop algorithms:Machine learning seizure prediction converging with implantable hardware is enabling predictive stimulation that reduces battery drain and extends device longevity.
- Remote programming platforms:Telehealth reimbursement permanence under Medicare is unlocking direct-to-patient software update channels that bypass traditional clinic-based device management.
Industry Challenges
- Neural interface firmware integration:Legacy implantable pulse generators lack over-the-air update architectures, forcing surgical revision or hardware abandonment when algorithm protocols advance.
- Biocompatibility certification bottlenecks:ISO 10993 cytotoxicity and sensitization testing backlogs at notified bodies are extending EU MDR conformity assessment timelines beyond 24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro Medical Devices Market |
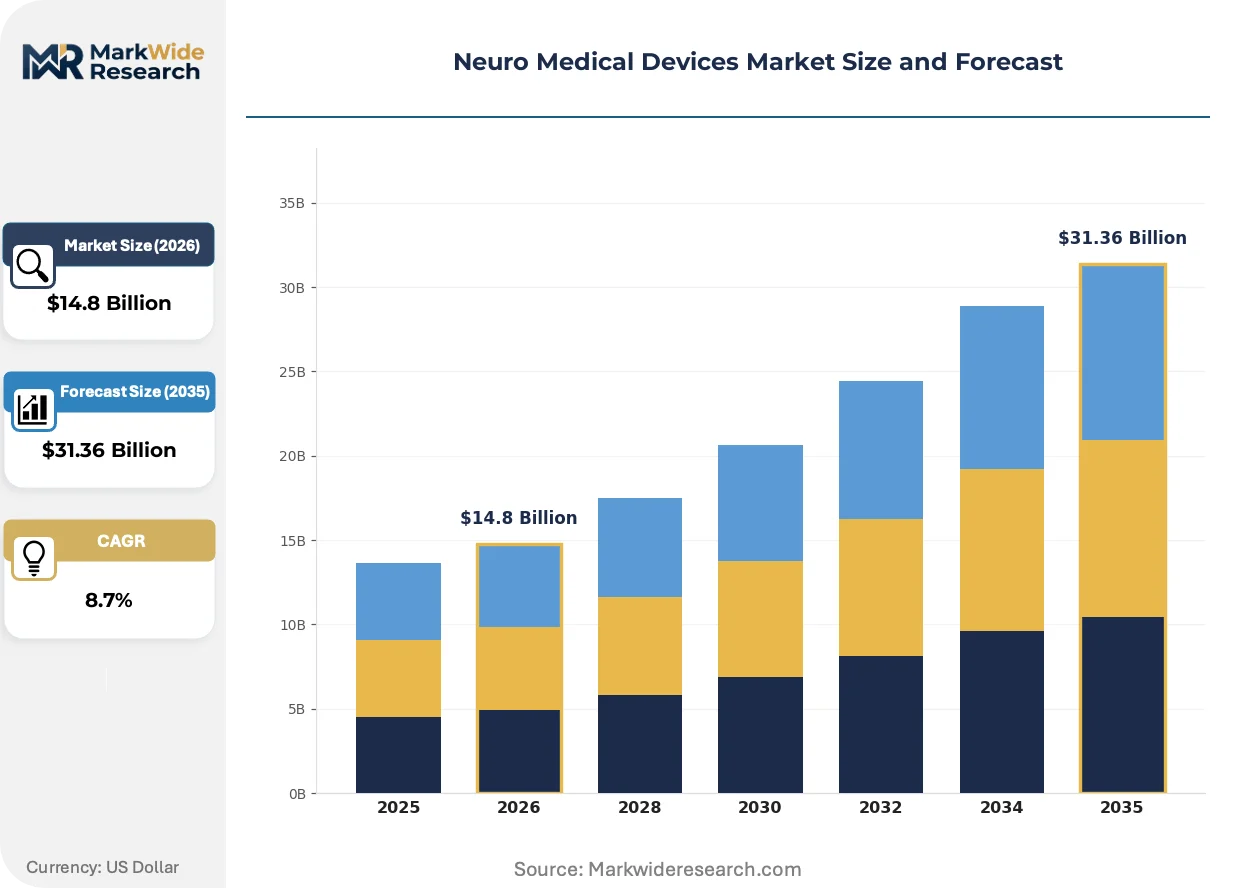
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, Neurolysis Devices, Surgical Instruments, Monitoring Systems Application: Pain Management, Functional Restoration, Diagnostics, Neurological Disorders End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Technology: Invasive Techniques, Non-invasive Techniques, Imaging Technology, Software Solutions |
| Companies Covered | Stryker, Johnson & Johnson Services, Medtronic, Koninklijke Philips, Blackrock Neurotech, Boston Scientific, Siemens Healthineers, GE Healthcare, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro Medical Devices Market Trends and Innovations
Neurostimulation ecosystems are fragmenting into modular hardware-software stacks where proprietary programming platforms capture margin previously retained by device manufacturers, while monitoring systems accelerate toward disposable, patch-based form factors.
Closed-loop adaptive stimulation is hybridizing conventional open-loop deep brain stimulation with real-time biomarker feedback, enabling automatic parameter adjustment without clinician intervention. Academic medical centers in Boston and Rotterdam are piloting these systems for movement disorders, compressing the traditional six-week programming protocol into automated titration that reduces patient travel burden and clinic capacity constraints.
EMA Medical Device Regulation and FDA Breakthrough Device Designation pathways are diverging in evidentiary requirements, forcing manufacturers to maintain parallel clinical trial infrastructures. The European F-Gas Regulation's phase-down of hydrofluorocarbon insulation compounds is compelling housing material redesigns, with implantable device vendors accelerating ceramic-to-metal sealing transitions to maintain hermeticity under stricter environmental compliance.
Hospital procurement consolidation is concentrating purchasing power within integrated delivery networks that unbundle neurostimulation hardware from long-term service contracts. Three-hundred-bed health systems in Texas and Florida are negotiating direct algorithm licensing arrangements, displacing traditional manufacturer-captive programming revenue streams and forcing vendors to price software subscriptions independently from implantable pulse generator sales.
Neuro Medical Devices Market Segmentation
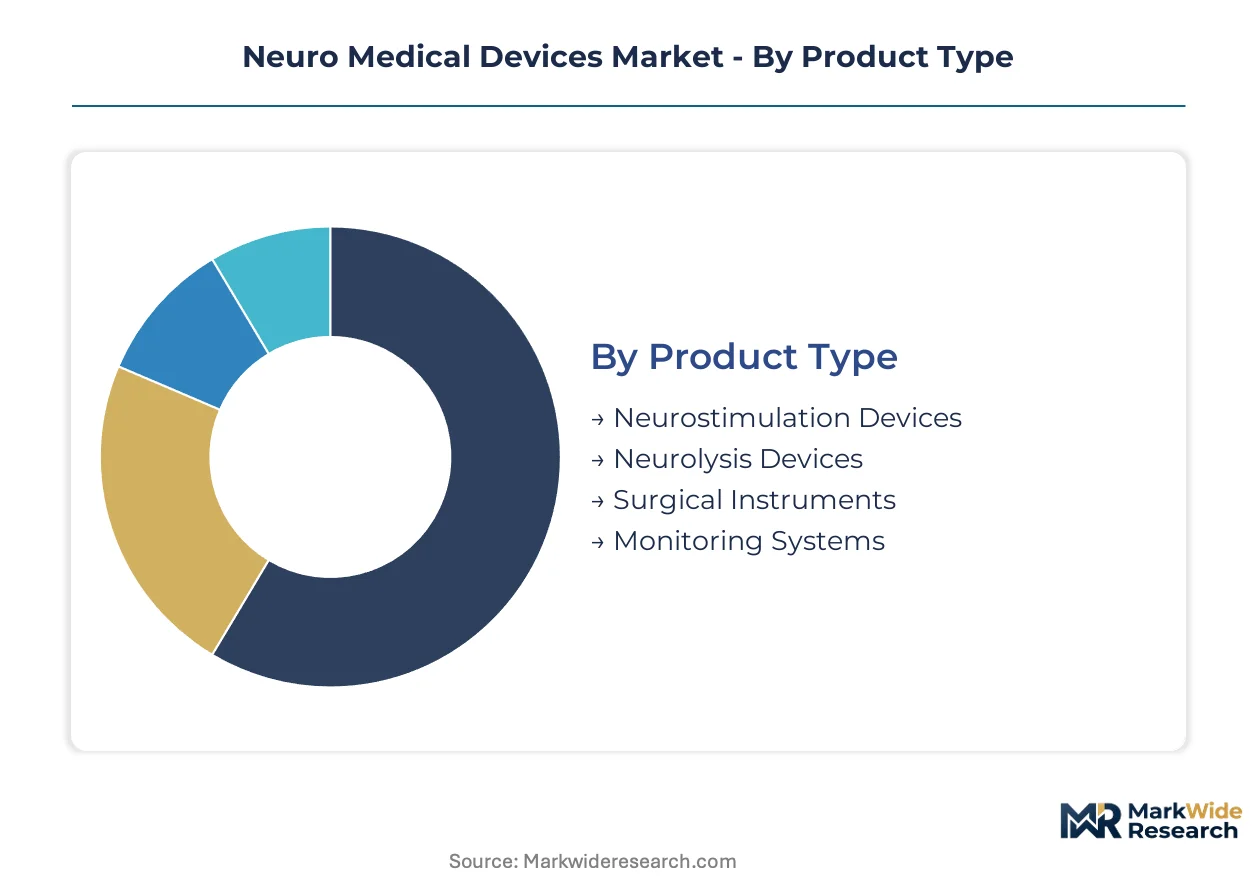
Segmentation in neuro medical devices reveals divergent lifecycle economics across hardware and software layers. Implantable systems command extended replacement cycles while monitoring platforms accelerate toward disposable, high-velocity turnover models.
Product Type:
Cycle times vary dramatically across this category, with implantable hardware stretching to multi-year lifecycles and monitoring platforms compressing toward quarterly refresh rates.
- Neurostimulation Devices:Implantable pulse generators and lead systems operating at 2-180 Hz frequencies with platinum-iridium electrode compositions. Deep brain stimulation procedures in the United States, Germany, and Japan concentrate demand as aging demographics expand Parkinson's disease caseloads and reimbursement coverage remains favorable.
- Monitoring Systems:Wireless cloud-integrated architectures for ambulatory electroencephalography and intracranial pressure sensing. Hospital procurement consolidation in Texas and Florida is unbundling hardware from service contracts, accelerating migration toward disposable patch-based form factors.
- Neurolysis Devices:Catheter-based systems for targeted nerve ablation using thermal or chemical agents.
- Surgical Instruments:Commoditized cranial access tools and disposables facing price compression from integrated delivery network consolidation.
Surgical Instruments anchors the volume base while Monitoring Systems gains share at the steepest rate.
Application:
Margin concentration follows therapy complexity, with functional restoration commanding premium pricing and diagnostics expanding through reimbursement innovation.
- Functional Restoration:Deep brain stimulation and spinal cord modulation for movement disorders. Academic medical centers in Boston and Rotterdam pilot closed-loop adaptive systems that automate parameter titration, reducing traditional six-week programming protocols.
- Pain Management:Chronic neuropathic pain interventions through implantable and external neuromodulation. REACH substance restrictions on fluorinated compounds are accelerating biocompatible polymer substitution in device housings for EU markets.
- Neurological Disorders:Epilepsy and essential tremor therapies through programmed neural interface protocols.
- Diagnostics:Seizure detection and biomarker monitoring through ambulatory architectures.
Pain Management anchors the volume base while Functional Restoration climbs the fastest as adaptive algorithms displace conventional open-loop systems.
End User:
Site-of-care migration is redistributing procurement authority from inpatient facilities toward home-based monitoring platforms.
- Hospitals:Dominant setting for implantable pulse generator placement and surgical navigation. Three-hundred-bed health systems negotiate direct algorithm licensing arrangements, displacing traditional manufacturer-captive programming revenue.
- Homecare Settings:Remote programming platforms enabled by Medicare telehealth reimbursement permanence. Direct-to-patient software update channels bypass traditional clinic-based device management.
- Clinics:Outpatient programming and parameter adjustment for implanted systems.
- Rehabilitation Centers:Post-implant functional recovery and neuroplasticity training.
Hospitals anchors the volume base while Homecare Settings expands most quickly as wireless architectures enable reimbursement for remote surveillance.
Technology:
Development intensity stratifies sharply between mature invasive hardware and emerging software-defined platforms.
- Software Solutions:Proprietary programming platforms and AI-enabled closed-loop algorithms. Machine learning seizure prediction converges with implantable hardware to enable predictive stimulation that reduces battery drain.
- Imaging Technology:Surgical navigation integration for cranial procedure planning. Stryker extends its surgical navigation hardware into integrated monitoring systems for precise electrode placement.
- Invasive Techniques:Implantable pulse generators and lead systems with biocompatible titanium housings.
- Non-invasive Techniques:Transcranial magnetic stimulation and focused ultrasound systems capturing therapy-resistant depression cases.
Invasive Techniques anchors the volume base while Software Solutions shows the steepest expansion trajectory as platform licensing reconfigures margin pools away from pure hardware sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany exhibit limited price elasticity due to comprehensive reimbursement frameworks, while procurement teams in India and Brazil face constrained budgets that prioritize cost-efficient monitoring solutions over premium implantable systems.
United States
Medicare telehealth reimbursement permanence unlocks direct-to-patient software channels for remote programming platforms. FDA premarket approval pathways impose 18-36 month review cycles with escalating clinical evidence thresholds. Academic medical centers in Boston pilot closed-loop adaptive neurostimulation systems that automate parameter titration protocols.
Germany
Aging demographics above median age 45 sustain Parkinson's disease procedural volumes for deep brain stimulation implants. EMA Medical Device Regulation conformity assessments and REACH substance restrictions on fluorinated compounds compel housing material redesigns. Industrial clusters in Baden-Württemberg concentrate surgical navigation hardware manufacturing for cranial procedures.
Japan
Expanded Parkinson's disease and epilepsy caseloads drive demand for implantable pulse generators as median ages rise. PMDA regulatory pathways align with international standards while maintaining distinct documentation requirements. Tokyo-based health systems negotiate direct algorithm licensing arrangements that displace traditional manufacturer-captive programming revenue.
India
CDSCO streamlined medical device registration creates entry points for ambulatory monitoring systems targeting underserved epilepsy populations. Private hospital networks in Mumbai and Bangalore expand neurosurgical capacity for implantable device placement. Procurement consolidation within three-hundred-bed health systems prioritizes cost-efficient wireless cloud-integrated architectures over premium hardware.
United Kingdom
NHS reimbursement frameworks for movement disorder therapies sustain procedural volumes for functional restoration applications. MHRA post-Brexit regulatory autonomy diverges from EMA pathways on clinical evidence requirements. London and Southeast England concentrate specialized epilepsy surgery centers that adopt closed-loop adaptive stimulation protocols.
Neuro Medical Devices Market Competitive Landscape
Capability concentration sits with algorithm developers and proprietary platform holders; scale advantage sits with diversified medical technology conglomerates with established surgical navigation portfolios. The vendor base stratifies across three tiers: integrated hardware-software ecosystem providers, specialized neurostimulation device manufacturers, and commoditized surgical instrument suppliers. Dominant competitive moves include strategic partnerships for AI-enabled closed-loop algorithm development and geographic expansion into India's private hospital networks.
Within the integrated ecosystem tier, Medtronic and Boston Scientific exemplify platform-centric positioning that captures recurring revenue through proprietary programming architectures. Stryker anchors the surgical navigation-to-monitoring integration vector. Johnson & Johnson Services, Koninklijke Philips, and Siemens Healthineers represent diversified health technology conglomerates with neuro device exposure alongside broader imaging and diagnostic portfolios.
| Leading Market Players |
|---|
| Stryker |
| Johnson & Johnson Services |
| Medtronic |
| Koninklijke Philips |
| Blackrock Neurotech |
| Boston Scientific |
| Siemens Healthineers |
| GE Healthcare |
| Abbott |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp freight corridors carry biocompatible titanium and platinum-iridium electrode materials from South African mining operations to European device manufacturers, with container rates compressing procurement economics for implantable pulse generator vendors while amplifying price differentiation between integrated and non-integrated supply chain models.
Pricing Analysis
Long-term offtake contracts dominate procurement for platinum-iridium electrodes and biocompatible titanium housings, insulating large manufacturers from spot market volatility while smaller competitors absorb 15% annual input cost swings. Price differentiation separates FDA Breakthrough Device Designation holders from CE-marked-only competitors, with certification tier and vertical integration into proprietary programming platforms commanding premium positioning. Cost compression in commoditized surgical instruments is intensifying because hospital procurement consolidation in Texas and Florida unbundles hardware from service contracts. Integrated delivery networks exhibit lowest price sensitivity for closed-loop adaptive systems, while private hospital networks in India prioritize cost-efficient wireless monitoring architectures.
Supply Chain Analysis
Export control regimes limiting dual-use neurotechnology flows constrain semiconductor and firmware component transfers to certain manufacturing jurisdictions, compelling device vendors to maintain parallel supply chains for implantable pulse generator control electronics. Manufacturing concentrates in the United States, Germany, and Japan for final device assembly, while South Africa and Russia anchor platinum-iridium electrode raw material extraction. Component dependencies center on biocompatible titanium alloys, hermetic ceramic-to-metal seals, and application-specific integrated circuits for neural signal processing. Single-source vulnerability in precious metal supply exposes manufacturers to geopolitical disruption. Distribution runs through hospital purchasing committees and group purchasing organizations in developed markets, with direct-to-hospital contracting accelerating in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive neuromodulation substitutes—transcranial magnetic stimulation and focused ultrasound systems—are capturing therapy-resistant depression cases that previously flowed to implantable vagus nerve stimulation, forcing incumbents to defend hardware-software ecosystem lock-in against external substitution threats.
For Market Incumbents: Build algorithm licensing moats through proprietary closed-loop platforms that automate parameter titration and capture recurring revenue independent of hardware replacement cycles. Secure backward integration into biocompatible polymer housing production to preempt REACH substance restriction compliance costs. Defend against non-invasive neuromodulation substitution by embedding predictive stimulation capabilities that extend device longevity beyond external alternatives. For New Entrants and Emerging Players: Pursue India's underserved epilepsy population through CDSCO-registered ambulatory EEG systems targeting private hospital networks in Mumbai and Bangalore. Penetrate the homecare monitoring segment where Medicare telehealth reimbursement permanence unlocks direct-to-patient software channels bypassing incumbent clinic relationships. Deploy AI-enabled seizure prediction as a differentiated go-to-market wedge against legacy wired inpatient systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates with underutilized neuro device assets trapped within broader imaging and diagnostic portfolios. Long-term viability favors platform-centric positioning with recurring software revenue over pure hardware manufacturing. Monitor FDA premarket approval timeline compression as an inflection signal—accelerated review cycles for breakthrough-designated closed-loop systems would validate algorithm-heavy business models and trigger consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Algorithm Development | Machine learning seizure prediction converging with implantable hardware reduces battery drain and extends device replacement cycles. |
| CE Marking Pathway Investment | EMA MDR conformity assessments exceeding 24 months create first-mover advantage for notified body relationships and technical documentation. |
| Hospital System Partnership | Three-hundred-bed health systems in Texas and Florida negotiate direct algorithm licensing arrangements displacing traditional manufacturer-captive revenue. |
| Biocompatible Polymer Substitution | REACH restrictions on fluorinated compounds accelerate housing material redesigns with compliant suppliers capturing EU market access. |
| Remote Programming Platform Launch | Medicare telehealth reimbursement permanence unlocks direct-to-patient software update channels bypassing clinic-based device management. |
Research Methodology
A standing panel of implantable pulse generator program directors, hospital purchasing committee chairs, biomedical engineers specializing in neural interfaces, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) and PMA filings, EMA MDR technical documentation databases, CMS Medicare reimbursement coding updates, and hospital procurement contract disclosures. Bottom-up demand modeling for implantable and monitoring device volumes triangulated against top-down manufacturer revenue assessments.
Scenario bracketing anchored the analytical framework across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled include product type, application, end user, and technology layer with software-versus-hardware revenue mix tracked separately. CAGRs derived from procedural volume trajectories, replacement cycle compression from adaptive algorithms, and reimbursement pathway expansion for home-based monitoring. Forecast inputs incorporated PMDA regulatory alignment timelines and CDSCO registration streamlining effects on emerging market penetration.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, precious metal commodity prices, or telehealth reimbursement permanence would shift the trajectory. Forecasts reflect documented assumptions on regulatory review cycle durations and algorithm adoption curves. Material shifts in FDA breakthrough designation evidentiary requirements or EMA MDR notified body capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Smart Bassinet Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Bariatric Beds Market
Medical Devices
Allografts Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Interspinous Process Decompression Devices Market