
 Pulmonology Devices Market | 2026-2036
Pulmonology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonology Devices Market Outlook
Hospital procurement consolidation is realigning vendor relationships across the pulmonology devices landscape. Medtronic plc leverages its integrated care platforms to secure long-term supply contracts with consolidated health systems. ResMed Inc. anchors its position through dedicated sleep-disordered breathing portfolios that hospital networks increasingly standardize around. Philips Respironics competes by extending its remote patient monitoring capabilities into outpatient workflows.
Pulmonology devices encompass diagnostic, therapeutic, and monitoring instruments engineered to measure lung function, deliver aerosolized medication, or provide mechanical ventilatory support with precision-calibrated flow rates and pressure algorithms. These systems serve the clinical imperative of managing obstructive and restrictive respiratory pathologies across acute, sub-acute, and chronic care continuums. Smart inhalers command premium positioning as connectivity integration reshapes adherence monitoring and real-world evidence collection. Portable spirometers represent the fastest-expanding technology segment, propelled by point-of-care decentralization and telemedicine solution bundling. Nebulizers retain mature volume status in emergency departments, though margin pools increasingly migrate toward home-compatible, mesh-based delivery platforms.
The FDA governs premarket clearance pathways for novel respiratory devices, while the EPA regulates ozone-emitting oxygen concentrator technologies under ambient air quality statutes. ISO 13485 certification and EU MDR conformity requirements shape export feasibility for manufacturers targeting European health system tenders. Stakeholders must monitor reimbursement coding shifts for connected respiratory therapies as payors recalibrate coverage frameworks for digital health integration.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating long-term service contracts over transactional equipment sales. Integrated delivery networks now demand outcome guarantees and remote monitoring integration from pulmonology device suppliers.
Growth Catalysts
- FDA's evolving guidance on connected inhaler technologies:The regulatory pathway clarity accelerates digital respiratory product development timelines. Manufacturers gain confidence to invest in sensor-integrated delivery systems.
- Home care settings:Post-acute respiratory management is migrating from hospital wards to residential environments. Patients with COPD and sleep apnea now expect portable diagnostic and therapeutic options.
- Reimbursement infrastructure expansion:United States payors are establishing dedicated coding frameworks for remote patient monitoring of chronic respiratory conditions. This financial infrastructure removes adoption barriers for connected devices.
Market Restraints
- Supply concentration in semiconductor components:Mesh nebulizer and smart inhaler production depends on specialized sensor chips sourced from limited East Asian foundries. Geopolitical friction threatens continuity.
- EU MDR conformity assessment bottlenecks:Extended notified body capacity constraints delay European market entry for novel spirometry platforms. Certification timelines now stretch twenty-four to thirty-six months.
- Oxygen concentrator ozone emission thresholds:EPA ambient air quality statutes impose costly filtration upgrades on home oxygen generation equipment. Compliance adds manufacturing overhead without clinical differentiation.
Strategic Opportunities
- Rural and frontier United States territories:Federally qualified health centers in Appalachian and Southwestern regions lack respiratory diagnostic infrastructure. Portable spirometry bundling with telemedicine platforms addresses this gap.
- Convergence of artificial intelligence with acoustic respiratory monitoring:Machine learning algorithms trained on cough and wheeze patterns enable predictive exacerbation alerts. This technology pairing creates new service revenue streams.
- Direct-to-patient subscription channels:Sleep apnea mask and tubing resupply is bypassing durable medical equipment intermediaries. Manufacturers capturing this channel gain margin recovery and adherence data ownership.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification bodies for medical device quality management systems face capacity constraints. Small and mid-sized manufacturers encounter twelve-month delays in surveillance audits.
- Legacy electronic health record integration complexity:Pulmonology device data streams require custom HL7 FHIR mapping for each hospital system. Engineering resources fragment across incompatible interoperability demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonology Devices Market |
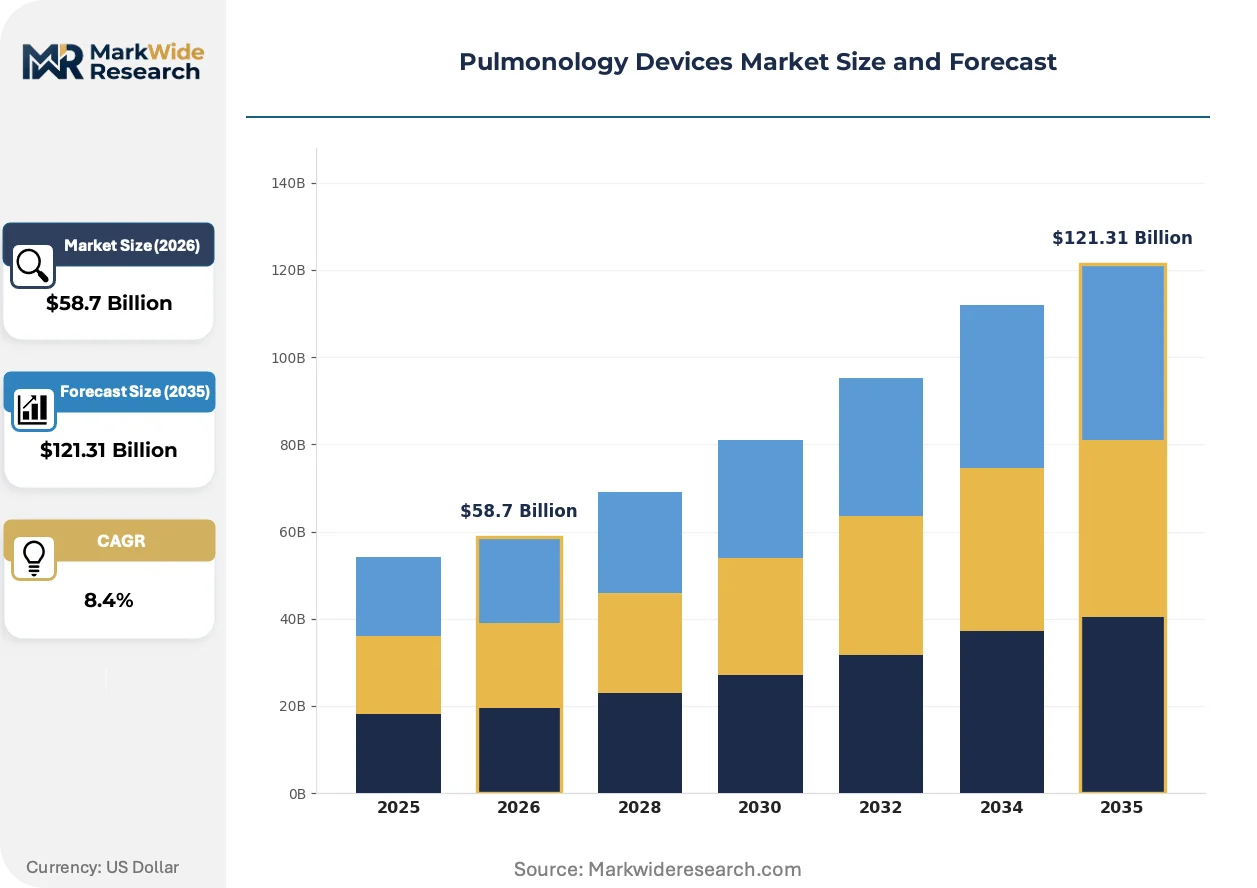
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Nebulizers, Inhalers, Oxygen Concentrators End User: Hospitals, Outpatient Clinics, Home Care Settings, Medical Research Institutions Technology: Smart Inhalers, Portable Spirometers, Non-Invasive Ventilation, Telemedicine Solutions Application: Asthma, COPD, Pulmonary Hypertension, Sleep Apnea |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Medtronic plc, ResMed Inc., Philips Respironics, Ambu A/S, CONMED Corporation, Fisher & Paykel Healthcare, Cook Medical Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonology Devices Market Strategic Shifts
Connectivity integration is redefining how respiratory therapies are prescribed, monitored, and reimbursed. Data generation from inhalation devices now rivals clinical biomarkers in payer decision frameworks.
Mesh-based nebulizer technology is overtating compressor-driven aerosol delivery in home care segments. Patients with cystic fibrosis and severe asthma are adopting silent, portable units that eliminate medication waste through precise particle sizing. The structural consequence is margin compression for legacy compressor manufacturers as reimbursement codes favor efficiency metrics.
REACH substance restriction protocols are compelling reformulation of device polymers and coatings. European manufacturers must eliminate certain phthalates and brominated flame retardants from ventilator housings and circuit components. Spirometer mouthpiece suppliers face particular pressure to certify biocompatible alternatives before the next authorization deadline.
Hospital equipment committees now bundle respiratory diagnostics with multi-year service and data analytics contracts. Traditional capital purchase models are yielding to per-patient or per-test pricing arrangements. This shift is most visible in United States integrated delivery networks standardizing around single-vendor pulmonary function testing platforms.
Pulmonology Devices Market Segmentation
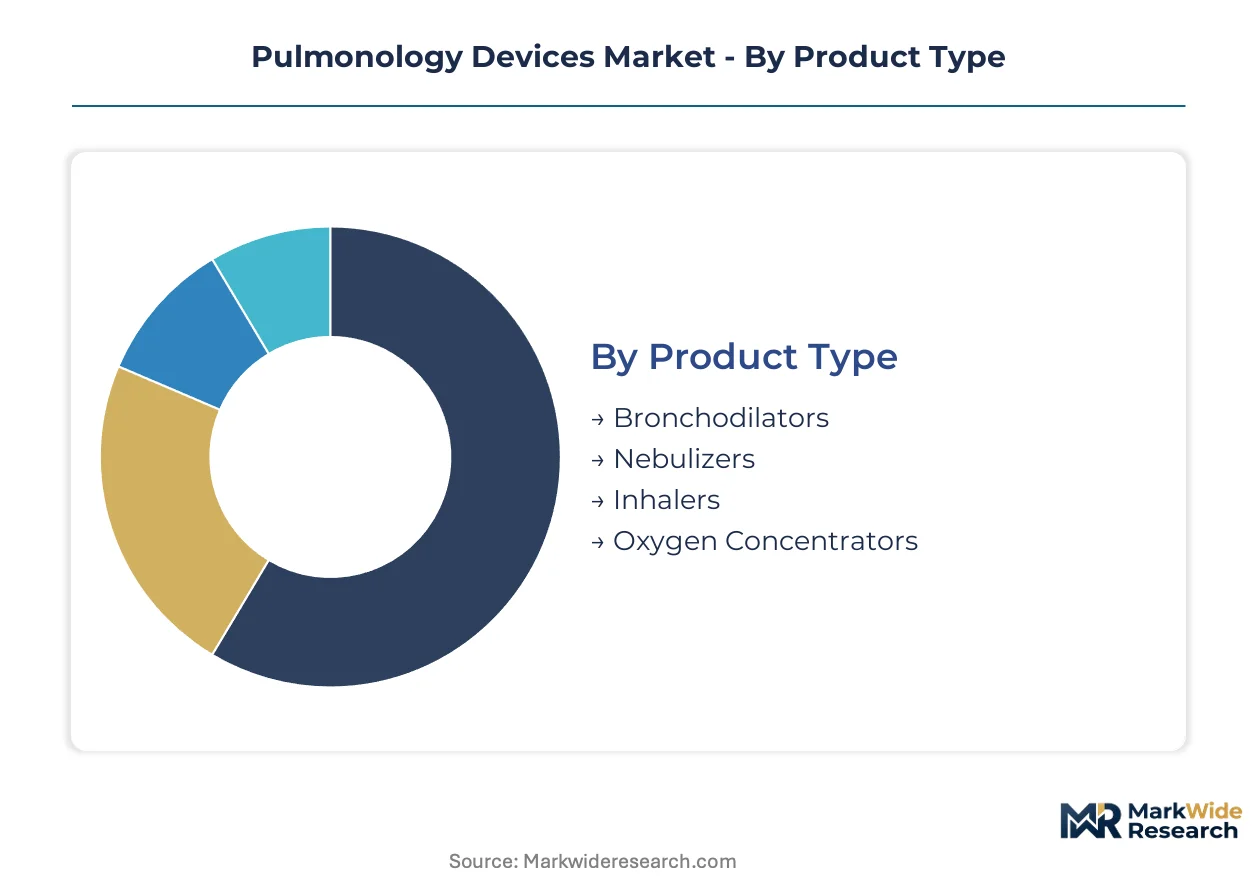
Pulmonology device procurement patterns diverge sharply across clinical settings and patient acuity levels. Supply chain configuration for each segment determines margin capture and vendor lock-in potential.
Product Type:
Component sourcing intensity clusters around sensor-integrated delivery systems and precision flow-control mechanisms.
- Inhalers:Metered-dose and dry-powder platforms dominate prescription volumes across United States pharmacy channels. Connectivity integration through Bluetooth-enabled adherence tracking is reshaping reimbursement eligibility in Medicare Advantage plans.
- Nebulizers:Mesh-based ultrasonic systems displace compressor-driven alternatives in home care environments. Silent operation and reduced medication waste attract COPD patients in Germany and Japan seeking residential therapy independence.
- Bronchodilators:Combination long-acting beta-agonist and corticosteroid formulations require specialized actuator manufacturing.
- Oxygen Concentrators:Pressure-swing adsorption units face EPA ozone emission compliance costs without clinical differentiation.
Today's leader: Inhalers. Tomorrow's challenger: Nebulizers.
End User:
Procurement authority and reimbursement pathway complexity fragment demand across institutional and residential channels.
- Home Care Settings:Patients with chronic respiratory conditions now manage therapies outside acute facilities. United States durable medical equipment suppliers bundle portable diagnostics with remote monitoring subscriptions.
- Hospitals:Integrated delivery networks consolidate pulmonary function testing platforms under multi-year service contracts. Medtronic and ResMed secure vendor standardization through outcome guarantees and data analytics integration.
- Outpatient Clinics:Federally qualified health centers in rural United States territories lack diagnostic infrastructure.
- Medical Research Institutions:Academic medical centers drive protocol development for novel therapeutic delivery mechanisms.
Volume concentrates in home care settings. Value capture accelerates fastest in hospital networks.
Technology:
Development resource allocation tracks regulatory pathway clarity and reimbursement coding maturity.
- Smart Inhalers:Sensor-integrated devices capture real-world adherence data for payor decision frameworks. FDA guidance evolution accelerates premarket submission confidence among manufacturers investing in digital respiratory platforms.
- Portable Spirometers:Handheld diagnostic units enable point-of-care lung function assessment outside traditional laboratory settings. Telemedicine platform bundling in United States rural health clinics addresses infrastructure gaps.
- Non-Invasive Ventilation:Bilevel positive airway pressure systems serve sleep-disordered breathing populations.
- Telemedicine Solutions:Remote patient monitoring integration requires custom HL7 FHIR mapping for each hospital electronic health record system.
Smart inhalers command premium positioning. Portable spirometers climb the fastest.
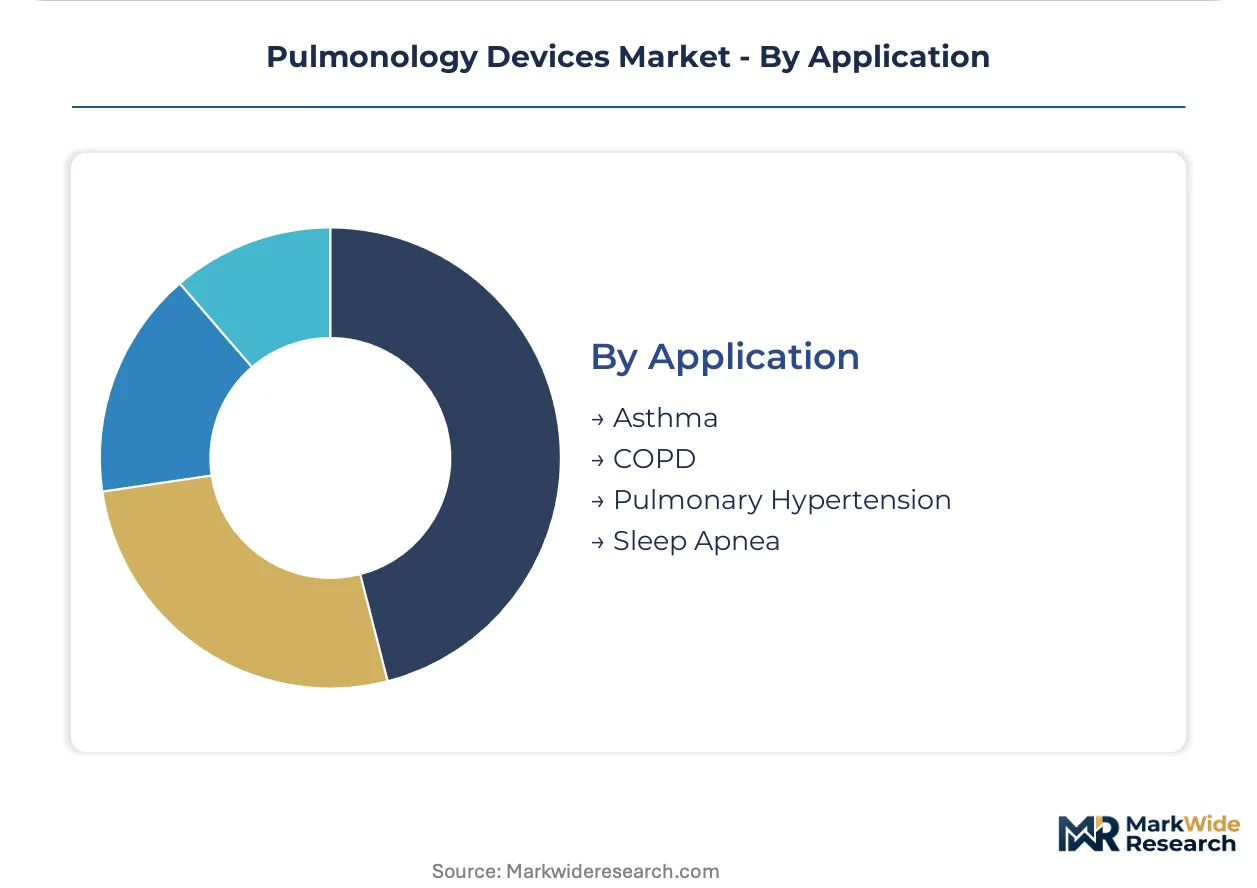
Application:
Disease prevalence and therapy chronicity determine device utilization intensity and replacement cycle frequency.
- COPD:Progressive airflow limitation drives continuous oxygen therapy and bronchodilator dependence. United States Medicare reimbursement infrastructure supports home oxygen concentrator and nebulizer resupply channels.
- Sleep Apnea:Positive airway pressure therapy generates recurring mask and tubing replacement demand. Direct-to-patient subscription models bypass durable medical equipment intermediaries for margin recovery.
- Asthma:Pediatric and adult populations require rescue and controller medication delivery platforms.
- Pulmonary Hypertension:Specialized inhaled prostacyclin therapy demands precision delivery systems.
COPD anchors installed base. Sleep apnea reshapes distribution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement infrastructure outpaces German coding maturity for connected respiratory therapies, while Japanese aging demographics accelerate home oxygen concentrator demand faster than United Kingdom procurement timelines.
United States
Medicare Advantage plans now mandate Bluetooth-enabled adherence tracking for preferred inhaler tier placement, while FDA premarket submission confidence climbs for sensor-integrated delivery systems. The EPA enforces ambient air quality statutes on home oxygen generation equipment, compelling costly filtration upgrades. Boston and the Research Triangle anchor telemedicine platform bundling with portable spirometry for rural federally qualified health centers.
Germany
Silent mesh nebulizer adoption among COPD patients seeking residential therapy independence exceeds compressor-driven replacement rates in outpatient settings. EU MDR conformity assessment bottlenecks stretch certification timelines to twenty-four months for novel spirometry platforms. Baden-Württemberg's medical technology cluster concentrates precision flow-control mechanism manufacturing for EU hospital tenders.
Japan
Pressure-swing adsorption unit demand from aging households with progressive airflow limitation outstrips acute facility procurement growth. METI standards guide domestic connectivity integration for real-world evidence collection platforms. Osaka-Kobe industrial corridor hosts specialized actuator manufacturing for combination bronchodilator formulations serving East Asian pharmacy channels.
China
Domestic production of portable diagnostic units for point-of-care lung function assessment scales faster than import dependency for premium sleep-disordered breathing systems. NMPA regulatory pathway evolution accelerates premarket clearance for digital respiratory platforms with local data residency requirements. Yangtze River Delta medical device parks concentrate sensor chip integration for smart inhaler contract manufacturing.
United Kingdom
NHS integrated care systems standardize pulmonary function testing platforms under multi-year service contracts with outcome guarantees, compressing transactional equipment sales. MHRA post-Brexit conformity assessment capacity constraints delay European market entry timelines for novel platforms. London-Southeast medtech corridor anchors remote patient monitoring integration engineering for HL7 FHIR mapping customization.
Pulmonology Devices Market Competitive Environment
United States producers anchor the premium connectivity tier; European specialists hold diagnostic precision positioning. Hospital procurement consolidation compresses vendor margins while elevating long-term service contracts over equipment transactions. Three archetypes dominate: integrated care platform vendors, dedicated sleep-disordered breathing portfolio holders, and remote monitoring capability extenders. Competitive moves concentrate on securing vendor standardization through outcome guarantees and custom electronic health record interoperability engineering.
Within the integrated delivery network tier, Medtronic plc and ResMed Inc. exemplify archetype consolidation. Philips Respironics occupies a position representing remote monitoring extension strategies. Olympus Corporation and Boston Scientific Corporation sit within the diagnostic precision cluster, anchoring bronchoscopy and interventional pulmonology equipment supply relationships.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Medtronic plc |
| ResMed Inc. |
| Philips Respironics |
| Ambu A/S |
| CONMED Corporation |
| Fisher & Paykel Healthcare |
| Cook Medical Incorporated |
| Others |
Value Chain & Pricing Dynamics
Mesh nebulizer production scaling in East Asian manufacturing corridors is compressing unit economics while concentrating sensor chip sourcing decisions among a narrowing supplier base. This dual transformation elevates procurement leverage for volume buyers and squeezes margin recovery for mid-tier device assemblers lacking captive component supply.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for portable diagnostic units as domestic manufacturers achieve ISO 13485 certification and compete for European hospital tenders. Three-tier pricing structure across premium, standard, and economy levels differentiates by connectivity integration depth and FDA premarket submission tier, with Medicare Advantage plans driving adherence toward Bluetooth-enabled tiers. Pricing pressure stems from GPO consolidation in United States integrated delivery networks demanding outcome guarantees alongside equipment procurement. Federally qualified health centers in rural territories exhibit highest price sensitivity, while academic medical centers prioritize precision metrics over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for sensor-integrated inhaler platforms, bypassing traditional durable medical equipment intermediaries. Component manufacturing concentrates in China, Taiwan, and Japan, with pressure-swing adsorption units for oxygen concentrators drawing from precision valve suppliers in Germany. Specialized MEMS sensors for smart inhalers rest on single-source foundry relationships vulnerable to geopolitical friction. Distribution runs through consolidated hospital procurement committees and direct-to-patient subscription platforms for sleep apnea resupply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pulmonology devices market functions as a regulatory compounder where FDA guidance evolution on connected inhaler technologies continuously resets competitive entry thresholds and reimbursement eligibility criteria.
For Market Incumbents: Extend remote patient monitoring integration into outpatient workflows to secure vendor standardization contracts with consolidating health systems. Deepen backward integration into sensor chip supply through strategic foundry partnerships, countering emerging entrant cost advantages in mesh nebulizer assembly. Invest in HL7 FHIR interoperability engineering teams to reduce fragmentation across incompatible hospital electronic health record systems. For New Entrants and Emerging Players: The gap between premium smart inhaler pricing and economy compressor nebulizer tiers creates entry space for mid-market portable spirometry bundling with telemedicine platforms. Target federally qualified health centers in Appalachian and Southwestern United States territories lacking respiratory diagnostic infrastructure. Pursue direct-to-patient subscription channels for sleep apnea mask resupply, capturing margin recovery and adherence data ownership bypassing durable medical equipment intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among diagnostic precision specialists with EU MDR conformity assessment bottlenecks delaying revenue recognition. Long-term viability favors manufacturers with captive supply of specialized flow-control mechanisms and established reimbursement coding relationships. Watch FDA premarket submission confidence indices for sensor-integrated delivery systems as inflection indicator for digital respiratory platform investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Regulatory pathway clarity accelerates digital respiratory product development timelines for connected inhalers. |
| CE Marking Pathway | EU MDR conformity assessment bottlenecks stretch certification timelines to twenty-four months for novel spirometry platforms. |
| Hospital System Partnership | Integrated delivery networks consolidate pulmonary function testing platforms under multi-year service contracts with outcome guarantees. |
| Software Companion Development | Machine learning algorithms trained on cough patterns enable predictive exacerbation alerts and new service revenue streams. |
| Reimbursement Strategy | Medicare Advantage plans mandate Bluetooth-enabled adherence tracking for preferred inhaler tier placement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and pulmonology clinicians with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body registries. Bottom-up segment sizing and top-down market triangulation cross-verified volume estimates across product type, end user, technology, and application dimensions.
Historical reference periods anchored the projection horizon, with CAGR derivation reflecting installed base replacement cycles, reimbursement coding maturity timelines, and connectivity adoption curves across chronic respiratory disease populations. Modeled segmentation spanned product type, clinical setting, technology tier, and disease application, incorporating sensor chip supply constraints, EPA ozone emission compliance costs, and telemedicine platform bundling velocity as industry-specific forecast inputs.
Caveats apply where FDA guidance revisions, EU MDR notified body capacity constraints, or semiconductor supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global External Fixators Market
Medical Devices
Artificial Corneal Implants Market