
 Empty IV Bags Market | 2026-2036
Empty IV Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Empty IV Bags Market Intelligence
Capital-intensity divergence between large-format extrusion specialists and regional converters is unwinding competitive stability in empty IV bag supply. ICU Medical, Inc. leverages captive film production to control resin specifications across multi-chamber designs. Baxter International anchors North American hospital contracts through integrated distribution networks that bypass wholesale intermediaries. Fresenius Kabi AG competes on parenteral nutrition compatibility testing, a niche where material certification requirements exceed standard infusion specifications.
Empty IV bags are flexible, sealed polymer containers manufactured through multi-layer extrusion, radio-frequency welding, and terminal sterilization, designed to store and administer sterile fluids, medications, or nutritional solutions via intravenous infusion. Polyolefin formulations now displace legacy polyvinyl chloride in oncology and neonatal applications where plasticizer leaching risks alter therapeutic safety profiles. Sterile single-chamber configurations dominate hospital procurement through economies of scale, while multi-chamber designs for parenteral nutrition command premium positioning due to compounding complexity and reduced contamination protocols. Homecare channels show structural momentum as ambulatory infusion expands, though reimbursement fragmentation constrains volume conversion from acute settings.
The FDA enforces biocompatibility and extractables testing under ISO 10993 for all polymer contact layers, while the EU Medical Device Regulation mandates notified body oversight for sterile empty containers classified as Class IIa devices. These frameworks elevate compliance costs for film converters lacking in-house toxicology capabilities, effectively filtering market access toward vertically integrated manufacturers. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions on fluorinated barrier films, as alternative oxygen-scavenging technologies remain unproven at clinical scale.
Market Dynamics
The FDA's phased scrutiny of di-ethylhexyl phthalate in PVC medical devices is forcing accelerated material transitions toward polyolefin alternatives, compressing legacy converter margins while elevating compliance costs for non-integrated manufacturers.
Growth Catalysts
- Aging demographics in the United States:Surgical caseloads and chronic disease management sustain elevated parenteral therapy volumes in acute care settings, driving replacement demand for single-use containers.
- EU Medical Device Regulation Class IIa classification:Notified body oversight for sterile empty containers filters market access toward vertically integrated manufacturers with in-house toxicology capabilities.
- Multi-layer radio-frequency welding:Advances in barrier film lamination enable oxygen-scavenging performance without fluorinated chemistries, opening oncology and neonatal segments previously restricted by plasticizer leaching risks.
Market Restraints
- Resin specification volatility:Polyolefin formulation costs fluctuate with propylene feedstock pricing, squeezing film converter margins on fixed-price hospital contracts.
- Capital intensity divergence:Large-format extrusion equipment requirements exceed regional converter financing capacity, consolidating supply among captive film producers.
- EPA per- and polyfluoroalkyl substance restrictions:Pending limitations on fluorinated barrier films threaten oxygen barrier performance in parenteral nutrition applications where alternative technologies remain clinically unproven.
Strategic Opportunities
- Ambulatory infusion expansion:Homecare channels show structural momentum as reimbursement frameworks stabilize for outpatient parenteral therapy, though volume conversion from acute settings remains fragmented.
- ISO 10993 biocompatibility certification:Third-party toxicology validation creates service-layer revenue for manufacturers with in-house extractables testing laboratories.
- Multi-chamber compounding designs:Parenteral nutrition compatibility testing requirements exceed standard infusion specifications, commanding premium positioning through reduced contamination protocols.
Industry Challenges
- Polymer toxicology expertise scarcity:Film converters lacking in-house biocompatibility assessment capabilities face extended FDA pre-submission timelines and 510(k) clearance delays.
- Terminal sterilization validation:Gamma irradiation dose mapping for multi-layer films requires capital-intensive dosimetry infrastructure that regional converters struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Empty IV Bags Market |
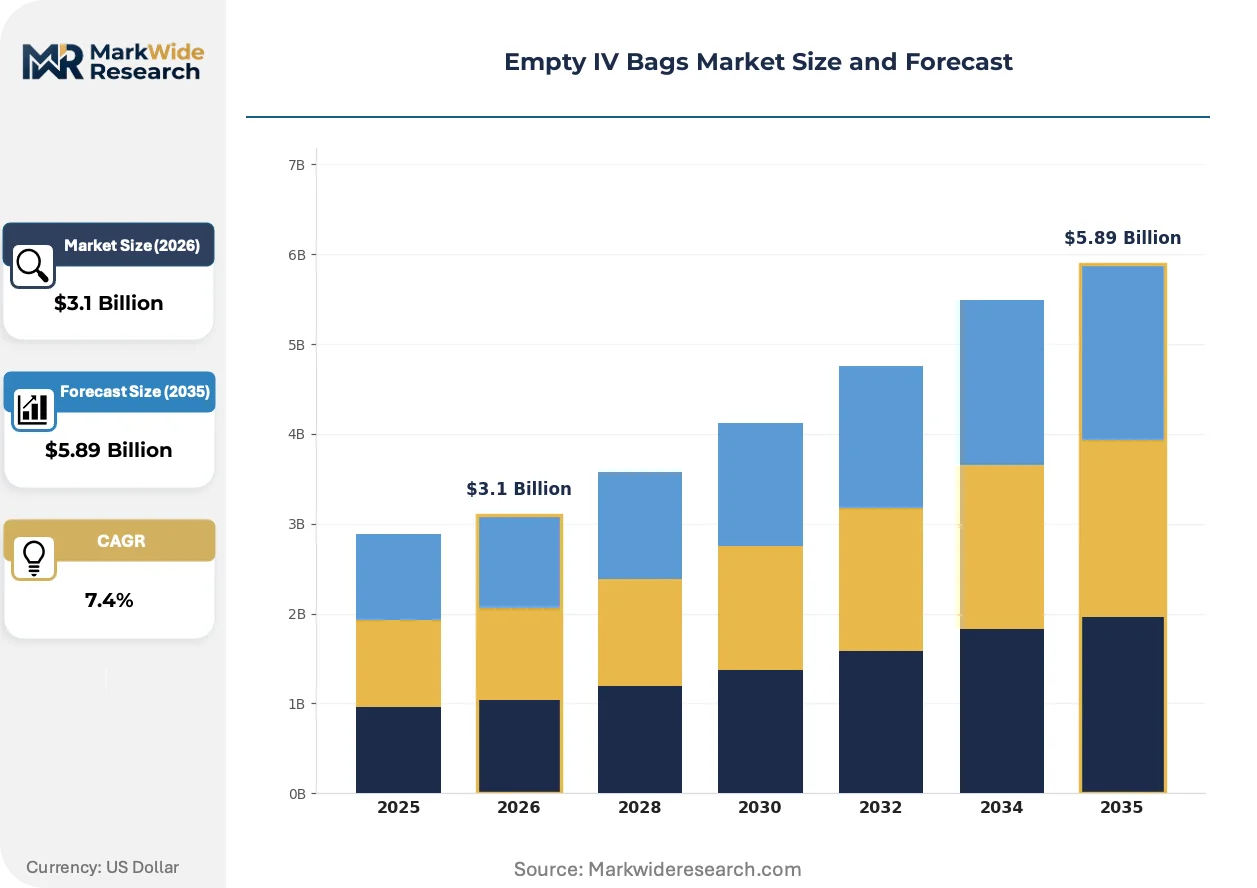
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Non-Sterile, Sterile, Multi-Chamber, Single-Chamber Material: Polyvinyl Chloride, Polyolefin, Ethylene Vinyl Acetate, Others End User: Hospitals, Homecare, Clinics, Pharmacies Application: Fluid Replacement, Nutrient Delivery, Medication Delivery, Parenteral Nutrition |
| Companies Covered | ICU Medical, Inc., Wipak, Baxter International, Technoflex, RENOLIT SE, B. Braun Medical Inc., Fresenius Kabi AG, POLYCINE GmbH, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Empty IV Bags Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are actively splitting the competitive landscape between legacy PVC converters and polyolefin specialists. Three developments warrant particular attention.
Multi-layer coextrusion technology is bifurcating the supply base. This manufacturing approach bonds distinct polymer grades into unified films with tailored permeation resistance. Oncology and neonatal units in tertiary hospitals are adopting these configurations fastest, compressing demand for legacy single-material containers and rewarding converters with captive lamination capacity.
REACH restrictions on phthalate plasticizers are accelerating PVC displacement timelines across European hospital procurement. The ECHA authorization requirements for DEHP in medical devices are compelling contract manufacturers to validate polyolefin alternatives ahead of sunset dates. German and French hospital groups now specify phthalate-free containers in tender documents, shifting supplier qualification criteria.
Integrated distribution networks are displacing wholesale intermediaries in North American hospital contracting. Manufacturers with direct logistics infrastructure capture preference through reduced lead times and lot-traceability guarantees. This pattern concentrates procurement volume among vertically integrated suppliers while fragmenting regional converter access to tier-one health systems.
Empty IV Bags Market Segmentation
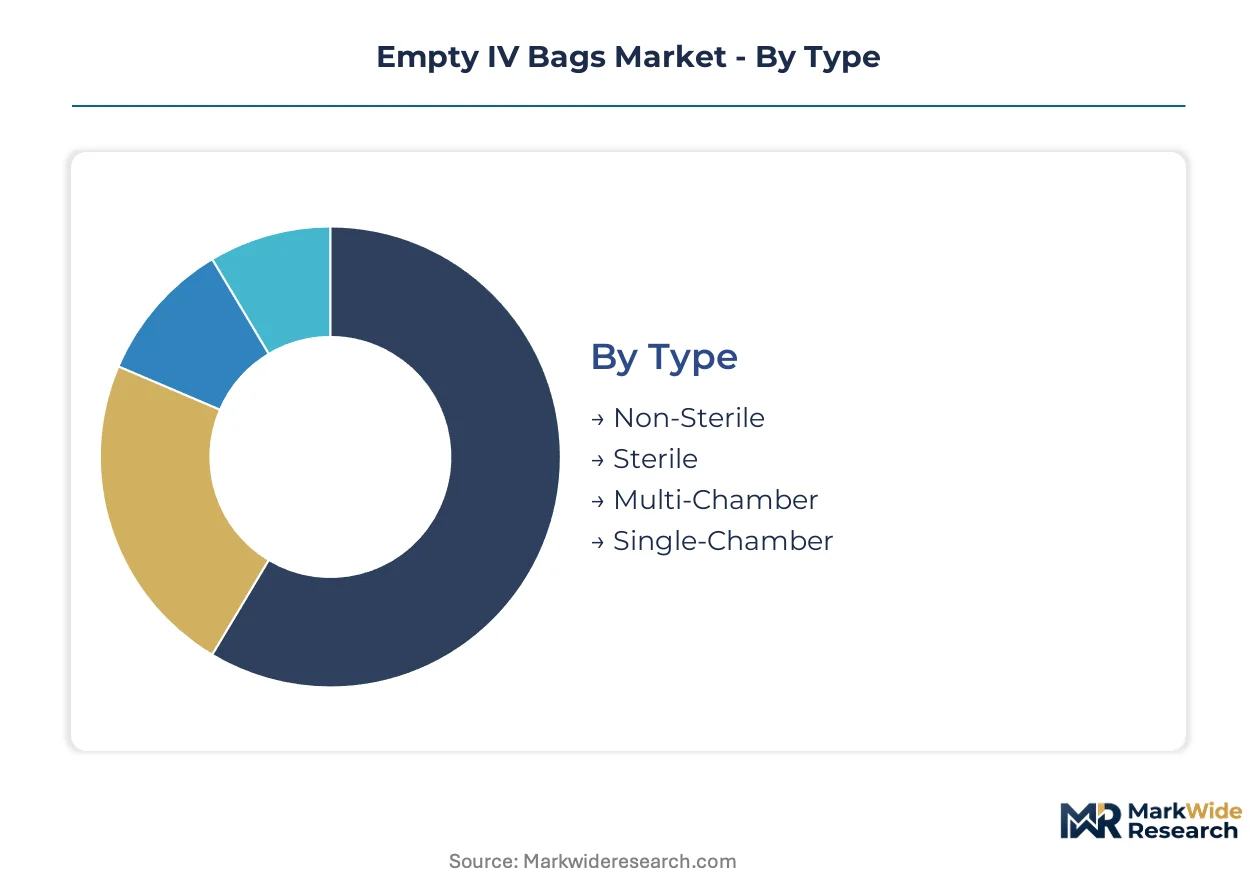
Empty IV bag procurement splits across technical specifications, regulatory classifications, and care setting requirements. Manufacturers configure production lines around these divides, with material chemistry and sterility assurance commanding the steepest compliance investments.
Type:
FDA and EU MDR classify sterile containers as Class IIa devices, imposing notified body oversight that filters production toward integrated manufacturers with in-house toxicology capabilities.
- Sterile:Terminal sterilization via gamma irradiation or ethylene oxide treatment eliminates bioburden prior to distribution. Hospital central pharmacies and oncology units in the United States specify these configurations for immediate-use applications where compounding time constraints dominate workflow efficiency.
- Multi-Chamber:Radio-frequency welded internal barriers separate incompatible components until point-of-use mixing. Tertiary hospital parenteral nutrition services drive specification, as reduced contamination protocols offset premium positioning through labor savings and compounding error reduction.
- Single-Chamber:Standard configurations for saline, dextrose, and electrolyte solutions dominate volume procurement through economies of scale.
- Non-Sterile:Bulk containers for in-house compounding operations where hospital pharmacies maintain captive sterilization capacity.
Established volume favors Single-Chamber; emerging adoption favors Multi-Chamber.
Material:
Cost tiers separate legacy converters from polyolefin specialists, with resin specification volatility squeezing margins on fixed-price contracts.
- Polyolefin:Phthalate-free coextruded films displace legacy alternatives in neonatal and oncology segments where DEHP leaching risks alter therapeutic safety profiles. REACH authorization requirements and FDA scrutiny of di-ethylhexyl phthalate accelerate validation timelines for European and United States hospital procurement.
- Polyvinyl Chloride:Plasticized formulations retain cost advantage in high-volume fluid replacement applications where regulatory sunset dates have not yet taken effect. German and French hospital groups now specify phthalate-free alternatives in tender documents, compressing residual demand toward price-sensitive markets.
- Ethylene Vinyl Acetate:Flexible, low-temperature performance suits cold-chain biologic delivery applications.
- Others:Experimental barrier films and fluorinated chemistries facing EPA per- and polyfluoroalkyl substance restrictions.
Regulatory pressure is concentrating specification authority toward Polyolefin; residual cost optimization sustains Polyvinyl Chloride.
End User:
Customer type determines distribution infrastructure requirements, with direct logistics networks displacing wholesale intermediaries in acute care contracting.
- Hospitals:Integrated health systems in the United States anchor demand through multi-year contracts specifying lot traceability and reduced lead times. Surgical caseloads and chronic disease management sustain elevated parenteral therapy volumes, with ICU and oncology units commanding the most stringent material certification requirements.
- Homecare:Ambulatory infusion expansion shows structural momentum as reimbursement frameworks stabilize for outpatient parenteral therapy. Home infusion providers in Florida, Texas, and California represent the steepest expansion trajectory among end-user categories.
- Clinics:Outpatient surgical centers and dialysis facilities with captive compounding operations.
- Pharmacies:Retail and specialty pharmacy channels for patient-directed therapy administration.
Acute care concentration favors Hospitals; channel diversification favors Homecare.
Application:
Maturity gradients separate commodity fluid replacement from specialized parenteral nutrition, with compatibility testing requirements elevating technical barriers.
- Parenteral Nutrition:Multi-component admixtures demand oxygen barrier performance and lipid compatibility validation exceeding standard infusion specifications. Neonatal intensive care units and intestinal failure centers in the United States specify these configurations, with material certification requirements filtering supply toward converters with in-house extractables testing laboratories.
- Medication Delivery:Chemotherapy, antibiotic, and analgesic infusion protocols require drug-contact material validation under ISO 10993 biocompatibility frameworks. Oncology units in tertiary hospitals drive specification, with stability data requirements extending supplier qualification timelines.
- Fluid Replacement:Standard saline and electrolyte solutions for surgical and emergency department resuscitation.
- Nutrient Delivery:Enteral and supplemental nutrition applications with lower barrier requirements than parenteral formulations.
Technical complexity favors Parenteral Nutrition; volume scale favors Fluid Replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States prioritizes multi-chamber parenteral nutrition configurations, while European procurement emphasizes phthalate-free material certifications ahead of regulatory sunset dates.
United States
Surgical caseloads and chronic disease management sustain elevated parenteral therapy volumes across integrated health systems. The FDA maintains phased scrutiny of di-ethylhexyl phthalate in PVC medical devices, accelerating hospital procurement shifts toward polyolefin alternatives. The Texas Medical Center in Houston anchors domestic demand through multi-year contracts specifying lot traceability and reduced lead times for ICU and oncology units.
Germany
German hospital groups now specify phthalate-free containers in tender documents, compressing residual PVC demand toward price-sensitive markets. ECHA authorization requirements under REACH compel contract manufacturers to validate polyolefin alternatives ahead of DEHP sunset dates. The Rhine-Ruhr metropolitan region concentrates converter activity, with film specialists near Düsseldorf expanding barrier film lamination capacity for oncology applications.
France
French tertiary hospitals drive multi-chamber specification for parenteral nutrition services, where reduced contamination protocols offset premium positioning through labor savings. ANSM oversight aligns with EU MDR Class IIa classification for sterile empty containers, filtering production toward integrated manufacturers. The Lyon-Saint-Étienne corridor hosts compounding specialists serving neonatal intensive care units across the Auvergne-Rhône-Alpes region.
Japan
Japan's aging demographic sustains homecare channel expansion as reimbursement frameworks stabilize for outpatient parenteral therapy. PMDA biocompatibility requirements under ISO 10993 elevate compliance costs for film converters lacking in-house toxicology capabilities. The Kansai region around Osaka anchors domestic production, with converters near Kyoto developing oxygen-scavenging barrier films for cold-chain biologic delivery.
India
India's hospital sector shows accelerating demand for single-chamber configurations in fluid replacement applications as surgical infrastructure expands in tier-two cities. CDSCO alignment with ISO 10993 frameworks for polymer contact layers extends supplier qualification timelines for imported film converters. The Mumbai-Pune corridor concentrates regional converter activity, with specialists near Thane scaling gamma irradiation capacity for terminal sterilization validation.
Empty IV Bags Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive film production separating the two groups. Large-format extrusion equipment requirements exceed regional converter financing capacity, consolidating supply among manufacturers with backward integration into resin specification control. Three archetypes dominate: integrated medical device conglomerates with direct distribution networks, specialized film converters with certified barrier lamination capacity, and regional compounders serving hospital captive pharmacies. Competitive moves concentrate on M&A for toxicology capabilities and capacity expansion in multi-layer radio-frequency welding.
Among integrated medical device conglomerates, ICU Medical, Inc., Baxter International, and Fresenius Kabi AG exemplify the tier that combines captive film production with direct hospital contracting. These companies occupy positions where in-house extractables testing laboratories and integrated distribution infrastructure create defensive moats against regional converters. POLYCINE GmbH represents the specialized film converter archetype, sitting within the certified barrier lamination tier that serves parenteral nutrition compatibility requirements exceeding standard infusion specifications.
| Leading Market Players |
|---|
| ICU Medical, Inc. |
| Wipak |
| Baxter International |
| Technoflex |
| RENOLIT SE |
| B. Braun Medical Inc. |
| Fresenius Kabi AG |
| POLYCINE GmbH |
| Becton, Dickinson and Company |
| Others |
Cost & Logistics Intelligence
FDA ISO 10993 biocompatibility certification gates both supplier qualification and price differentiation simultaneously, concentrating procurement authority among manufacturers with in-house extractables testing laboratories while fragmenting regional converter access to tier-one hospital contracts.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with multi-year contracts specifying fixed resin pricing and volume commitments. Price differentiation separates multi-chamber parenteral nutrition configurations from standard single-chamber fluid replacement by certification grade and compounding complexity. Cost compression in polyolefin formulations is intensifying because propylene feedstock volatility squeezes converter margins on legacy PVC displacement timelines. Price-sensitive procurement concentrates in high-volume saline and electrolyte applications, while oncology and neonatal segments show reduced sensitivity due to therapeutic safety requirements.
Supply Chain Analysis
Inventory lead times compress for integrated manufacturers with direct distribution networks, while regional converters face extended sterilization validation queues. Supply concentrates in the United States, Germany, and Japan, where large-format extrusion infrastructure and gamma irradiation capacity anchor production. Raw material flows draw from propylene feedstock suppliers, multi-layer barrier film laminators, and radio-frequency welding equipment providers. Single-source vulnerability in fluorinated oxygen barrier films threatens parenteral nutrition supply continuity as EPA restrictions advance. Distribution runs through integrated health system contracts that bypass wholesale intermediaries, capturing preference through lot-traceability guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Empty IV Bags Market is recovering from material transition cyclicality as FDA and ECHA phthalate restrictions force accelerated PVC-to-polyolefin conversion, creating replacement demand windows for qualified suppliers.
For Market Incumbents: Compound defensive positioning through captive multi-layer lamination capacity and direct hospital logistics infrastructure. Threats from emerging polyolefin specialists with certified barrier film capabilities require backward integration into resin specification control. Priority levers include gamma irradiation dosimetry infrastructure and in-house toxicology laboratories that accelerate 510(k) clearance timelines. For New Entrants and Emerging Players: Lead with homecare channel specialization in Florida, Texas, and California, where reimbursement stabilization for outpatient parenteral therapy creates white-space expansion. The most penetrable segment is non-sterile bulk containers for hospital captive compounding operations. Go-to-market positioning should emphasize ISO 10993 biocompatibility certification as a service-layer revenue differentiator. For Investors and Strategic Acquirers: ECHA REACH DEHP sunset dates reshape the acquisition landscape toward polyolefin converters with validated oncology and neonatal material certifications. Long-term viability centers on five-to-ten year regulatory compliance moats rather than commodity scale. Target acquisition archetypes include specialized film converters with barrier lamination capacity and in-house extractables testing. The signal to watch is EPA per- and polyfluoroalkyl substance restriction timing on fluorinated barrier alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for polyolefin alternatives ahead of PVC sunset timelines. |
| CE Marking Pathway | Enables EU MDR Class IIa sterile container distribution under notified body oversight. |
| Hospital System Partnership | Secures multi-year offtake agreements with integrated US health systems. |
| Backward Integration | Captures resin specification control and margins from film extrusion through terminal sterilization. |
| Reimbursement Strategy | Positions homecare channel products for outpatient parenteral therapy coverage expansion. |
Research Approach
A spread of perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and film converter operations directors converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA medical device registrations, hospital procurement databases, and customs trade data. Bottom-up volume modeling and top-down market sizing triangulated across these inputs to establish segment boundaries.
Segmentation dimensions modeled include sterile versus non-sterile configuration, single-chamber versus multi-chamber design, polyolefin versus PVC versus EVA material chemistry, and hospital versus homecare versus clinic end-user channels. CAGRs derived from regression analysis against parenteral therapy volume drivers and material transition adoption curves. Industry-specific forecast inputs encompass surgical caseload projections and regulatory sunset date enforcement patterns.
Forecasts assume regulatory continuity in FDA ISO 10993 frameworks and ECHA REACH authorization requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Skin Tac Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Cryotubes Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Glass Pasteur Pipettes Market