
 Glass Pasteur Pipettes Market | 2026-2036
Glass Pasteur Pipettes Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Pasteur Pipettes Market Foresight
Polypropylene is hardening its position as a lower-cost alternative in non-sterile liquid handling, yet borosilicate glass retains irreplaceable thermal and chemical resistance for precision applications. Thermo Fisher Scientific leverages its broad distribution network to sustain volume leadership across academic and pharmaceutical channels. VWR International anchors its competitive stance through private-label glassware programs and consolidated procurement contracts with research institutions.
Glass Pasteur pipettes are slender, tapered borosilicate glass tubes calibrated for volumetric liquid transfer in analytical and preparative procedures, typically manufactured through controlled flame-drawing to achieve uniform bore diameters of 0.5–1.1 millimeters. Their primary purpose centers on delivering precise microliter-to-milliliter volumes in settings where chemical inertness and autoclave compatibility are mandatory. The Material Grade dimension shows borosilicate glass commanding the dominant share due to its thermal shock resistance, while quartz glass represents the fastest-expanding niche for high-temperature spectroscopy applications. Among End Users, contract research organizations are outpacing academic institutions in volume growth as outsourced pharmaceutical testing expands.
FDA cGMP guidelines and EPA Good Laboratory Practice standards enforce traceable calibration and contamination-control protocols that directly shape product specifications for U.S.-market pipettes. The EU REACH regulation and MDR framework restrict heavy-metal content and mandate biocompatibility documentation, elevating compliance costs for European suppliers while creating barriers for low-cost imports. Stakeholders must monitor how evolving sustainability mandates affect single-use versus reusable product strategies.
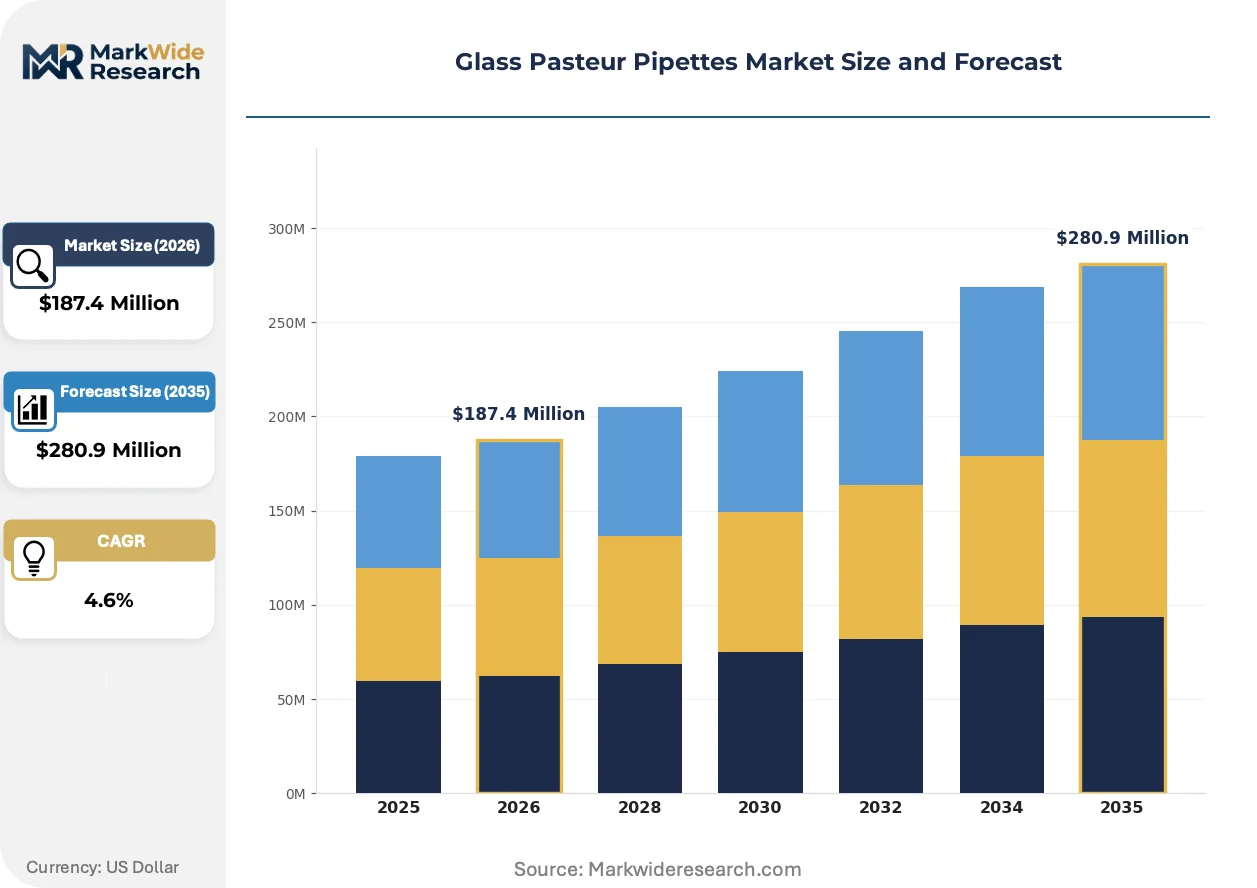
Market Dynamics
Contract research organizations are consolidating analytical chemistry procurement around borosilicate-grade glassware, creating volume concentration effects that reshape supplier relationships and compliance documentation requirements across pharmaceutical testing workflows.
Growth Catalysts
- REACH Material Purity Mandates:ECHA enforcement of heavy-metal thresholds for laboratory glassware imports is filtering out low-cost competitors and elevating certified European suppliers.
- Sterile Compounding Expansion:Pharmaceutical testing laboratories are scaling autoclave-compatible liquid handling infrastructure for parenteral drug preparation workflows.
- Quartz Spectroscopy Demand:High-temperature analytical applications in materials science are driving specialized glass grade adoption beyond standard borosilicate specifications.
Market Restraints
- Borosilicate Raw Material Concentration:Specialty glass sand supply clusters in Germany and the Czech Republic create geographic vulnerability for precision bore manufacturers.
- Polypropylene Substitution Pressure:Non-sterile liquid handling in academic settings is migrating to disposable plastic alternatives on cost grounds.
- MDR Documentation Burden:EU medical device regulation biocompatibility certification timelines extend 14-18 months for glassware classified as Class I medical devices.
Strategic Opportunities
- Private-Label Consolidation:Research institutions are consolidating procurement through single-source glassware contracts with integrated distributors.
- Reusable Product Premium:Sustainability mandates in German public research funding are creating preference for autoclave-durable glass over single-use plastics.
- Spectroscopy Grade Diversification:UV-transmissible quartz pipettes are capturing share in semiconductor materials testing applications.
Industry Challenges
- Flame-Drawing Skill Scarcity:Precision bore uniformity requires craft technicians with 5-7 year training curves that outpace workforce replacement rates.
- Multi-Jurisdiction Certification:Simultaneous FDA cGMP, EPA GLP, and REACH compliance creates documentation fragmentation for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Pasteur Pipettes Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipettes, Graduated Pipettes, Filtered Pipettes, Disposable Pipettes, Autoclave Resistant Pipettes Material Grade: Borosilicate Glass, Aluminosilicate Glass, Soda Lime Glass, Quartz Glass, Lead Glass Application: Laboratory Research, Pharmaceutical Testing, Environmental Analysis, Food & Beverage Testing, Chemical Manufacturing End User: Academic Institutions, Biotech Firms, Contract Research Organizations, Diagnostic Laboratories, Quality Control Units |
| Companies Covered | VWR International, Eppendorf, Thermo Fisher Scientific, BrandTech Scientific, Kimble Chase, Corning, Fisher Scientific, Bellco Glass, DWK Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Pasteur Pipettes Market Shifts & Advancements
Digital traceability systems and automated quality verification are compressing calibration documentation cycles while reshaping how analytical laboratories validate liquid handling precision across regulated workflows.
Laser-interferometric bore measurement is unifying dimensional verification protocols across pharmaceutical contract manufacturers. Thermo Fisher Scientific and VWR International procurement teams are mandating sub-micron tolerance certificates for high-volume analytical chemistry contracts. This metrology convergence is compressing supplier qualification timelines from 90 days to 45 days while elevating capital requirements for glassworks seeking CRO business.
EU MDR biocompatibility documentation is forcing glassware importers to establish European Authorized Representative structures and maintain post-market surveillance systems. German contract research organizations now require ISO 10993 cytotoxicity test reports for all cell culture contact applications. Suppliers without in-house toxicology dossiers are losing preferred vendor status in EU pharmaceutical testing tenders.
Consolidated procurement contracts are displacing spot purchasing for Pasteur pipettes in academic and pharmaceutical channels. University systems in Germany and research hospital networks in Switzerland are mandating three-year framework agreements with volume commitments and audit rights. This channel compression favors distributors with private-label glassware programs and integrated logistics capabilities over standalone manufacturers.
Glass Pasteur Pipettes Market Segmentation
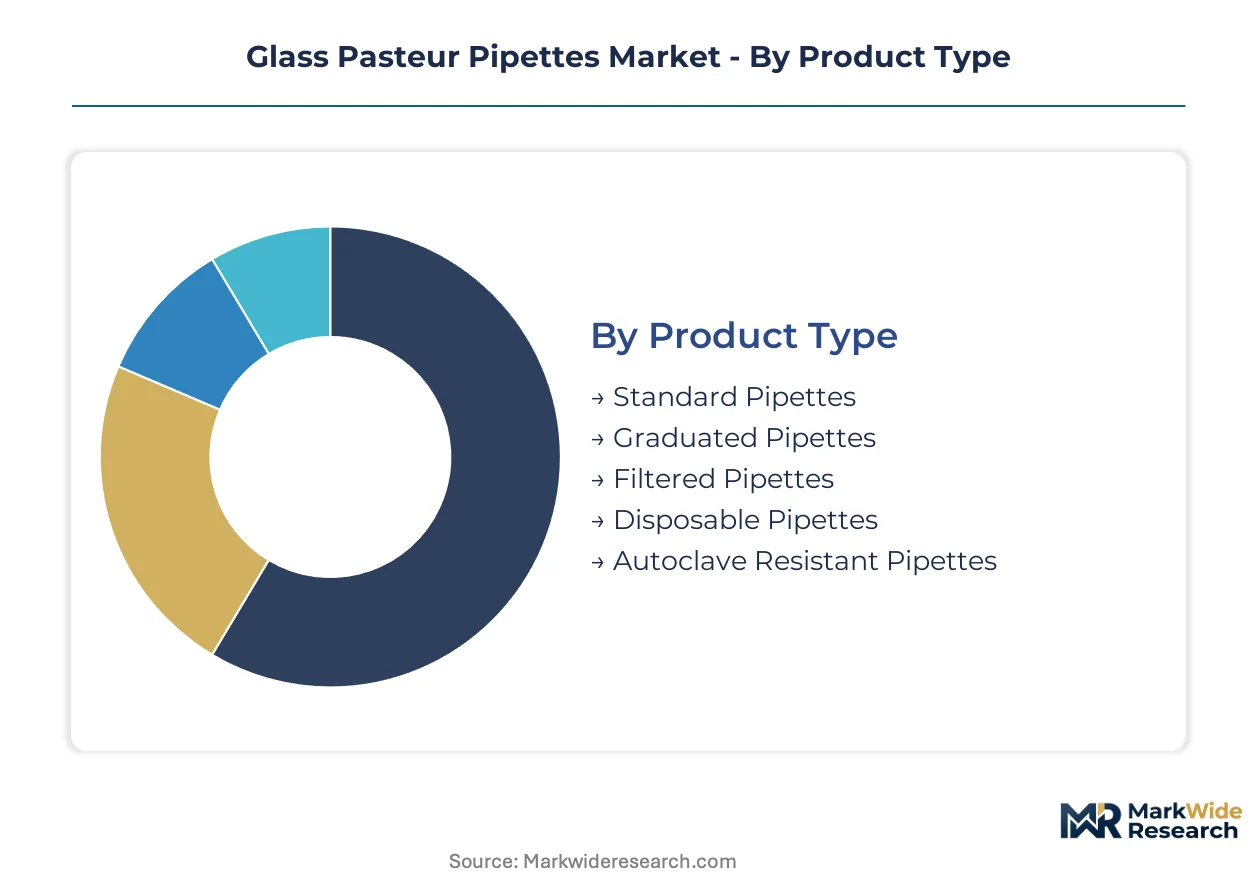
Glass Pasteur pipettes fragment across five distinct dimensions, each carrying different capital requirements and compliance burdens. Procurement patterns diverge sharply between sterile pharmaceutical workflows and routine academic use. Understanding these fault lines clarifies where pricing power concentrates and where substitution threats loom.
Product Type:
Capital intensity peaks with autoclave-compatible and filtered variants, where bore precision and thermal shock resistance demand flame-drawing expertise and metrology infrastructure.
- Standard Pipettes:Ungraduated borosilicate tubes with uniform 0.5–1.1 millimeter bores serve general liquid transfer in teaching laboratories. German academic consortia purchase these in pallet quantities through consolidated framework agreements.
- Graduated Pipettes:Calibrated volumetric markings etched or printed onto the glass surface enable approximate volume delivery without auxiliary measurement. Pharmaceutical testing laboratories in Switzerland specify these for non-sterile preparative steps.
- Filtered Pipettes:Cotton or synthetic plugs at the aspiration end prevent aerosol contamination during cell culture work. EU MDR biocompatibility documentation extends supplier qualification timelines to 14–18 months for this grade.
- Disposable Pipettes:Thin-walled soda lime construction prioritizes cost over durability for single-use academic protocols. Polypropylene substitution is most advanced here.
- Autoclave Resistant Pipettes:Heavy-wall borosilicate formulations withstand repeated sterilization cycles without dimensional drift. Contract research organizations in Germany mandate these for parenteral drug preparation workflows.
Most installed capacity flows through Standard Pipettes. Expansion is steepest in Autoclave Resistant Pipettes.
Material Grade:
Raw material sourcing geography and specialty sand purity thresholds create tiered supply risk profiles across these five glass compositions.
- Borosilicate Glass:Thermal expansion coefficient near 3.3 × 10⁻⁶/K enables direct flame sterilization and rapid temperature cycling. REACH heavy-metal thresholds favor European suppliers sourcing specialty sand from Germany and the Czech Republic.
- Aluminosilicate Glass:Higher alumina content than borosilicate improves mechanical strength for high-throughput automation. Demand concentrates in Japanese pharmaceutical manufacturing where robotic liquid handling systems require dimensional stability under mechanical stress.
- Quartz Glass:UV transmissibility and 1,100°C continuous service temperature support semiconductor materials testing and high-temperature spectroscopy. Swiss materials science institutes specify these for photolithography chemical handling.
- Soda Lime Glass:Lowest-cost option with higher thermal expansion limits autoclave compatibility to single-cycle use. Academic institutions in India deploy these for undergraduate teaching laboratories.
- Lead Glass:Radiation shielding properties serve nuclear medicine and isotope handling applications. Declining volume reflects safety handling concerns and regulatory substitution pressure.
Procurement volume concentrates in Borosilicate Glass. Quartz Glass commands the steepest expansion trajectory as semiconductor testing scales.
Application:
Regulatory stringency and contamination tolerance define five distinct use environments with divergent product specifications.
- Laboratory Research:Exploratory protocols tolerate broader dimensional tolerances than regulated manufacturing. Academic purchasing favors cost-optimized soda lime and standard borosilicate grades.
- Pharmaceutical Testing:FDA cGMP and EPA GLP enforcement mandates traceable calibration certificates and lot-specific contamination documentation. German contract research organizations drive volume here.
- Environmental Analysis:Trace metal and organic contaminant testing demands inert surfaces that do not leach or adsorb analytes. EPA Method specifications influence product selection for US environmental laboratories.
- Food & Beverage Testing:FSSAI in India and EFSA protocols in Europe require food-contact material compliance. Autoclave resistance supports repeated sterilization between microbiological samples.
- Chemical Manufacturing:Process scale-up from laboratory to pilot plant uses Pasteur pipettes for sampling corrosive or high-purity reagents. Chemical inertness overrides thermal shock requirements in this segment.
Pharmaceutical Testing absorbs the largest procurement budgets. Environmental Analysis is expanding most quickly as contamination monitoring mandates tighten.
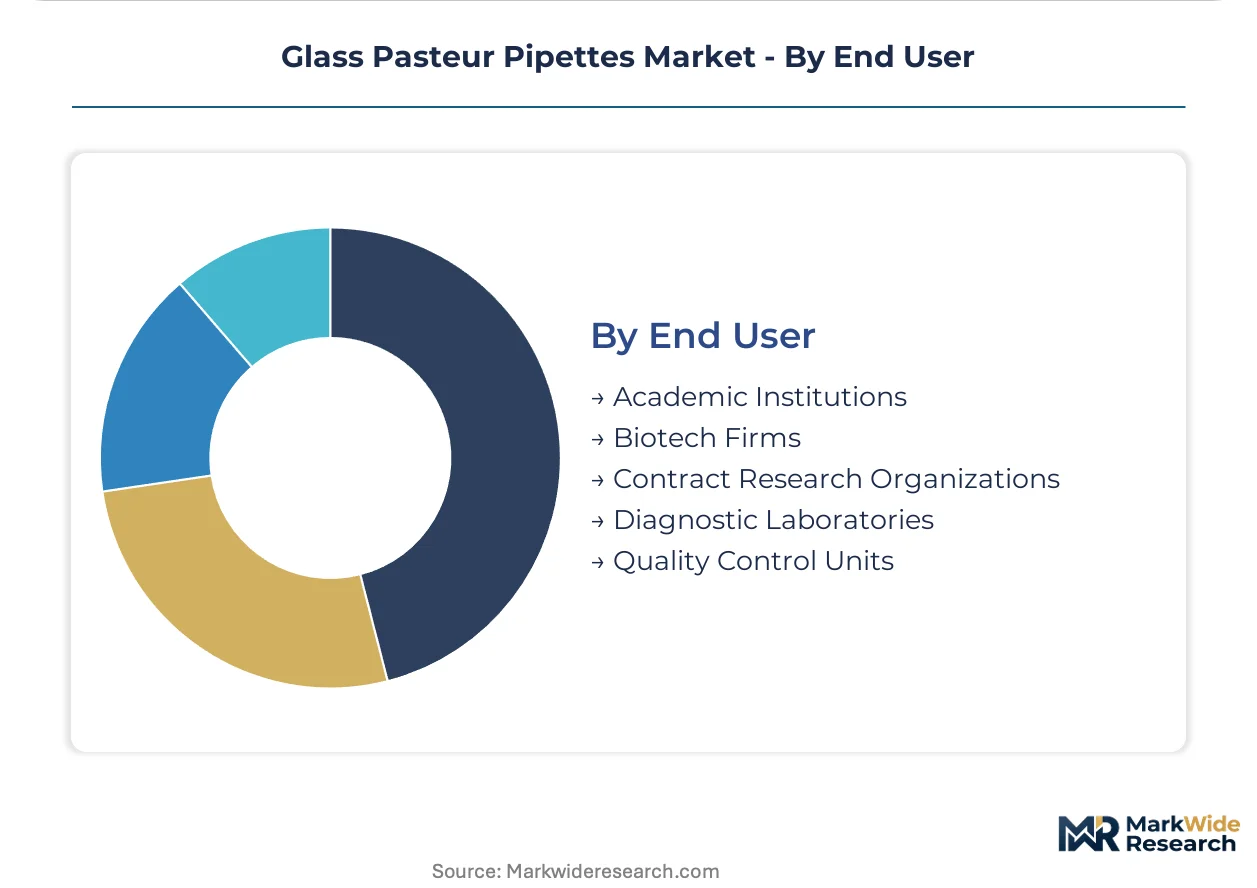
End User:
Customer sophistication and compliance infrastructure create distinct purchasing patterns across five organizational types.
- Academic Institutions:Budget-constrained procurement through university system contracts favors private-label distributors. German public research funding sustainability criteria now prefer reusable glass over disposable plastics.
- Biotech Firms:Venture-funded development-stage companies prioritize speed over cost, accepting premium pricing for certified sterile grades. Swiss biotech clusters near Basel concentrate demand.
- Contract Research Organizations:Outsourced pharmaceutical testing expansion is reshaping volume concentration. CROs consolidate suppliers around integrated distributors offering audit rights and three-year framework agreements.
- Diagnostic Laboratories:High-throughput clinical testing requires disposable or rapidly sterilizable handling tools. EU MDR classification as Class I medical devices elevates documentation burdens for glassware suppliers.
- Quality Control Units:In-house pharmaceutical and chemical manufacturing QC demands metrology-traceable calibration. Laser-interferometric bore measurement certificates are becoming mandatory for high-volume contracts.
Contract Research Organizations channel the steepest volume growth. Academic Institutions remain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract research organizations anchor pharmaceutical testing demand for borosilicate-grade pipettes, while REACH enforcement and sustainability mandates reshape procurement patterns across European research clusters.
Germany
Contract research organizations in the Rhine-Main and Rhine-Neckar regions scale analytical chemistry operations for outsourced pharmaceutical testing. ECHA REACH heavy-metal thresholds filter low-cost glassware imports, elevating certified domestic suppliers. Munich and Heidelberg research hospital networks mandate three-year framework agreements with audit rights.
Switzerland
Swissmedic biocompatibility documentation requirements extend supplier qualification timelines for cell culture contact applications. Basel biotech clusters prioritize speed-to-market over cost, accepting premium pricing for certified sterile grades. Zurich materials science institutes drive quartz pipette demand for semiconductor photolithography chemical handling.
United States
FDA cGMP and EPA Good Laboratory Practice standards enforce traceable calibration certificates for pharmaceutical testing laboratories. Boston and San Francisco Bay Area biotech hubs consolidate procurement through integrated distributors. Diagnostic laboratories face elevated documentation burdens under FDA Class I medical device classification.
India
FSSAI food-contact material compliance mandates shape testing laboratory procurement for beverage microbiology workflows. Maharashtra and Karnataka academic institutions purchase soda lime pipettes in pallet quantities for undergraduate teaching laboratories. CDSCO pharmaceutical manufacturing inspections drive adoption of autoclave-compatible borosilicate grades in Mumbai-Pune corridor.
Japan
METI industrial standards and PMDA pharmaceutical manufacturing guidelines enforce dimensional tolerance specifications for precision liquid handling. Osaka-Kobe pharmaceutical manufacturing clusters deploy aluminosilicate grades for robotic high-throughput automation. Tokyo materials science institutes expand quartz spectroscopy applications for high-temperature analytical procedures.
Glass Pasteur Pipettes Market Competitive Landscape
Global majors compete with regional champions across distribution reach and compliance infrastructure, producing a tiered structure where volume leadership and specialization coexist. Thermo Fisher Scientific leverages broad channel presence across academic and pharmaceutical segments, while VWR International anchors private-label consolidation. Three archetypes dominate: integrated distributors with logistics networks, specialized glassworks with flame-drawing craft capabilities, and diversified life science conglomerates with metrology infrastructure. Competitive moves concentrate on three-year framework agreements with audit rights and laser-interferometric bore certification standardization.
Among integrated distributors, Thermo Fisher Scientific and VWR International exemplify the scale-driven archetype through consolidated procurement relationships with research institutions and contract research organizations. DWK Life Sciences occupies a position within the specialized glassworks tier, representing craft-intensive manufacturing capabilities for precision bore uniformity. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| VWR International |
| Eppendorf |
| Thermo Fisher Scientific |
| BrandTech Scientific |
| Kimble Chase |
| Corning |
| Fisher Scientific |
| Bellco Glass |
| DWK Life Sciences |
| Others |
Supply & Pricing Matrix
Contract research organization consolidation around three-year framework agreements with audit rights is compressing supplier margins and forcing glassworks to absorb metrology infrastructure costs that previously sat with distributors. This procurement concentration elevates pricing power for integrated distributors while squeezing standalone manufacturers unable to offer bundled compliance documentation.
Pricing Analysis
Specialty glass sand and flame-drawing labor costs pass through unevenly across product tiers, with autoclave-resistant borosilicate grades absorbing the steepest input inflation. Three-tier pricing structure across premium, standard, and economy levels separates laser-certified pharmaceutical grades from teaching-laboratory soda lime variants. Cost compression in disposable pipettes intensifies as polypropylene substitution accelerates in Indian and German academic channels. Academic institutions exhibit highest price sensitivity, while Swiss biotech clusters near Basel accept premium positioning for certified sterile grades with ISO 10993 documentation.
Supply Chain Analysis
Precision bore uniformity rests on specialty glass sand deposits clustered in Germany and the Czech Republic, with secondary sourcing from Japanese aluminosilicate producers for robotic automation applications. Flame-drawing craft technicians, borosilicate raw material, and laser-interferometric metrology equipment constitute critical input dependencies. Single-source vulnerability concentrates in the 5-7 year training pipeline for precision glassblowers, where workforce replacement rates lag retirement curves. Distribution runs through integrated laboratory supply distributors holding private-label contracts and consolidated procurement relationships with research hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in autoclave-resistant grades where sustainability mandates and REACH compliance are shifting procurement preference toward reusable borosilicate over disposable plastics.
For Market Incumbents: To counter polypropylene substitution in academic channels, deepen backward integration into captive specialty glass sand sourcing and expand laser-interferometric certification capacity to compress CRO supplier qualification timelines. Anchor channel control through exclusive three-year framework agreements with German research hospital networks that bundle audit rights with volume commitments. For New Entrants and Emerging Players: Launch via private-label partnerships with established distributors targeting Indian pharmaceutical testing laboratories where CDSCO inspections are accelerating autoclave-compatible grade adoption. White-space opportunity sits in quartz spectroscopy pipettes for semiconductor materials testing, with Swiss materials science institutes representing the most penetrable premium segment for UV-transmissible grades. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized glassworks possessing in-house flame-drawing craft capabilities and established ECHA REACH certification dossiers. Long-term viability hinges on durability of CRO outsourcing trends and sustainability-driven substitution away from single-use plastics. Watch German public research funding criteria as the inflection signal, where reusable glass preference mandates would accelerate premium-tier volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Interferometric Metrology Investment | Compresses CRO supplier qualification timelines from 90 days to 45 days. |
| Backward Integration into Specialty Glass Sand | Secures REACH-compliant raw material sourcing from German and Czech deposits. |
| EU Authorized Representative Structure Establishment | Enables MDR biocompatibility documentation for Class I medical device classification. |
| Private-Label Distributor Partnership | Accesses consolidated academic procurement contracts with three-year volume commitments. |
| Quartz Spectroscopy Grade Development | Captures semiconductor materials testing demand from Swiss and Japanese research institutes. |
Research Methodology
Bottom-up contract research organization procurement modeling reconciled against top-down specialty glassware production tracking forms the analytical core of this study. Primary interviews with laboratory procurement managers, quality control directors at pharmaceutical manufacturers, flame-drawing craft technicians, and distributor category buyers were validated against secondary sources including ECHA REACH registration databases, FDA cGMP inspection records, German academic consortium tender documents, and SEC filings from listed laboratory supply distributors. Triangulation between end-use demand signals and supply-side capacity announcements ensures dimensional consistency across volume estimates.
Input-output matrices map flame-drawing labor availability, specialty sand sourcing geography, and metrology certification penetration against CRO outsourcing intensity and sustainability procurement criteria across the analysis window. Segmentation dimensions span material grade, product type, end-user archetype, and application regulatory stringency. CAGRs derive from regression of historical procurement volume against CRO facility expansion announcements and REACH enforcement trend lines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt polypropylene substitution acceleration or ECHA heavy-metal threshold tightening beyond current trajectories. Projections reflect assumptions regarding CRO outsourcing durability, flame-drawing workforce replacement rates, and REACH documentation burden stability. A small set of named triggers warrants ongoing watch: German public research funding sustainability criteria revisions, Swissmedic biocompatibility documentation timeline changes, and Indian CDSCO pharmaceutical manufacturing inspection intensity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Drosophila Bottles Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Smear Mask Market
Medical Supplies
Face Mask Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Suture Tapes Market
Medical Supplies
Microtome Knife Sharpeners Market