
 Enteral Stents Market | 2026-2036
Enteral Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Enteral Stents Market Analysis
Procedure bundling and device servicing contracts are restructuring how enteral stent vendors capture lifetime value from hospital accounts. Cook Medical leverages its direct sales infrastructure to sustain deep relationships with interventional gastroenterology departments across major academic medical centers. Boston Scientific Corporation competes through specialized product portfolios spanning covered and uncovered configurations. Taewoong Medical Inc. anchors its position in Asia-Pacific markets with manufacturing scale and cost-optimized nitinol stent production.
Enteral stents are tubular prostheses, typically 6–10 cm in length and 18–22 mm in diameter when deployed, constructed from nitinol wire mesh or silicone-covered metal frameworks to relieve luminal obstruction in the esophagus, duodenum, or colon. These devices restore patency for swallowing, gastric emptying, or fecal transit in patients with malignant or benign strictures, eliminating the morbidity of open surgical bypass. Self-expandable metallic stents dominate procedural volume due to their conformability and radial force, while covered variants command premium positioning where tissue ingrowth prevention matters. Ambulatory surgical centers represent the fastest-growing end-user channel as same-day stent placement protocols expand. Biodegradable polymer research is displacing permanent metal implants in select benign indications, though metal platforms retain clinical preference for palliative malignant cases.
The FDA regulates enteral stents as Class II medical devices under 510(k) premarket notification pathways, while the EU MDR requires notified body conformity assessment with enhanced clinical evidence for permanent implant materials. Japan's PMDA imposes additional biocompatibility testing protocols for nitinol alloys used in gastrointestinal applications, extending development timelines for new market entrants. Stakeholders must monitor evolving reimbursement thresholds for palliative stenting procedures across Medicare, NHS England, and Japan's MHLW fee schedules, as coverage determinations directly shape hospital purchasing committee priorities and vendor selection criteria.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around full-service contracts that bundle device supply with procedural training and complication management support, compressing the competitive field to manufacturers with direct sales infrastructure and clinical education capabilities.
Growth Catalysts
- Aging Demographics in Developed Economies:Japan's super-aged population and Germany's expanding cohort of patients over 75 sustain procedure volumes for palliative malignant obstruction management. Interventional gastroenterology departments prioritize stent placement over surgical bypass.
- EU MDR Conformity Requirements:Enhanced clinical evidence mandates for permanent implant materials are accelerating hospital adoption of established manufacturers with robust technical documentation. Biocompatibility testing protocols favor nitinol platforms with proven safety profiles.
- Biodegradable Polymer Research:Select benign indications are transitioning away from permanent metal implants as absorbable scaffolds demonstrate comparable patency rates. Academic medical centers in the United States pilot these platforms for non-malignant strictures.
Market Restraints
- Nitinol Raw Material Concentration:Superelastic alloy supply chains concentrate among specialty metallurgical processors in the United States and Europe, exposing stent manufacturers to input price volatility and allocation constraints during demand surges.
- Reimbursement Compression:Medicare's hospital outpatient prospective payment system and NHS England's tariff structures impose fixed procedural bundles that limit device cost recovery, pressuring purchasing committees toward lower-cost uncovered configurations.
- Technical Limitation in Tissue Integration:Covered stents prevent tumor ingrowth but exhibit higher migration rates in tortuous anatomy, restricting their deployment in certain duodenal and colonic obstructions where conformability demands exceed current polymer adhesion properties.
Strategic Opportunities
- Ambulatory Surgical Center Expansion:Same-day stent placement protocols are migrating procedures from inpatient settings to specialized outpatient facilities in the United States. Vendors with streamlined logistics and rapid restocking capabilities capture this channel shift.
- Japan's PMDA Biocompatibility Pathways:Extended development timelines for nitinol alloys create defensive moats for established market entrants with approved device dossiers. New competitors face 18-24 month regulatory delays.
- Silicone-Covered Configuration Innovation:Advances in membrane adhesion technologies are unifying radial force maintenance with ingrowth prevention. Interventionalists in academic medical centers increasingly specify these hybrid platforms for complex strictures.
Industry Challenges
- Interventional Gastroenterologist Training Bottlenecks:Advanced endoscopic stent placement requires specialized fellowship exposure that remains concentrated at major tertiary centers. Community hospital adoption lags due to procedural volume thresholds and credentialing complexity.
- EU MDR Technical Documentation Burden:Notified body conformity assessments for legacy device families demand substantial clinical data compilation. Manufacturers face resource reallocation from pipeline innovation to regulatory remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enteral Stents Market |
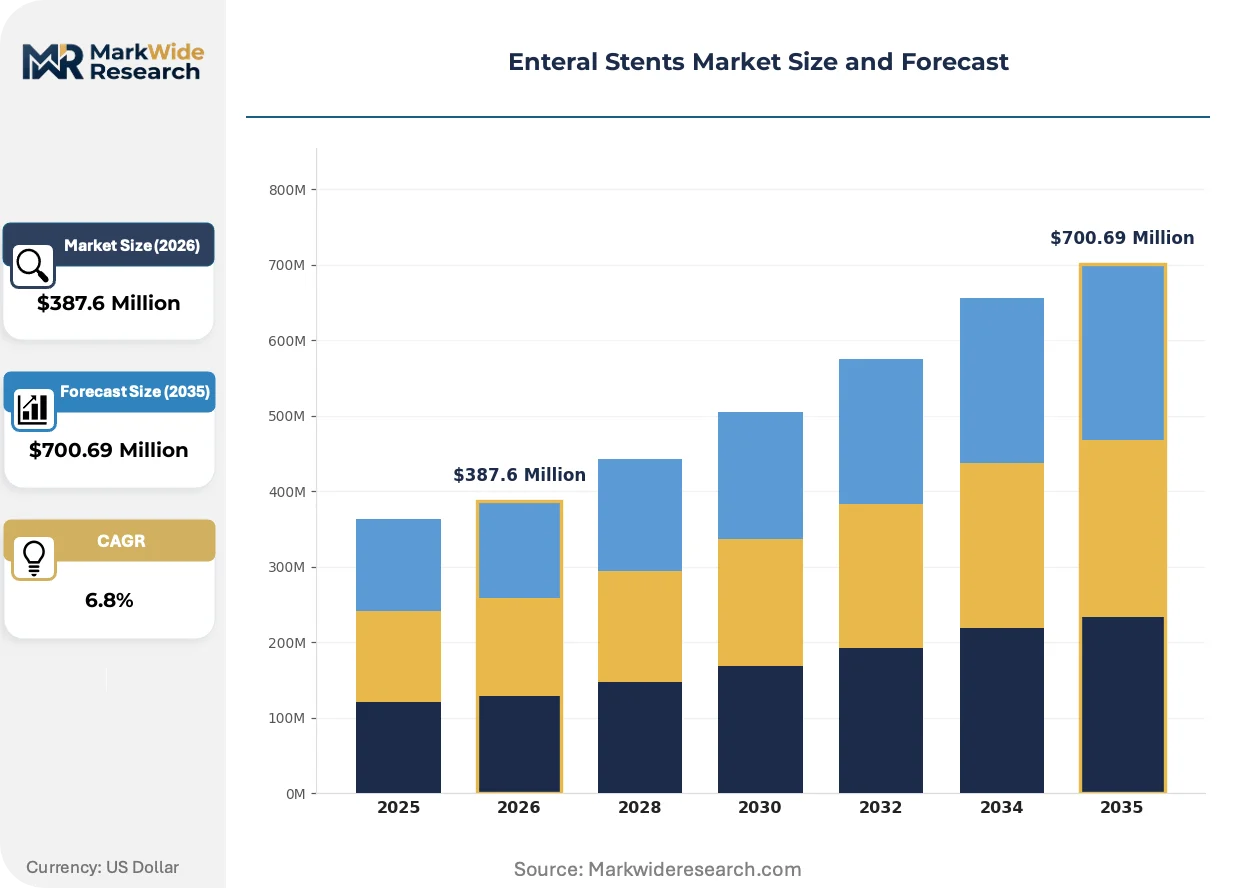
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-expandable, Balloon-expandable, Covered, Uncovered End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Material: Metal, Polymer, Hybrid, Biodegradable Application: Malignant Obstruction, Non-malignant Obstruction, Palliative Care, Nutritional Support |
| Companies Covered | Cook Medical, Stryker Corporation, Boston Scientific Corporation, Micro-Tech (Nanjing) Co Ltd, Cardinal Health Inc., Medtronic Inc., Taewoong Medical Inc., Merit Medical Systems Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enteral Stents Market Emerging Trajectories
Device architecture is converging toward hybrid platforms that balance immediate patency restoration with long-term complication prevention, while regulatory frameworks and procurement models simultaneously reshape competitive positioning.
Biodegradable polymer scaffolds are unifying the mechanical support function of traditional metal stents with complete resorption timelines matched to benign stricture healing windows. Pediatric gastroenterology departments and inflammatory bowel disease clinics in the United States and Germany are piloting these absorbable platforms for non-malignant esophageal and colonic strictures. This technology is unifying two previously separate device categories into a single therapeutic algorithm, compressing the addressable market for permanent implants in select indications.
Japan's PMDA has imposed supplemental biocompatibility testing protocols for nitinol alloys used in gastrointestinal applications beyond standard ISO 10993 frameworks. These requirements extend premarket submission timelines and elevate documentation costs for new market entrants. Domestic Japanese manufacturers with established quality management systems and historical clinical data repositories maintain competitive advantage under these tightened standards.
Hospital value analysis committees are consolidating purchasing decisions at the health system level rather than individual facility autonomy. Interventional gastroenterology departments at academic medical centers in the United States now coordinate stent selection across multi-hospital networks, favoring vendors with standardized pricing architectures and system-wide service agreements. This concentration is most visible in the southeastern and midwestern United States where hospital consolidation has advanced furthest.
Enteral Stents Market Segmentation
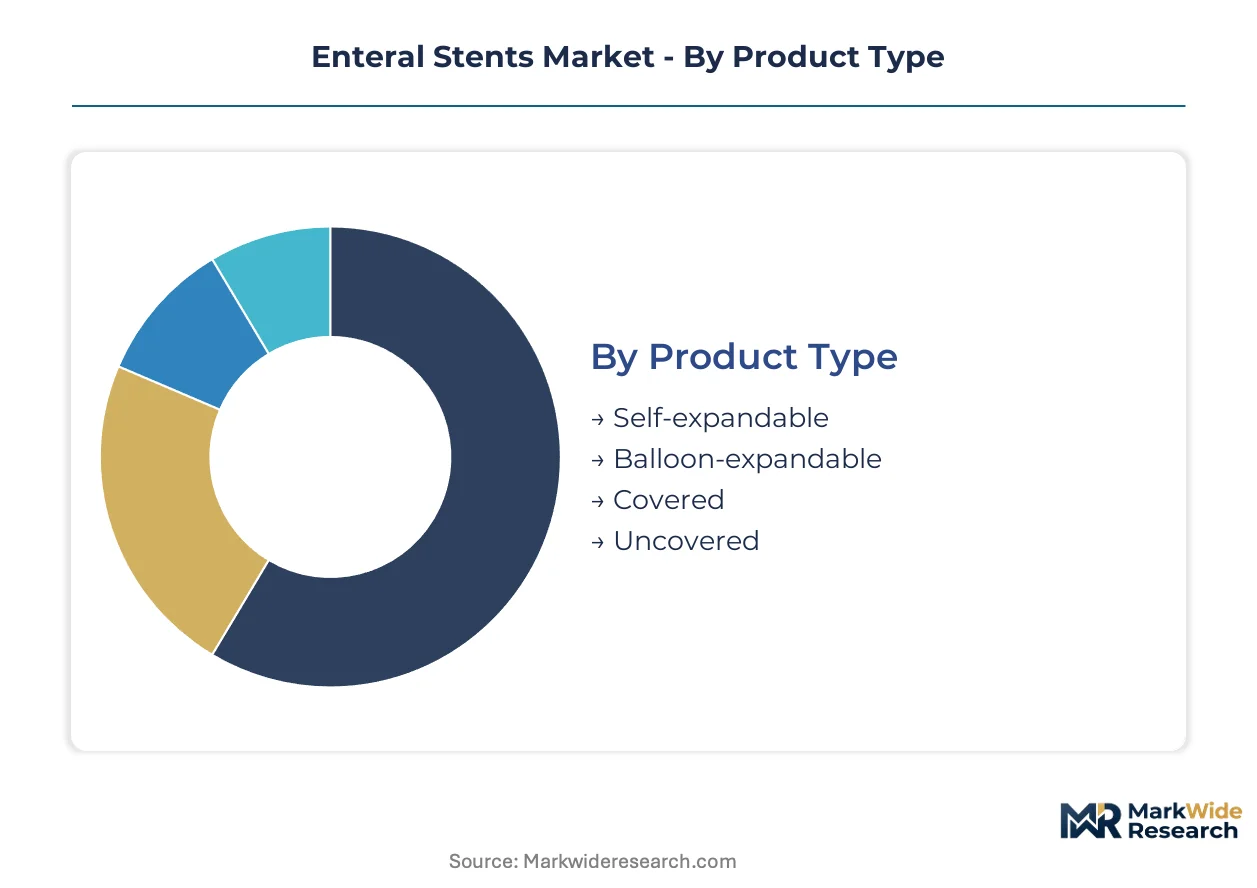
Enteral stent purchasing decisions fragment across technical specifications, care settings, and clinical objectives. Procurement committees weight radial force requirements against migration risks, while reimbursement pathways shape material selection and placement venue.
Product Type:
Replacement cycles differ sharply between permanent metallic platforms and temporary balloon-deployed alternatives, with covered variants commanding premium positioning in complex anatomies.
- Self-expandable:Nitinol wire mesh constructs deploy at body temperature without balloon assistance, delivering conformable radial force for tortuous esophageal and duodenal strictures. Hospital systems in the United States and Germany concentrate procurement of these platforms for malignant obstruction protocols, prioritizing immediate patency restoration over retrieval feasibility.
- Covered:Silicone or polymer membrane barriers overlay metal frameworks to prevent tumor ingrowth, extending functional patency in palliative esophageal cases. Academic medical centers specify these configurations for strictures where tissue integration would compromise stent longevity, accepting higher unit costs against reintervention frequency.
- Balloon-expandable:Stainless steel or cobalt-chromium platforms require controlled inflation for deployment, offering precise diameter calibration in non-tortuous anatomy.
- Uncovered:Bare metal mesh permits epithelialization and tissue incorporation, reducing migration risk in colonic applications where conformability demands exceed membrane flexibility.
Volume placements concentrate in self-expandable configurations; the faster expansion belongs to covered variants as ingrowth prevention protocols proliferate.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from streamlined outpatient facilities, with reimbursement differentials dictating venue migration.
- Hospitals:Tertiary centers maintain 24-hour interventional gastroenterology coverage for emergency obstruction management, handling complex strictures requiring fluoroscopic guidance and anesthesia support. These facilities capture high-acuity malignant cases across the United States, Japan, and Germany, where procedure bundling under DRG frameworks consolidates device purchasing authority.
- Ambulatory Surgical Centers:Same-day stent placement protocols for stable elective patients reduce facility fees and recovery costs. United States outpatient networks in Texas, Florida, and Arizona are expanding endoscopic suites with rapid turnover capabilities, capturing volume from inpatient DRG compression.
- Clinics:Office-based endoscopy suites handle uncomplicated esophageal strictures with conscious sedation protocols.
- Home Care:Enteral feeding tube management and stent monitoring services extend post-procedural oversight outside institutional settings.
Procedure volume remains anchored in hospital-based interventional suites; ambulatory surgical centers are climbing the fastest as payor incentives shift toward site-neutral reimbursement.
Material:
Margin structures diverge between commodity nitinol supply chains and emerging biodegradable platforms, with regulatory documentation costs filtering competitive participation.
- Metal:Superelastic nitinol alloys dominate permanent stent construction, delivering shape memory and kink resistance across temperature ranges. FDA 510(k) clearances and Japan's PMDA biocompatibility protocols favor established metallurgical specifications with historical safety databases, entrenching incumbent manufacturers.
- Biodegradable:Poly-lactic acid and polyglycolic acid scaffolds resorb over 3-6 month timelines matched to benign stricture healing windows. Pediatric gastroenterology departments at Boston Children's Hospital and Charité Berlin pilot these absorbable platforms for non-malignant esophageal strictures, eliminating permanent foreign body retention.
- Polymer:Silicone and polyurethane membranes provide ingrowth barriers in covered stent configurations.
- Hybrid:Metal-polymer composites balance radial force with tissue protection in complex anatomies.
Metal platforms retain the dominant placement share; biodegradable alternatives are gaining share fastest in pediatric and inflammatory bowel disease indications.
Application:
Customer type segmentation separates curative intent from palliative protocols, with life expectancy and performance status dictating device selection criteria.
- Malignant Obstruction:Esophageal, gastric outlet, and colonic strictures from metastatic disease require rapid patency restoration for oral intake or fecal transit. Interventional gastroenterologists prioritize self-expandable metallic stents over surgical bypass in patients with limited life expectancy, minimizing procedural morbidity.
- Palliative Care:End-stage cancer patients receive stent placement for symptom control without curative intent, prioritizing swallowing function and quality of life over longevity metrics. Hospice-eligible patients in the United States Medicare program drive volume for covered esophageal configurations that minimize reintervention burden.
- Non-malignant Obstruction:Peptic strictures, anastomotic stenoses, and radiation-induced narrowing respond to temporary stenting with retrieval protocols.
- Nutritional Support:Enteral feeding access through percutaneous or transoral routes maintains caloric delivery in neurologic or postsurgical patients.
Malignant obstruction commands the highest procedure volume; palliative care applications are expanding most quickly as hospice enrollment criteria broaden and interventional symptom management protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for nitinol-based stent platforms centers in the United States, Germany, and Japan, while consumption distributes across aging populations in these same markets where interventional gastroenterology infrastructure sustains procedure volumes.
United States
Academic medical centers in Boston and Houston drive adoption of covered self-expandable configurations for malignant esophageal obstruction. FDA 510(k) clearance pathways favor established manufacturers with historical safety databases for nitinol alloys. The southeastern hospital consolidation corridor concentrates procurement authority at the health system level, compressing vendor selection to direct-sales infrastructure holders.
Germany
Charité Berlin and Heidelberg University Hospital pilot biodegradable polymer platforms for pediatric non-malignant strictures. EU MDR conformity assessments for permanent implant materials demand enhanced clinical evidence, elevating documentation costs for new entrants. The Baden-Württemberg medical technology cluster anchors nitinol processing capabilities for stent wire mesh production.
Japan
Super-aged demographics in Tokyo and Osaka sustain palliative stent placement volumes for gastric outlet obstruction. PMDA biocompatibility testing protocols for gastrointestinal nitinol applications extend premarket timelines beyond standard ISO 10993 frameworks. Domestic manufacturers with established quality management systems maintain defensive positioning under these tightened regulatory standards.
United Kingdom
NHS England tariff structures impose fixed procedural bundles that pressure purchasing committees toward uncovered configurations. London teaching hospitals coordinate stent selection across multi-hospital networks, favoring vendors with standardized pricing architectures. The Oxford-Cambridge corridor concentrates interventional gastroenterology fellowship programs that credential advanced endoscopic placement techniques.
South Korea
Seoul National University Hospital and Asan Medical Center drive volume for duodenal stenting in pancreatic cancer palliation. MFDS regulatory pathways align with international standards while maintaining supplemental requirements for implantable device biocompatibility. The Seoul Capital Area medical device manufacturing base supports regional supply chain resilience for nitinol alloy procurement.
Enteral Stents Market Vendor Landscape
Top-tier vendors anchor hospital procurement through direct sales infrastructure and clinical education capabilities, while mid-tier specialists compete on manufacturing scale and regional regulatory dossiers. The competitive field compresses around full-service contracts bundling device supply with procedural training. Three archetypes dominate: diversified medtech conglomerates with interventional portfolios, specialized gastrointestinal device manufacturers, and Asia-Pacific scale producers with cost-optimized nitinol fabrication. Consolidation pressure intensifies through health system purchasing centralization and EU MDR documentation burdens that favor incumbents with legacy clinical data repositories.
Among diversified medtech conglomerates, Boston Scientific Corporation and Stryker Corporation occupy positions spanning covered and uncovered stent configurations across multiple anatomical applications. Cook Medical exemplifies the specialized gastrointestinal device archetype with deep interventional gastroenterology department relationships at major academic medical centers. Taewoong Medical Inc. represents Asia-Pacific manufacturing scale with cost-optimized production capabilities. These three company profiles illustrate how competitive positioning fragments across direct sales depth, product specialization breadth, and regional manufacturing economics.
| Leading Market Players |
|---|
| Cook Medical |
| Stryker Corporation |
| Boston Scientific Corporation |
| Micro-Tech (Nanjing) Co Ltd |
| Cardinal Health Inc. |
| Medtronic Inc. |
| Taewoong Medical Inc. |
| Merit Medical Systems Inc. |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Nitinol alloy costs cascade through stent manufacturing tiers, with superelastic wire mesh commanding premium positioning at academic medical centers while cost-optimized configurations penetrate ambulatory surgical centers. Raw material volatility from United States and European specialty metallurgical processors compresses margins for uncovered configurations as hospital purchasing committees consolidate vendor relationships.
Pricing Analysis
Margin tightening in standard uncovered configurations reflects Medicare's hospital outpatient prospective payment system bundling device costs into fixed procedural reimbursements. Three-tier pricing structure across covered hybrid platforms, bare metal mesh, and balloon-expandable alternatives separates premium silicone-membrane configurations with FDA 510(k) clearances from economy-tier imports. Cost-down pressure on standard metallic stents accelerates because NHS England tariff structures and Japan's MHLW fee schedules limit cost recovery. Academic medical centers exhibit lowest price sensitivity for covered configurations where reintervention avoidance justifies unit premiums, while community hospitals prioritize uncovered alternatives under DRG compression.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume procurement from United States, Germany, and Japanese manufacturing bases, bypassing distributor markups for major academic medical center networks. Nitinol wire mesh production draws from specialty metallurgical processors in the United States and Europe, with silicone membrane adhesion technologies sourcing from German and South Korean polymer specialists. Single-source vulnerability concentrates in superelastic alloy supply chains where demand surges trigger allocation constraints. Distribution runs through manufacturer-direct sales infrastructure for interventional gastroenterology departments, with streamlined logistics capabilities capturing ambulatory surgical center channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity documentation burdens are forcing weaker manufacturers without legacy clinical data repositories toward exit or acquisition, consolidating competitive positioning around established incumbents with robust technical dossiers.
For Market Incumbents: Lock in hospital system procurement relationships through full-service contracts bundling device supply with procedural training and complication management support. Deepen backward integration into nitinol alloy processing to defend against raw material price volatility from United States and European specialty metallurgical processors. Prioritize CE marking pathway investments for silicone-covered hybrid configurations where membrane adhesion technologies unify radial force with ingrowth prevention. For New Entrants and Emerging Players: Begin with biodegradable polymer platforms for pediatric non-malignant strictures at Charité Berlin and Boston Children's Hospital, where absorbable scaffolds demonstrate comparable patency without permanent foreign body retention. Target ambulatory surgical centers in Texas, Florida, and Arizona with streamlined logistics and rapid restocking capabilities as same-day stent placement protocols expand. Pursue Japan's PMDA biocompatibility pathways as defensive moats where 18-24 month regulatory delays protect approved device dossiers. For Investors and Strategic Acquirers: Hospital value analysis committee consolidation at the health system level is the leading indicator that vendor selection criteria are narrowing to direct-sales infrastructure holders with standardized pricing architectures. Position acquisition strategy around specialized gastrointestinal device manufacturers with deep interventional gastroenterology department relationships and established EU MDR technical documentation. Watch ambulatory surgical center licensing expansion as signal for channel shift viability and outpatient volume capture.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clears nitinol platforms for malignant obstruction management under Class II device pathways. |
| CE Marking Pathway | Validates permanent implant materials under EU MDR enhanced clinical evidence mandates. |
| Hospital System Partnership | Secures multi-facility procurement authority across southeastern and midwestern United States networks. |
| Biodegradable Scaffold Development | Captures pediatric and inflammatory bowel disease indications away from permanent metal implants. |
| Reimbursement Strategy | Aligns covered configuration positioning with Medicare hospice eligibility criteria expansion. |
Methodological Framework
Document review covered FDA 510(k) clearances, EU MDR technical documentation, and Japan PMDA biocompatibility protocols, complemented by interviews with interventional gastroenterologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare fee schedules, NHS England tariff structures, and nitinol alloy trade data. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates across the analysis window.
Segmentation outputs reflect product type, end user venue, material composition, and application intent modeled across the projection horizon. CAGRs derived from regression analysis against aging demographic trajectories, regulatory pathway timelines, and reimbursement policy shifts. Forecast inputs incorporated interventional gastroenterology fellowship program expansion rates and ambulatory surgical center licensing data.
Underlying measurement precision varies by segment; malignant obstruction and self-expandable metallic stent placements carry tighter precision than emerging biodegradable platforms where clinical adoption remains pilot-phase. Forecasts reflect assumptions regarding EU MDR notified body capacity, nitinol raw material supply stability, and palliative care enrollment criteria evolution. Periodic stress-testing of base assumptions against PMDA regulatory timeline extensions and hospital consolidation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Smart Syringe Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Vaginal Pessary Market
Medical Devices
North America Wheelchair Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Endodontic Files Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Europe Foot Orthotic Insoles Market