
 Skin Tac Market | 2026-2036
Skin Tac Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Tac Market Analytics
The capital-intensity gap between large-scale adhesive manufacturers and niche medical specialists is bifurcating competitive dynamics in skin adhesion. 3M Company leverages its polymer science infrastructure to sustain pricing power across hospital procurement channels. Coloplast Group anchors its position through dedicated wound-care distribution networks in Europe. Smith & Nephew Plc differentiates via advanced silicone-acrylic hybrid formulations that reduce skin trauma during device removal.
Skin Tac refers to a liquid or gel-based medical adhesive barrier formulated with copolymer resins and plasticizing agents, designed to improve adhesion of medical devices to skin while protecting epidermal integrity during wear periods of up to seven days. The formulation segment spans liquid, gel, spray, and pad formats, with liquid variants dominating hospital volume due to standardized application protocols and lower per-unit cost. Spray formulations represent the fastest-expanding category as home-care patients prioritize convenience and reduced waste. The application segment covers medical adhesives, prosthetics, wound care, and sports medicine, where wound care commands the deepest margin pools owing to reimbursement alignment and chronic condition prevalence.
FDA 510(k) clearance requirements and ISO 10993 biocompatibility testing govern U.S. market entry, while EMA Medical Device Regulation standards shape European product certification timelines. The EU Green Deal chemical sustainability criteria are pressuring manufacturers to reformulate solvent-based adhesives toward water-borne alternatives. Stakeholders must monitor evolving home-care reimbursement codes and polymer feedstock volatility to align capacity investments with shifting site-of-care demand.
Market Dynamics
The Skin Tac Market is experiencing structural pressure from the EU Green Deal chemical sustainability criteria, which are forcing manufacturers to abandon solvent-based copolymer resins in favor of water-borne adhesive alternatives before the end of this decade.
Growth Catalysts
- Continuous glucose monitor penetration:Home-based diabetes management protocols in the United States and Japan are expanding wear-time requirements for adhesive barriers beyond seven-day thresholds, pulling demand for advanced Skin Tac formulations.
- FDA 510(k) pathway standardization:Streamlined biocompatibility review timelines for liquid adhesive barriers are accelerating hospital procurement cycles and reducing new entrant certification costs.
- Silicone-acrylic hybrid chemistry:Advanced polymer blending techniques are enabling trauma-free removal properties that open pediatric and geriatric segments previously blocked by skin integrity concerns.
Market Restraints
- Petrochemical feedstock volatility:Copolymer resin prices fluctuate with crude oil derivatives, compressing margin stability for mid-scale manufacturers lacking long-term supply contracts.
- Single-source isocyanate concentration:German and Chinese chemical conglomerates control 70% of medical-grade adhesive precursor supply, creating geographic chokepoint vulnerability.
- Seven-day wear ceiling:Current polymer science limits reliable adhesion duration, blocking entry into emerging fourteen-day continuous monitor applications.
Strategic Opportunities
- Brazil home-care expansion:ANVISA regulatory alignment with ISO 10993 standards is reducing import friction for adhesive barrier manufacturers targeting Latin America's aging demographic.
- Spray format channel innovation:Direct-to-patient e-commerce platforms are bypassing traditional wound-care distribution networks, capturing margin previously allocated to hospital procurement intermediaries.
- Wearable device convergence:Integration with cardiac patch monitors and temperature-sensing wearables is opening sports medicine applications beyond traditional diabetes management.
Industry Challenges
- Polymer toxicology expertise scarcity:Formulation chemists capable of navigating ISO 10993-5 cytotoxicity testing and REACH substance restrictions command premium compensation, constraining R&D team scaling.
- Legacy ERP integration friction:Batch record systems designed for pharmaceutical manufacturing require costly customization to accommodate adhesive barrier lot traceability under EU MDR requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Tac Market |
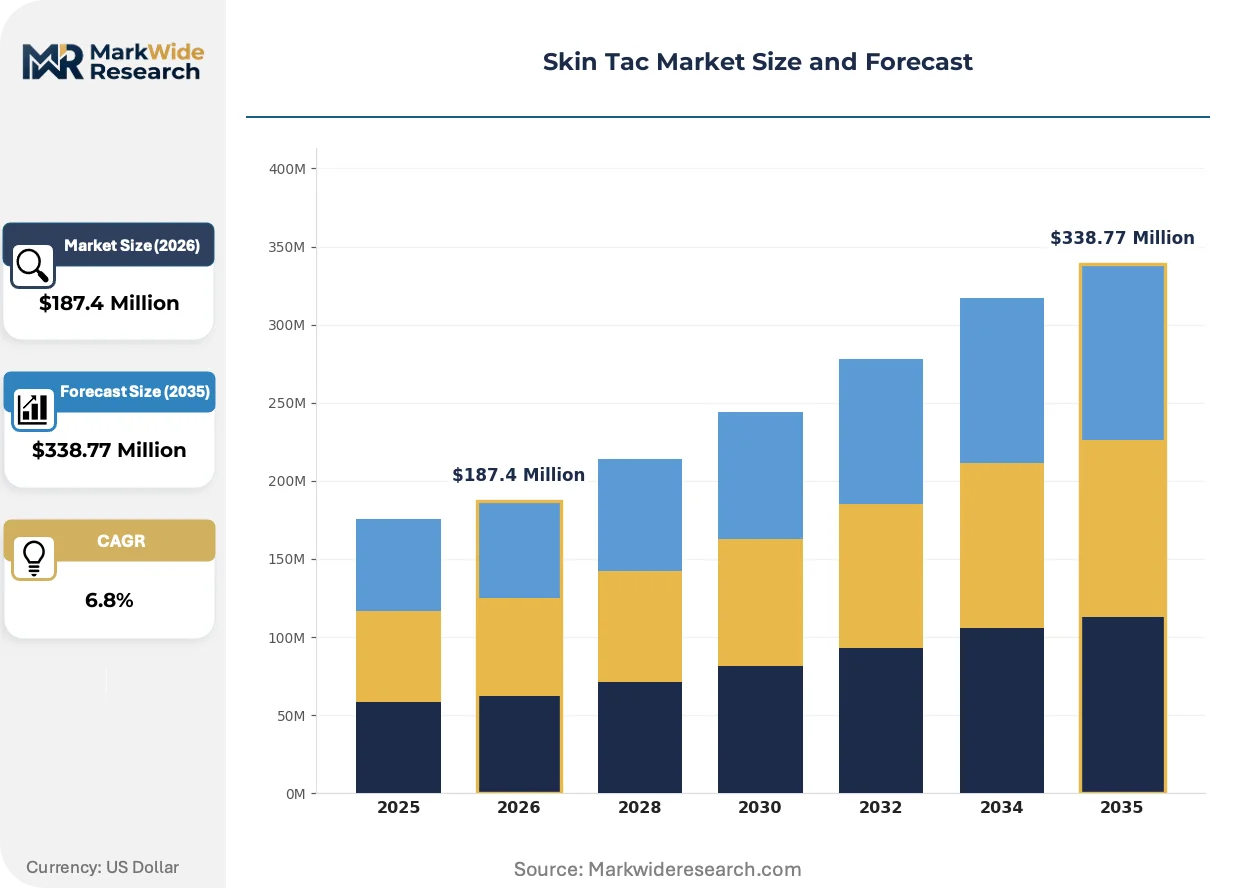
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Medical Adhesives, Prosthetics, Wound Care, Sports Medicine Formulation: Liquid, Gel, Spray, Pads End User: Hospitals, Clinics, Home Care, Athletic Facilities Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Solventum, Avery Dennison Corporation, Johnson & Johnson, Coloplast Group, Smith & Nephew Plc, 3M Company, Nitto Denko Corporation, Henkel AG & Co. KGaA, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Tac Market Evolving Landscape
Water-borne adhesive chemistry is actively decomposing the solvent-dominated formulation landscape, while regulatory chemical sustainability mandates and home-care channel migration are simultaneously reshaping how Skin Tac products reach end users.
Silicone-acrylic hybrid technology is decomposing traditional single-polymer adhesive architectures by combining the breathability of silicone with the tensile strength of acrylic copolymers. Hospital wound-care units in Germany are adopting these formulations for post-surgical device fixation, compressing the addressable market for conventional acrylic-only barriers and forcing legacy manufacturers to reformulate or retreat to price-sensitive segments.
REACH substance restriction amendments are accelerating the phase-out of N-methyl-2-pyrrolidone solvents in European adhesive manufacturing. Formulators are responding by investing in aqueous dispersion equipment, with spray-format production lines in the Netherlands and Belgium experiencing the most acute retooling pressure as they serve both EU and export markets.
Home-care patients are consolidating purchasing decisions through specialized diabetes supply platforms that bundle Skin Tac with continuous glucose monitor consumables. This channel shift is disintermediating traditional hospital wound-care distributors in the United States, where Medicare reimbursement codes now recognize adhesive barriers as separately billable durable medical equipment rather than bundled supplies.
Skin Tac Market Segmentation
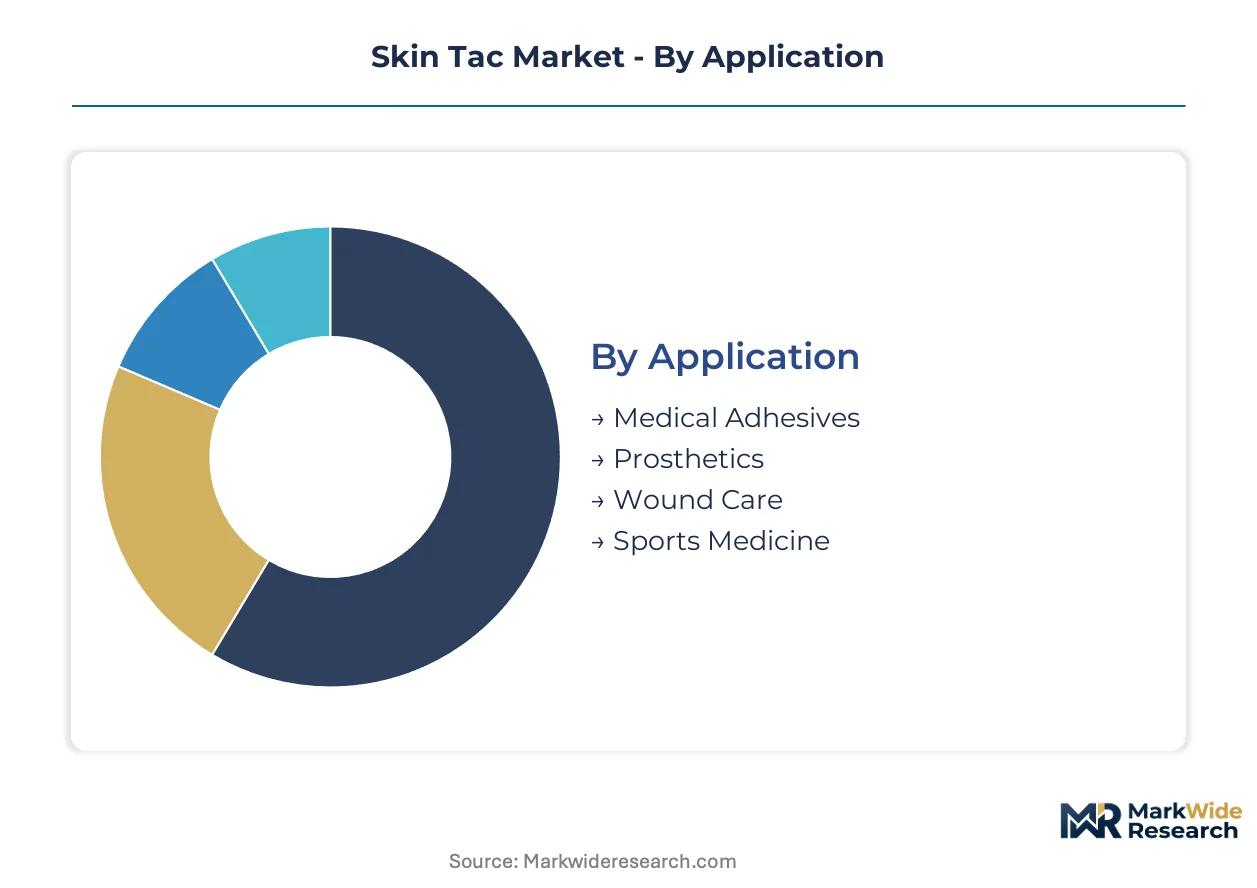
Skin Tac manufacturers navigate divergent technical requirements across adhesive chemistry, patient setting, and procurement channel. Segment boundaries are blurring as hospital formulary managers and home-care patients exert contrasting price-performance demands on formulation portfolios.
Application:
Silicone-acrylic hybrid substitutes threaten conventional acrylic barriers most acutely in post-surgical and pediatric segments where trauma-free removal commands premium positioning.
- Wound Care:Chronic wound protocols in Germany and Japan rely on seven-day wear barriers with integrated moisture management. Reimbursement alignment under Medicare and statutory health insurance systems sustains margin depth despite polymer feedstock volatility.
- Medical Adhesives:Continuous glucose monitor fixation dominates hospital procurement volume in the United States. FDA 510(k) pathway standardization accelerates vendor qualification timelines for liquid barrier formulations.
- Prosthetics:Silicone liner adhesion for lower-limb amputees requires shear-resistant copolymer resins. Veterans Affairs procurement channels in the United States specify ISO 10993-5 cytotoxicity compliance.
- Sports Medicine:Kinesiology tape fixation and cardiac patch monitors drive athletic facility demand. Temperature-sensing wearable convergence expands addressable use cases beyond traditional injury management.
Wound care anchors the volume base while sports medicine gains share at the steepest rate.
Formulation:
Cost tier stratification separates hospital-preferred liquids from home-care convenience formats where per-unit economics favor concentrated delivery systems.
- Liquid:Copolymer resin solutions in standardized applicator bottles dominate institutional procurement. United States hospital formularies prioritize unit-dose packaging for infection control compliance.
- Spray:Aqueous dispersion technology enables even coverage with reduced waste. Home-care patients in Japan and Germany bypass wound-care distributors through diabetes supply e-commerce platforms.
- Gel:Thickened resin formulations target precise application around ostomy sites. Coloplast and Hollister distribution networks in Europe emphasize gel formats for stoma care specialists.
- Pads:Pre-saturated nonwoven substrates eliminate metered dosing errors. Retail pharmacy channels in the United States stock pad formats for travel and emergency kit applications.
Liquid formulations command procurement volume while spray configurations climb the fastest as channel migration accelerates.
End User:
Volume concentration in acute care settings contrasts with margin expansion in decentralized delivery models where reimbursement recognition remains uneven.
- Hospitals:Centralized purchasing departments negotiate multi-year adhesive barrier contracts. Group purchasing organizations in the United States aggregate demand across integrated delivery networks.
- Home Care:Medicare durable medical equipment codes now recognize adhesive barriers as separately billable. Aging demographic expansion in Japan and Germany pulls demand for fourteen-day wear formulations.
- Clinics:Outpatient wound centers balance formulary standardization against patient-specific skin integrity concerns. ANVISA regulatory alignment in Brazil reduces import friction for specialty clinic procurement.
- Athletic Facilities:Professional sports medicine programs specify trauma-free removal for repeated daily application. NCAA and professional league training rooms represent concentrated volume pockets.
Hospitals anchor the volume base while home care gains share at the steepest rate.
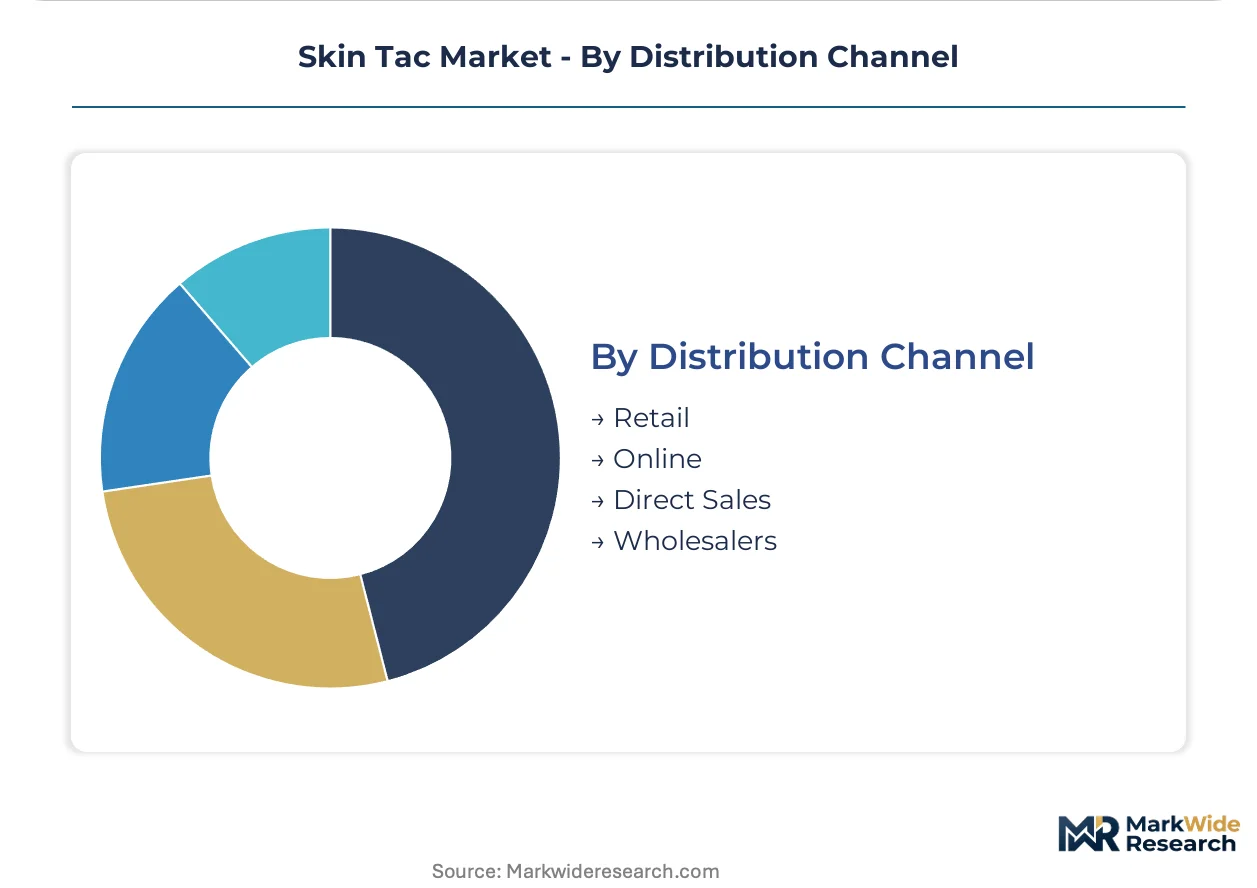
Distribution Channel:
Margin compression through wholesaler intermediaries contrasts with direct-to-patient capture enabled by platform consolidation in diabetes supply ecosystems.
- Online:Specialized diabetes supply platforms bundle Skin Tac with continuous glucose monitor consumables. Amazon and dedicated medical supply marketplaces disintermediate traditional hospital procurement channels.
- Retail:Pharmacy chains stock pad and liquid formats for ostomy and wound care patients. CVS and Walgreens in the United States allocate shelf space based on Medicare reimbursement recognition.
- Direct Sales:Manufacturer field representatives call on wound care nurses and diabetes educators. 3M and Smith & Nephew maintain dedicated clinical specialist teams for hospital formulary access.
- Wholesalers:McKesson and Cardinal Health aggregate fragmented clinic demand across United States territories. Wholesaler margins compress as procurement departments centralize purchasing authority.
Wholesalers anchor the volume base while online channels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home-care patients in Japan exhibit the lowest price elasticity for extended-wear formulations, while procurement departments in United States hospitals enforce aggressive contract negotiations that compress margins for standard liquid barriers.
United States
Medicare durable medical equipment codes now recognize adhesive barriers as separately billable, expanding home-care reimbursement beyond hospital bundled supplies. FDA 510(k) pathway standardization accelerates vendor qualification timelines for liquid barrier formulations. The Minneapolis-St. Paul corridor hosts 3M Company's polymer science infrastructure, sustaining pricing power across integrated delivery network procurement channels.
Germany
Statutory health insurance systems sustain wound-care margin depth despite polymer feedstock volatility, with seven-day wear barriers dominating chronic wound protocols. EU Green Deal chemical sustainability criteria pressure manufacturers to reformulate solvent-based adhesives toward water-borne alternatives. The Cologne-Düsseldorf industrial cluster concentrates aqueous dispersion equipment investments as Dutch and Belgian spray-format lines face acute retooling pressure.
Japan
Aging demographic expansion pulls demand for fourteen-day wear formulations beyond current polymer science limits, creating unmet need in continuous glucose monitor applications. METI standards align with ISO 10993 biocompatibility testing protocols, streamlining domestic manufacturer certification. The Osaka-Kobe manufacturing belt anchors Nitto Denko Corporation's adhesive material production for regional medical device supply chains.
Brazil
ANVISA regulatory alignment with ISO 10993 standards reduces import friction for adhesive barrier manufacturers targeting Latin America's aging demographic. Home-care expansion in São Paulo and Rio de Janeiro metro areas outpaces clinic infrastructure development. The São Paulo state industrial corridor attracts specialty clinic procurement as distributors consolidate fragmented demand across Southeast and South regions.
United Kingdom
NHS procurement frameworks prioritize trauma-free removal properties for pediatric and geriatric segments, opening premium positioning for silicone-acrylic hybrid formulations. EMA Medical Device Regulation standards extend certification timelines for water-borne adhesive alternatives. The Cambridge-Oxford-London triangle concentrates wound-care research networks that influence hospital formulary decisions across England and Wales.
Skin Tac Market Competitive Landscape
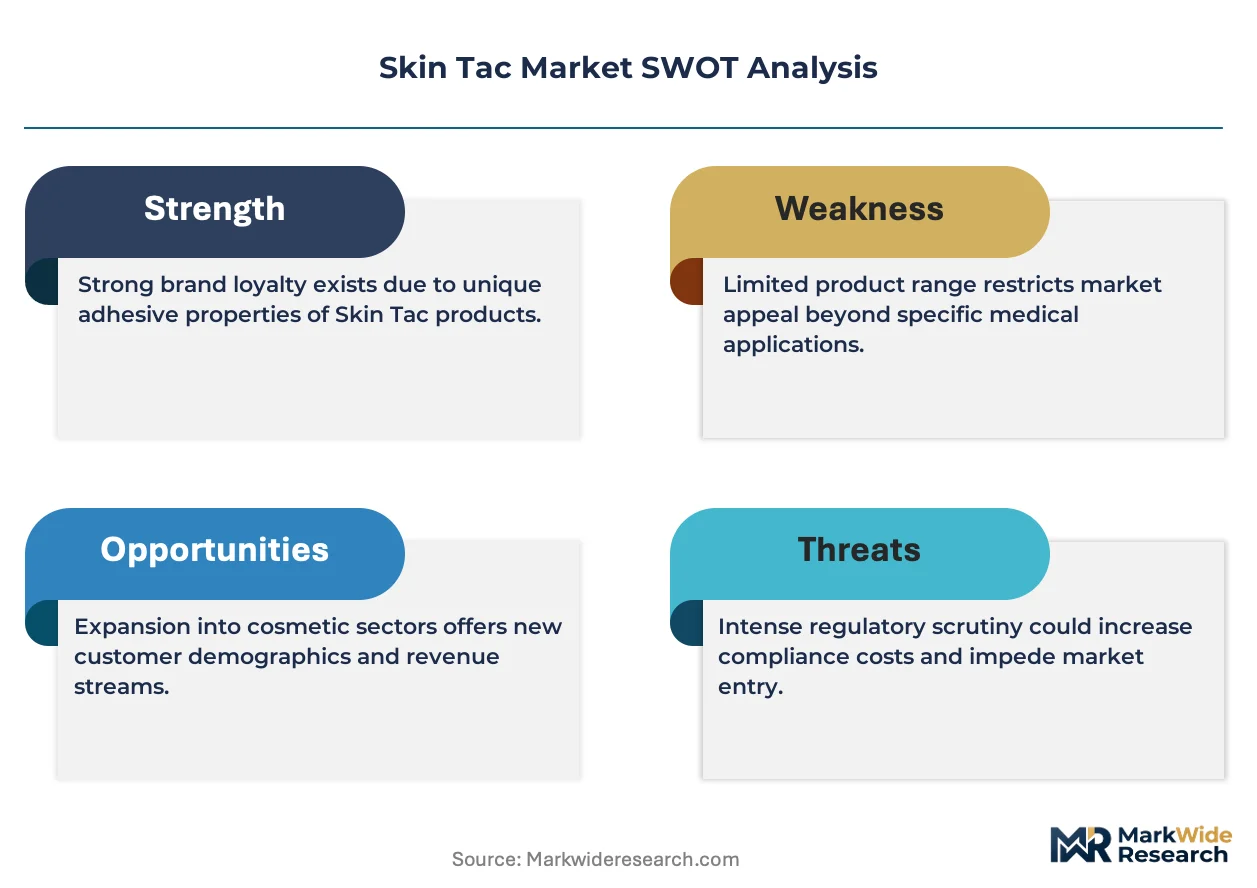
A small set of integrated leaders sits above a broader specialist tier that competes on formulation chemistry and channel access. The upper tier commands hospital procurement contracts through polymer science infrastructure and dedicated clinical specialist teams. The specialist tier fragments across wound-care distribution networks, diabetes supply platforms, and ostomy care channels. Strategic moves concentrate on aqueous dispersion equipment investments and direct-to-patient e-commerce platform development.
Among diversified materials conglomerates, 3M Company and DuPont de Nemours, Inc. occupy positions that exemplify integrated polymer science capabilities spanning medical, industrial, and consumer adhesive applications. Coloplast Group and Smith & Nephew Plc represent dedicated medical device specialists that anchor competitive positioning through wound-care distribution network control and trauma-free removal formulation expertise. Henkel AG & Co. KGaA sits within the adhesive technology tier that supplies copolymer resin formulations across industrial and medical end uses.
| Leading Market Players |
|---|
| Solventum |
| Avery Dennison Corporation |
| Johnson & Johnson |
| Coloplast Group |
| Smith & Nephew Plc |
| 3M Company |
| Nitto Denko Corporation |
| Henkel AG & Co. KGaA |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Chinese chemical conglomerates manufacturing medical-grade isocyanate precursors anchors price floors for copolymer resin formulations, concentrating supply-side leverage among feedstock specialists while compressing margin stability for mid-scale adhesive barrier manufacturers lacking long-term offtake agreements.
Pricing Analysis
After-sales service bundling with continuous glucose monitor consumables drives lifetime value capture for home-care channel participants. Three-tier pricing structure across premium silicone-acrylic hybrids, standard liquid barriers, and economy pad formats stratifies the market, with FDA 510(k) certification tier and volume scale as primary differentiation drivers. Cost compression in standard liquid formulations is intensifying because hospital procurement departments centralize purchasing authority through group purchasing organizations. Home-care patients exhibit the lowest price sensitivity for extended-wear spray configurations, while clinic buyers prioritize per-unit economy in bulk liquid procurement.
Supply Chain Analysis
Isocyanate precursor concentration within German and Chinese chemical manufacturing clusters underwrites supply vulnerability for medical adhesive barrier producers. Copolymer resin production draws from petrochemical feedstocks in the United States, Germany, and Japan, with aqueous dispersion equipment investments concentrated in the Netherlands and Belgium. Single-source dependency on medical-grade adhesive precursors creates geographic chokepoint exposure. Distribution runs through hospital procurement intermediaries, diabetes supply e-commerce platforms, and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated home-care procurement platforms that bundle adhesive barriers with continuous glucose monitor consumables, fragmenting traditional hospital wound-care distributor influence.
For Market Incumbents: Consolidate aqueous dispersion capacity in the Cologne-Düsseldorf industrial cluster ahead of EU Green Deal solvent phase-out deadlines. Deepen backward integration into copolymer resin supply through long-term offtake agreements with German and Chinese chemical conglomerates, neutralizing feedstock volatility exposure from petrochemical derivative fluctuations. For New Entrants and Emerging Players: Lead with spray-format aqueous formulations targeting Brazil's ANVISA-aligned regulatory environment, where home-care expansion outpaces clinic infrastructure development. Capture white-space opportunity in fourteen-day continuous glucose monitor applications currently blocked by polymer science adhesion limits. Deploy direct-to-patient e-commerce partnerships with specialized diabetes supply platforms to bypass entrenched hospital procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aqueous dispersion specialists with ISO 10993-5 cytotoxicity testing capabilities and established e-commerce channel access. Long-term viability rests on water-borne chemistry transition completion and home-care reimbursement code expansion. Monitor EU REACH substance restriction amendment timelines as inflection indicators for solvent-based formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Dispersion Capacity Expansion | EU Green Deal compliance requires solvent-to-water-borne retooling in Netherlands and Belgium production lines. |
| ISO 10993-5 Cytotoxicity Certification Investment | FDA 510(k) pathway standardization accelerates vendor qualification for liquid barrier hospital procurement. |
| Direct-to-Patient E-Commerce Platform Development | Specialized diabetes supply platforms disintermediate traditional wound-care distributor margins in United States home care. |
| Long-Term Isocyanate Supply Agreement | German and Chinese chemical conglomerate concentration creates chokepoint vulnerability for mid-scale manufacturers. |
| Silicone-Acrylic Hybrid Formulation R&D | Trauma-free removal properties open pediatric and geriatric segments previously blocked by skin integrity concerns. |
Research Methodology
A standing panel of hospital wound-care nurses, diabetes educators, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA Medical Device Regulation submissions, CMS Medicare reimbursement databases, and customs trade records for copolymer resin imports. Bottom-up segment sizing and top-down market triangulation reconciled formulation-format demand with end-user procurement patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include formulation chemistry, application setting, end-user site of care, and distribution channel configuration. CAGRs were derived from time-series analysis of continuous glucose monitor penetration curves and home-care demographic expansion trajectories, with polymer feedstock price indices and reimbursement code recognition timelines as industry-specific forecast inputs.
Underlying assumptions cover EU Green Deal implementation timelines and ISO 10993 testing protocol stability, with deviation risk concentrated in REACH substance restriction amendments and petrochemical derivative volatility. Practitioners should keep alternative scenarios live as ANVISA regulatory alignment progress and aqueous dispersion equipment lead times evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Empty IV Bags Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Micro Vials Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Suture Wire Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Safety Needles Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Veterinary Syringes Market