
 Italy Ostomy Care and Accessories Market | 2026-2036
Italy Ostomy Care and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Ostomy Care and Accessories Market Insights
MDR is decoupling low-cost imports from viable market participation by mandating clinical evidence and post-market surveillance for ostomy devices. Coloplast A/S dominates hydrocolloid barrier technology through its in-house polymer research. B. Braun Melsungen anchors hospital procurement channels across northern Italy with integrated wound and stoma portfolios. Hollister Incorporated differentiates through dedicated stoma care nurse education programs that lock in clinician preference.
Ostomy care and accessories encompass drainage collection systems, skin-protective barriers, and pouching solutions engineered from multilayer films with odor-blocking activated carbon filters and moisture-wicking nonwoven backings; these devices manage effluent diversion following surgical creation of a stoma in the abdominal wall. Colostomy bags occupy the largest product volume share due to the prevalence of colorectal cancer interventions, while skin barriers capture disproportionate margin pools because adhesive formulation patents create switching costs. Home care leads end-user growth as Italy's regions expand telemedicine reimbursement for stoma nurse remote monitoring, though hospitals still control initial fitting and patient training workflows.
Italy's Ministry of Health coordinates with AIFA to classify ostomy products within the national medical device reimbursement registry, where CE marking under MDR and conformity with UNI EN ISO 13485 quality standards determine market access eligibility. Regional health authorities in Lombardy and Veneto operate parallel tendering systems that fragment procurement rules and force manufacturers to navigate multiple compliance pathways. Stakeholders must monitor how Italy's planned harmonization of regional device purchasing pools will reshape competitive access for both established suppliers and emerging barrier technology developers.
Market Dynamics
Italy's Medical Device Regulation (MDR) transition is restructuring competitive access by decoupling low-cost imports from viable participation through mandatory clinical evidence and post-market surveillance requirements for ostomy devices.
Growth Catalysts
- Regional telemedicine expansion:Lombardy and Veneto health authorities now reimburse remote stoma nurse monitoring, accelerating home care migration away from hospital-centric follow-up.
- UNI EN ISO 13485 harmonization:Quality standard alignment streamlines manufacturer certification pathways, reducing time-to-market for advanced barrier technologies.
- Colorectal intervention volume:Surgical procedure rates in northern Italy's dense clinic networks sustain baseline demand for colostomy systems.
Market Restraints
- Hydrocolloid polymer cost volatility:Specialized adhesive raw materials face supply concentration among European chemical suppliers, compressing margin pools for domestic converters.
- Regional tender fragmentation:Parallel procurement systems across Lombardy, Veneto and Emilia-Romagna force redundant compliance investments without scale economies.
- MDR clinical evidence burden:Small manufacturers lack resources to generate post-market surveillance data, consolidating viable supply among capitalized multinationals.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily lack specialized stoma care clinic density, creating whitespace for mobile nurse networks and direct-to-patient distribution.
- Activated carbon filter convergence:Integration of odor-blocking layers with moisture-wicking nonwoven backings enables premium pouch differentiation.
- National purchasing pool harmonization:Planned Ministry of Health centralization of regional device procurement would simplify market access for emerging barrier developers.
Industry Challenges
- Stoma care nurse shortage:Specialized wound and ostomy certification programs produce insufficient graduates to match patient-to-clinician ratios required for home care expansion.
- Legacy hospital procurement lock-in:Integrated wound and stoma portfolio contracts create switching friction for standalone ostomy specialists seeking hospital channel entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Ostomy Care and Accessories Market |
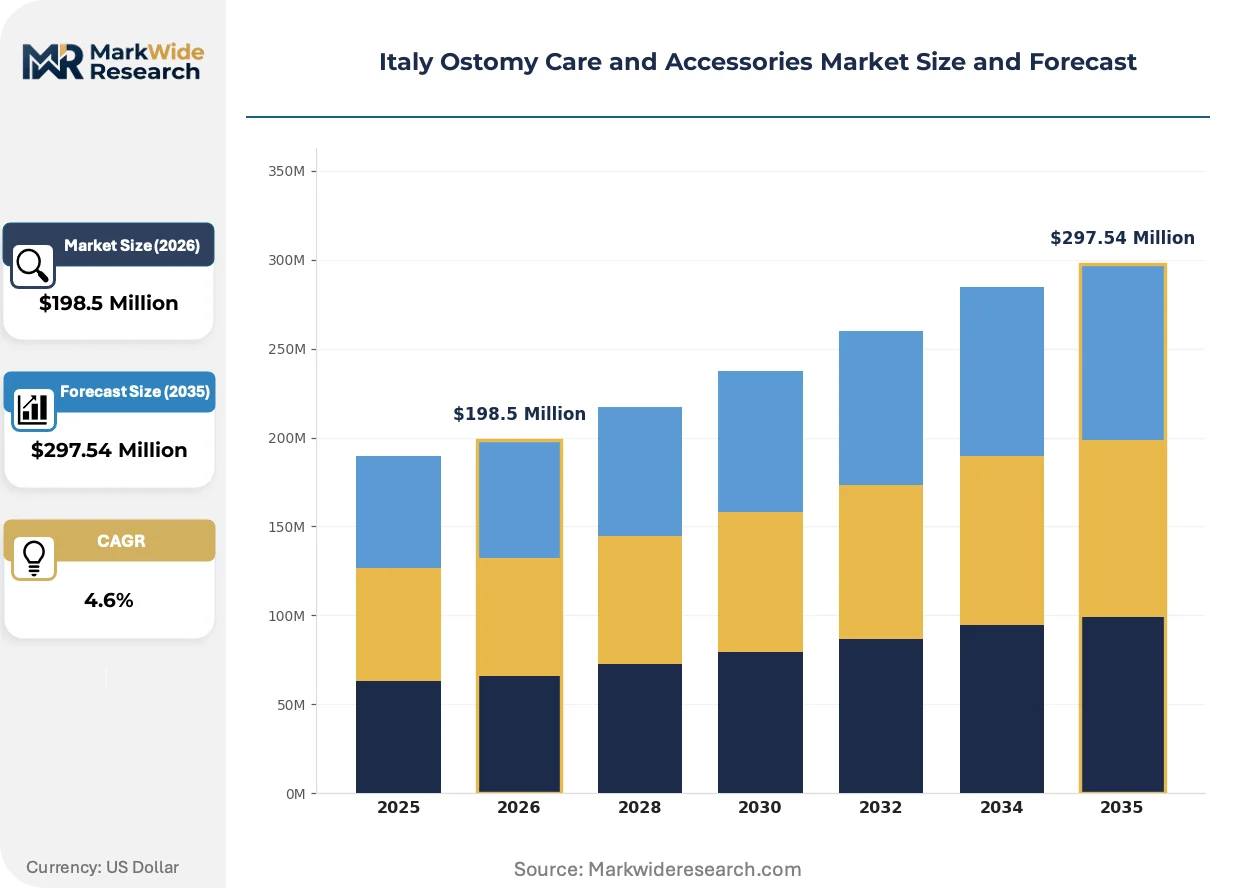
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $297.54 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colostomy Bags, Ileostomy Bags, Urostomy Bags, Skin Barriers Application: Chronic Illness, Post-Surgical Care, Pediatric Care, Oncology End User: Hospitals, Home Care, Ambulatory Surgical Centers, Nursing Facilities Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | B. Braun Melsungen, PAUL HARTMANN AG, Coloplast A/S, Salts Healthcare Ltd., ALCARE Co., Ltd, ConvaTec Group PLC, Dansac A/S, Welland Medical Limited, Hollister Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Ostomy Care and Accessories Market Trends and Innovations
Multilayer film engineering and remote patient monitoring infrastructure are converging to redefine how ostomy systems integrate into chronic care workflows across Italy's regional health systems.
Smart barrier systems incorporating pH-sensing adhesives and wearable connectivity modules are unifying skin health monitoring with effluent management. Home care providers in Lombardy pilot these platforms to reduce emergency department visits for peristomal complications. The technology is unifying previously separate device and service revenue streams into subscription-based remote care models.
Italy's MDR implementation timeline for Class IIa medical devices compresses certificate validity periods and mandates annual surveillance audits. Manufacturers must rebuild technical documentation for legacy products or face market withdrawal. Northern regional health authorities now require MDR compliance as a tender prerequisite, accelerating supplier consolidation.
Patients increasingly self-direct pouch and barrier purchases through pharmacy channels rather than awaiting hospital supply fulfillment. This channel migration fragments volume across retail points and reduces manufacturer visibility into actual consumption patterns. Veneto's regional formulary system responds by creating direct-ship programs that preserve hospital reimbursement while accommodating patient preference.
Italy Ostomy Care and Accessories Market Segmentation
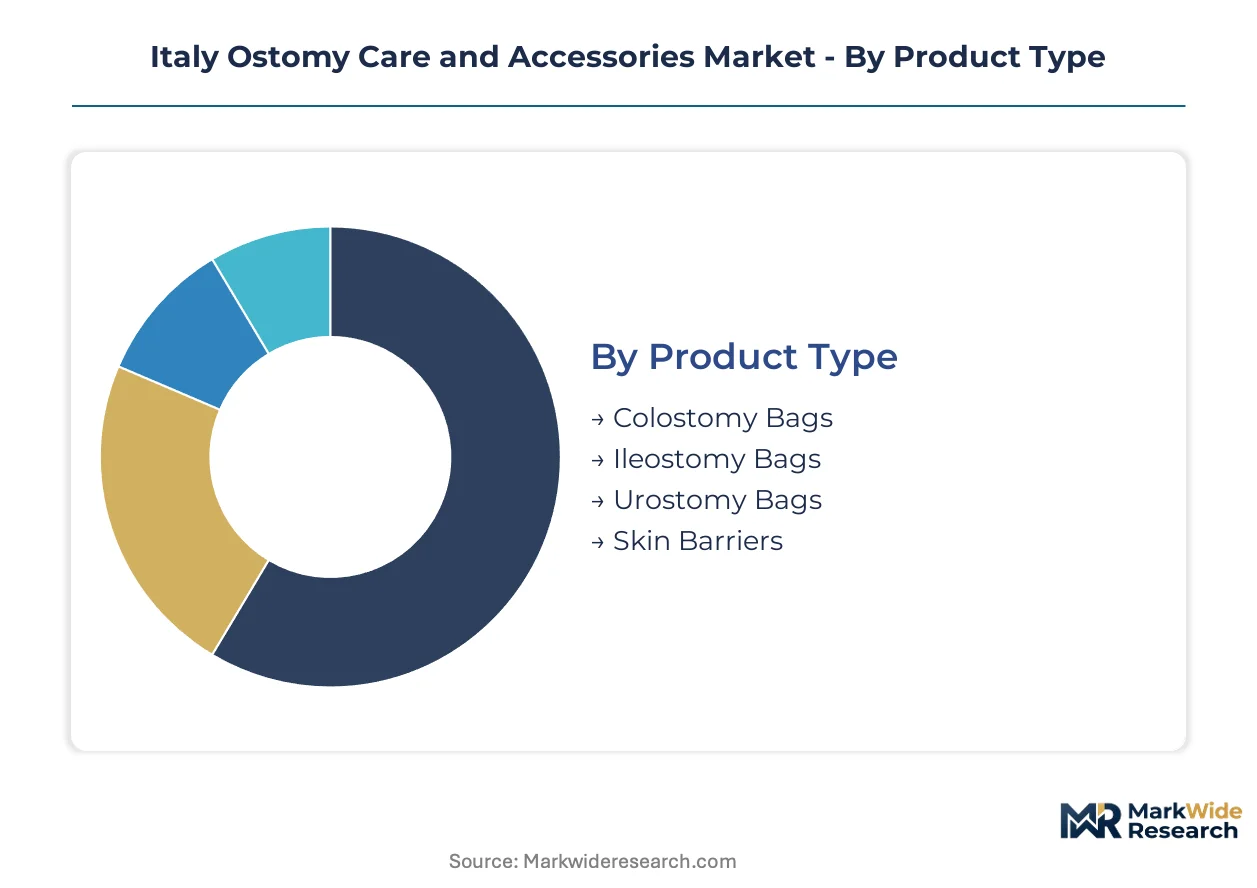
Segmentation in Italy's ostomy care market reveals divergent margin structures across device categories and care settings. Procurement concentration in northern regions and reimbursement channel fragmentation create distinct competitive battlegrounds for each segment tier.
Product Type:
Patient anatomy and surgical indication drive device selection, with reimbursement eligibility hinging on Ministry of Health classification tiers.
- Colostomy Bags:These one-piece and two-piece pouching systems employ multilayer films with activated carbon odor barriers to manage colonic effluent. Demand concentrates in Lombardy's dense oncology networks, where colorectal intervention volumes sustain bulk procurement contracts.
- Skin Barriers:Hydrocolloid and acrylic adhesive formulations protect peristomal skin while enabling pouch attachment. Northern Italy's specialized stoma care clinics generate premium pricing for advanced barrier technologies with extended wear times.
- Ileostomy Bags:Higher-capacity systems with enhanced drainage mechanisms manage liquid effluent from small intestine diversions.
- Urostomy Bags:Urinary diversion pouches incorporate anti-reflux valves and night drainage adapters for neobladder patients.
Colostomy bags lead on scale; skin barriers lead on momentum.
Application:
Clinical urgency and care duration shape procurement patterns, with chronic conditions enabling subscription-based supply models absent in acute post-surgical episodes.
- Post-Surgical Care:Immediate postoperative fitting requires hospital-based stoma nurse intervention and standardized starter kits. Veneto's regional health authorities mandate specific product formularies for initial discharge supplies, locking in manufacturer relationships.
- Chronic Illness:Long-term management of inflammatory bowel disease and diverticular conditions generates recurring revenue through pharmacy channel replenishment. Lombardy's telemedicine reimbursement expansion accelerates remote monitoring integration for this cohort.
- Oncology:Cancer-related ostomies demand specialized barrier systems for radiation-compromised skin.
- Pediatric Care:Smaller anatomical specifications and growth accommodation requirements drive custom fabrication needs.
Chronic illness leads on scale; post-surgical care leads on momentum.
End User:
Care setting determines reimbursement pathway complexity, with hospital procurement governed by regional tender systems and home care subject to pharmacy benefit structures.
- Home Care:Patient-directed management through pharmacy and online channels now captures the steepest expansion trajectory as Italy's regions expand remote nurse monitoring reimbursement. Emilia-Romagna's direct-ship programs preserve hospital reimbursement while accommodating patient channel preference.
- Hospitals:Initial fitting and patient training workflows remain concentrated in acute settings, with B. Braun and Coloplast anchoring integrated wound and stoma portfolio contracts across northern procurement regions.
- Ambulatory Surgical Centers:Same-day discharge protocols compress fitting timeframes and favor pre-sterilized kit configurations.
- Nursing Facilities:Institutional long-term care generates volume demand for economy-tier pouching systems with simplified application.
Hospitals lead on scale; home care leads on momentum.
Distribution Channel:
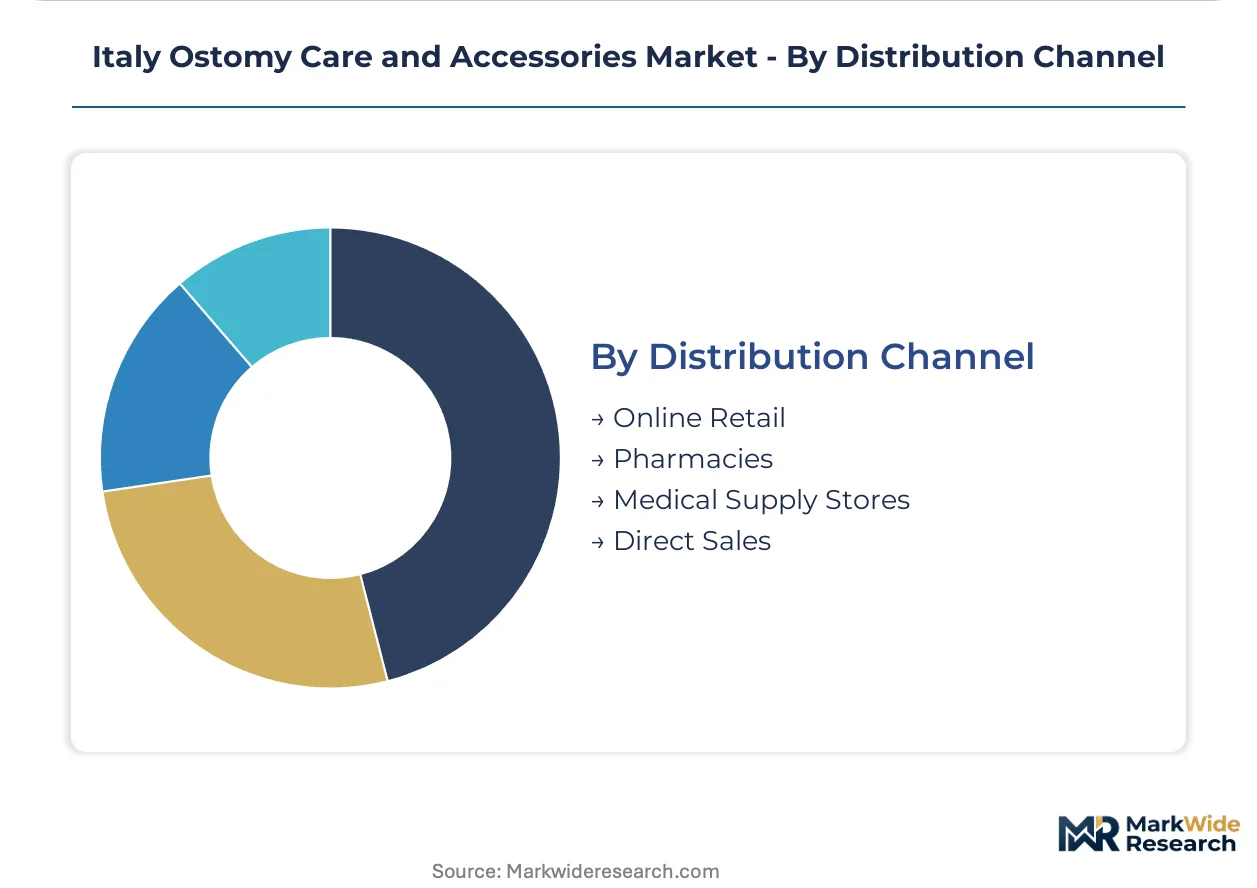
Channel selection reflects patient mobility, digital literacy, and regional formulary access constraints.
- Pharmacies:Community retail points dominate recurring supply replenishment, with regional formularies determining product availability. Veneto's pharmacy network processes the majority of reimbursed ostomy supply claims under AIFA coordination.
- Online Retail:Direct-to-patient platforms gain share among younger cohorts and rural populations facing clinic access barriers. Sicily and Campania's underpenetrated clinic density accelerates digital channel adoption.
- Medical Supply Stores:Specialized durable medical equipment dealers serve patients requiring fitting consultation.
- Direct Sales:Manufacturer field representatives secure institutional contracts through hospital procurement committees.
Pharmacies lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized stoma care nurse concentrations in northern Italy anchor the country's ostomy device expertise, with Lombardy and Emilia-Romagna hosting the densest clinical training networks. Regional health authorities operate fragmented procurement systems that shape competitive access patterns. Southern regions present whitespace opportunities due to clinic underpenetration.
Lombardy
Milan's oncology hub generates colorectal intervention volumes that sustain bulk procurement contracts for colostomy systems. The regional health authority reimburses remote stoma nurse monitoring through expanded telemedicine protocols. B. Braun anchors hospital procurement channels with integrated wound and stoma portfolio contracts across the province.
Veneto
Regional formulary systems mandate specific product configurations for initial discharge supplies, locking manufacturer relationships at the hospital exit point. The pharmacy network processes the majority of reimbursed ostomy supply claims under AIFA coordination. Verona and Padua host specialized stoma care clinics that generate premium pricing for advanced barrier technologies.
Emilia-Romagna
Bologna's medical device cluster supports converter operations for hydrocolloid adhesive formulations. Direct-ship programs preserve hospital reimbursement while accommodating patient channel preference for home delivery. The region operates parallel tendering systems that force redundant compliance investments without scale economies.
Campania
Naples and surrounding provinces lack specialized stoma care clinic density relative to patient populations. Mobile nurse networks and direct-to-patient distribution models present whitespace opportunities for market entry. Online retail channels gain share among younger cohorts facing clinic access barriers.
Sicily
Palermo and Catania exhibit underpenetrated clinic infrastructure that accelerates digital channel adoption for supply replenishment. Regional health authorities lag in telemedicine reimbursement expansion compared to northern counterparts. Pharmacy networks remain the dominant reimbursed supply channel despite geographic access constraints.
Italy Ostomy Care and Accessories Market Competitive Landscape
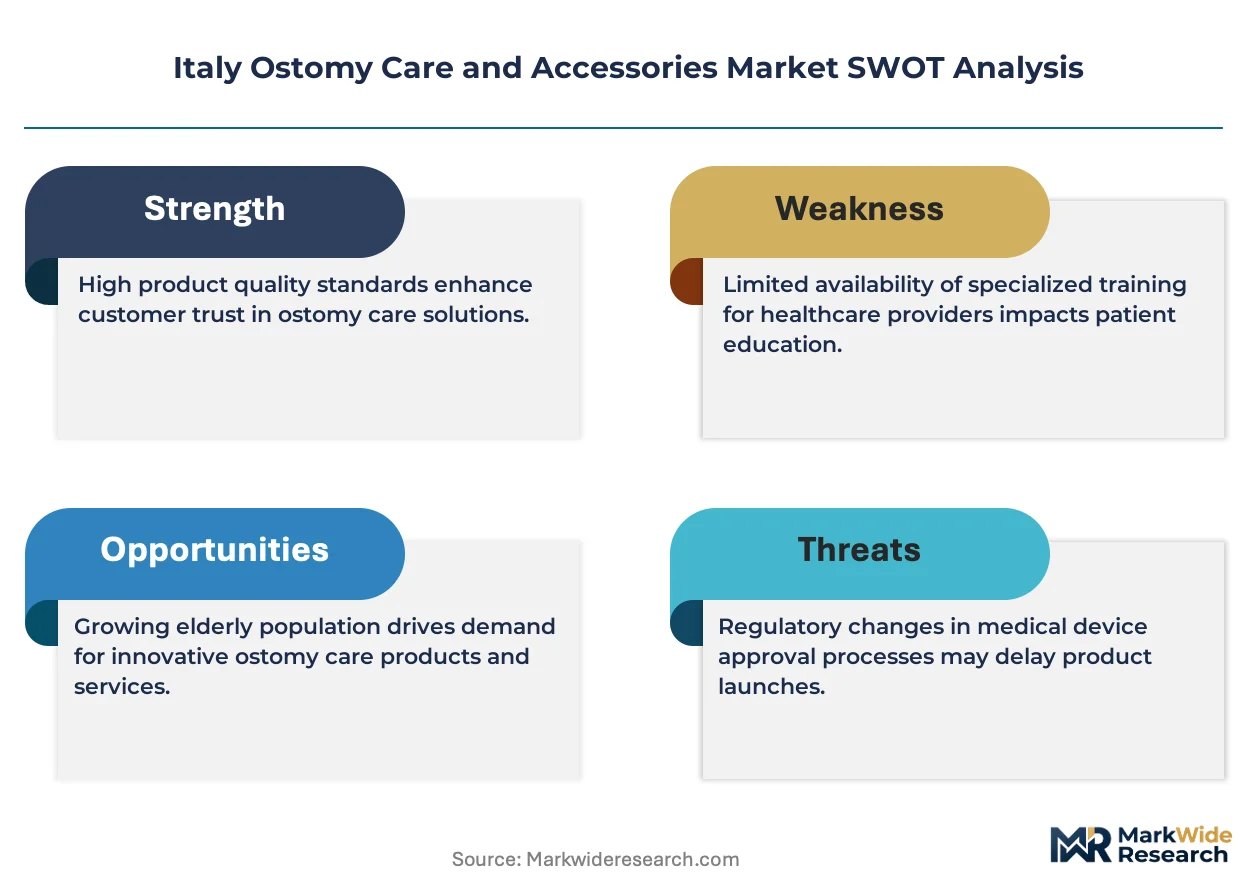
Diversified conglomerates compete with focused pure-play specialists across Italy's ostomy care market, creating a tiered structure where capitalized multinationals control hospital procurement and smaller converters serve pharmacy channels. The vendor base separates into three strategic archetypes: integrated wound care conglomerates with stoma portfolios, dedicated ostomy technology developers, and regional converters serving local tender systems. M&A activity consolidates viable supply among MDR-compliant entities, while strategic partnerships between device manufacturers and telemedicine platforms unify hardware with remote monitoring services.
Among the integrated wound and stoma portfolio holders, B. Braun Melsungen and Coloplast A/S occupy positions that exemplify divergent competitive approaches—B. Braun anchoring hospital procurement through bundled contracts, Coloplast representing dedicated barrier technology specialization. Hollister Incorporated sits within the education-driven archetype, where clinician training programs lock in preference formation. These three entities collectively illustrate how competitive positioning in Italy's ostomy market depends on channel control, technology depth, and service integration rather than product differentiation alone.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| PAUL HARTMANN AG |
| Coloplast A/S |
| Salts Healthcare Ltd. |
| ALCARE Co., Ltd |
| ConvaTec Group PLC |
| Dansac A/S |
| Welland Medical Limited |
| Hollister Incorporated |
| Others |
Pricing and Supply Chain Analysis
Hydrocolloid polymer resin costs cascade through Italy's ostomy device value chain, compressing converter margins in Emilia-Romagna while enabling premium pricing for patented adhesive formulations in Lombardy's specialized clinic networks. Raw material concentration among German and Belgian chemical suppliers feeds into three-tier pricing stratification across premium extended-wear barriers, standard hospital formulary systems, and economy-tier pharmacy channel products.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes competitive positioning across Italy's regional health systems. Hospital procurement contracts favor integrated wound-stoma portfolios with embedded nurse training services, while pharmacy channel transactions isolate device pricing from clinical support. Price differentiation hinges on MDR compliance certification and hydrocolloid wear-time performance, with northern regional tenders commanding premium tiers and southern markets gravitating toward economy alternatives. Cost compression in standard-tier barriers is intensifying because raw material volatility transfers downstream without corresponding reimbursement adjustments. Home care patients exhibit highest price sensitivity due to out-of-pocket exposure, whereas hospital purchasing committees prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Freight cost volatility from German and Belgian polymer suppliers strains just-in-time converter operations across Italy's northern manufacturing belt. Geographic supply concentration centers on Germany for hydrocolloid resins, Belgium for acrylic adhesives, and domestic Emilia-Romagna facilities for multilayer film lamination. Raw material dependencies encompass petroleum-derived polymers, medical-grade activated carbon, and moisture-wicking nonwoven substrates. Single-source vulnerability in specialized adhesive chemistry creates procurement risk for MDR-transitioning manufacturers. Distribution runs through regional pharmacy networks for recurring patient replenishment, with direct-ship programs emerging as Veneto and Emilia-Romagna experiment with hospital-reimbursed home delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's ostomy market functions as a geographic-arbitrage play where MDR compliance costs in northern Europe create entry barriers that southern Italian underpenetration partially offsets through lower channel establishment expenses.
For Market Incumbents: To counter MDR-driven supplier consolidation, anchor hospital procurement through backward integration into hydrocolloid formulation capacity within Emilia-Romagna's chemical cluster. Deepen telemedicine service bundling to lock in Lombardy's remote monitoring reimbursement expansion and create switching friction against emerging barrier developers. For New Entrants and Emerging Players: Capture Campania and Sicily's clinic whitespace through mobile nurse networks paired with direct-to-patient online distribution. Target pharmacy channel bypass strategies in regions where hospital formulary lock-in remains incomplete, leveraging Veneto's direct-ship program architecture as a proven reimbursement pathway template. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR surveillance audit burdens exceed small converter cash flow capacity, creating distressed acquisition opportunities among ISO 13485-certified regional formulators. Monitor AIFA reimbursement registry harmonization signals as inflection indicators for national purchasing pool centralization that would reshape competitive access economics.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Rebuild | Certificate validity compression under Italy's Class IIa timeline forces legacy product portfolio reinvestment or withdrawal. |
| Telemedicine Platform Partnership | Lombardy's remote stoma nurse reimbursement protocols unify device and service revenue into subscription models. |
| Regional Tender System Navigation | Parallel procurement pathways across Lombardy, Veneto and Emilia-Romagna demand redundant compliance investments without scale. |
| Southern Italy Mobile Nurse Network | Campania's clinic underpenetration enables direct-to-patient distribution models that bypass hospital formulary gatekeepers. |
| Hydrocolloid Polymer Backward Integration | Captive adhesive supply from German-Belgian chemical inputs insulates margin compression from European supplier concentration. |
Research Methodology
Bottom-up patient cohort modeling reconciled against top-down hospital procurement tracking forms the analytical core of this study. Primary interviews with stoma care nurses, hospital purchasing committee members, biomedical engineers and regional GPO contracts managers were cross-validated against secondary sources including AIFA reimbursement registry filings, regional health authority tender databases, UNI EN ISO 13485 certification records and Ministry of Health medical device classification documentation. Triangulation between demand-side patient volume estimates and supply-side manufacturer shipment patterns ensures segmentation integrity across product type, application and end-user dimensions.
Historical procedure volume trendlines from northern Italy's oncology networks anchor the projection framework, with CAGR derivation reflecting surgical intervention rates, home care migration velocity and telemedicine reimbursement expansion trajectories across the analysis window. Segmentation modeling incorporates product architecture (one-piece versus two-piece systems), care setting transition patterns (hospital-to-home shift rates), regional regulatory cluster heterogeneity and channel fragmentation depth. Forecast inputs encompass colorectal cancer incidence data, inflammatory bowel disease prevalence estimates and stoma care nurse workforce growth constraints.
MDR implementation timeline delays, regional purchasing pool harmonization reversals and hydrocolloid raw material supply disruptions are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Cryotubes Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Safety Needles Market