
 Petri Dishes Market | 2026-2036
Petri Dishes Market Size, Share, and Industry Trends Forecast 2026-2036
Petri Dishes Market Outlook
Modular bundling of sterile petri dishes with compatible lids and ventilation options is pivoting procurement patterns across European and North American laboratories. Greiner AG leverages integrated manufacturing of polystyrene resins and finished dishes to control cost curves. SARSTEDT AG anchors distribution through direct hospital and research laboratory channels in Germany and Austria. Thermo Fisher Scientific differentiates via bundled workflow solutions that incorporate disposable petri dishes within broader cell culture platforms.
Petri dishes are shallow cylindrical vessels, typically 90–100 mm in diameter and 15–20 mm in height, manufactured from borosilicate glass or injection-molded polystyrene, designed to provide a sterile, flat surface for microbial culture, cell propagation, or chemical diffusion assays. Disposable polystyrene variants dominate volume due to elimination of autoclave reprocessing costs in high-throughput pharmaceutical screening. Biochemical petri dishes with treated surfaces for adherent cell culture command premium positioning within oncology and stem cell research workflows. Glass segments retain stable demand from educational institutions and environmental monitoring agencies requiring repeated sterilization cycles.
The FDA enforces 21 CFR Part 820 quality system regulations for medical-grade laboratory plastics, while the EU MDR mandates CE marking and post-market surveillance for devices used in diagnostic applications. ISO 11137 sterilization validation standards shape supplier qualification protocols, particularly for pharmaceutical company vendors. REACH compliance in Europe restricts certain plasticizers in polystyrene formulations, redirecting R&D toward polypropylene alternatives. Stakeholders must monitor evolving biocompatibility testing requirements as cell therapy manufacturing scales beyond traditional research volumes.
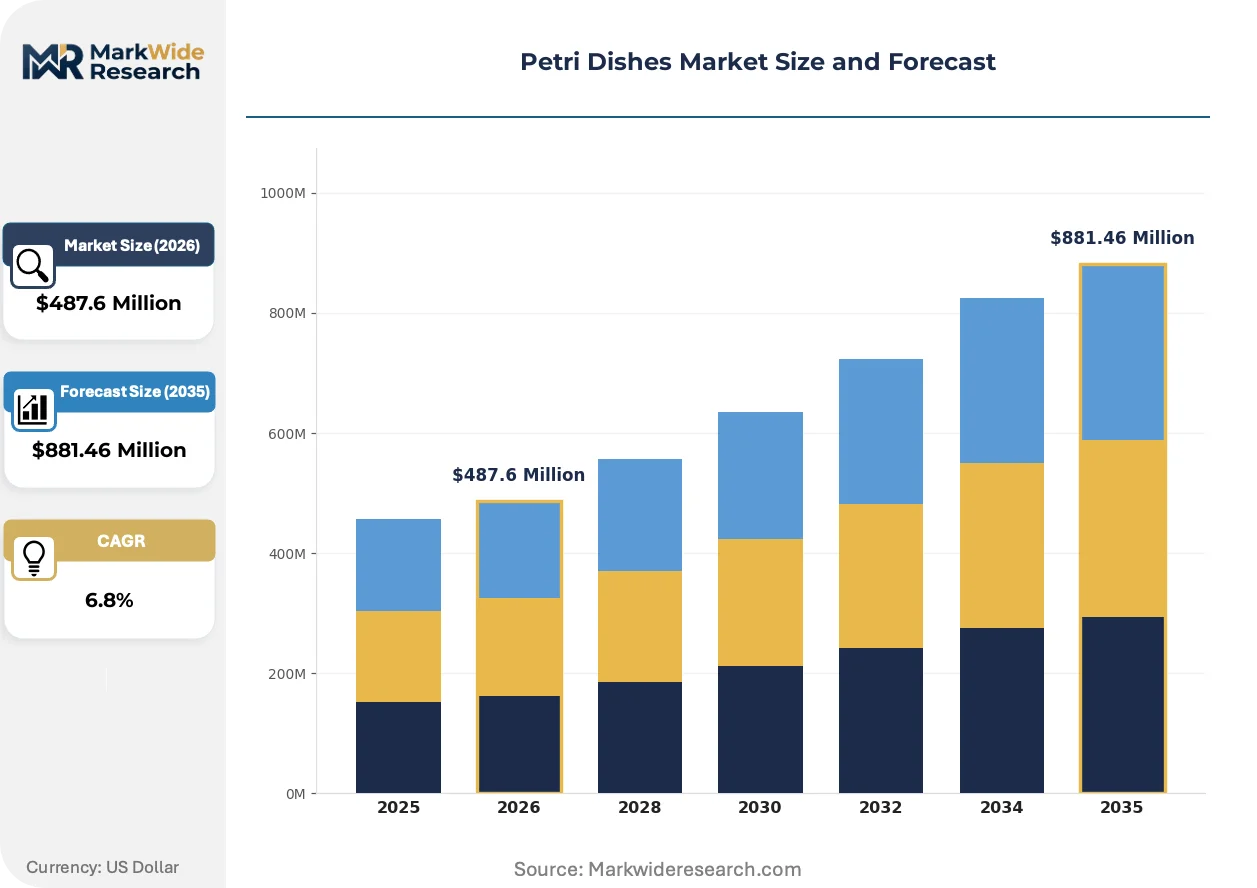
Market Dynamics
Pharmaceutical sterilization standards are compressing supplier qualification timelines while polystyrene resin volatility reshapes contract structures across laboratory consumables procurement.
Growth Catalysts
- EU MDR sterilization mandates:CE marking requirements for diagnostic devices are forcing pharmaceutical vendors to pre-qualify petri dish suppliers against ISO 11137 validation protocols, locking in multi-year procurement contracts.
- Cell therapy manufacturing scale-up:Adherent cell culture workflows for CAR-T production are consuming treated-surface biochemical petri dishes at volumes exceeding traditional research laboratory throughput.
- German manufacturing cluster density:Concentrated injection-molding capacity around Stuttgart and Nuremberg enables 48-hour fulfillment windows for sterile consumables across Central European pharmaceutical hubs.
Market Restraints
- Polystyrene monomer cost volatility:Crude-derived styrene feedstock fluctuations transmit directly to petri dish unit economics, compressing margins for distributors without backward resin integration.
- Single-source sterilization dependency:Gamma irradiation capacity concentrates at three European contract facilities, creating bottleneck risk for batch-release timelines during peak pharmaceutical campaign periods.
- Glass-to-plastic substitution ceiling:Environmental monitoring agencies and educational institutions retain autoclave-compatible borosilicate demand, capping disposable polystyrene penetration in regulated water-testing workflows.
Strategic Opportunities
- Polypropylene formulation pivot:REACH plasticizer restrictions on polystyrene are accelerating R&D into propylene-based alternatives with comparable optical clarity and cell adhesion properties.
- Direct-to-laboratory e-procurement channels:Hospital and research institute buying groups are bypassing traditional distributor markups through integrated marketplace platforms with real-time sterile-stock visibility.
- Modular ventilation-lid bundling:Gas-permeable membrane accessories for anaerobic culture workflows command premium attach rates when co-merchandised with standard 90mm dish formats.
Industry Challenges
- Gamma sterilization validation backlog:ISO 11137 dose-mapping studies for new polymer formulations extend supplier qualification timelines by 8-14 months, delaying product launches.
- Cross-functional talent scarcity:Combined polymer chemistry and cell biology expertise required for surface-treatment R&D concentrates at a handful of German and Swiss research institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petri Dishes Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Petri Dishes, Biochemical Petri Dishes, Disposable Petri Dishes, Multi-well Plates Material: Glass, Polystyrene, Polypropylene, Polycarbonate End User: Research Laboratories, Hospitals, Educational Institutions, Pharmaceutical Companies Application: Microbiology, Drug Testing, Environmental Monitoring, Food Safety |
| Companies Covered | Greiner AG, SARSTEDT AG & Co. KG, Thermo Fisher Scientific Inc., TPP Techno Plastic Products AG, BD, Corning Incorporated, Avantor, Inc., CELLTREAT Scientific Products, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petri Dishes Market Strategic Shifts
Surface chemistry engineering and procurement platform digitization are compressing traditional sterile consumables supply chains while regulatory sterilization standards fragment vendor qualification protocols across jurisdictions.
Treated polystyrene with plasma-activated hydrophilic coatings is rewriting competitive positioning in adherent cell culture applications. Contract development and manufacturing organizations are specifying these surfaces for stem cell propagation workflows. The technology is compressing differentiation timelines for mid-tier suppliers previously competing on price alone.
REACH plasticizer restrictions are redirecting formulation R&D toward polypropylene and cyclic olefin copolymer alternatives. ECHA substance evaluation deadlines are accelerating substitution investments ahead of sunset date uncertainties. German laboratory plastics manufacturers are responding with pilot lines for medical-grade propylene resins.
Consolidated buying groups within university hospital systems are disintermediating traditional laboratory distributor networks. Group purchasing organizations negotiate direct sterile consumables contracts with manufacturers. This channel compression is most visible across Nordic and Benelux research hospital clusters where procurement centralization has advanced furthest.
Petri Dishes Market Segmentation
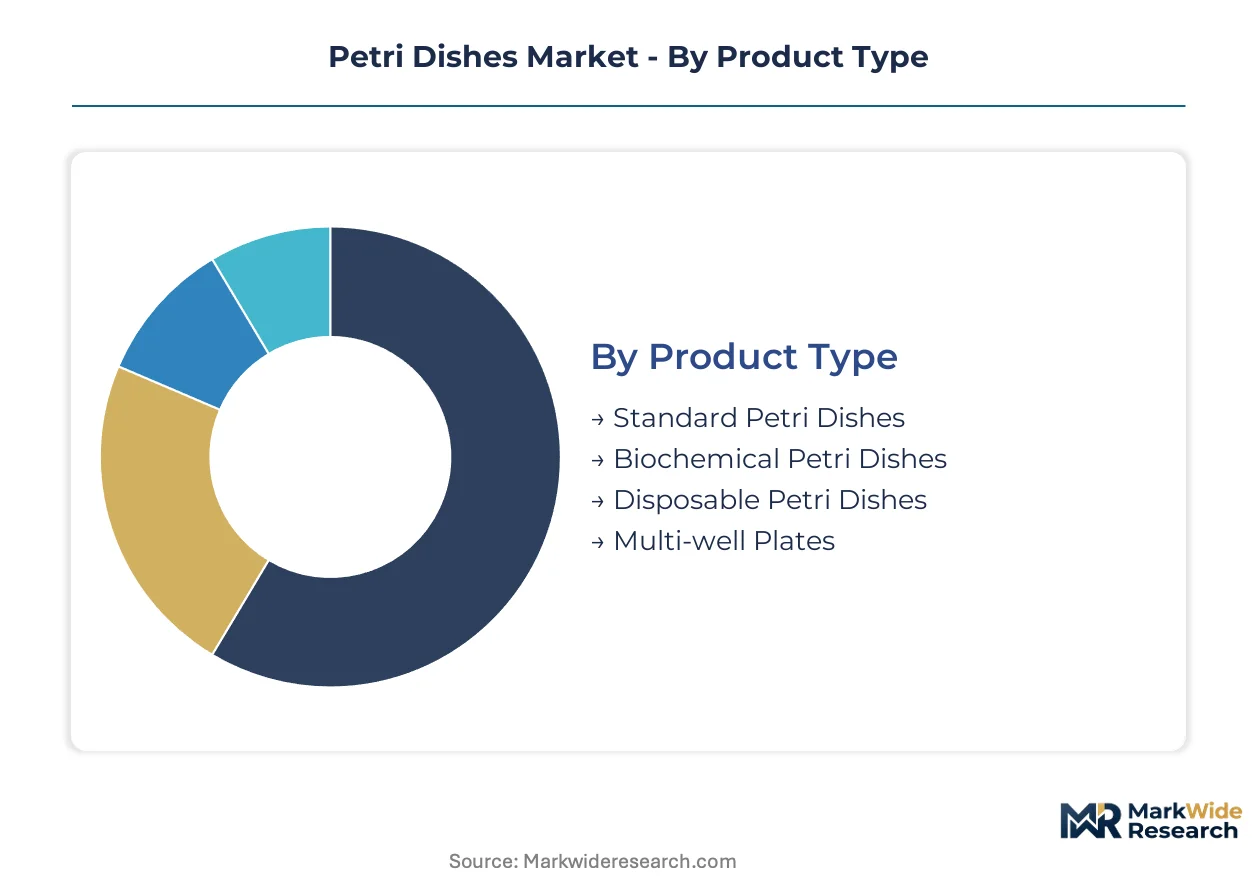
Petri dish procurement patterns diverge sharply between high-volume disposable workflows and precision-engineered biochemical formats. Understanding these segment boundaries clarifies where sterilization validation investments concentrate versus where unit cost optimization dominates supplier selection.
Product Type:
Disposable formats command volume leadership while biochemical variants extract premium pricing through surface engineering.
- Standard Petri Dishes:Injection-molded polystyrene vessels with untreated surfaces serve routine microbial culture and educational training protocols. Demand concentrates in Indian and Chinese educational procurement tenders where autoclave infrastructure scarcity favors single-use economics over glass reusability.
- Biochemical Petri Dishes:Plasma-activated hydrophilic coatings enable adherent cell propagation for stem cell and oncology research. CAR-T manufacturing workflows in German pharmaceutical facilities consume these at throughput rates exceeding traditional research laboratories by an order of magnitude.
- Disposable Petri Dishes:Pre-sterilized gamma-irradiated formats eliminate reprocessing labor in high-throughput screening operations.
- Multi-well Plates:Arrayed formats integrate with automated liquid handling systems for compound library screening.
Mature deployment sits with Standard Petri Dishes. Newer deployment is concentrated in Biochemical Petri Dishes.
Material:
Optical clarity requirements and sterilization compatibility dictate material selection across end-use applications.
- Glass:Borosilicate formulations withstand repeated autoclave cycles at 121°C for environmental monitoring agencies and educational institutions with captive sterilization infrastructure. German water-testing laboratories retain glass mandates for regulatory compliance in drinking water microbiology.
- Polystyrene:Amorphous thermoplastic delivers superior optical transparency and cost-efficient injection molding for disposable workflows. REACH plasticizer restrictions are redirecting formulation R&D toward propylene-based alternatives with comparable clarity profiles.
- Polypropylene:Semi-crystalline structure resists chemical stress cracking in aggressive solvent environments.
- Polycarbonate:High-impact strength supports reusable formats in industrial microbiology applications.
Polystyrene anchors current volume. Polypropylene is gaining share fastest as regulatory pressure intensifies.
End User:
Procurement sophistication varies from centralized hospital buying groups to fragmented educational purchasing.
- Research Laboratories:Academic and government facilities specify treated-surface biochemical formats for cell biology workflows. Nordic university hospital clusters have advanced procurement centralization furthest, disintermediating traditional distributor networks through direct manufacturer contracts.
- Pharmaceutical Companies:GMP-compliant sterile consumables procurement for cell therapy manufacturing commands the most stringent supplier qualification protocols. EU MDR CE marking requirements and ISO 11137 validation standards lock in multi-year supply agreements with pre-qualified vendors.
- Hospitals:Clinical microbiology laboratories prioritize batch-traceable sterile stock with rapid fulfillment windows.
- Educational Institutions:Budget-constrained procurement favors standard polystyrene formats in bulk packaging.
Educational Institutions represent the most price-sensitive tier. Pharmaceutical Companies deploy the most demanding qualification standards.
Application:
Regulatory stringency and throughput requirements fragment demand across use cases.
- Microbiology:Standard culture workflows for bacterial and fungal isolation dominate unit volume across clinical and industrial laboratories. German manufacturing clusters enable 48-hour sterile stock fulfillment for Central European pharmaceutical hubs.
- Drug Testing:High-content screening and cytotoxicity assays require optical-grade surfaces with minimal birefringence. Contract development organizations specify plasma-treated biochemical formats for stem cell propagation workflows.
- Environmental Monitoring:Drinking water and wastewater testing retains glass format mandates for regulatory reproducibility.
- Food Safety:Pathogen detection workflows in commercial laboratories prioritize pre-sterilized disposable formats.
Microbiology commands installed base leadership. Drug Testing shows the steepest expansion trajectory as cell therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in German industrial clusters while consumption disperses across pharmaceutical hubs in the United States, China, and Western Europe. This geographic split shapes fulfillment logistics and sterilization validation protocols.
Germany
Stuttgart and Nuremberg host dense injection-molding capacity for laboratory plastics serving Central European pharmaceutical demand. EU MDR sterilization mandates lock in multi-year supplier contracts with ISO 11137 validation requirements. Greiner AG and SARSTEDT AG anchor production clusters with 48-hour fulfillment windows to regional biotech facilities.
United States
FDA 21 CFR Part 820 quality system regulations govern medical-grade laboratory plastics procurement for cell therapy manufacturing. The Boston-Cambridge biotech corridor and San Diego research clusters drive treated-surface biochemical dish consumption. Thermo Fisher Scientific channels distribution through bundled workflow platforms targeting high-throughput screening operations.
China
NMPA regulatory frameworks for in-vitro diagnostic consumables are tightening import substitution policies for sterile laboratory plastics. Yangtze River Delta pharmaceutical manufacturers scale adherent cell culture workflows for domestic CAR-T production. Shanghai and Suzhou industrial parks attract polystyrene resin compounders serving regional disposable consumables demand.
India
CDSCO medical device regulations and BIS standards shape sterile consumables qualification for contract research organizations. Educational procurement tenders in Maharashtra and Karnataka favor disposable polystyrene formats over glass reusables. Hyderabad and Bangalore biotech clusters import surface-treated biochemical dishes for stem cell research workflows.
Switzerland
Swissmedic device regulations and REACH-aligned chemical restrictions concentrate demand for polypropylene formulation alternatives. Basel pharmaceutical headquarters specify GMP-compliant sterile consumables with full material traceability. The country's precision manufacturing heritage supports niche suppliers serving cell therapy manufacturing quality standards.
Petri Dishes Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Thermo Fisher Scientific and Merck KGaA leverage life science portfolio breadth to bundle petri dishes within integrated cell culture platforms. Three archetypes dominate: integrated resin-to-dish manufacturers controlling cost curves, direct-channel specialists serving hospital laboratories, and workflow bundlers attaching consumables to automated platforms. Competitive moves center on backward integration into polystyrene resin supply and disintermediation of traditional distributor networks through e-procurement platforms.
Within the integrated manufacturing tier, Greiner AG exemplifies captive resin compounding paired with finished dish production. SARSTEDT AG occupies a position as a German GmbH-structured direct-channel anchor for Central European hospital and research laboratory procurement. Thermo Fisher Scientific represents the diversified conglomerate archetype, embedding disposable consumables within broader cell culture instrumentation ecosystems.
| Leading Market Players |
|---|
| Greiner AG |
| SARSTEDT AG & Co. KG |
| Thermo Fisher Scientific Inc. |
| TPP Techno Plastic Products AG |
| BD |
| Corning Incorporated |
| Avantor, Inc. |
| CELLTREAT Scientific Products |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap manufacturers in Germany and Austria anchor pricing discipline through captive polystyrene resin compounding and finished-dish production, compressing margin capture for distributors lacking backward integration while EU MDR sterilization mandates lock pharmaceutical buyers into multi-year contracts at premium tiers.
Pricing Analysis
Margin tightening in standard disposable tiers reflects polystyrene monomer volatility transmitted directly from crude-derived styrene feedstock fluctuations. Three-tier pricing structure across premium biochemical, standard sterile, and economy educational levels separates ISO 11137-validated GMP formats from bulk educational procurement. Cost-down pressure on mid-tier distributors accelerates because Greiner AG and SARSTEDT AG control captive resin supply. Educational institutions in India and China represent the most price-sensitive segment, while pharmaceutical companies deploying CAR-T manufacturing absorb premium biochemical pricing without elasticity.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical buyers mandate gamma irradiation qualification at multiple contract facilities, yet capacity concentrates at three European locations. Manufacturing clusters in Germany, Austria, and Switzerland feed Central European pharmaceutical demand, drawing from polystyrene resin compounders in the Rhine-Ruhr industrial corridor. Single-source sterilization dependency creates bottleneck risk during peak campaign periods. Distribution runs through direct hospital and research laboratory channels in Germany, with Nordic buying groups disintermediating traditional distributor networks via integrated marketplace platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Petri Dishes Market sits in a materials-transition phase as REACH plasticizer restrictions displace legacy polystyrene formulations toward polypropylene and cyclic olefin copolymer alternatives with comparable optical clarity.
For Market Incumbents: Lock in multi-year sterilization validation contracts with ISO 11137-compliant facilities before gamma irradiation capacity bottlenecks intensify during peak pharmaceutical campaign periods. Deepen backward integration into medical-grade propylene resin supply as ECHA substance evaluation deadlines accelerate substitution investments. Channel control through direct e-procurement platforms represents the critical lever for defending margin position against distributor disintermediation. For New Entrants and Emerging Players: Launch via direct-to-laboratory marketplace platforms targeting Nordic and Benelux research hospital clusters where procurement centralization has advanced furthest and traditional distributor markups remain vulnerable. Surface-treated biochemical formats for stem cell propagation workflows offer the most penetrable white space, as CAR-T manufacturing throughput exceeds supply from incumbent specialists. Position around plasma-activated hydrophilic coating capabilities sourced from Swiss and German polymer chemistry institutes. For Investors and Strategic Acquirers: Distressed-cycle entries favor polypropylene formulation specialists with pilot line capacity in Germany and REACH-compliant material traceability systems. Long-term viability hinges on capturing share during the polystyrene-to-polypropylene transition window as regulatory pressure intensifies. Watch ECHA sunset date announcements for plasticizer restrictions as the inflection signal for accelerated substitution investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Resin Supply | Greiner AG's captive polystyrene compounding insulates margin from feedstock volatility affecting non-integrated competitors. |
| Direct E-Procurement Platform Launch | SARSTEDT AG's hospital laboratory channels bypass distributor markups in centralized Nordic buying group contracts. |
| Polypropylene Formulation Pivot | German manufacturers investing in propylene pilot lines anticipate REACH plasticizer restrictions ahead of ECHA deadlines. |
| Gamma Sterilization Capacity Expansion | ISO 11137 validation backlog of 8-14 months creates first-mover advantage for qualified suppliers serving pharmaceutical GMP demand. |
| Modular Ventilation-Lid Bundling | Gas-permeable membrane accessories for anaerobic workflows command premium attach rates in biochemical segment procurement. |
Study Parameters
Multi-period observation of EU MDR implementation timelines, REACH plasticizer evaluation deadlines, and gamma irradiation capacity utilization anchored the trend analysis, supplemented by interviews with laboratory plastics procurement managers at German pharmaceutical companies, sterilization validation specialists at ISO 11137 contract facilities, polymer chemistry R&D directors at Swiss research institutes, and hospital purchasing committee members in Nordic university systems. Secondary validation drew from ECHA substance evaluation databases, FDA 21 CFR Part 820 quality system guidance, customs records of polystyrene resin trade flows, and SEC filings of listed life science conglomerates. Bottom-up demand modeling across end-use segments triangulated against top-down manufacturing capacity assessments.
Segment-weighting approaches distributed value projections across product type, material formulation, end-user sophistication tier, and application regulatory stringency throughout the forecast period. CAGRs derived from sterilization validation throughput constraints, cell therapy manufacturing scale-up trajectories, and educational procurement tender volumes in emerging markets. Industry-specific inputs included gamma irradiation dose-mapping study durations, plasma surface treatment yield rates, and REACH compliance cost pass-through elasticity.
The model assumes a particular technology adoption path toward polypropylene and cyclic olefin copolymer alternatives; alternative pathways for polystyrene plasticizer reformulation would alter the outlook for incumbent resin compounders. Forecasts reflect assumptions about ECHA enforcement intensity, pharmaceutical sterilization standard harmonization, and cell therapy manufacturing localization trends. Deviation in gamma irradiation capacity expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Suture Wire Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market