
 Global Blood Gas and Electrolyte Analyzer Market | 2026-2036
Global Blood Gas and Electrolyte Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Gas and Electrolyte Analyzer Market Insights
CLIA-waived testing capability is rotating toward the center of product strategy across the competitive landscape. Siemens Healthineers leverages its installed base of centralized lab systems to extend into decentralized blood gas testing. Abbott Laboratories anchors its position through handheld analyzer specialization that targets rapid-response clinical environments. Nova Biomedical competes by sustaining domestic manufacturing scale for sensor cartridges that feed its instrument ecosystem.
Blood gas and electrolyte analyzers measure partial pressures of oxygen and carbon dioxide, blood pH, and concentrations of sodium, potassium, calcium, and chloride ions in whole blood samples using electrochemical or optical sensor technologies, primarily to guide ventilation management, acid-base correction, and electrolyte replacement in critically ill patients. Portable analyzers now lead volume shipments as hospitals push testing closer to the patient bedside, while bench-top systems retain margin concentration in high-throughput reference laboratories. Multi-parameter technology is displacing single-analyte instruments as clinicians demand simultaneous blood gas, electrolyte, and metabolite readouts from a single sample draw.
The FDA's CLIA complexity categorization and the EU's In Vitro Diagnostic Regulation shape market access by mandating analytical performance documentation and post-market surveillance that smaller manufacturers struggle to resource. ISO 15189 accreditation requirements in diagnostic laboratories drive replacement cycles toward instruments with automated quality control and calibration verification. Stakeholders must monitor how decentralized testing expansion alters the service and consumable revenue mix against traditional capital equipment models.
Market Dynamics
Point-of-care testing expansion is compressing the traditional centralized laboratory model as hospitals prioritize bedside diagnostic turnaround over batch processing economics. This structural shift redistributes value capture from capital equipment vendors toward consumable-centric business models.
Growth Catalysts
- ICU Capacity Expansion:Government-funded critical care infrastructure programs in China, Germany, and the United States are accelerating instrument procurement cycles.
- CLIA-Waived Test Expansion:The FDA's streamlined complexity categorization for moderate-complexity devices is opening emergency department deployment pathways previously restricted to central labs.
- Sensor Multiplexing:Electrochemical array technologies now enable simultaneous blood gas, electrolyte, and metabolite quantification from single-drop samples.
Market Restraints
- Precious Metal Input Volatility:Platinum and iridium price swings in sensor electrode manufacturing compress margin predictability for cartridge producers.
- EU IVDR Compliance Burden:The In Vitro Diagnostic Regulation's expanded clinical evidence requirements and notified body bottlenecks are extending time-to-market for new analytes by 18-24 months.
- Optical Sensor Substitution:Emerging photonic detection methods for blood gas parameters threaten electrochemical sensor incumbency in high-throughput reference settings.
Strategic Opportunities
- Ambulatory Surgery Center Penetration:Outpatient procedural volume growth in the United States creates demand for compact, non-laboratory-staffed analyzer configurations.
- Integrated Connectivity Mandates:The EU's Electronic Health Record exchange format requirements are creating pull for analyzers with native HL7 FHIR interoperability.
- Veterinary Critical Care:Companion animal ICU specialization in Japan and South Korea represents an underdeveloped vertical with analogous technical specifications to human devices.
Industry Challenges
- Bioanalytical Talent Scarcity:Electrochemical sensor engineering expertise concentrates among a narrow cohort of specialists with blood gas-specific calibration experience.
- Laboratory Information System Integration:Proprietary data formats from legacy hospital IT architectures create middleware development burdens for point-of-care device vendors.
- ISO 15189 Audit Compression:Accelerated accreditation renewal cycles are forcing continuous quality control documentation rather than periodic batch verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Gas and Electrolyte Analyzer Market |
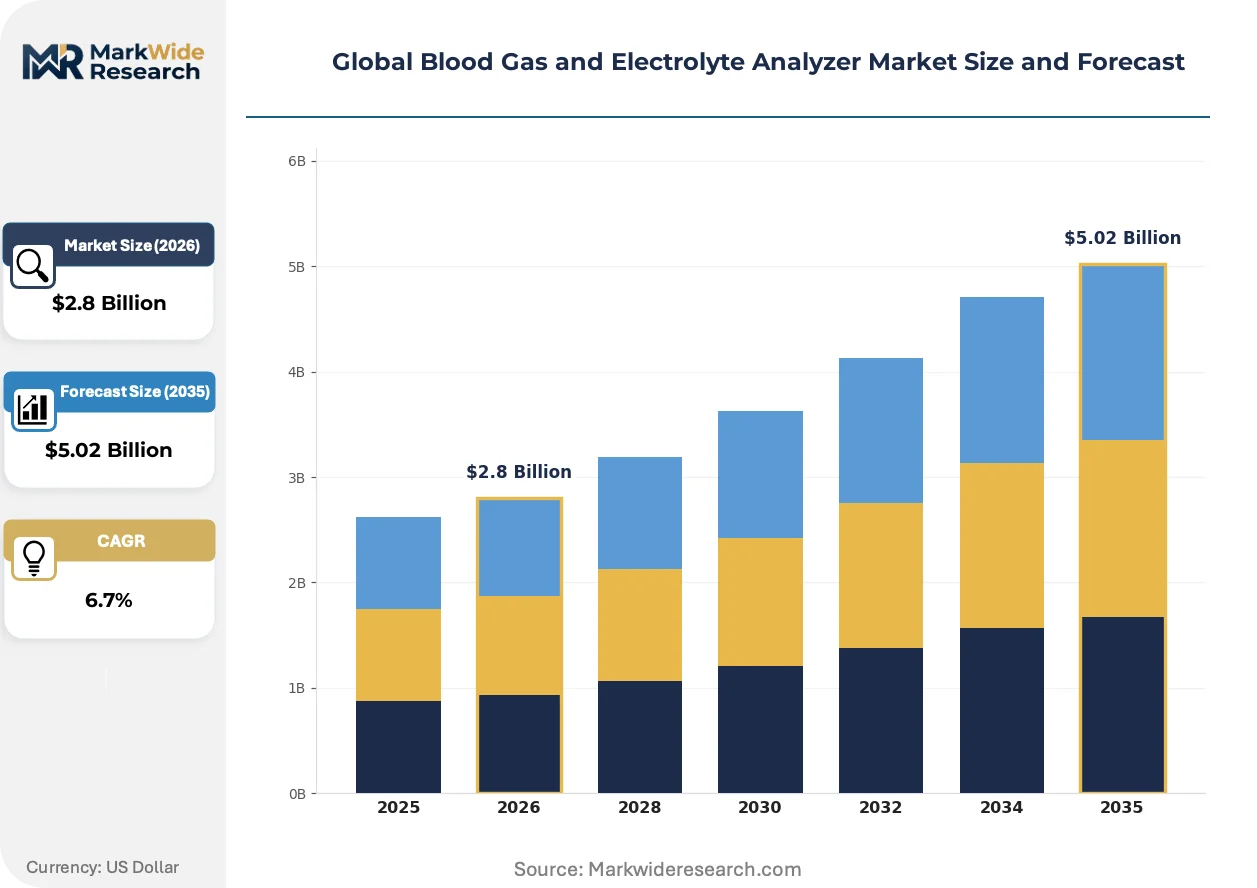
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Bench-top Analyzers, Handheld Analyzers, Continuous Monitor Systems Application: Critical Care, Emergency Medicine, Neonatology, Cardiology Technology: Optical Sensors, Electrochemical Sensors, Ion-selective Electrodes, Multi-parameter Technology End User: Hospitals, Diagnostic Laboratories, Research Centers, Urgent Care Facilities |
| Companies Covered | Siemens Healthineers, Roche Diagnostics, Abbott Laboratories, Radiometer Medical, Medica Corporation, Instrumentation Laboratory, Nova Biomedical, OPTI Medical Systems, EDAN Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Gas and Electrolyte Analyzer Market Trends and Innovations
Sensor fusion architectures and wireless connectivity protocols are redefining how diagnostic data flows from patient to clinical decision support. These technical currents are compressing the gap between sample acquisition and therapeutic intervention.
Microfabricated electrochemical sensor arrays are miniaturizing blood gas analysis from bench-top footprints to handheld devices without sacrificing analytical precision. Emergency departments in the United States and Germany are adopting these portable configurations for rapid respiratory assessment. The technology is miniaturizing the physical and economic boundaries between central laboratory and bedside testing, enabling decentralized revenue models.
The EU's In Vitro Diagnostic Regulation now mandates post-market performance monitoring and unique device identification traceability across the product lifecycle. This regulatory architecture elevates documentation burdens for manufacturers but creates competitive moats against lower-resourced entrants. Small-to-mid-sized analyzer producers are responding by consolidating quality management functions and outsourcing notified body interactions.
Hospital procurement committees are unbundling instrument capital costs from per-test consumable commitments, favoring reagent rental structures with minimum volume guarantees. This financing shift disrupts traditional distributor relationships and compresses upfront revenue recognition for manufacturers. The transformation is most visible in German and Chinese hospital systems where public procurement rules favor operational expenditure classification over capital budget allocation.
Global Blood Gas and Electrolyte Analyzer Market Segmentation
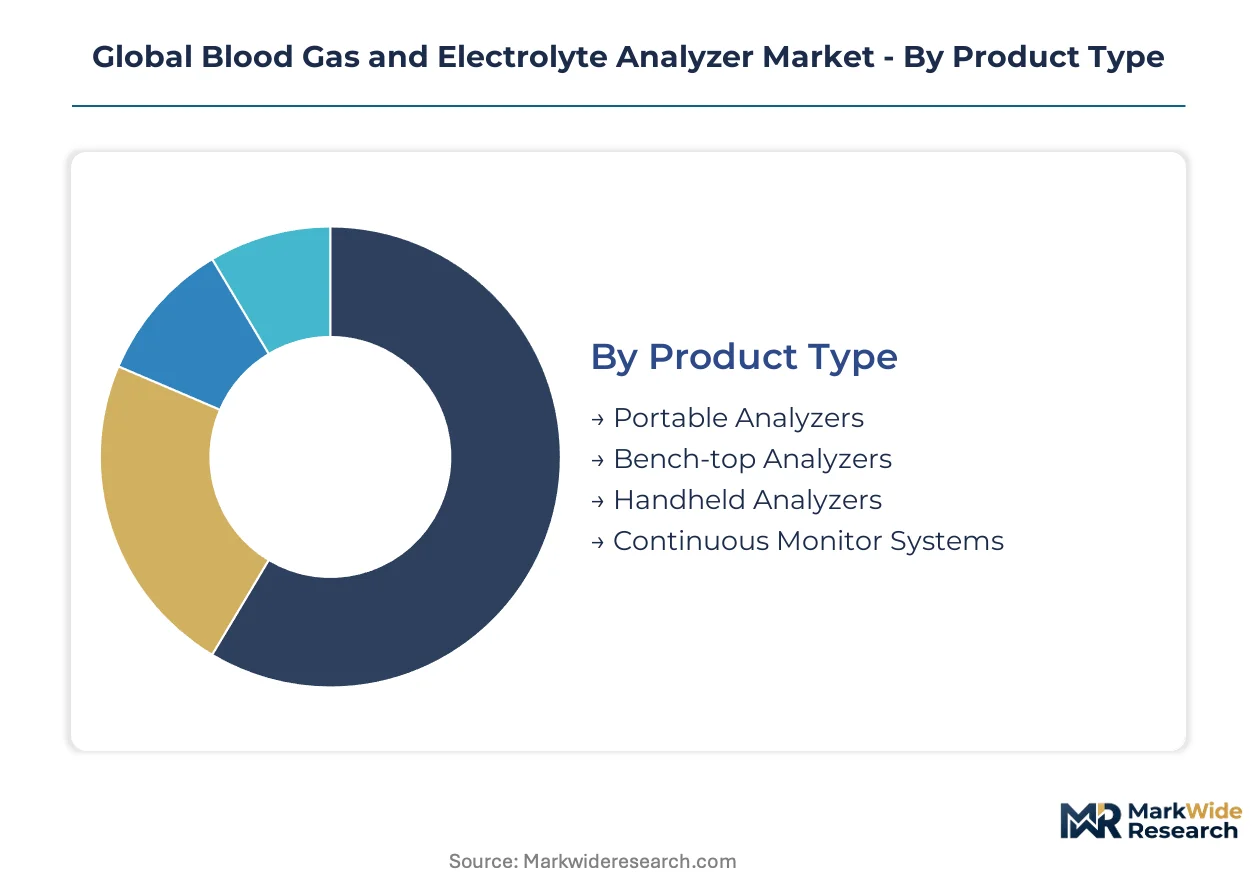
Segmentation in blood gas and electrolyte analyzers reveals divergent technology-commercialization pathways. Product form factors, clinical applications, sensor technologies, and end-user settings each command distinct procurement criteria, regulatory pathways, and margin structures that reshape competitive positioning across the value chain.
Product Type:
Portable and handheld configurations dominate domestic hospital procurement in the United States and Germany, while bench-top systems sustain export-led demand from centralized reference laboratories in China.
- Portable Analyzers:These mid-size units balance throughput capacity with mobility, typically housing electrochemical sensor arrays for simultaneous blood gas and electrolyte quantification. United States emergency departments are consolidating purchasing around these units to support bedside respiratory management. CLIA-waived certification requirements are compressing development timelines for manufacturers targeting this segment.
- Bench-top Analyzers:High-throughput instruments with automated sample handling and integrated quality control systems serve centralized laboratory workflows. German hospital systems favor these configurations for intensive care unit satellite labs where batch processing economics persist against point-of-care decentralization. The EU IVDR's analytical performance documentation mandates disproportionately burden this segment's replacement cycles.
- Handheld Analyzers:Single-patient-use devices with disposable cartridge interfaces enable non-laboratory personnel to execute rapid blood gas assessments. Chinese county-level hospitals are expanding procurement of these units under government-funded critical care infrastructure programs.
- Continuous Monitor Systems:Intravascular or transcutaneous sensors providing real-time blood gas trending in surgical and intensive care settings. Adoption concentrates in Japanese and South Korean tertiary cardiac centers with established perfusionist staffing models.
Bench-top analyzers command the established base. The steepest expansion runs through handheld analyzers.
Application:
Cost tier differentiation separates premium multi-parameter systems for cardiac surgery from standard configurations deployed in general emergency medicine.
- Critical Care:Multi-parameter monitoring of acid-base status, oxygenation, and electrolyte balance guides mechanical ventilation and renal replacement therapy in intensive care units. United States health systems are prioritizing analyzer placement in medical ICU expansion projects funded by federal critical care infrastructure allocations.
- Emergency Medicine:Rapid turnaround requirements for trauma and respiratory distress assessment drive demand for CLIA-waived portable devices. German emergency departments are standardizing around handheld units to reduce central laboratory turnaround times for arterial blood gas sampling.
- Neonatology:Micro-volume sample requirements and specialized reference ranges for premature infants necessitate dedicated analyzer configurations with modified sensor calibration curves. Chinese maternal-child health hospitals are expanding procurement under national neonatal intensive care network development initiatives.
- Cardiology:Continuous or frequent arterial blood gas monitoring during cardiac catheterization, bypass surgery, and post-operative recovery. Japanese cardiovascular centers maintain concentrated demand for high-precision bench-top systems with specialized cardiac output calculation modules.
Critical care applications anchor installed base concentration. Emergency medicine is gaining share fastest as point-of-care protocols expand.
Technology:
Supply concentration in electrochemical sensor manufacturing creates margin pressure, while optical sensor development is accelerating through diversified photonics supplier networks.
- Optical Sensors:Photometric or fluorescence-based detection of blood gas parameters and electrolyte concentrations, typically employing optode membranes or luminescent dyes. Research centers in Switzerland and the Netherlands are piloting these systems for non-invasive transcutaneous monitoring applications.
- Electrochemical Sensors:Amperometric and potentiometric measurement using platinum, iridium, and silver-silver chloride electrode assemblies. This mature technology dominates hospital procurement due to established analytical performance documentation and CLIA categorization precedent.
- Ion-selective Electrodes:Specialized membrane-based potentiometric sensors for sodium, potassium, calcium, and chloride quantification with reduced interference from protein and lipid matrices. German diagnostic laboratories favor these for high-volume electrolyte panels in pre-analytical automation lines.
- Multi-parameter Technology:Integrated sensor arrays combining blood gas, electrolyte, and metabolite measurement in single-sample, single-cartridge workflows. Chinese manufacturers are investing in domestic multi-parameter platform development to reduce import dependence for critical care diagnostics.
Electrochemical sensors command the established base. Multi-parameter technology is climbing the fastest as cartridge integration reduces sample volume requirements.
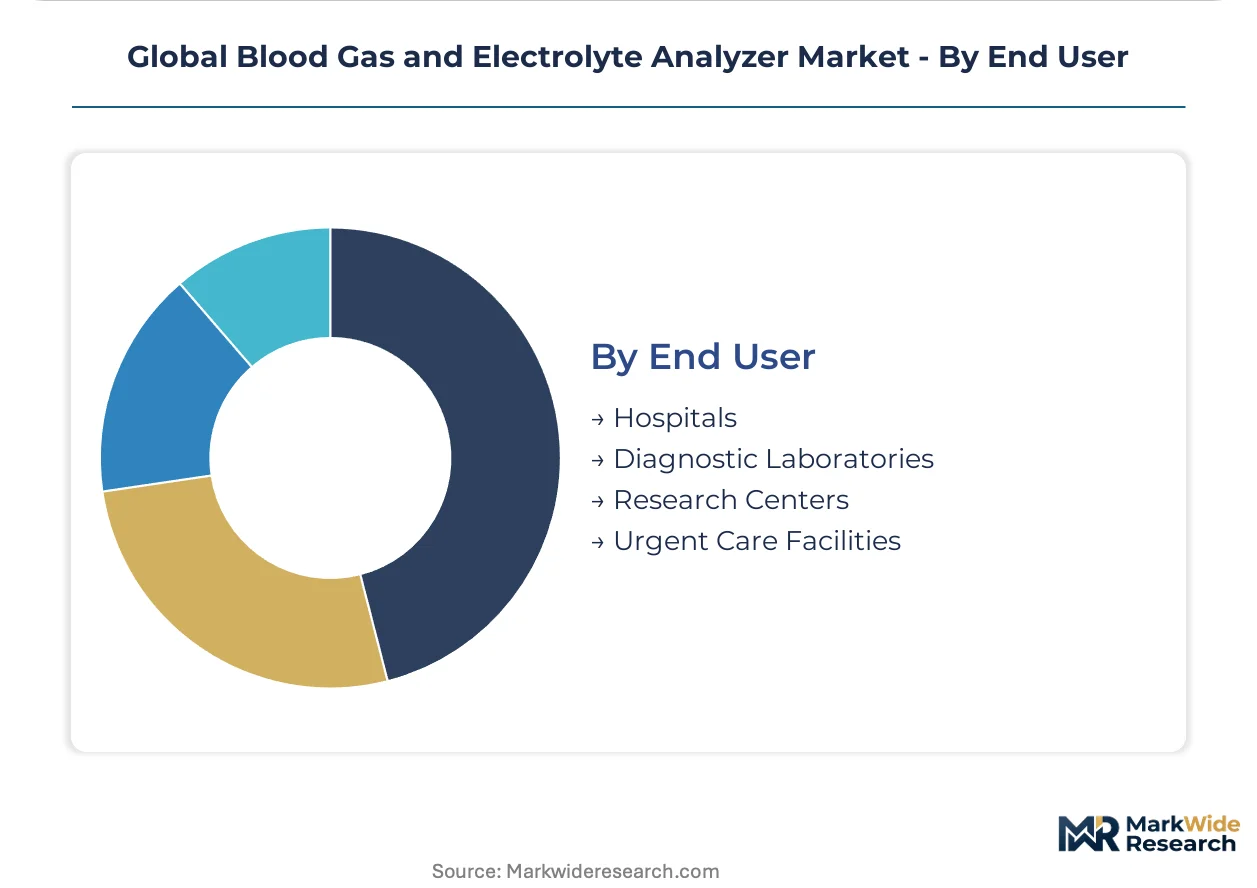
End User:
Customer type stratification separates capital-intensive hospital procurement committees from reagent-rental-focused diagnostic laboratory chains.
- Hospitals:Integrated health systems with mixed centralized and decentralized testing architectures, purchasing across portable, bench-top, and handheld configurations. United States hospital procurement is shifting toward operational expenditure models with per-test consumable commitments rather than upfront capital allocation.
- Diagnostic Laboratories:High-throughput reference facilities and regional laboratory networks prioritizing batch processing efficiency and automated quality control. German and Chinese public laboratory systems are driving demand for bench-top analyzers with native laboratory information system interoperability.
- Research Centers:Academic medical centers and contract research organizations requiring specialized analytical performance for clinical trial protocols and method development. Swiss and Australian research institutes maintain concentrated demand for research-use-only configurations with expanded analyte menus.
- Urgent Care Facilities:Freestanding emergency and ambulatory surgery centers with limited laboratory staffing, prioritizing CLIA-waived simplicity and minimal maintenance requirements. United States urgent care chain expansion is accelerating handheld analyzer placement in non-hospital settings.
Hospitals command the established base. Urgent care facilities represent the steepest expansion trajectory as outpatient procedural volume shifts from inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical sensor manufacturing concentrates in Germany and the United States, while Chinese assemblers dominate handheld analyzer production for domestic hospital procurement. Regulatory divergence between FDA CLIA pathways and EU IVDR compliance timelines fragments go-to-market strategies across major demand centers.
United States
Emergency department point-of-care expansion and federal ICU infrastructure funding drive analyzer placement in tertiary hospitals. FDA CLIA-waived complexity categorization accelerates deployment pathways for moderate-complexity devices in non-laboratory settings. Boston and Minneapolis medical device clusters house electrochemical sensor engineering talent pools that supply cartridge calibration expertise.
Germany
Public hospital procurement rules favor operational expenditure models with per-test consumable commitments over capital budget allocation. EU IVDR analytical performance documentation mandates extend replacement cycles toward instruments with automated quality control. Baden-Württemberg diagnostic laboratory networks anchor demand for bench-top systems with native LIS interoperability.
China
Government-funded critical care infrastructure programs accelerate instrument procurement in county-level hospitals. NMPA streamlined registration pathways for domestically manufactured multi-parameter platforms reduce import dependence. Yangtze River Delta medical device assemblers scale handheld analyzer production for provincial hospital network tenders.
Japan
Companion animal ICU specialization creates demand for veterinary-configured analyzers with analogous specifications to human devices. PMDA post-market surveillance requirements elevate documentation burdens for imported cartridge systems. Tokyo and Osaka tertiary cardiac centers sustain concentrated demand for continuous monitor systems with perfusionist staffing models.
Switzerland
Research-use-only configurations with expanded analyte menus serve academic medical centers and contract research organizations. Swissmedic clinical evidence requirements for novel sensor technologies create competitive moats against lower-resourced entrants. Basel and Zurich biotech clusters pilot optical sensor systems for non-invasive transcutaneous monitoring applications.
Global Blood Gas and Electrolyte Analyzer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the blood gas and electrolyte analyzer market. Siemens Healthineers, Roche Diagnostics, and Abbott Laboratories anchor the premium tier through centralized lab system integration and handheld specialization respectively. Mid-scale domestic manufacturers compete on cartridge production economics and regional service proximity. Consolidation pressure intensifies through strategic partnerships for sensor multiplexing development and geographic expansion into ambulatory surgery center channels.
Among diversified health technology conglomerates, Siemens Healthineers and Roche Diagnostics occupy positions spanning centralized laboratory and decentralized point-of-care configurations. Abbott Laboratories exemplifies handheld analyzer specialization targeting rapid-response clinical environments. Nova Biomedical represents the domestic manufacturing scale archetype, sustaining sensor cartridge production that feeds instrument ecosystem lock-in. These three anchors illustrate how competitive positioning diverges between system integration breadth and consumable-centric vertical focus.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Roche Diagnostics |
| Abbott Laboratories |
| Radiometer Medical |
| Medica Corporation |
| Instrumentation Laboratory |
| Nova Biomedical |
| OPTI Medical Systems |
| EDAN Instruments |
| Others |
Pricing and Supply Chain Analysis
Optical sensor substitution for electrochemical platinum-iridium electrodes is simultaneously redrawing manufacturing geography and compressing margin structures across portable analyzer tiers. This materials transition weakens incumbent sensor cartridge pricing power while opening assembly cost advantages for Chinese and South Korean producers.
Pricing Analysis
FDA CLIA complexity categorization dictates the pricing tier structure across hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-waived handheld units from moderate-complexity portable systems and high-throughput bench-top configurations. Cost compression in economy handheld tiers is intensifying because domestic Chinese manufacturers are scaling multi-parameter cartridge production under NMPA streamlined pathways. Emergency medicine departments exhibit highest price sensitivity due to volume procurement mandates, while cardiac surgery suites maintain lowest sensitivity given procedure-critical performance requirements.
Supply Chain Analysis
Germany and the United States anchor electrochemical sensor electrode manufacturing, while China dominates handheld analyzer final assembly. Platinum and iridium supply draws from South African and Russian mining operations, creating raw material concentration risk. Single-source vulnerability in specialty membrane coatings for ion-selective electrodes threatens cartridge production continuity. Distribution runs through hospital procurement committees and diagnostic laboratory GPO contracts rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability mandates from the EU's Electronic Health Record exchange format are transforming analyzer purchasing into platform-economics decisions where data integration capabilities override standalone instrument specifications.
For Market Incumbents: Consolidate sensor cartridge production scale through backward integration into platinum-iridium electrode manufacturing or captive membrane coating capacity. Optical sensor entrants threaten electrochemical incumbency in high-throughput reference laboratories; defend through CLIA-waived certification depth and native HL7 FHIR connectivity investment. For New Entrants and Emerging Players: Differentiate on veterinary critical care configurations for Japanese and South Korean companion animal ICU networks, where human-device technical specifications apply without established incumbent lock-in. Ambulatory surgery centers in the United States represent the most penetrable end-user segment due to CLIA-waived simplicity requirements and minimal laboratory staffing. For Investors and Strategic Acquirers: EU IVDR post-market surveillance requirements reshape the acquisition landscape toward targets with documented analytical performance portfolios and notified body relationship infrastructure. Five-to-ten year viability hinges on consumable-centric revenue models displacing capital equipment dependence. Signal to monitor: German and Chinese hospital procurement shifts from capital allocation to operational expenditure classification.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-parameter Cartridge Development | Chinese manufacturers reduce import dependence under NMPA domestic platform incentives. |
| CLIA-Waived Certification Investment | FDA streamlined pathways accelerate emergency department deployment against central lab models. |
| HL7 FHIR Interoperability Integration | EU Electronic Health Record mandates create competitive moat for connected analyzer architectures. |
| Veterinary Configuration Launch | Japanese companion animal ICU specialization opens adjacent vertical with analogous specifications. |
| Reagent Rental Structure Adoption | German operational expenditure procurement rules favor per-test consumable commitment models. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at IVD manufacturers and refined through secondary validation against FDA 510(k) filings, EU IVDR technical documentation, hospital procurement databases, and CMS Medicare laboratory fee schedules. Bottom-up instrument placement estimates triangulated with top-down critical care infrastructure spending analysis.
Variance decomposition across product type, application, technology, end-user setting, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Forecast inputs incorporated ICU capacity expansion program announcements from health ministries and CLIA-waived test menu expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of continued point-of-care testing expansion and stable precious metal input costs; material deviation in optical sensor substitution velocity or EU IVDR notified body capacity would warrant model refresh. Recalibration cycles align with material shifts in regulatory complexity categorization and hospital procurement expenditure classification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Platelet Aggregation Devices Market