
 Disposable Hospital Supplies Market | 2026-2036
Disposable Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Hospital Supplies Market Analysis
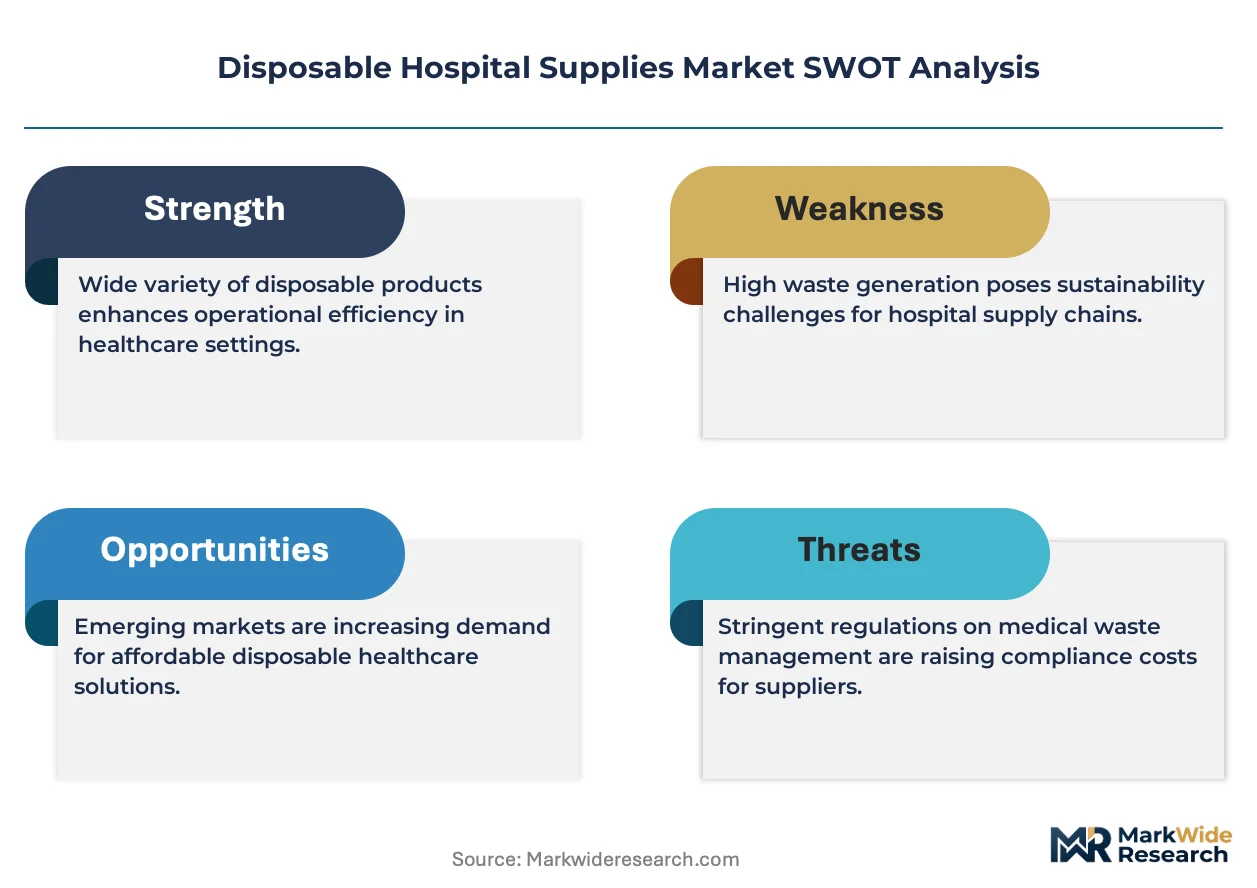
Single-use sterilization assurance tiers are reorganizing procurement criteria across acute care networks. Cardinal Health leverages captive distribution networks to sustain contract penetration with integrated delivery networks. Medline Industries anchors private-label sourcing strategies that compete on unit economics against branded alternatives. 3M Company differentiates through proprietary nonwoven lamination technologies that command premium positioning in orthopedic and cardiac procedure kits.
Disposable hospital supplies encompass single-use medical products manufactured from polyethylene films, spunbond-meltblown-spunbond nonwoven composites, natural rubber latex, or kraft paper substrates, engineered to maintain sterile fields and prevent cross-contamination during diagnostic, therapeutic, or surgical interventions. Surgical drapes and gowns manufactured from multilayer nonwoven fabrics represent the dominant product category by revenue, reflecting their irreplaceable role in maintaining aseptic conditions during invasive procedures. Infusion therapy applications are expanding fastest among clinical use cases, driven by the shift toward outpatient parenteral administration and home-based chemotherapy protocols. Long-term care facilities constitute a margin-accretive end-user segment where lower patient acuity permits simplified product specifications and higher volume throughput per bed.
The FDA enforces 510(k) premarket notification and quality system regulation compliance for all sterile disposable devices, while ISO 13485 certification has become a baseline qualifier for supplier qualification by multinational hospital chains. The EPA regulates ethylene oxide sterilization emissions, pressuring manufacturers toward alternative terminal sterilization modalities such as gamma irradiation or vaporized hydrogen peroxide. Stakeholders must monitor evolving state-level extended producer responsibility mandates for medical plastic waste, as these frameworks will reshape material selection and end-of-life cost allocation across supply contracts.
Market Dynamics
FDA sterilization validation updates are compressing product development timelines while elevating barrier performance requirements for domestic manufacturers, forcing supply base consolidation around validated production platforms.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volume is accelerating single-use drape and gown consumption across freestanding surgical facilities in the United States.
- India's hospital infrastructure programs:Government capital allocation toward public health facilities is driving procurement volume for disposable gloves and surgical kits.
- Medical tourism concentration:Destination hospitals in Thailand and Malaysia are standardizing on premium infection control disposables to maintain international accreditation.
Market Restraints
- Ethylene oxide supply constraints:EPA emission restrictions on EtO sterilization are limiting terminal sterilization capacity and extending production lead times.
- Natural rubber latex price volatility:Plantation yield fluctuations in Southeast Asia are compressing margins for glove manufacturers dependent on raw latex supply.
- Polypropylene feedstock concentration:Spunbond-meltblown-spunbond nonwoven production clusters in Saudi Arabia and China create geographic supply risk for surgical fabric substrates.
Strategic Opportunities
- Home infusion therapy protocols:Parenteral administration outside acute settings is expanding addressable demand for sterile IV start kits and closed-system transfer devices.
- Extended producer responsibility mandates:State-level medical plastic waste frameworks in California and New York are creating first-mover advantage for biodegradable substrate developers.
- Gamma irradiation infrastructure:Terminal sterilization modality shift away from EtO is enabling regional service hub development near manufacturing clusters.
Industry Challenges
- 510(k) sterilization validation timelines:FDA documentation requirements for novel barrier materials are extending regulatory approval cycles by twelve to eighteen months.
- ISO 13485 certification scarcity:Qualified quality management auditors are concentrated in Western Europe, creating bottlenecks for Asian manufacturer qualification.
- Legacy ERP integration:Hospital procurement system modernization is delaying real-time inventory visibility for disposable supply vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Hospital Supplies Market |
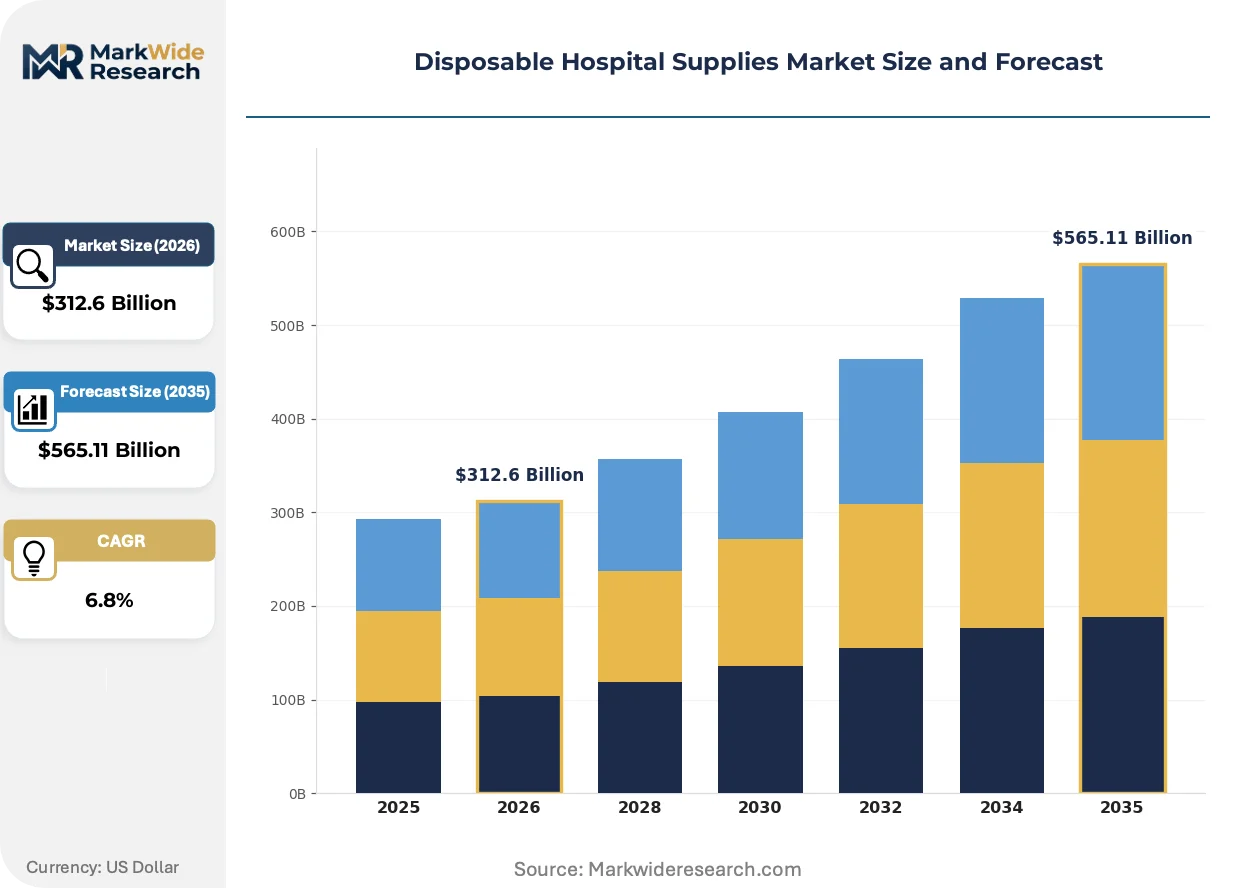
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Drapes, Gloves, Masks, Gowns Application: Emergency Care, Surgical Procedures, Infusion Therapy, Patient Examination End User: Hospitals, Clinics, Diagnostic Laboratories, Long-term Care Facilities Material: Polyethylene, Nonwoven Fabrics, Paper, Latex |
| Companies Covered | Johnson & Johnson, Cardinal Health, Medtronic, 3M Company, Medline Industries, BD (Becton Dickinson), B. Braun, Terumo Corporation, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Hospital Supplies Market Emerging Trajectories
Material science advances and sterilization modality transitions are restructuring product specifications and manufacturing footprints across the disposable supply base.
Biodegradable polylactic acid nonwoven laminates are supplanting petroleum-based spunbond fabrics in surgical drape applications. European orthopedic centers are piloting these substrates for arthroscopy kits. The shift is compressing reliance on fossil-derived feedstocks while requiring new composting infrastructure partnerships.
REACH restrictions on persistent organic pollutants are accelerating fluorinated polymer phase-out in liquid barrier coatings. German and French surgical textile manufacturers are reformulating multilayer gowns with silicone-based alternatives. Cardiac procedure kits face the steepest reformulation burden due to stringent blood strike-through requirements.
Consolidated procurement through integrated delivery networks is displacing individual hospital purchasing autonomy. Group purchasing organizations are mandating standardized product specifications across member facilities. This concentration is most pronounced in Texas and Florida where health system mergers have reduced independent acute care buyers by half.
Disposable Hospital Supplies Market Segmentation
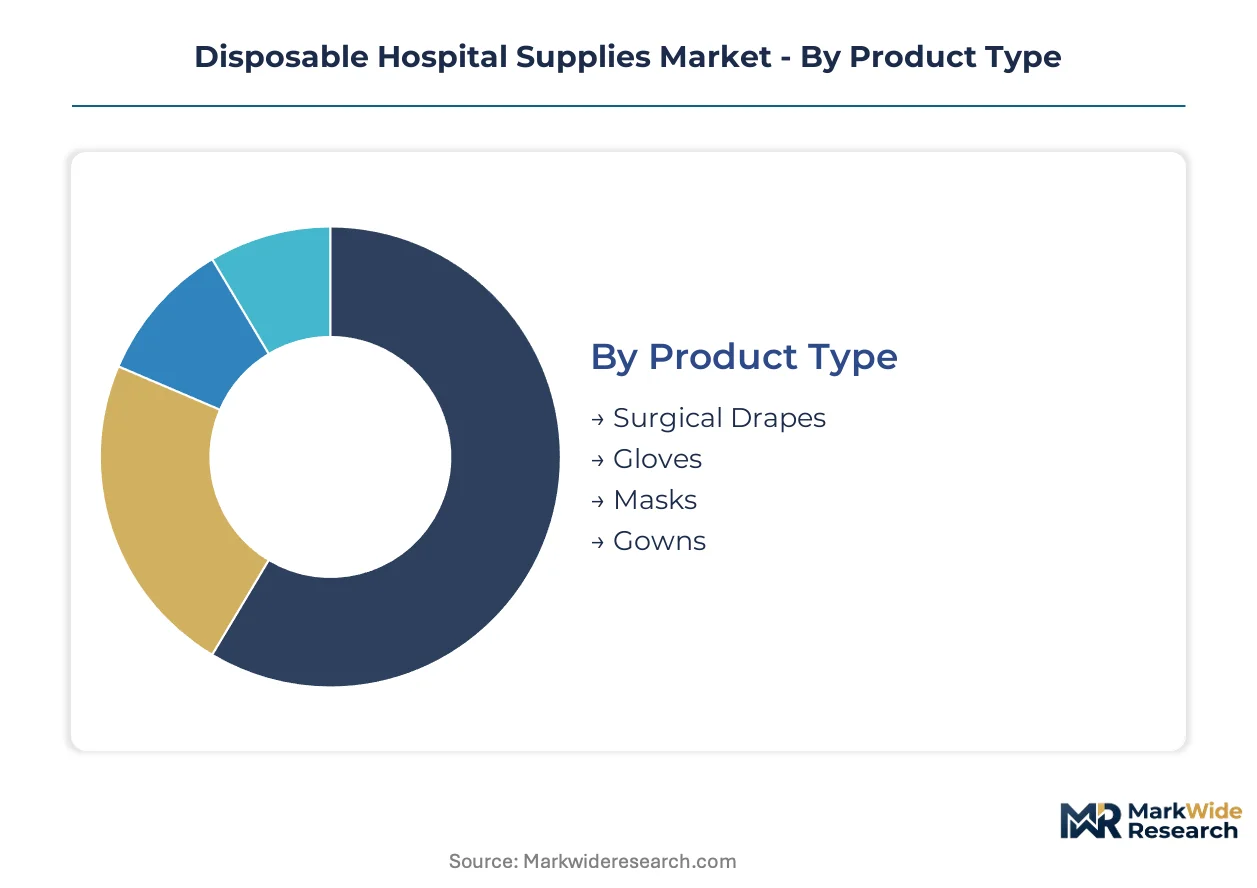
Disposable hospital supplies serve distinct clinical workflows with divergent barrier performance requirements and procurement economics. Segmentation reveals where FDA sterilization validation creates competitive moats versus commodity price competition.
Product Type:
FDA 510(k) clearance tiers separate segments by barrier validation burden and reimbursement linkage.
- Surgical Drapes:Multilayer nonwoven laminates with reinforced critical zones dominate orthopedic and cardiac procedure kits. India's government hospital infrastructure programs are accelerating volume procurement of sterile field maintenance products.
- Gloves:Natural rubber latex and nitrile formulations face divergent raw material risk profiles. Thailand's medical tourism destination hospitals are standardizing on premium examination gloves to maintain Joint Commission accreditation.
- Masks:ASTM F2100-rated bacterial filtration efficiency distinguishes clinical from industrial use.
- Gowns:AAMI Level 3-4 liquid barrier certification commands pricing premiums in trauma centers.
Surgical drapes handle the majority of throughput; gloves are expanding most quickly on share.
Application:
Volume concentration follows patient acuity and reimbursement setting.
- Surgical Procedures:Invasive interventions require comprehensive sterile field maintenance with multilayer drape systems and impermeable gowns. Ambulatory surgical centers in the United States are displacing hospital-based volume for low-acuity cases.
- Infusion Therapy:Parenteral administration outside acute settings demands sterile IV start kits and closed-system transfer devices. Home-based chemotherapy protocols are expanding addressable demand beyond traditional hospital purchasing.
- Emergency Care:Trauma activation protocols prioritize rapid donning and fluid strike-through resistance.
- Patient Examination:Lower barrier requirements permit simplified specifications and higher volume throughput.
Surgical procedures anchor revenue concentration; infusion therapy is gaining share fastest.
End User:
Procurement sophistication and contract structure vary sharply by care setting.
- Hospitals:Integrated delivery networks consolidate purchasing through group purchasing organizations with standardized specifications. Texas and Florida health system mergers have reduced independent acute care buyers substantially.
- Long-term Care Facilities:Lower patient acuity permits simplified product specifications and higher volume throughput per bed. This segment delivers margin-accretive economics for suppliers with efficient distribution.
- Clinics:Federally qualified health centers operate under distinct 340B drug pricing program procurement rules.
- Diagnostic Laboratories:Specimen handling protocols drive specialized glove and drape requirements.
Hospitals handle the majority of throughput; long-term care is climbing the fastest on share.
Material:
Feedstock geography and sterilization compatibility determine supply security.
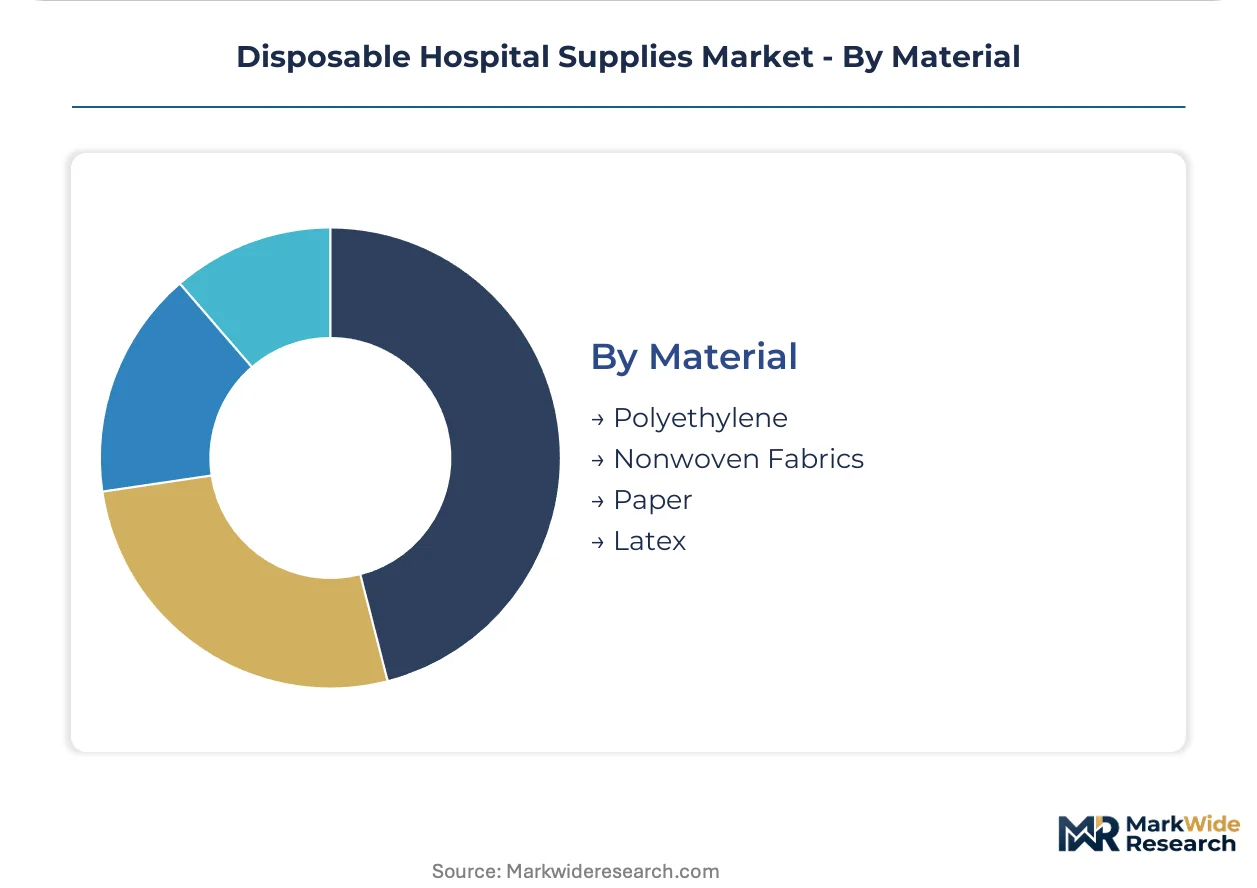
- Nonwoven Fabrics:Spunbond-meltblown-spunbond composites dominate surgical textile applications. Production clusters in Saudi Arabia and China create geographic concentration risk for surgical fabric substrates.
- Polyethylene:Film-based products face extended producer responsibility mandates in California and New York that favor recyclable or biodegradable alternatives.
- Latex:Plantation yield fluctuations in Southeast Asia compress margins for glove manufacturers dependent on raw latex supply.
- Paper:Kraft-based sterilization wraps compete on cost in lower-acuity settings.
Nonwoven fabrics handle the majority of throughput; polyethylene faces the steepest regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spunbond-meltblown-spunbond nonwoven production clusters in Saudi Arabia and China concentrate raw material supply for surgical fabric substrates, while terminal sterilization capacity constraints in the United States and ethylene oxide emission restrictions in Europe are redrawing manufacturing footprints across major demand centers.
United States
Ambulatory surgical centers in Texas and Florida are displacing hospital-based procedure volume and accelerating consumption of single-use drapes and gowns. FDA's updated 510(k) sterilization validation requirements are elevating barrier performance standards for domestic manufacturers. The Midwest manufacturing corridor around Chicago anchors contract sterilization hub development as gamma irradiation capacity expands to offset ethylene oxide constraints.
Germany
REACH restrictions on persistent organic pollutants are accelerating fluorinated polymer phase-out in liquid barrier coatings for surgical textiles. German orthopedic centers are piloting biodegradable polylactic acid nonwoven laminates for arthroscopy kits. The Baden-Württemberg industrial cluster houses reformulation specialists developing silicone-based alternatives for cardiac procedure gowns.
India
Government hospital infrastructure programs and medical tourism are accelerating volume uptake of disposable surgical drapes and gloves. CDSCO's alignment with international quality system regulations is streamlining import pathways for multinational suppliers. Tamil Nadu's medical device manufacturing zone near Chennai is attracting contract production investments for sterile field maintenance products.
China
Domestic production of spunbond-meltblown-spunbond composites supplies regional surgical textile demand while NMPA quality system enforcement elevates export qualification barriers. Yangtze River Delta manufacturing clusters are integrating gamma irradiation terminals to serve Asia-Pacific sterilization demand. Zhejiang province's nonwoven fabric producers are expanding capacity for multilayer surgical drape laminates.
Thailand
Destination hospitals serving medical tourism are standardizing on premium infection control disposables to maintain Joint Commission International accreditation. Natural rubber latex glove production around Hat Yai faces margin pressure from plantation yield fluctuations across Southeast Asia. Bangkok's private hospital networks are consolidating procurement through regional group purchasing organizations.
Disposable Hospital Supplies Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the disposable hospital supplies sector. The market structure consolidates around integrated health system procurement networks while fragmenting across specialized material suppliers and regional sterilization service providers. Three archetypes dominate: multinational distributors with captive logistics networks, private-label manufacturers competing on unit economics, and proprietary technology developers commanding premium positioning in procedure-specific kits. Competitive dynamics center on backward integration into nonwoven substrate production and geographic expansion of terminal sterilization capacity.
Among diversified health supply conglomerates, Johnson & Johnson and Cardinal Health exemplify scale-driven archetypes with integrated distribution reach. Medline Industries occupies a position within the private-label tier, while 3M Company represents technology-led differentiation through material science capabilities. These three anchors illustrate the strategic divergence between cost-competitive sourcing and premium barrier performance positioning.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Cardinal Health |
| Medtronic |
| 3M Company |
| Medline Industries |
| BD (Becton Dickinson) |
| B. Braun |
| Terumo Corporation |
| Boston Scientific |
| Others |
Supply Flow & Price Mechanics
Spunbond-meltblown-spunbond capacity utilization rates in Zhejiang province and Saudi Arabia's Sadara cluster anchor global price floors for surgical drape substrates. Scale concentration among these nonwoven producers permits selective pricing power during feedstock volatility, while gamma irradiation terminal scarcity in the United States compresses sterilization service margins and forces contract renegotiation.
Pricing Analysis
FDA 510(k) sterilization validation dictates the pricing tier structure across disposable hospital supplies, separating premium barrier-certified products from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects AAMI liquid barrier certification grades, with Level 4 cardiac procedure gowns commanding substantial premiums over Level 1 examination products. Cost compression in nitrile glove segments is intensifying because Southeast Asian latex plantation yield fluctuations destabilize raw material input costs. Long-term care facilities exhibit highest price sensitivity due to simplified product specifications, while integrated delivery networks leverage volume scale for standardized contract terms.
Supply Chain Analysis
Strait of Hormuz transit underwrites polypropylene feedstock security for Saudi Arabian nonwoven producers serving European surgical textile demand. Raw material supply draws from Saudi Arabia, China, and Thailand for spunbond-meltblown-spunbond composites, natural rubber latex, and nitrile butadiene rubber respectively. Single-source vulnerability concentrates in Chinese Zhejiang province for multilayer surgical drape laminates, where NMPA export qualification barriers compound geographic risk. Distribution runs through Cardinal Health and Medline Industries captive logistics networks, with group purchasing organizations consolidating hospital procurement into standardized contract streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable hospital supplies are approaching a platform-economics inflection as integrated delivery networks mandate interoperability between vendor ERP systems and hospital inventory management platforms. This shift rewards suppliers with real-time demand signaling capabilities and penalizes fragmented legacy distribution models.
For Market Incumbents: Fortify barrier technology differentiation through proprietary nonwoven lamination investments, particularly in orthopedic and cardiac procedure kits where 3M Company commands premium positioning. Expand gamma irradiation terminal capacity near Midwest manufacturing corridors to offset ethylene oxide constraints and capture sterilization service revenue streams. Secure ISO 13485 certification depth across Asian contract manufacturing partners before auditor scarcity worsens qualification bottlenecks.
For New Entrants and Emerging Players: Home infusion therapy kit assembly represents an underserved service layer where incumbents lack specialized distribution infrastructure for patient-direct delivery. Target long-term care facilities in Texas and Florida health system merger corridors, where simplified product specifications permit rapid volume penetration without AAMI Level 4 certification burden. Pursue biodegradable polylactic acid substrate partnerships with German orthopedic centers piloting sustainable arthroscopy kits.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterilization modality transition plays, particularly gamma irradiation infrastructure developers and vaporized hydrogen peroxide equipment manufacturers. Long-term viability rests on regulatory alignment with EPA ethylene oxide emission restrictions and FDA 510(k) validation streamlining. Monitor state-level extended producer responsibility mandate passage in California and New York as inflection indicators for biodegradable substrate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma Irradiation Infrastructure Expansion | Midwest sterilization hub development near Chicago captures EtO displacement demand from EPA-regulated facilities. |
| Biodegradable Substrate Partnership | Polylactic acid nonwoven alliances with German orthopedic centers secure REACH-compliant positioning ahead of fluorinated polymer phase-out. |
| Integrated Delivery Network Contract Consolidation | Texas and Florida GPO standardization mandates reward vendors with real-time inventory visibility systems. |
| CDSCO Quality System Alignment | Indian regulatory pathway streamlining enables Tamil Nadu manufacturing zone access for multinational sterile field suppliers. |
| Home Infusion Therapy Distribution Buildout | Patient-direct sterile IV kit delivery networks capture parenteral administration volume shifting outside acute settings. |
Methodological Framework
Cross-validation between hospital procurement database analysis and GPO contract disclosure reviews anchors the qualitative findings in verifiable transaction patterns. Primary interviews with biomedical engineers, GPO contracts managers, sterile processing department heads, and regulatory affairs specialists at FDA-registered manufacturers informed barrier performance requirement evolution. Secondary validation drew from FDA 510(k) clearance databases, EPA ethylene oxide emission compliance filings, CMS Medicare spending data, and ISO 13485 certification registries. Bottom-up demand modeling across procedure volumes and top-down supply capacity assessment triangulated market size estimates.
Sensitivity analysis across feedstock price scenarios and sterilization modality transition timelines tested forecast robustness throughout the projection horizon. Segmentation modeling incorporated product type, application workflow, end-user procurement sophistication, and material substrate chemistry dimensions. CAGRs derived from procedure volume elasticity coefficients and reimbursement setting shifts, with infusion therapy protocol expansion and ambulatory surgical center displacement of hospital-based volume serving as key demand drivers.
Forecasts assume regulatory continuity in FDA 510(k) validation requirements and EPA ethylene oxide emission frameworks; material policy shifts would require re-modeling of sterilization capacity allocation and barrier certification timelines. Practitioners should keep alternative scenarios live as REACH restriction scope expansion and state-level extended producer responsibility mandate implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Safety Needles Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Global Lancets Market
Medical Supplies
US Hospital Consumables Market