
 Double-Fed Wind Turbine Market | 2026-2036
Double-Fed Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Double-Fed Wind Turbine Market Insights
The EU F-Gas Regulation is expanding compliance burdens for cooling systems inside turbine converters, raising capital requirements for new market entrants. Vestas Wind Systems A/S leverages its European service footprint to sustain aftermarket revenue streams. Siemens Gamesa Renewable Energy S.A. anchors its competitive position through dedicated offshore nacelle assembly lines. ABB competes aggressively on converter control software that meets evolving grid code requirements across multiple jurisdictions.
A double-fed wind turbine employs a wound-rotor induction generator connected to the grid through both stator and rotor circuits, with a back-to-back voltage source converter controlling rotor slip power across a speed range typically spanning 30% above and below synchronous speed. This architecture enables variable-speed operation while using a partial-scale power converter rated at roughly 30% of total turbine capacity, reducing converter cost versus full-conversion designs. Onshore installations dominate current deployment volumes, though offshore product types command premium pricing due to salt-corrosion specifications and remote maintenance logistics. Gear-driven technology segments retain cost advantages in mature markets, while direct drive alternatives displace conventional drivetrains in offshore applications where reliability premiums outweigh upfront capital differences.
Germany's KBA certifies transport configurations for oversized nacelle components, while China's GB standards mandate low-voltage ride-through capabilities that shape converter design specifications. The EPA oversees end-of-life blade disposal protocols in the United States, adding operational compliance layers for fleet operators. Stakeholders must monitor evolving grid interconnection standards in target markets before committing to platform generation upgrades.
Market Dynamics
Converter software upgrades under tightening EU network codes are compressing product lifecycles and forcing premature replacement schedules across installed fleets. Northern European offshore developers now specify multi-megawatt units with integrated grid-forming capabilities, reshaping procurement specifications and vendor qualification criteria.
Growth Catalysts
- EU F-Gas Regulation:Cooling system retrofits inside turbine converters are creating aftermarket demand for compliant thermal management solutions.
- China's coastal provinces:Provincial governments in Jiangsu and Guangdong fast-track interconnection approvals for variable-speed installations.
- Grid-forming converter technology:Advanced control algorithms enable synthetic inertia provision, satisfying evolving stability requirements.
Market Restraints
- Rare earth magnet price volatility:Neodymium supply concentration in Chinese processing facilities creates input cost uncertainty for direct-drive alternatives.
- Converter semiconductor shortages:IGBT and SiC module fabrication capacity constraints limit power electronics scaling.
- GB standard compliance costs:China's low-voltage ride-through mandates require redundant crowbar circuits that add capital intensity.
Strategic Opportunities
- Floating offshore platforms:Tension-leg and semi-submersible foundations in deeper waters require compact nacelle designs favoring double-fed architectures.
- Green hydrogen co-location:Electrolyzer-turbine hybrid sites create demand for flexible power control and grid-islanding capabilities.
- India's PLI scheme:Domestic manufacturing incentives for renewable energy components attract converter assembly investments.
Industry Challenges
- Power electronics specialist scarcity:Grid-forming firmware development requires rare combinations of power systems and control theory expertise.
- Blade end-of-life disposal protocols:EPA oversight in the United States adds operational compliance layers and extended producer responsibility costs.
- Legacy drivetrain integration:Retrofitting grid-forming capabilities into existing wound-rotor generators involves complex rotor circuit redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double-Fed Wind Turbine Market |
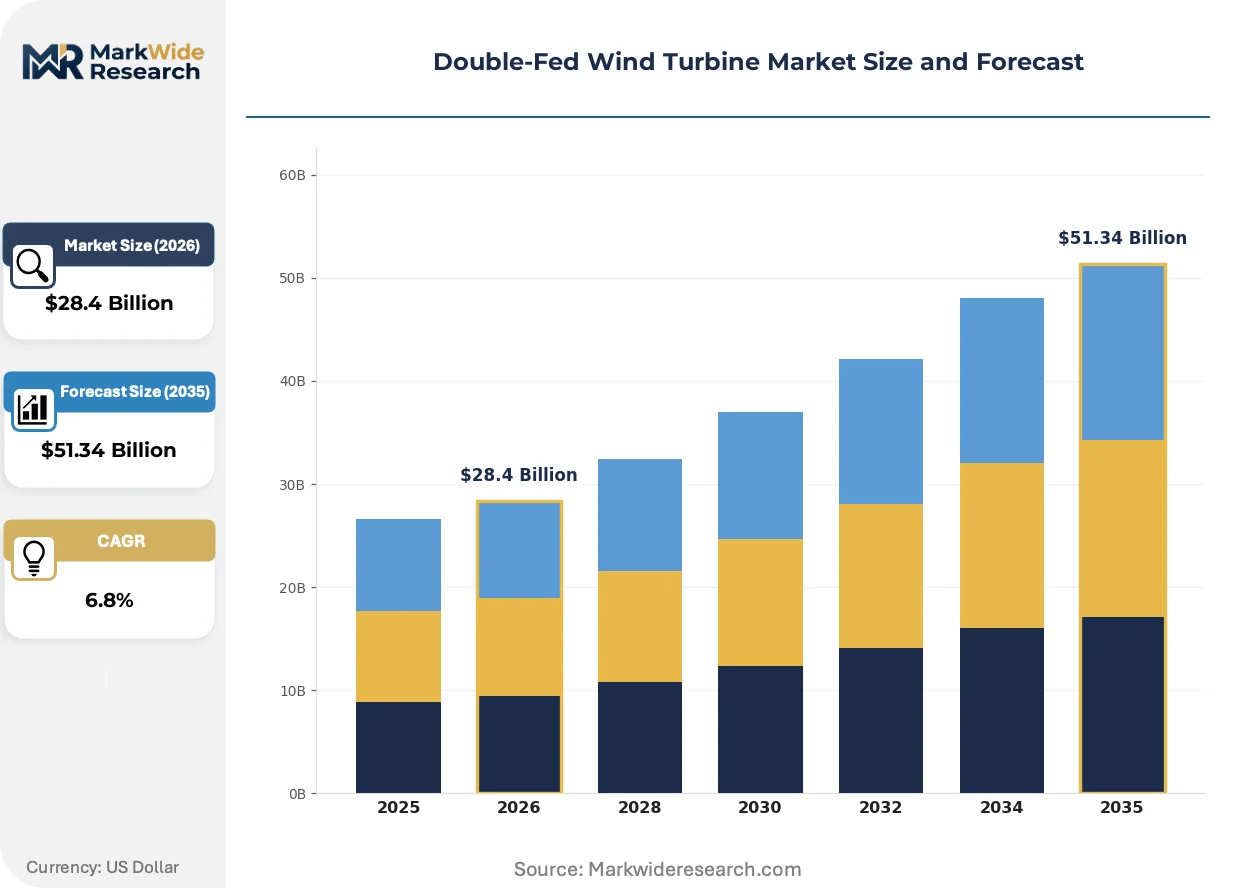
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Independent Power Producers, Renewable Energy Developers, Government Technology: Direct Drive, Gear-Driven, Permanent Magnet, Induction Generator Installation Type: Ground Mounted, Rooftop, Floating, Hybrid |
| Companies Covered | ABB, CRRC Zhuzhou Electric Co., Ltd., XEMC Windpower Co., Ltd., Wolong Electric Group Co., Ltd., Shanghai Electric, Sany Heavy Energy Co., Ltd., VEM Motors, Siemens Gamesa Renewable Energy S.A., Vestas Wind Systems A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double-Fed Wind Turbine Market Trends and Innovations
Modular converter architectures are compressing upgrade timelines and enabling field-swappable power stacks without full nacelle removal. Software-defined control strategies now dominate competitive differentiation as hardware commoditizes.
Silicon carbide power semiconductors are unifying inverter efficiency and thermal performance in next-generation rotor-side converters. Offshore developers in the North Sea specify these modules for 66-kV collection systems. The technology is unifying medium-voltage and low-voltage converter product lines into single platform families.
REACH substance restrictions are forcing reformulation of converter potting compounds and thermal interface materials. European nacelle assemblers now qualify alternative chemistries ahead of sunset dates. Offshore product categories face the steepest compliance burden due to salt-corrosion coating requirements.
Buyers now unbundle long-term service agreements from initial turbine supply contracts. Independent service providers capture gearbox and converter maintenance scopes previously held by original manufacturers. This pattern concentrates in mature European markets with large installed bases approaching warranty expiration.
Double-Fed Wind Turbine Market Segmentation
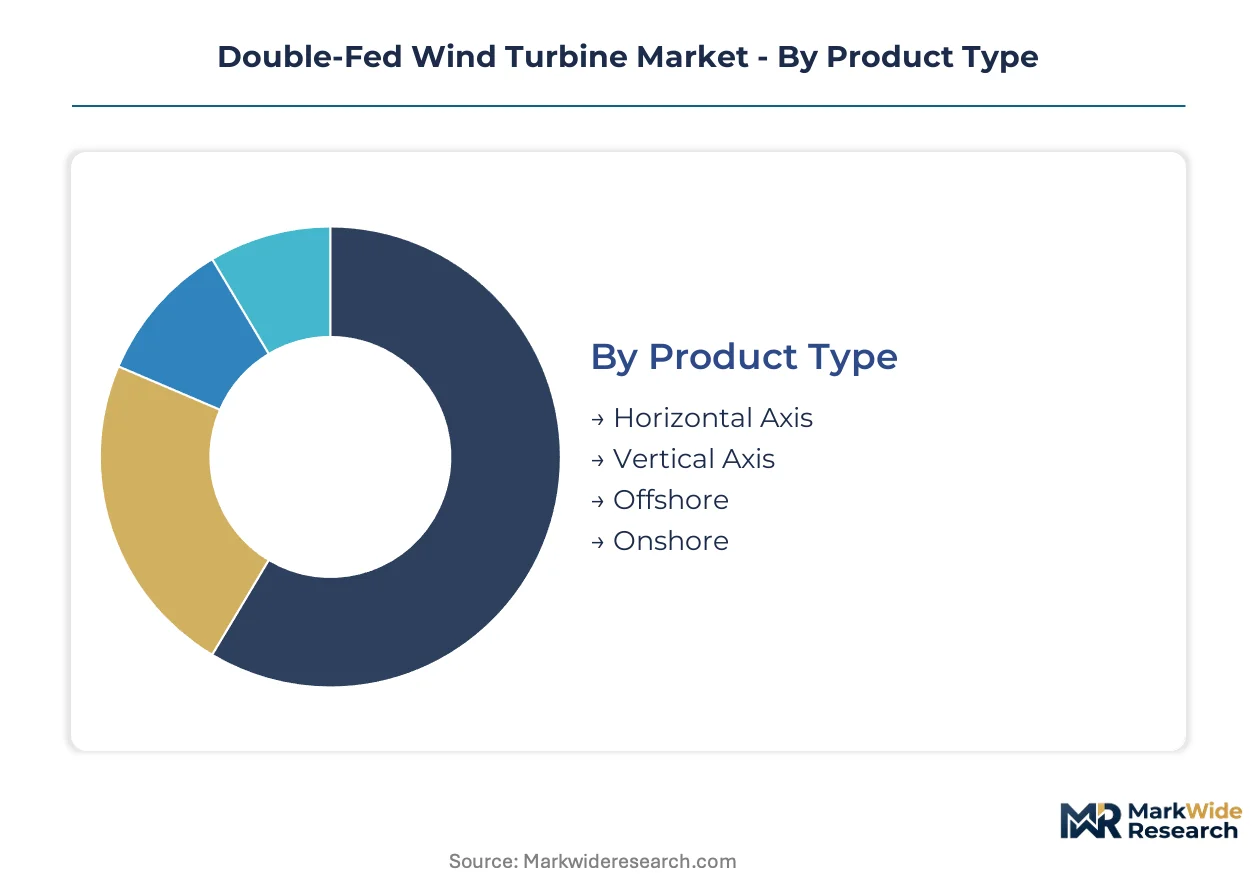
Segmentation in the double-fed wind turbine market reveals distinct capital deployment patterns across product architectures, customer risk profiles, and installation environments. Each dimension carries specific implications for converter sizing, grid compliance costs, and long-term service revenue capture.
Product Type:
Capital intensity varies sharply across product categories, with offshore configurations demanding the highest upfront outlays for corrosion-resistant nacelle assemblies and specialized transport logistics.
- Horizontal Axis:The dominant architecture positions rotor blades perpendicular to wind flow, enabling swept-area optimization across 2-15 MW nameplate ratings. Jiangsu and Guangdong provincial authorities fast-track interconnection approvals for these units in coastal wind corridors, though nacelle transport constraints through Germany's KBA-certified configurations limit hub-height scaling.
- Offshore:Salt-corrosion specifications and remote maintenance logistics inflate capital costs 40-60% above onshore equivalents. Northern European developers specify these units with integrated grid-forming capabilities under tightening EU network codes, compressing product lifecycles and forcing premature converter replacement schedules.
- Vertical Axis:Omnidirectional blade arrangements suit distributed urban installations where wind direction variability dominates.
- Onshore:Mature supply chains and standardized foundation designs minimize balance-of-plant costs across established wind corridors.
Horizontal axis configurations absorb the bulk of installed capacity; offshore product types are expanding most quickly.
End User:
Customer sophistication determines procurement complexity, with utilities commanding the most stringent technical specifications and longest-term service negotiations.
- Utilities:Vertically integrated grid operators leverage scale to mandate grid-forming converter capabilities and 25-year service agreements. China's coastal utilities drive the largest procurement volumes, though EU F-Gas Regulation compliance burdens raise capital requirements for cooling system retrofits inside turbine converters.
- Independent Power Producers:Merchant developers prioritize rapid deployment timelines and unbundled maintenance contracts. These stakeholders increasingly capture gearbox and converter maintenance scopes previously held by original manufacturers as European installed bases approach warranty expiration.
- Renewable Energy Developers:Project-specific entities optimize for construction financing efficiency and offtake agreement security.
- Government:Direct procurement concentrates in emerging markets seeking technology transfer and local assembly requirements.
Utilities dominate current order books; independent power producers are gaining share fastest.
Technology:
Technology selection trades upfront capital efficiency against long-term reliability premiums, with direct drive alternatives displacing conventional drivetrains in offshore applications.
- Gear-Driven:Multi-stage planetary gearboxes enable generator speed optimization while reducing nacelle mass. These systems retain cost advantages in mature onshore markets where maintenance infrastructure density supports scheduled gearbox replacement intervals.
- Direct Drive:Elimination of gearbox components reduces mechanical failure modes and enables compact nacelle designs favored by floating offshore platforms. Neodymium supply concentration in Chinese processing facilities creates input cost uncertainty for permanent magnet variants.
- Permanent Magnet:Synchronous generator architectures achieve highest conversion efficiency across partial load operation.
- Induction Generator:Wound-rotor designs enable double-fed operation with partial-scale converters rated at roughly 30% of total turbine capacity.
Gear-driven technology retains the largest installed base; direct drive alternatives are climbing the fastest.
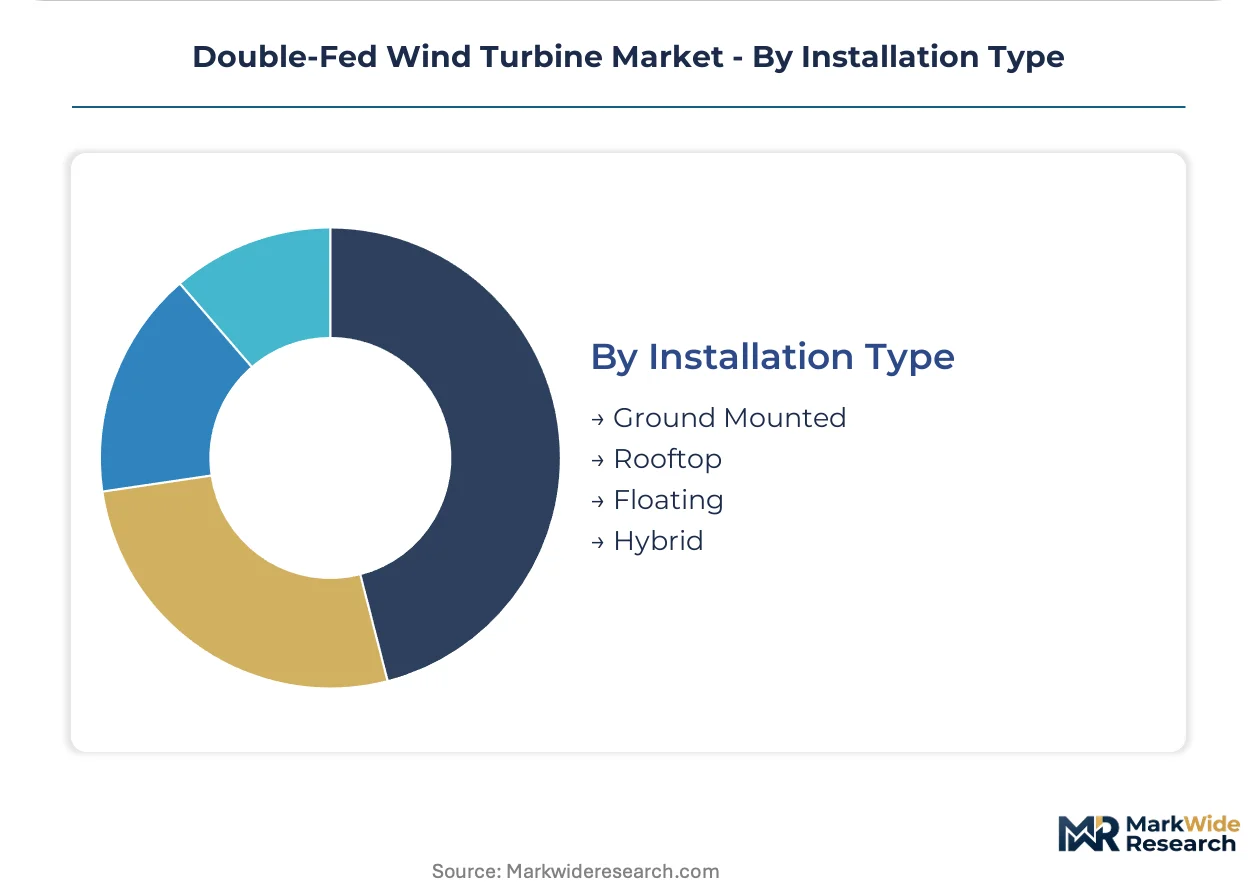
Installation Type:
Foundation engineering requirements create tiered capital structures, with floating platforms commanding specialized mooring and dynamic cable investments.
- Ground Mounted:Conventional tubular steel towers and reinforced concrete foundations dominate onshore deployment economics. These installations face EPA end-of-life blade disposal protocol compliance in the United States, adding operational layers for fleet operators.
- Floating:Tension-leg and semi-submersible foundations unlock deeper water sites where fixed-bottom economics fail. Silicon carbide power semiconductors in rotor-side converters enable compact nacelle designs critical for platform stability.
- Rooftop:Distributed urban installations face height restrictions and noise constraints limiting turbine scale.
- Hybrid:Co-location with solar PV or electrolyzer assets demands flexible power control and grid-islanding capabilities.
Ground mounted foundations anchor current deployment volumes; floating installations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal provinces concentrate the heaviest procurement volumes for multi-megawatt double-fed units, while Northern European offshore corridors drive premium-specification demand. Grid code tightening across multiple jurisdictions is fragmenting regional equipment standards.
China
Jiangsu and Guangdong provincial authorities fast-track interconnection approvals for variable-speed installations in coastal wind corridors. The GB standards mandate low-voltage ride-through capabilities that shape converter design specifications nationwide. Shanghai Electric and Sany Heavy Energy anchor manufacturing capacity in the Yangtze River Delta cluster.
Germany
Offshore developers in the North Sea specify grid-forming converter capabilities under tightening EU network codes. The KBA certifies transport configurations for oversized nacelle components moving through Hamburg and Bremerhaven. Vestas Wind Systems A/S leverages its European service footprint to sustain aftermarket revenue across the Baltic corridor.
United States
Independent power producers prioritize rapid deployment timelines and unbundled maintenance contracts in Texas and Midwest wind corridors. The EPA oversees end-of-life blade disposal protocols, adding operational compliance layers for fleet operators. Siemens Gamesa Renewable Energy S.A. positions converter assembly investments to serve Atlantic offshore lease areas.
India
The PLI scheme for domestic renewable energy components attracts converter assembly investments into Gujarat and Tamil Nadu. State electricity boards mandate grid stability provisions that favor variable-speed architectures. Wolong Electric Group Co., Ltd. exemplifies Chinese manufacturers targeting technology transfer partnerships in the subcontinent.
United Kingdom
Round 4 and 5 offshore lease allocations require synthetic inertia provision from turbine converters. The Contracts for Difference mechanism supports floating platform pilots in Scottish waters. ABB competes on converter control software meeting evolving grid code requirements across North Sea interconnectors.
Double-Fed Wind Turbine Market Competitive Landscape
Danish and German producers anchor one tier; Chinese specialists hold volume positions in cost-sensitive procurement. The vendor base splits between integrated turbine OEMs and power electronics pure-plays. Three archetypes dominate: converter-integrated OEMs, independent power electronics suppliers, and emerging domestic champions in Asia. Capacity expansion and strategic technology licensing represent the dominant competitive vectors.
Among European-integrated OEMs, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy S.A. exemplify the converter-turbine bundling archetype. ABB occupies a position as the independent power electronics specialist competing across multiple jurisdictions. CRRC Zhuzhou Electric Co., Ltd. and Wolong Electric Group Co., Ltd. represent Chinese domestic champions scaling through coastal province procurement programs.
| Leading Market Players |
|---|
| ABB |
| CRRC Zhuzhou Electric Co., Ltd. |
| XEMC Windpower Co., Ltd. |
| Wolong Electric Group Co., Ltd. |
| Shanghai Electric |
| Sany Heavy Energy Co., Ltd. |
| VEM Motors |
| Siemens Gamesa Renewable Energy S.A. |
| Vestas Wind Systems A/S |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance for converter cooling systems gates qualified supply access and premium-tier pricing for turbine OEMs serving Northern European offshore corridors. Buyers without certified thermal management partners face exclusion from grid-code-compliant procurement pools, compressing viable vendor sets and inflating contract premiums for compliant configurations.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as IGBT and SiC module fabrication constraints stretch converter delivery schedules. Pricing stratifies across certified grid-forming tiers, uncertified standard configurations, and spot-market legacy inventory, with differentiation anchored in GB standard low-voltage ride-through validation and EU F-Gas thermal compliance. Cost compression in standard onshore units is intensifying as Chinese coastal province procurement concentrates volume bargaining power with state-linked utilities. Independent power producers exhibit highest price sensitivity due to merchant financing structures, while vertically integrated utilities absorb premiums for synthetic inertia capabilities.
Supply Chain Analysis
Power electronics specialist scarcity in Germany, Denmark, and China's Yangtze River Delta clusters constrains converter control software scaling. Neodymium processing concentration in Chinese facilities, silicon carbide wafer fabrication in Japan and the United States, and copper winding supply from Chilean mines feed nacelle assembly networks. Single-source vulnerability in rare earth magnet supply creates input cost uncertainty for direct-drive permanent magnet variants. Distribution runs through Hamburg and Bremerhaven for North Sea offshore projects, with Shanghai and Guangdong ports anchoring Asia-Pacific flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Double-fed wind turbine vendors face a vertical-integration race where captive converter semiconductor sourcing and in-house grid-forming firmware development determine margin sustainability. Players without upstream power electronics control surrender pricing power to independent specialists.
For Market Incumbents: Hedge against silicon carbide module shortages through long-term foundry agreements with Japanese and South Korean wafer fabricators. Vestas and Siemens Gamesa must defend service contract attachment rates as independent providers capture gearbox and converter maintenance scopes in warranty-expiring European fleets. Backward integration into converter control software protects grid-code compliance margins across tightening EU network codes. For New Entrants and Emerging Players: India's PLI scheme for domestic renewable energy components opens a window for converter assembly investments targeting state electricity board procurement in Gujarat and Tamil Nadu. Floating offshore platform pilots in Scottish and Norwegian waters represent the most penetrable white-space segment, with tension-leg foundation demand outpacing qualified nacelle suppliers. A technology licensing partnership with established European OEMs accelerates grid-forming capability certification without full R&D burden. For Investors and Strategic Acquirers: First-mover grid-forming converter deployments in UK Round 4 and 5 lease allocations are the leading indicator that synthetic inertia provision will become standard procurement specification across North Sea interconnectors. Acquisition targets should center on power electronics pure-plays with certified firmware stacks for 66-kV collection systems and floating platform compact nacelle designs. Watch for GB standard expansion beyond low-voltage ride-through toward active power control mandates as the inflection signal for converter upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Converter Migration | Next-generation rotor-side converters unify medium-voltage and low-voltage product lines for 66-kV North Sea collection systems. |
| Grid-Forming Firmware Certification | Synthetic inertia algorithms satisfy UK Round 4 lease requirements and EU network code stability mandates. |
| Floating Platform Nacelle Optimization | Compact direct-drive designs reduce mass for tension-leg and semi-submersible foundation stability. |
| EU F-Gas Thermal Compliance Retrofit | Cooling system upgrades inside turbine converters unlock aftermarket revenue from installed European fleets. |
| India PLI Converter Assembly Localization | Domestic manufacturing incentives attract power electronics investments to serve state electricity board procurement. |
Research Methodology
Trade flow databases, IEA renewable energy deployment statistics, and FERC interconnection queue filings formed the secondary backbone for demand calibration. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors for offshore foundation installation, and grid operators for interconnection specification validated secondary estimates. Conversations with converter control software engineers and power semiconductor procurement leads at turbine OEMs informed technology adoption assumptions. Bottom-up capacity installation forecasts triangulated against top-down renewable energy target aggregations across national regulatory frameworks.
Bottom-up modeling tracked individual project development pipelines by capacity tier, foundation type, and grid connection voltage class. Segmentation dimensions spanned product architecture (horizontal axis, vertical axis), installation environment (onshore, offshore, floating), drivetrain technology (gear-driven, direct drive), and end-user risk profile (utility, independent power producer, merchant developer). CAGRs derived from fitted adoption curves reflecting grid code compliance deadlines and interconnection approval timelines. Forecast inputs incorporated silicon carbide module supply constraints, rare earth magnet price volatility, and floating platform foundation engineering maturity.
The model assumes a particular technology adoption path; alternative pathways for grid-forming converter deployment or direct-drive permanent magnet scaling would alter the outlook for double-fed architecture market share. Forecasts embed assumptions regarding EU F-Gas Regulation enforcement timing, China's GB standard expansion trajectory, and offshore lease allocation schedules across North Sea jurisdictions. Supply chain disruption in semiconductor fabrication, rare earth processing, or composite blade supply would revise installation volume projections. A small set of named triggers—grid-forming mandate adoption rates, floating platform cost curves, and converter semiconductor supply normalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Boat Wind Turbine Market