
 Vapor Recovery Services Market | 2026-2036
Vapor Recovery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Recovery Services Market Insights
Asset-light leasing and project finance structures is tilting competitive dynamics toward operators with balance-sheet flexibility rather than pure equipment ownership. Cimarron Energy leverages its integrated manufacturing and field service footprint across North American shale basins. AEREON anchors its position through combustion and vapor control technology leadership in upstream and midstream applications. Zeeco competes with specialized thermal oxidation systems that extend its reach into refinery and petrochemical emission control.
Vapor recovery services encompass the capture, processing, and reclamation of volatile organic compounds and hydrocarbon vapors from industrial storage, transfer, and processing operations, typically achieving recovery efficiencies exceeding 95% through mechanical compression, absorption, or condensation methods. The primary commercial purpose centers on regulatory compliance with air quality standards while converting recovered vapors into salable product or fuel gas. Mobile recovery services dominate short-term turnaround and well completion applications where capital deployment flexibility matters most. Fixed recovery systems anchor margin pools at terminal and storage facilities with predictable throughput profiles. Membrane separation technology leads growth among processing methods due to lower energy intensity and modular scalability for midstream gas conditioning.
The EPA enforces New Source Performance Standards under 40 CFR Part 60 Subpart OOOOa that mandate vapor recovery at oil and gas production, processing, and transmission facilities, directly expanding the addressable service market. State-level air quality regulators in Texas, Colorado, and New Mexico supplement federal rules with methane intensity targets and leak detection requirements that tighten compliance schedules. OSHA process safety management standards shape equipment certification and technician training protocols for hazardous vapor handling operations. Stakeholders must monitor evolving state methane rules and carbon intensity accounting frameworks to align service portfolios with buyer compliance timelines and capital planning cycles.
Market Dynamics
Asset-light leasing structures are compressing capital barriers for oil and gas operators seeking vapor recovery compliance without balance-sheet strain. The shift from equipment ownership to service-based models concentrates margin pools with field-service networks and project finance providers rather than pure manufacturers.
Growth Catalysts
- EPA Subpart OOOOa mandates:Federal methane capture requirements at oil and gas production sites expand the addressable service market for wellhead vapor recovery units.
- Permian Basin flaring restrictions:Texas and New Mexico regulators tighten gas flaring limits, forcing operators to deploy mobile recovery services during completion and workover operations.
- Membrane separation technology:Lower energy intensity and modular scalability for midstream gas conditioning accelerates adoption over traditional compression and absorption methods.
Market Restraints
- Steel and alloy input volatility:Pressure vessel fabrication costs fluctuate with nickel and chromium pricing, squeezing margins on fixed system deployments.
- Specialized technician scarcity:OSHA process safety management certification requirements limit the pool of qualified field personnel for hazardous vapor handling operations.
- Gas gathering infrastructure bottlenecks:Pipeline capacity constraints in the Delaware and Midland sub-basins strand recovered vapors, reducing net recovery economics for operators.
Strategic Opportunities
- Carbon intensity accounting frameworks:Emerging Scope 1 methane disclosure rules create demand for certified vapor recovery services that generate verifiable emissions reductions for ESG reporting.
- Refinery turnaround services:Petrochemical storage tank degassing and railcar loading operations represent underpenetrated applications for mobile thermal oxidation and vapor control units.
- Lease-to-own financing structures:Equipment-backed project finance vehicles enable mid-tier operators to access recovery technology without upfront capital deployment.
Industry Challenges
- Legacy SCADA integration complexity:Retrofitting vapor recovery units with digital monitoring systems requires custom protocol translation at aging terminal and tank farm facilities.
- State regulatory fragmentation:Divergent methane intensity targets across Colorado, Texas, and New Mexico force service providers to maintain multiple compliance protocols and reporting formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Recovery Services Market |
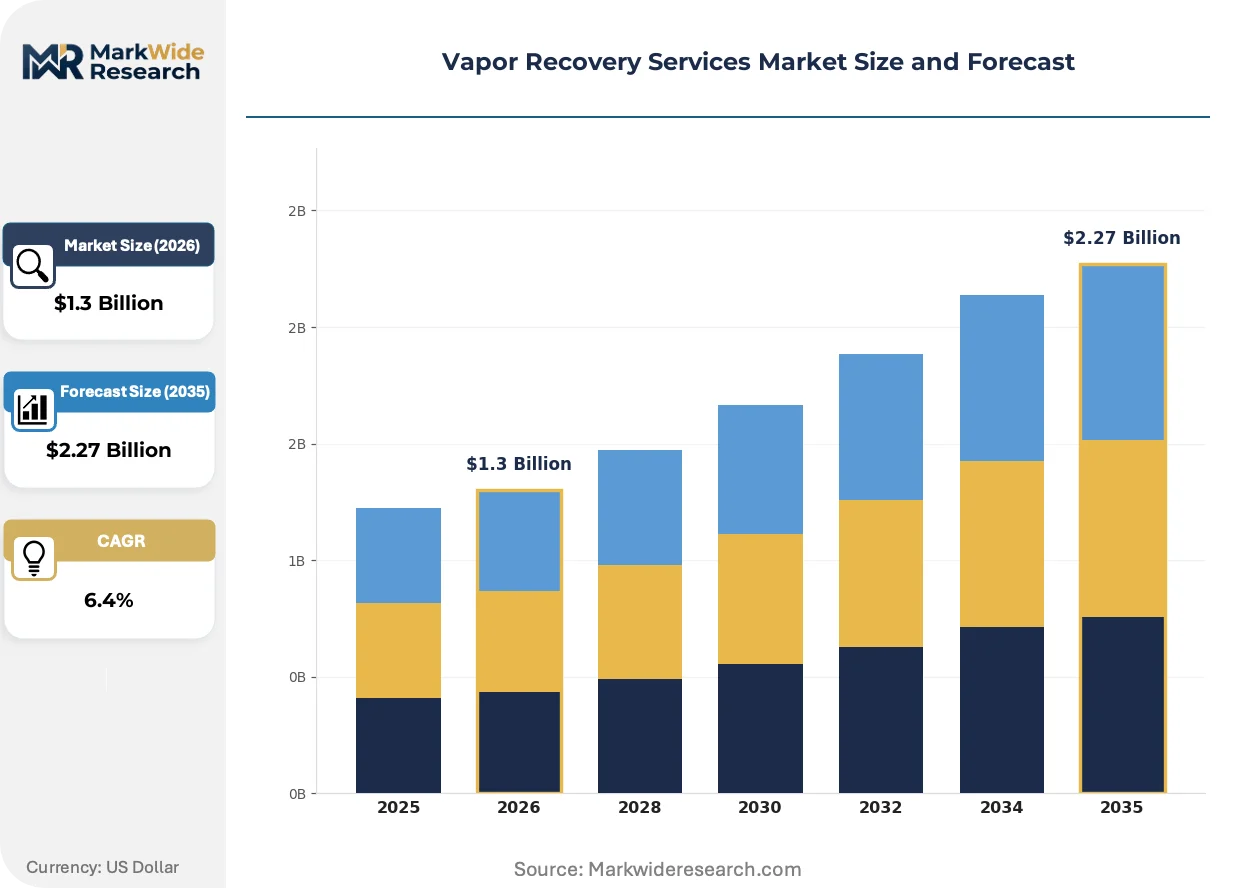
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Recovery, Fixed Recovery, Centralized Recovery, Stationary Recovery End User: Petrochemical, Oil & Gas, Chemical Processing, Transportation Technology: Thermal Oxidation, Condensation, Adsorption, Membrane Separation Application: Fuel Storage, Distribution, Chemical Manufacturing, Emission Control |
| Companies Covered | Cimarron Energy, AEREON, John Zink Hamworthy Combustion, Zeeco, PSG Dover, Ingersoll Rand, Petrogas Systems, Hy-Bon/EDI, Flogistix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Recovery Services Market Trends and Innovations
Digital instrumentation and predictive maintenance architectures are displacing reactive service models across vapor recovery operations. The convergence of IoT sensors with cloud-based analytics compresses downtime windows and shifts competitive advantage toward data-integrated service providers.
Edge computing platforms embedded in vapor recovery unit controllers are digitizing real-time compression performance and leak detection. Midstream operators with distributed storage terminals deploy these systems to preempt equipment failures before methane releases trigger regulatory violations. The technology is digitizing field service dispatch decisions, replacing scheduled maintenance with condition-based interventions that reduce technician truck rolls by routing crews only to flagged anomalies.
The EPA's 2024 enforcement emphasis on 40 CFR Part 60 Subpart OOOOa optical gas imaging inspections intensifies compliance scrutiny at upstream facilities. Oil and gas producers face expanded documentation requirements for vapor recovery unit uptime and maintenance records during agency audits. Smaller independent operators in the Permian Basin respond by outsourcing entire compliance programs to specialized service firms with embedded regulatory expertise and inspection-ready record systems.
Buyer consolidation among supermajor oil and gas companies concentrates procurement leverage over vapor recovery service contracts. Integrated operators now bundle wellhead, gathering, and terminal vapor control under single-source master service agreements that displace fragmented vendor relationships. This concentration is most visible in the Permian Basin, where ExxonMobil and Chevron have consolidated midstream emission control contracts with providers offering basin-wide coverage and standardized equipment fleets.
Vapor Recovery Services Market Segmentation
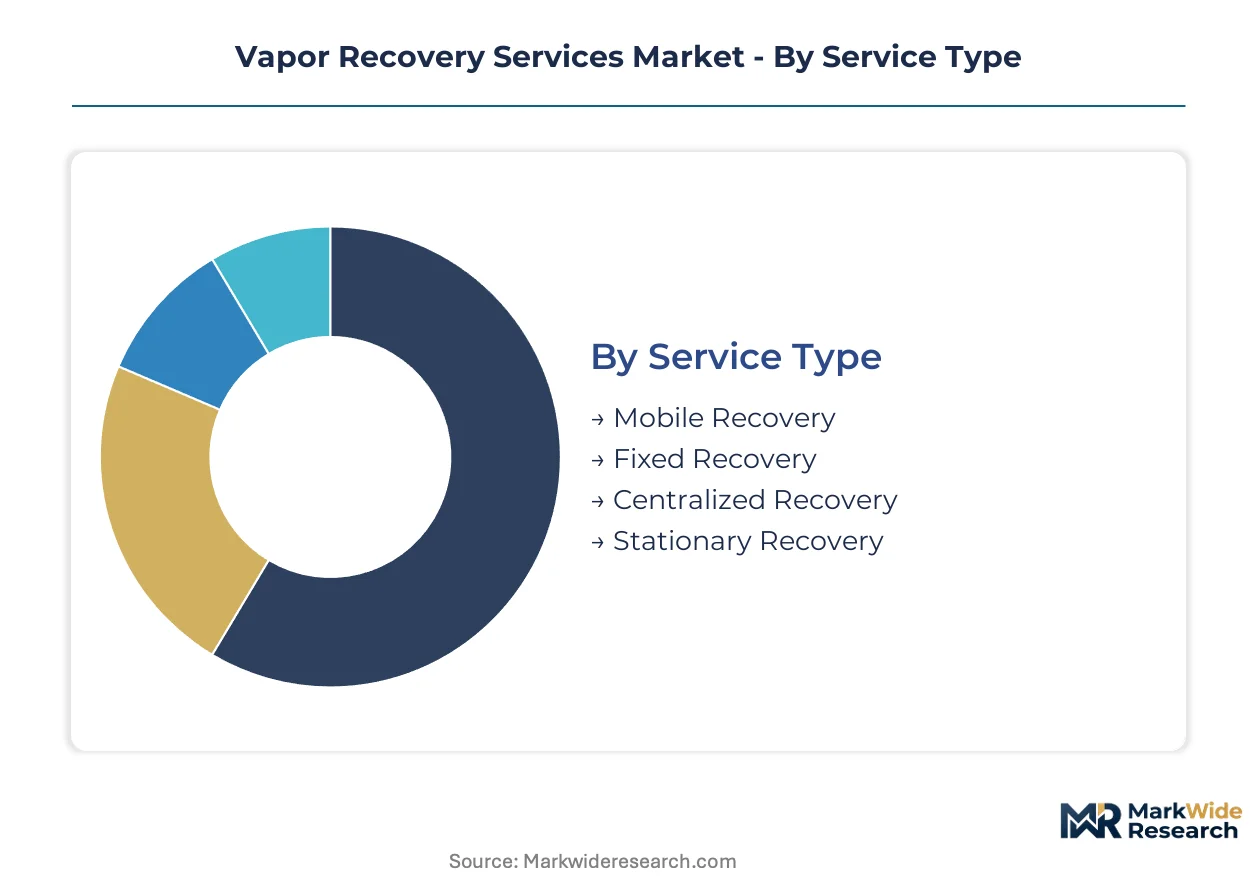
Vapor recovery services fragment across service models, end-use industries, processing technologies, and application settings. Each segmentation axis reveals distinct margin structures, capital intensity profiles, and regulatory exposure levels that shape provider positioning.
Service Type:
Mobile and fixed configurations span the use-case spectrum from episodic wellhead operations to permanent terminal infrastructure.
- Mobile Recovery:Trailer-mounted compression and thermal oxidation units deploy to well completions, turnarounds, and emergency response scenarios. Permian Basin operators lease these services during drilling surges when flaring restrictions tighten and pipeline connections lag behind production.
- Fixed Recovery:Permanently installed vapor recovery units anchor storage terminal and refinery tank farm operations with predictable throughput economics. Gulf Coast petrochemical complexes favor these systems for continuous emission control compliance under EPA Subpart OOOOa mandates.
- Centralized Recovery:Shared processing facilities serve multiple small producers in gas gathering-constrained basins, pooling vapor streams before pipeline injection.
- Stationary Recovery:Modular skid-mounted systems occupy intermediate positions between fully mobile and permanently fixed installations, common at midstream compressor stations.
The dominant share belongs to Fixed Recovery, while Mobile Recovery is closing the gap fastest.
End User:
Customer concentration varies by capital deployment cycle and regulatory scrutiny intensity across industrial sectors.
- Oil & Gas:Upstream producers and midstream gatherers drive baseline demand through wellhead vapor capture and storage tank emission control. Texas and New Mexico regulators enforce methane intensity targets that expand service procurement across the Permian, Delaware, and Midland sub-basins.
- Petrochemical:Refinery tank degassing, railcar loading, and process vent recovery command premium pricing for specialized thermal oxidation and membrane separation services. Gulf Coast complexes facing EPA enforcement emphasis on optical gas imaging inspections outsource compliance program management.
- Chemical Processing:Specialty chemical manufacturers deploy adsorption-based recovery for solvent vapor reclamation with product value recovery economics.
- Transportation:Marine terminal and truck loading operations capture vapors during fuel transfer, with California and Texas coastal facilities leading adoption.
Oil & Gas commands the largest revenue pool, though Petrochemical end-use is expanding most quickly on turnaround service demand.
Technology:
Processing method selection hinges on vapor composition, energy cost exposure, and salable product recovery potential.
- Membrane Separation:Polymeric membrane modules separate hydrocarbon vapors from nitrogen and air with lower energy intensity than compression-based alternatives. Midstream operators in gas conditioning applications favor this technology for modular scalability and reduced carbon footprint.
- Thermal Oxidation:High-temperature combustion destroys volatile organic compounds when vapor recovery is uneconomical, dominating refinery flare gas and hazardous waste applications. Zeeco and AEREON compete on combustion efficiency and NOx minimization in these systems.
- Condensation:Refrigeration-based vapor recovery captures high-value product streams from storage tank breathing losses, common at chemical and petrochemical terminals.
- Adsorption:Activated carbon and zeolite systems target trace contaminant removal and solvent recovery in chemical processing facilities.
Thermal Oxidation retains the largest installed base, yet Membrane Separation is gaining share fastest on midstream energy efficiency priorities.
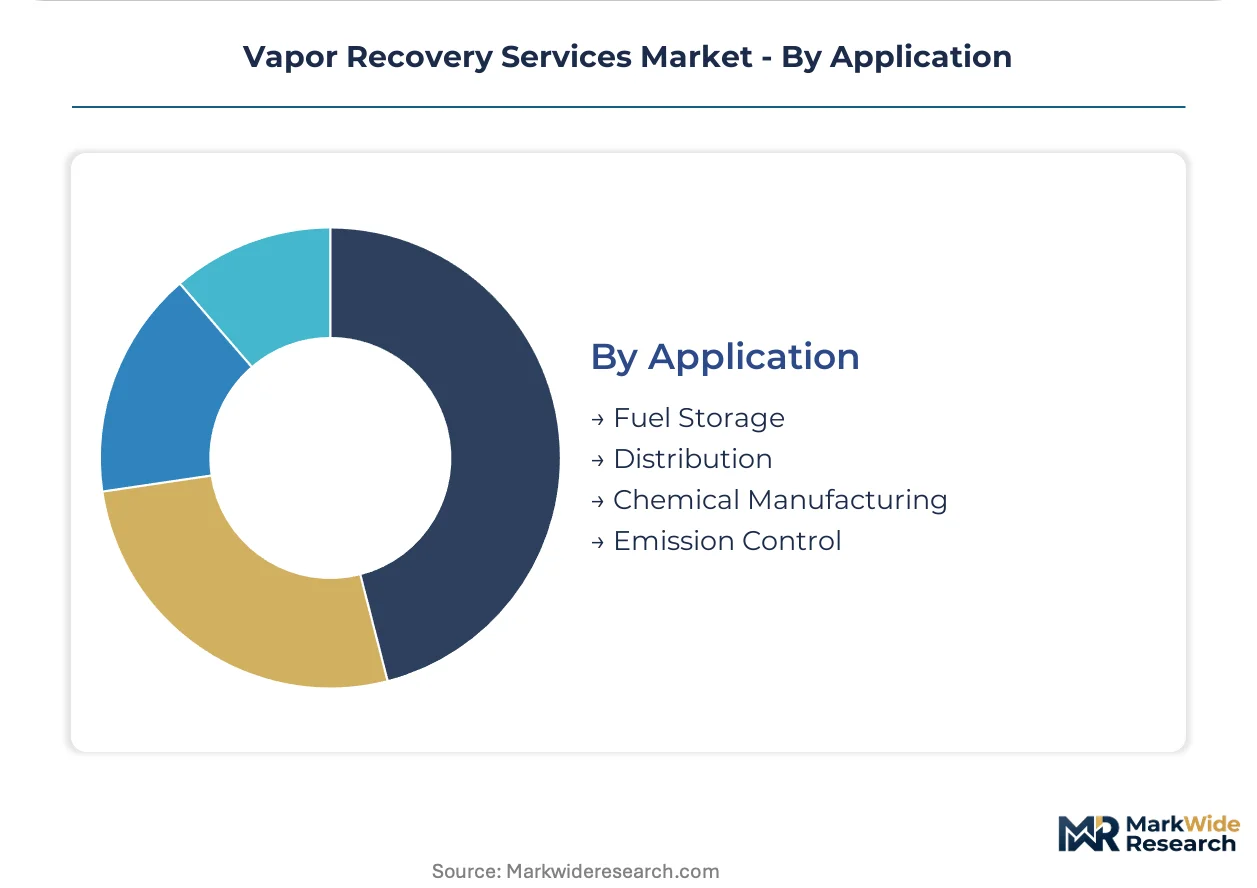
Application:
Regulatory trigger points and product value recovery potential define application-level demand patterns.
- Emission Control:Compliance-driven vapor capture at production sites, storage facilities, and transfer points responds directly to EPA Subpart OOOOa mandates and state methane rules. Documentation requirements for uptime and maintenance records intensify under 2024 enforcement emphasis.
- Fuel Storage:Underground and aboveground tank vapor recovery addresses gasoline distribution and crude oil storage in urban air quality non-attainment areas.
- Distribution:Pipeline, rail, and marine loading operations capture transfer vapors with mobile and fixed recovery configurations.
- Chemical Manufacturing:Process vent and equipment degassing applications recover valuable solvents and monomers while meeting OSHA process safety management standards.
Emission Control applications dominate procurement volume, with Chemical Manufacturing climbing fastest on solvent value recovery economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA methane regulations under 40 CFR Part 60 Subpart OOOOa and parallel state-level programs in major oil-producing jurisdictions are directing capital deployment toward vapor recovery infrastructure. Service demand concentrates in shale basins where flaring restrictions and gathering constraints intersect.
United States
Permian Basin operators in Texas and New Mexico contract mobile vapor recovery units during completion surges when pipeline connections lag production. EPA Subpart OOOOa mandates methane capture at wellheads and storage facilities, expanding the compliance-driven service market. Midland and Delaware sub-basins anchor procurement volume, with supermajors consolidating emission control contracts under single-source agreements.
Canada
Alberta oil sands and conventional production sites deploy vapor recovery for methane reduction under provincial emission intensity regulations. The country's national energy regulator enforces facility-level reporting that drives service outsourcing among mid-tier operators. Calgary-based service networks coordinate deployment across the Western Canadian Sedimentary Basin where cold-weather equipment specifications differentiate provider capabilities.
Germany
Industrial chemical complexes in North Rhine-Westphalia and Bavaria utilize vapor recovery for solvent reclamation and emission compliance under REACH and TA Luft air quality standards. The EU Green Deal carbon border adjustment mechanism intensifies monitoring requirements at refinery and petrochemical terminals. BASF and Bayer facility clusters around Ludwigshafen and Leverkusen represent premium service opportunities for specialized thermal oxidation and membrane separation providers.
Saudi Arabia
Aramco upstream and downstream operations anchor vapor recovery demand across the Eastern Province oil and gas processing corridor. The national oil company's methane intensity reduction commitments drive service procurement at Ghawar field facilities and Ras Tanura refinery complexes. Domestic content requirements under Vision 2030 industrial localization programs shape joint venture structures between international technology providers and Saudi fabrication partners.
China
Petrochemical storage terminals in the Yangtze River Delta and Pearl River Delta deploy vapor recovery for urban air quality compliance under MEE emission standards. Dual carbon goals accelerate membrane separation adoption at midstream gas conditioning facilities seeking lower energy intensity. Ningbo and Shanghai port complexes represent high-volume applications for marine loading and tank farm emission control services.
Vapor Recovery Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented service tiers. The vendor base separates into integrated field-service networks, combustion technology specialists, and modular equipment fabricators. Three archetypes dominate: balance-sheet-flexible lessors with basin-wide coverage, technology-anchored system providers with manufacturing depth, and project-finance-enabled regional operators. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for technology licensing.
Among North American integrated service providers, Cimarron Energy and AEREON exemplify contrasting archetypes. Cimarron represents the manufacturing-anchored model with in-house fabrication and field service integration across shale basins. AEREON occupies a position within combustion and vapor control technology leadership for upstream and midstream applications. Zeeco, a specialized thermal oxidation system provider, anchors the refinery and petrochemical emission control segment. These three companies illustrate the strategic segmentation between field-service scale, technology specialization, and end-market focus that structures competitive positioning.
| Leading Market Players |
|---|
| Cimarron Energy |
| AEREON |
| John Zink Hamworthy Combustion |
| Zeeco |
| PSG Dover |
| Ingersoll Rand |
| Petrogas Systems |
| Hy-Bon/EDI |
| Flogistix |
| Others |
Pricing and Supply Chain Analysis
Steel and alloy input volatility determines both pricing tier spreads and supply chain shape across vapor recovery services. Nickel and chromium price swings compress margins on fixed system deployments while pushing service providers toward asset-light leasing structures that transfer fabrication risk to contract manufacturers.
Pricing Analysis
Certification level under EPA and OSHA standards creates the primary spread between premium and standard service tiers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance complexity and field service bundling. Cost compression in the economy tier is intensifying because commodity steel price volatility squeezes fixed-system fabricators without captive sourcing. Independent operators in the Permian Basin exhibit highest price sensitivity, while supermajor bundled contracts show least sensitivity due to master service agreement structures.
Supply Chain Analysis
Contract manufacturing concentration sits with Gulf Coast pressure vessel fabricators and Midwest modular equipment specialists. Geographic supply concentration centers on Texas, Louisiana, and Oklahoma for fabrication capacity, with specialty membrane modules drawing from Massachusetts and California technology clusters. Raw material dependencies rest on nickel-alloy steel plate, polymeric membrane substrates, and high-temperature combustion ceramics. Single-source vulnerability runs through specialized membrane polymer suppliers. Distribution runs through basin-wide field service networks that position mobile units near drilling activity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. EPA Subpart OOOOa mandates and state methane intensity rules create switching costs that lock operators into established service relationships.
For Market Incumbents: Insulate position by deepening backward integration into membrane module manufacturing and expanding certified technician training pipelines. The threat of mobile-first regional entrants with lower overhead structures demands countermeasures through master service agreement renewals that embed multi-basin coverage commitments.
For New Entrants and Emerging Players: The petrochemical refinery turnaround segment offers the most penetrable white-space target, with Gulf Coast complexes outsourcing compliance program management under EPA optical gas imaging enforcement. A go-to-market angle anchored in digital instrumentation integration—edge computing platforms with predictive maintenance architectures—differentiates against legacy reactive service models.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors balance-sheet-flexible lessors with basin-wide coverage. Long-term viability over the next decade rests on carbon intensity accounting framework alignment and ESG reporting credentialization. The acquisition target archetype combines field service scale with embedded regulatory expertise. The signal to watch is supermajor procurement consolidation velocity, particularly ExxonMobil and Chevron master service agreement bundling patterns in the Permian Basin.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Midstream operators favor lower-energy separation methods for gas conditioning applications. |
| Basin-Wide Field Service Expansion | Permian Delaware and Midland sub-basins reward coverage density with contract consolidation. |
| Digital Platform Integration | IoT-enabled predictive maintenance compresses downtime windows and reduces technician dispatch costs. |
| Regulatory Compliance Outsourcing | EPA enforcement emphasis drives smaller independents toward full-service program management. |
| Project Finance Vehicle Structuring | Lease-to-own arrangements unlock mid-tier operator access without upfront capital deployment. |
Research Methodology
A standing panel of vapor recovery service operations managers, EPA compliance officers at upstream producers, midstream gathering system engineers, and field service technicians provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from EPA enforcement databases, state air quality regulator filings, FERC infrastructure reports, and oil and gas operator SEC disclosures. Bottom-up equipment deployment tallies and top-down service revenue estimates underwent cross-triangulation to anchor segmentation splits.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. The analytical framework modeled service type, end-use industry, processing technology, and application setting dimensions alongside regional regulatory intensity tiers. CAGRs derived from equipment deployment run rates, contract renewal patterns, and methane regulation phase-in schedules. Forecast inputs incorporated membrane technology adoption curves, steel price volatility bands, and supermajor procurement consolidation velocity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by balance-sheet-flexible lessors or accelerated membrane technology licensing would shift outcomes. Regulatory enforcement intensity variations, gas gathering infrastructure buildout delays, and carbon intensity accounting standard adoption pace represent specific revision risks. Quarterly review of EPA inspection announcement patterns, state methane rulemaking calendars, and supermajor master service agreement award flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market