

Enclosed Waste Gas Flares Market Size, Share, and Industry Trends Forecast 2026-2036
Enclosed Waste Gas Flares Market Insights
The United States Gulf Coast is narrowing its technology gap with European combustion standards. John Zink leverages its vertical integration across burner design and control systems to sustain project margins. Zeeco anchors its position through specialized engineering for high-pressure refinery applications. Cimarron Energy competes by extending service reach across upstream and midstream flare retrofits.
Enclosed waste gas flares are engineered combustion systems that destroy volatile organic compounds and hazardous air pollutants through controlled high-temperature oxidation, typically operating between 1,200°F and 2,000°F with destruction efficiencies exceeding 98%. These systems serve petroleum refineries, chemical plants, and waste treatment facilities that must manage vent streams containing methane, hydrogen sulfide, or hydrocarbon vapors without visible flame or smoke emissions. Thermal flares dominate installed base volumes across legacy refining infrastructure, while flare gas recovery technology commands premium positioning as operators seek to capture valuable hydrocarbons rather than destroy them. Remote monitoring capabilities are expanding fastest among technology categories, driven by predictive maintenance contracts and regulatory data reporting requirements.
EPA flare management regulations and OSHA process safety standards shape product design mandates and inspection frequencies across United States installations. The European Union's Industrial Emissions Directive and F-Gas Regulation create parallel compliance obligations for multinational operators with transatlantic assets. Stakeholders must weigh capital allocation between combustion hardware upgrades and vapor recovery integration as emission thresholds tighten without corresponding relief in project payback periods.
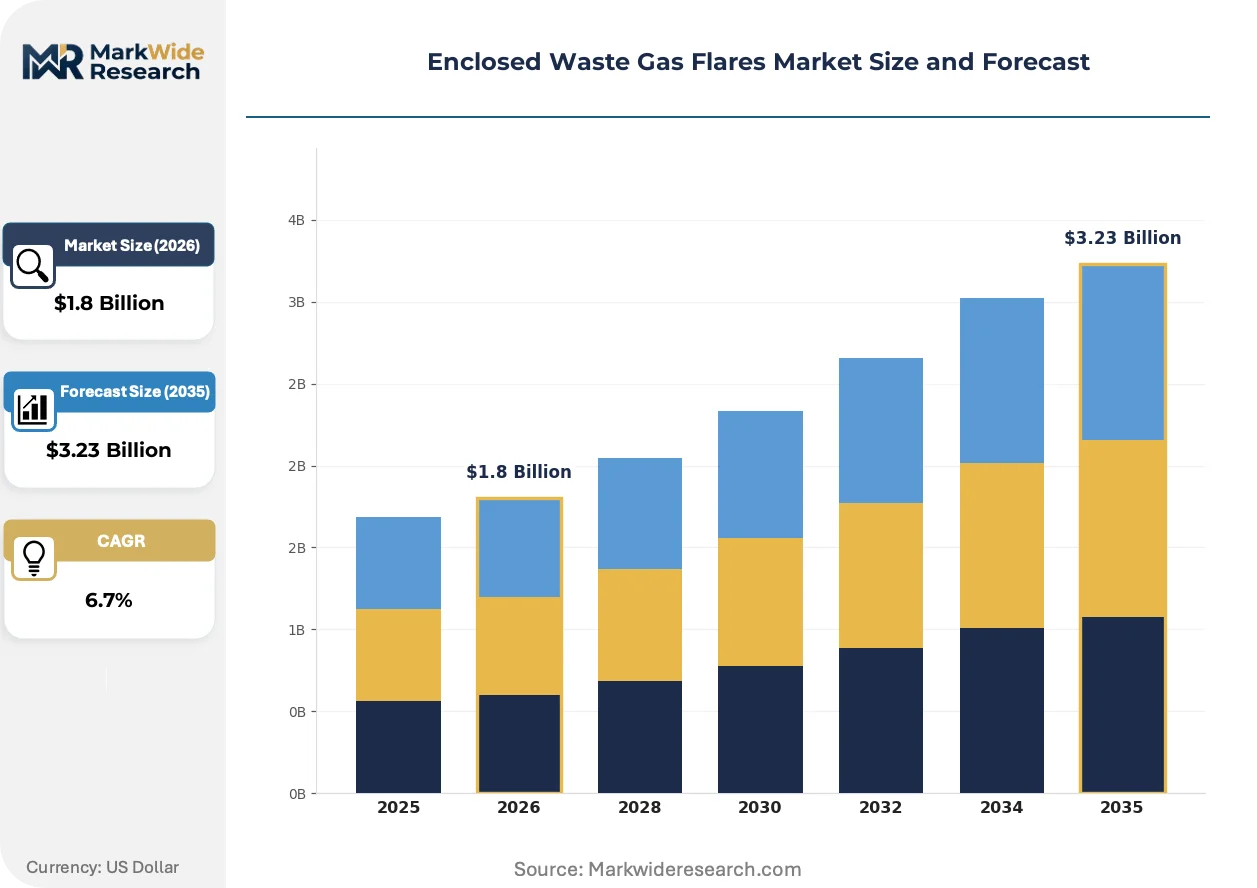
Market Dynamics
EPA flare management rules are compressing payback periods for combustion hardware upgrades, forcing refinery operators to choose between immediate retrofit investments and deferred regulatory penalties. This regulatory pressure is restructuring capital allocation across petroleum processing infrastructure.
Growth Catalysts
- EPA Flare Management Rules:Tightened emission thresholds for volatile organic compounds drive replacement cycles across Gulf Coast refining clusters. Operators face penalty exposure without combustion efficiency improvements.
- Permian Basin Investment:Steam-assisted flare systems attract capital as upstream operators seek visible-flame elimination in high-visibility production zones. Basin-specific engineering requirements create technology pull.
- Remote Monitoring Adoption:Predictive maintenance contracts expand as regulatory data reporting mandates require continuous emission verification. Sensor integration creates recurring revenue attachment for hardware suppliers.
Market Restraints
- Specialized Alloy Costs:High-nickel stainless steels for high-temperature combustion chambers expose fabricators to volatile commodity pricing. Material cost pass-through limits margin protection for project-based contracts.
- Engineering Talent Concentration:Combustion system design expertise clusters in Oklahoma and Texas metro areas. Geographic concentration creates wage pressure and project timeline risk for national deployments.
- Flare Gas Recovery Substitution:Vapor capture systems for methane and light hydrocarbons reduce waste gas volumes available for combustion destruction. Recovery economics improve with carbon credit pricing mechanisms.
Strategic Opportunities
- Digital Twin Integration:Computational fluid dynamics modeling converges with IoT sensor networks to optimize combustion efficiency in real time. Combined platforms enable performance-based service contracting.
- Chemical Plant Expansion:Petrochemical capacity additions along the US Gulf Coast create greenfield demand for enclosed flare systems. Newbuild specifications exceed retrofit requirements for destruction efficiency.
- OSHA Process Safety Alignment:Integrated safety system specifications create bundling opportunities for flare controls with pressure relief valve monitoring. Cross-regulatory compliance reduces buyer procurement complexity.
Industry Challenges
- Combustion Engineering Skill Gap:Experienced burner designers with high-pressure hydrocarbon expertise retire faster than training programs replenish supply. Project execution timelines stretch as specialized labor competes across energy infrastructure.
- Legacy Control System Integration:DCS and SCADA retrofits for 1990s-era refinery infrastructure require custom protocol translation. Integration complexity extends commissioning schedules and warranty exposure.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enclosed Waste Gas Flares Market Trends and Innovations
Digital instrumentation and advanced combustion modeling are displacing rule-of-thumb burner design across refinery flare specifications. These capabilities compress engineering cycles while tightening emission performance guarantees.
Plasma-assisted ignition systems eliminate pilot fuel consumption in continuous flare operations. Refinery operators in Texas and Louisiana deploy these systems to reduce methane slip and operating cost simultaneously. Conventional pilot burner maintenance is rendering obsolete as flame detection reliability improves with optical sensors and real-time temperature feedback.
EPA's updated flare combustion efficiency requirements mandate minimum 98% destruction removal efficiency with continuous monitoring verification. Refinery engineering teams must redesign tip configurations and staging protocols to maintain performance across varying waste gas compositions. High-hydrogen vent streams from hydrotreating units face the most stringent compliance testing schedules under the revised framework.
Integrated service contracts bundle hardware, installation, and multi-year maintenance under single-source accountability. Refinery procurement departments favor this structure over fragmented vendor management for critical emission control assets. The Gulf Coast petrochemical corridor shows the fastest contract structure evolution, with operators consolidating supplier relationships to reduce interface risk during turnaround periods.
Enclosed Waste Gas Flares Market Segmentation
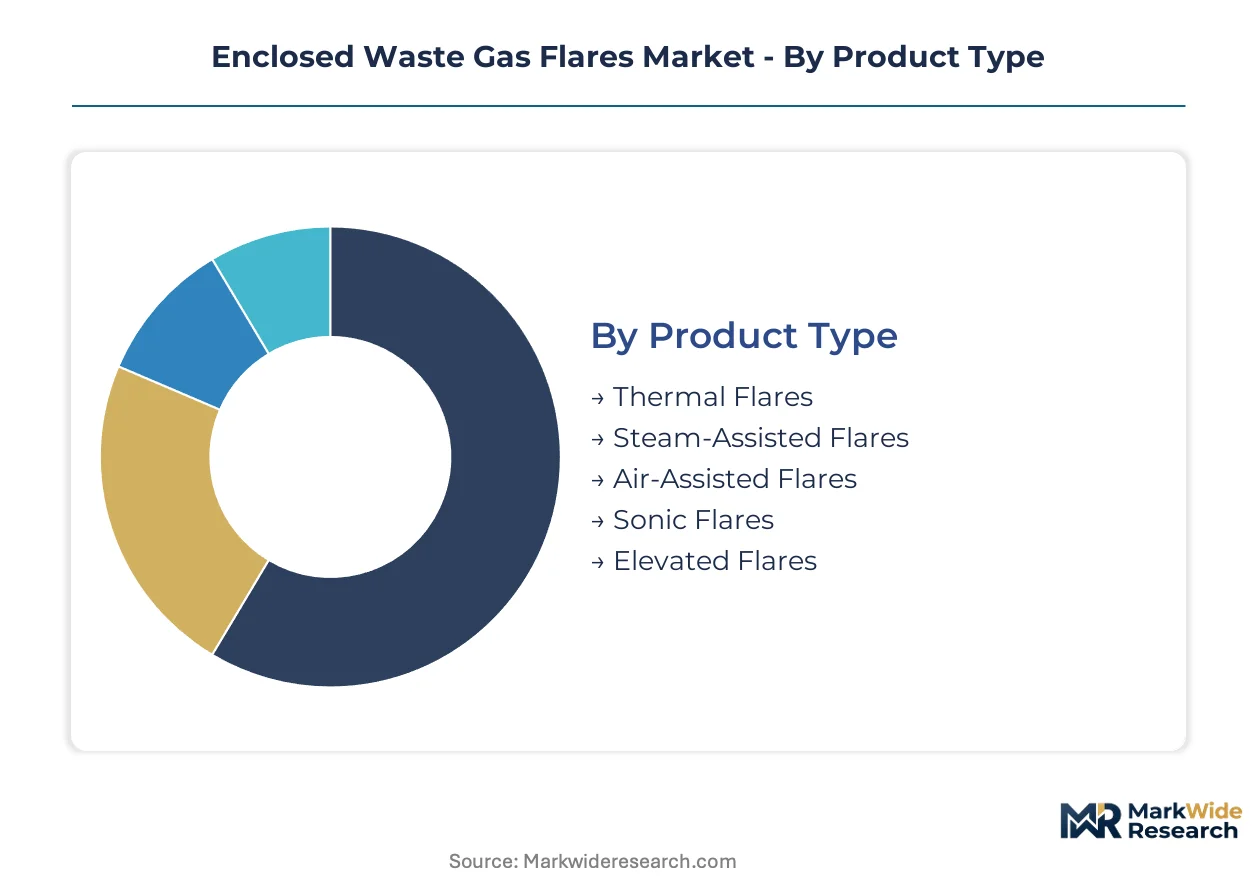
Segmentation in enclosed waste gas flares reveals divergent engineering requirements across combustion technologies and end-use environments. Each product category carries distinct maintenance protocols, spare parts inventories, and field service deployment patterns that shape supplier economics.
Product Type:
After-sales service intensity varies dramatically across flare designs, with steam-assisted systems demanding the most intensive field engineering support due to boiler maintenance and water treatment integration.
- Thermal Flares:These systems rely on direct combustion without auxiliary media, utilizing refractory-lined combustion chambers rated for continuous operation at 1,200°F to 2,000°F. Refinery operators on the US Gulf Coast specify thermal flares for high-volume routine venting where simplicity outweighs efficiency optimization. Service contracts concentrate on refractory replacement cycles and burner tip refurbishment.
- Steam-Assisted Flares:Steam injection at the flare tip entrains ambient air to improve combustion efficiency and suppress smoke formation. Permian Basin upstream operators deploy these systems to eliminate visible flame in production zones near populated areas. The steam generation subsystem requires continuous water chemistry monitoring and boiler tube inspection protocols.
- Air-Assisted Flares:Blowers force combustion air through the flare tip, eliminating steam infrastructure in arid regions. These systems suit remote installations where water supply is unreliable.
- Sonic Flares:High-velocity gas discharge creates supersonic conditions that enhance mixing and destruction efficiency. Sonic designs serve specialized high-pressure relief applications.
- Elevated Flares:Tall stack structures disperse combustion products above ground-level receptors. These dominate legacy refinery installations with substantial structural maintenance requirements.
By volume, Thermal Flares leads. By growth pace, Steam-Assisted Flares is ahead.
Technology:
Technology selection tracks regulatory stringency gradients, with operators in jurisdictions with EPA enforcement prioritizing verified destruction efficiency over capital cost minimization.
- Gas Combustion:Conventional open-flame oxidation remains the baseline technology for hydrocarbon destruction, with EPA mandates now requiring minimum 98% destruction removal efficiency. Refinery engineering teams specify staged combustion configurations to handle variable waste gas compositions from hydrotreating units.
- Vapor Recovery:Compression and condensation systems capture valuable hydrocarbons before they reach combustion stages. Chemical plants along the Texas Gulf Coast install vapor recovery to reduce feedstock losses and carbon credit exposure simultaneously.
- Flare Gas Recovery:These systems route waste gas back into process fuel networks or product streams, eliminating combustion entirely when economically viable. Recovery economics improve with methane pricing and carbon offset mechanisms.
- Emission Control:Add-on scrubbing and filtration technologies address specific pollutant categories beyond standard combustion.
- Remote Monitoring:IoT sensor networks enable predictive maintenance and regulatory data reporting. Louisiana refineries adopt remote monitoring fastest to satisfy EPA continuous verification requirements.
Gas Combustion dominates current installation base. Remote Monitoring is expanding most quickly as regulatory data mandates harden.
Application:
Application segmentation reflects divergent gas composition profiles, with refining applications handling the most complex mixed hydrocarbon streams and biogas operations managing consistent methane-dominant feeds.
- Refining:Petroleum refineries generate waste gas streams from catalytic cracking, hydrotreating, and sulfur recovery units with highly variable flow rates and heating values. US Gulf Coast operators face the most stringent EPA flare combustion efficiency requirements in this segment.
- Petrochemical Processing:Ethylene crackers and aromatics units produce concentrated vent streams with high hydrogen content. Texas petrochemical corridor expansions drive greenfield demand for enclosed flare specifications exceeding retrofit standards.
- Chemical Manufacturing:Specialty chemical plants manage intermittent venting from batch processes with unpredictable composition swings.
- Landfill Gas Management:Municipal waste decomposition generates methane-rich gas requiring controlled destruction or utilization. Collection system variability challenges combustion stability.
- Biogas Plants:Anaerobic digesters at agricultural and wastewater facilities produce consistent methane streams. Renewable energy incentives support upgrading to pipeline quality rather than flaring.
Refining commands the largest equipment spend. Petrochemical Processing shows the steepest expansion trajectory from capacity additions.
End User:
End user categories separate by procurement sophistication, with oil refineries maintaining dedicated combustion engineering staff while renewable energy producers rely more heavily on supplier technical support.
- Oil Refineries:Integrated petroleum refineries operate the largest installed base of enclosed flares, with dedicated reliability teams managing turnaround schedules. Marathon Petroleum and Valero facilities on the Gulf Coast drive replacement cycles as EPA rules tighten.
- Chemical Plants:Dow and LyondellBasell operations specify high-availability systems with redundant ignition and staged combustion for process safety compliance. OSHA process safety management integration shapes control system architecture.
- Waste Treatment Facilities:Industrial wastewater and hazardous waste incinerators manage corrosive vent streams with specialized metallurgy requirements.
- Renewable Energy Producers:Biogas and landfill gas developers prioritize modular systems with rapid deployment timelines.
- Power Generation:Natural gas power plants utilize enclosed flares for startup and upset conditions, with lower utilization rates than continuous process applications.
Oil Refineries account for the greatest installed capacity. Renewable Energy Producers are gaining share fastest from biogas infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors North American demand through its dense concentration of refineries and ethylene crackers. Pipeline networks connecting Permian Basin production to Texas processing hubs concentrate combustion hardware procurement decisions in Houston and Beaumont.
United States
EPA flare management rules mandate 98% destruction removal efficiency with continuous monitoring verification. Refinery operators in Texas and Louisiana face compressed payback periods for combustion hardware upgrades. The Houston Ship Channel corridor drives replacement cycles as Marathon Petroleum and Valero facilities modernize emission control assets.
Germany
The EU Industrial Emissions Directive and F-Gas Regulation create compliance obligations for chemical manufacturers along the Rhine corridor. BASF and Bayer facilities in Ludwigshafen and Leverkusen specify enclosed flares for volatile organic compound destruction. The country's process safety standards exceed baseline EU requirements for combustion system redundancy.
China
MEE emission standards for petroleum refining tighten destruction efficiency requirements in Shandong and Liaoning provinces. Sinopec operates the largest installed base of thermal flares across its Jinan and Dalian refineries. The Yangtze River Delta petrochemical cluster attracts domestic fabrication capacity for steam-assisted systems.
Saudi Arabia
SABIC's Jubail Industrial City complex generates concentrated demand for high-capacity combustion systems. The country's national petroleum regulator enforces flare minimization protocols across upstream and downstream assets. Ras Tanura refinery expansion projects specify enclosed flares for new hydrotreating unit vent streams.
India
Reliance Industries' Jamnagar refinery drives specialized engineering requirements for high-volume routine venting. The Central Pollution Control Board mandates smokeless combustion for refinery flares above specified throughput thresholds. Gujarat's Dahej petrochemical zone attracts investment in air-assisted flare systems for water-scarce installations.
Enclosed Waste Gas Flares Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in burner tip and refractory supply. The vendor base organizes around three strategic archetypes: full-service combustion houses with in-house fabrication, specialized engineering consultancies with licensed manufacturing partnerships, and regional fabricators competing on delivery speed. Consolidation pressure intensifies as integrated service contracts favor single-source accountability over fragmented procurement. Technology licensing agreements and backward integration into sensor networks represent the dominant competitive moves.
Among Oklahoma and Texas-based combustion houses, John Zink and Zeeco occupy positions as full-service platform providers. Cimarron Energy exemplifies the mid-tier specialist archetype with extended service reach across upstream and midstream retrofit markets. These three anchors illustrate how geographic concentration of engineering talent in the south-central United States shapes competitive positioning.
| Leading Market Players |
|---|
| John Zink |
| Zeeco |
| Cimarron Energy |
| AEREON |
| Varec Biogas |
| Parnel Biogas |
| Eneraque |
| Combustion Research Associates |
| GBA Flare |
| Others |
Pricing and Supply Chain Analysis
Houston Ship Channel freight corridors carry high-nickel alloy shipments from domestic mills to Gulf Coast fabrication yards, concentrating supply-side leverage among Oklahoma and Texas-based combustion houses. This logistics chokepoint amplifies price differentiation between premium engineered systems and commodity thermal flares.
Pricing Analysis
Volume-discount tiering structures separate premium EPA-compliant systems with continuous monitoring verification from standard thermal flares and economy-grade retrofits for legacy infrastructure. Price differentiation hinges on destruction efficiency certification levels and after-sales service bundling. Pricing pressure stems from volatile nickel alloy commodity costs compressing margins on fixed-price project contracts. Renewable energy producers exhibit highest price sensitivity due to modular procurement budgets, while integrated refineries prioritize performance guarantees over capital cost minimization.
Supply Chain Analysis
Export-control regimes on advanced combustion modeling software and optical sensor technologies limit technology transfer to certain fabrication markets, concentrating high-end system production in the United States, Germany, and Japan. Raw material dependencies center on high-nickel stainless steels, refractory ceramics, and precision burner tip alloys. Supply chain risk manifests in single-source vulnerability for specialized engineering talent clustered in south-central US metro areas. Distribution runs through direct OEM relationships with refinery operators and EPC contractors for greenfield petrochemical projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combustion engineering expertise is retiring faster than training pipelines replenish, creating a capability scarcity that rewards firms controlling specialized talent and proprietary burner design IP.
For Market Incumbents: Build switching-cost moats through integrated service contracts bundling hardware, installation, and predictive maintenance under multi-year single-source accountability. Deepen backward integration into sensor networks and IoT platforms to capture recurring revenue attachment. Defensive consolidation should target regional fabricators with established refinery relationships before flare gas recovery economics improve further. For New Entrants and Emerging Players: Establish a beachhead in landfill gas management and biogas plant applications where procurement sophistication lags refining and petrochemical standards. White-space opportunities concentrate in water-scarce regions requiring air-assisted flare systems without steam infrastructure. A rapid-deployment modular product architecture with standardized field commissioning protocols offers the clearest go-to-market angle against entrenched full-service providers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized combustion divisions lacking standalone scale. Long-term viability favors platform integrators with captive engineering talent and digital service capabilities over component specialists facing margin compression. The signal to watch is EPA enforcement intensity on continuous monitoring verification requirements, which would accelerate replacement cycles and consolidate procurement toward single-source accountable suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Networks | Captive supply of IoT hardware enables performance-based service contracting with Louisiana refineries facing EPA verification mandates. |
| Digital Twin Platform Development | Computational fluid dynamics convergence with real-time sensor data creates recurring revenue streams beyond equipment sales. |
| Specialized Engineering Talent Acquisition | Combustion system design expertise in Oklahoma and Texas metro areas commands premium positioning as project timelines stretch. |
| Modular System Architecture for Biogas | Standardized rapid-deployment designs penetrate renewable energy producer segments with compressed procurement cycles. |
| Integrated Service Contract Expansion | Single-source accountability structures reduce interface risk for Gulf Coast operators during turnaround periods. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery reliability directors, EPC contractor procurement leads, combustion engineering consultants, and aftermarket service managers. Secondary validation drew from EPA enforcement databases, FERC filing records, EIA refinery capacity reports, and SEC 10-K disclosures from disclosed petroleum processing operators. Bottom-up unit economics triangulated against top-down sector spend estimates to anchor volume and value projections.
Calibration against historical replacement cycles and regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include combustion technology type, application environment, end-user procurement sophistication, and regional regulatory enforcement intensity. CAGRs were derived from installed base depreciation schedules and greenfield capacity addition pipelines. Industry-specific forecast inputs incorporated flare gas recovery economics sensitivity and carbon credit pricing mechanism evolution.
Macroeconomic conditions sit as an overlay; deviation in nickel alloy commodity pricing, refinery utilization rates, or Permian Basin production investment would shift the trajectory. Forecasts reflect documented assumptions on EPA enforcement continuity and OSHA process safety alignment timelines. Material shifts in flare gas recovery technology cost curves or carbon offset valuation regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.