
 Electric Vehicle Grid Integration Solutions Market | 2026-2036
Electric Vehicle Grid Integration Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Grid Integration Solutions Market Insights
ISO 15118-20 certification for bidirectional power transfer is collapsing the supplier landscape to firms with embedded automotive and utility expertise. Tesla leverages its proprietary Supercharger network and energy software stack to anchor integrated home-grid-fleet offerings. ABB Ltd. competes through high-power charging hardware and grid-tied inverter systems for commercial depots. EDF Group sustains its position via utility-scale aggregation platforms that pool distributed EV assets across European markets.
Electric vehicle grid integration solutions encompass bidirectional power electronics, communication protocols, and software platforms that synchronize EV battery dispatch with grid frequency regulation and peak load balancing. These systems operate across AC and DC coupling architectures, with power ratings from 7 kW residential units to 350 kW fleet hubs, enabling real-time telemetry between vehicles, chargers, and distribution network operators. Vehicle-to-Grid technology leads deployment in pilot markets but faces margin pressure from hardware commoditization, while Energy Management Systems capture expanding software recurring revenue as utilities seek virtual power plant orchestration. Smart Charging dominates residential and commercial installation volumes where dynamic load management prevents distribution transformer overload.
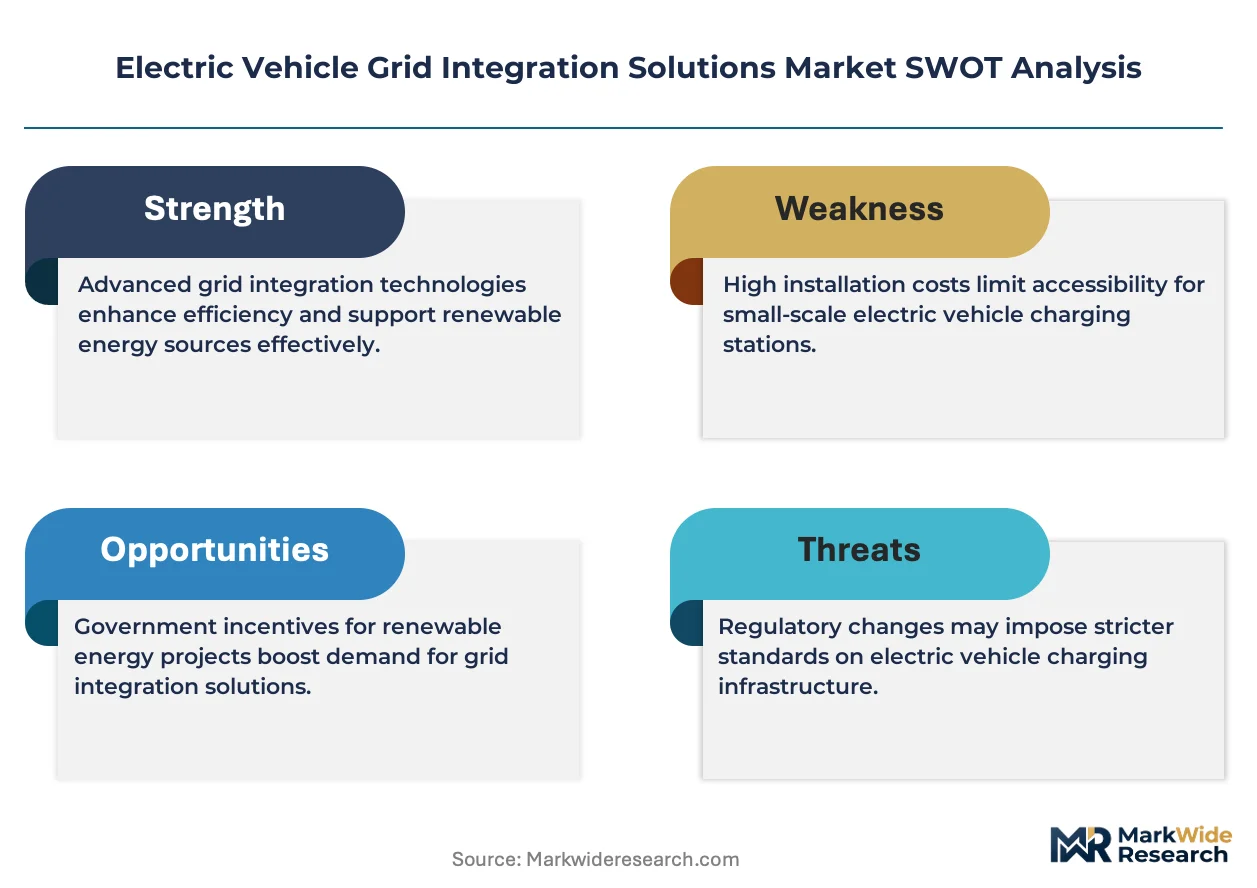
FERC Order 2222 in the United States enables aggregated distributed energy resources to participate in wholesale markets, directly expanding revenue streams for EV fleet integrators. The EU Green Deal and national implementation frameworks under the Clean Energy Package mandate interoperability standards that shape product roadmaps across the value chain. China's GB/T standards and dual carbon goals from MEE accelerate domestic bidirectional charging deployment while creating export compliance requirements for foreign suppliers. Stakeholders must monitor how evolving grid codes in multiple jurisdictions redefine certification burdens and first-mover advantages.
Market Dynamics
ISO 15118-20 certification requirements for bidirectional power transfer are compressing the supplier base toward firms possessing simultaneous automotive and utility domain expertise, fundamentally restructuring competitive entry barriers.
Growth Catalysts
- California's Title 24 building codes:Mandates for EV-ready infrastructure in new construction are accelerating residential bidirectional charger pre-installation across the state.
- Fleet electrification mandates:Corporate sustainability commitments and municipal procurement rules are scaling vehicle-to-grid pilots in commercial depot configurations.
- Utility-backed aggregation platforms:Germany's distribution network operators are maturing virtual power plant models that pool distributed EV assets for frequency regulation services.
Market Restraints
- Silicon carbide semiconductor supply concentration:Power electronics manufacturers face input cost volatility from limited qualified substrate suppliers concentrated in East Asian foundries.
- F-Gas Regulation compliance friction:The EU's phasedown of fluorinated greenhouse gases is forcing thermal management redesigns in high-power charging systems.
- AC coupling technical ceiling:Residential bidirectional systems face inherent power limitations that constrain grid services revenue potential versus DC architectures.
Strategic Opportunities
- FERC Order 2222 implementation:Wholesale market participation rules for aggregated distributed energy resources are opening revenue streams for EV fleet integrators in US organized markets.
- Vehicle-to-home emergency backup:Grid resilience concerns are driving consumer willingness to pay for bidirectional capability as a premium feature in residential segments.
- China's dual carbon goals:MEE directives and GB/T standard evolution are creating compliance requirements that favor suppliers with domestic certification capabilities.
Industry Challenges
- Embedded software talent scarcity:Real-time grid communication protocol development requires power systems engineers with automotive cybersecurity expertise, a skill intersection in short supply.
- Multi-jurisdiction certification timelines:Divergent grid code requirements across US ISOs, EU member states, and Chinese provinces are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Grid Integration Solutions Market |
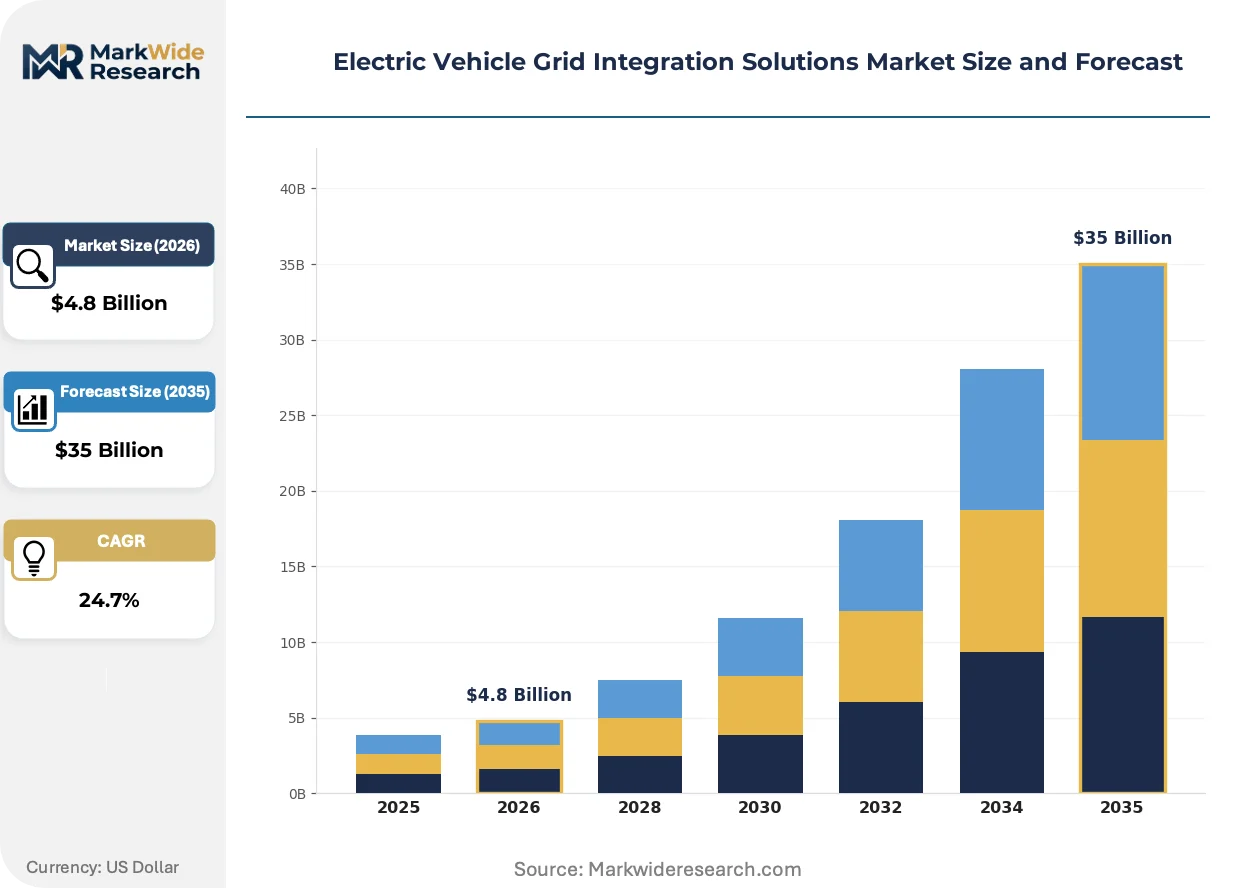
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vehicle-to-Grid, Smart Charging, Bidirectional Charging, Dynamic Load Management Product Type: Charging Stations, Inverters, Energy Management Systems, Communication Interfaces End User: Fleet Operators, Utilities, Commercial Buildings, Residential Users Service Type: Installation, Maintenance, Consulting, Software Development |
| Companies Covered | Nuvve Corporation, Nissan Motor Corporation, EDF Group, Enel X, Tesla Inc., BMW Group, Hyundai Motor Company, Renault Group, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Grid Integration Solutions Market Trends and Innovations
Technology convergence between automotive power electronics and utility-scale inverter design is dissolving traditional sector boundaries, while regulatory pressure on interoperability is forcing open-architecture investments.
Silicon carbide MOSFETs in 800V architectures are supplanting silicon IGBTs in high-power charging hardware. Tier-1 automotive suppliers are adopting these devices for 350kW fleet hubs, compressing thermal management costs and enabling compact form factors that reduce installation footprint in urban depots.
The EU's F-Gas Regulation is accelerating natural refrigerant adoption in charging system thermal management. Equipment manufacturers are redesigning cooling loops to accommodate CO2 and propane alternatives, with commercial depot installations in Germany and the Netherlands facing the earliest compliance deadlines.
Fleet operators are consolidating procurement around energy-as-a-service contracts that unbundle hardware ownership from grid revenue participation. This model transfers capital burden to integrators while capturing ongoing software fees, with California municipal fleets and European logistics operators leading contract restructuring.
Electric Vehicle Grid Integration Solutions Market Segmentation
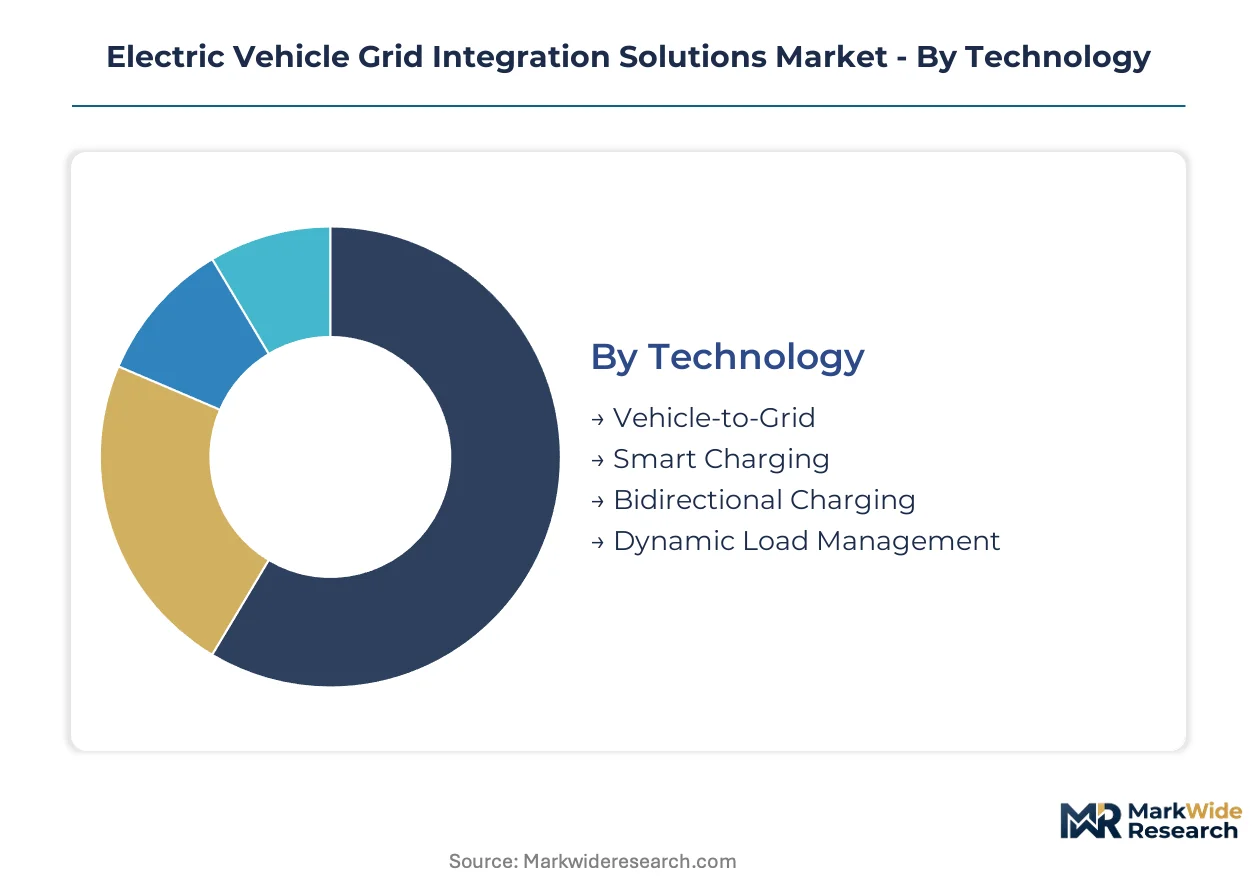
Segmentation in electric vehicle grid integration solutions reveals how hardware commoditization pressures and software value capture split across distinct technology-product-service combinations. Understanding these divisions exposes where margin pools concentrate versus where volume scales.
Technology:
Smart Charging and Vehicle-to-Grid solutions flow primarily through utility procurement channels and fleet integrators, while Dynamic Load Management and Bidirectional Charging penetrate via commercial depot operators and residential installer networks.
- Smart Charging:Systems that modulate charging rates based on grid conditions, tariff signals, and local load constraints. Demand concentrates in California municipal fleets and German distribution network operator programs where dynamic load management prevents transformer overload during evening peaks.
- Vehicle-to-Grid:Bidirectional power transfer enabling EV batteries to discharge into grid infrastructure. Fleet operators in the Netherlands and Denmark are scaling pilot deployments where ISO 15118-20 certification unlocks frequency regulation revenue streams.
- Bidirectional Charging:Hardware enabling AC or DC power flow in both directions. Residential markets in Japan and South Korea show willingness-to-pay premiums for emergency backup capability.
- Dynamic Load Management:Software-controlled power distribution across multiple charging points. Commercial building operators in France deploy these systems to avoid demand charge penalties.
Smart Charging dominates installed base. Vehicle-to-Grid is where expansion concentrates.
Product Type:
Cost tier stratification separates premium DC fast-charging hardware from commoditized AC residential units, with software platforms capturing recurring revenue independent of equipment margins.
- Charging Stations:AC and DC hardware ranging from 7 kW residential wallboxes to 350 kW fleet hubs. Silicon carbide MOSFETs in 800V architectures are displacing silicon IGBTs in high-power units, compressing thermal management costs for urban depot installations.
- Energy Management Systems:Software platforms orchestrating distributed EV assets as virtual power plants. These systems capture expanding recurring revenue as European utilities seek aggregation capabilities under EU Green Deal frameworks.
- Inverters:Grid-tied power electronics converting DC battery output to AC grid-synchronized power. Supply concentrates among firms with simultaneous automotive and utility domain expertise.
- Communication Interfaces:Protocol hardware and middleware enabling ISO 15118-20, OCPP, and utility-specific telemetry standards. F-Gas Regulation compliance is forcing thermal management redesigns in high-power configurations.
Charging Stations dominate installed base. Energy Management Systems is where expansion concentrates.
End User:
Customer type determines contract structure, with fleet operators consolidating around energy-as-a-service models while residential users purchase hardware outright through installer channels.
- Fleet Operators:Commercial and municipal vehicle operators managing depot-based charging at scale. These customers are restructuring procurement around contracts that unbundle hardware ownership from grid revenue participation, transferring capital burden to integrators.
- Utilities:Distribution network operators and load-serving entities aggregating distributed EV assets. Germany's DSOs are maturing virtual power plant models that pool EV batteries for frequency regulation services.
- Commercial Buildings:Property owners and facility managers installing workplace and retail charging. California Title 24 building codes mandate EV-ready infrastructure in new construction, accelerating pre-installation across the state.
- Residential Users:Individual EV owners installing home charging with or without bidirectional capability. Grid resilience concerns are driving willingness-to-pay premiums for vehicle-to-home backup functionality.
Fleet Operators dominate installed base. Utilities is where expansion concentrates.
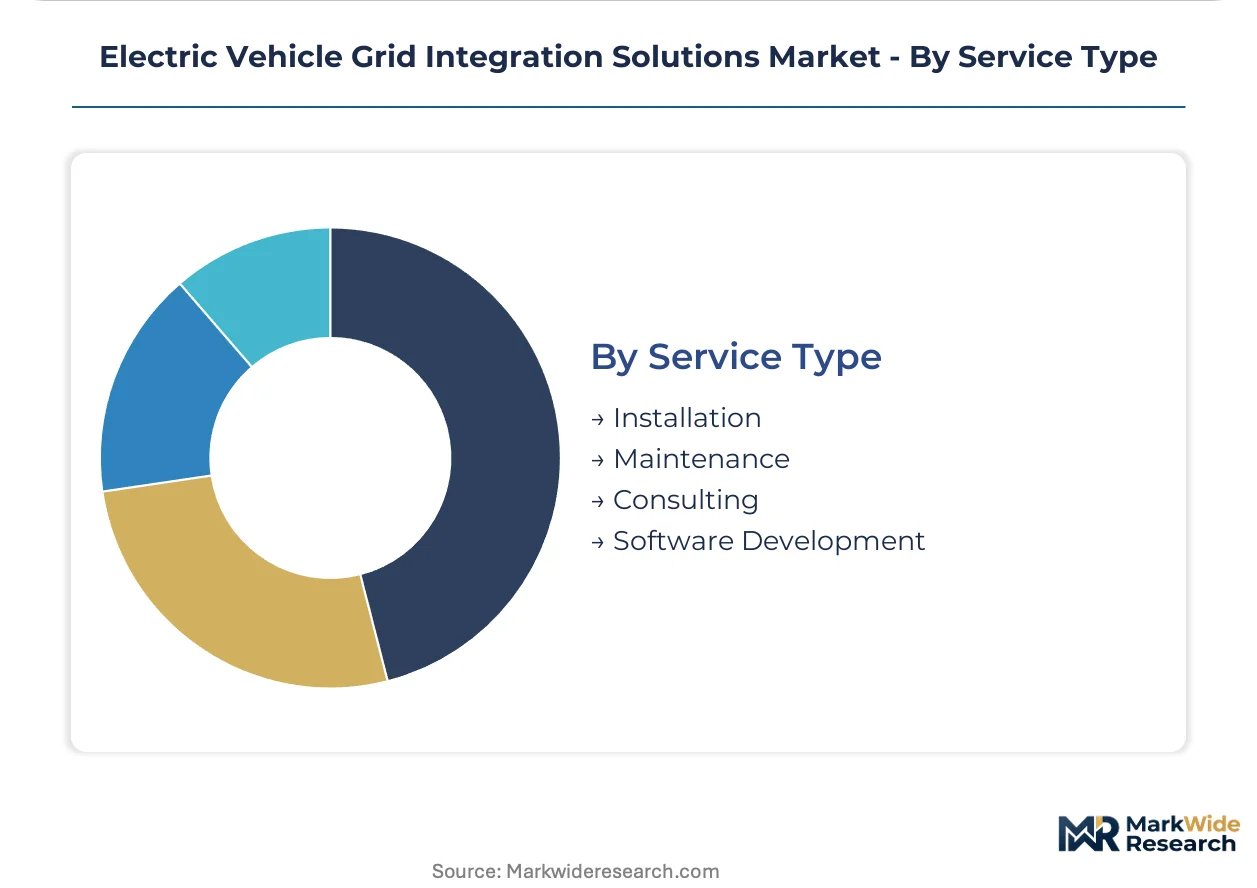
Service Type:
Maturity gradients separate established installation and maintenance services from emerging software development and consulting offerings that scale with grid integration complexity.
- Software Development:Custom platform engineering for utility telemetry, fleet management, and grid communication protocols. Real-time grid communication development requires power systems engineers with automotive cybersecurity expertise, a skill intersection in short supply.
- Installation:Electrical contracting for charger deployment, grid interconnection, and permitting compliance. Volume scales with residential and commercial construction activity subject to building code mandates.
- Maintenance:Preventive and corrective service for charging hardware and power electronics. F-Gas Regulation phasedown is forcing thermal management system redesigns that alter service requirements.
- Consulting:Grid integration strategy, regulatory navigation, and revenue optimization advisory. FERC Order 2222 implementation is opening wholesale market participation rules that require specialized guidance.
Installation dominates installed base. Software Development is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and utilities concentrate procurement in Germany, the United States, and China, with secondary demand clusters emerging in Japan and the Netherlands where vehicle-to-grid pilots scale fastest.
United States
California's Title 24 building codes mandate EV-ready infrastructure in new construction, accelerating residential bidirectional charger pre-installation. FERC Order 2222 enables aggregated distributed energy resources to participate in wholesale markets, expanding revenue streams for fleet integrators. The San Francisco Bay Area hosts the densest concentration of vehicle-to-grid pilot deployments among municipal fleets.
Germany
Distribution network operators mature virtual power plant models that pool distributed EV assets for frequency regulation services. The EU F-Gas Regulation forces thermal management redesigns in high-power charging systems ahead of phasedown deadlines. Industrial clusters in North Rhine-Westphalia concentrate utility-backed aggregation platform development.
China
MEE dual carbon goals and evolving GB/T standards accelerate domestic bidirectional charging deployment while creating export compliance requirements for foreign suppliers. State Grid Corporation pilots vehicle-to-grid aggregation at scale in megacity demonstration zones. The Yangtze River Delta region dominates silicon carbide semiconductor foundry capacity for power electronics.
Japan
METI regulations and disaster resilience priorities drive consumer willingness-to-pay premiums for vehicle-to-home emergency backup capability. CHAdeMO protocol heritage creates installed base advantages for bidirectional hardware deployment. Tokyo metropolitan area utilities lead residential aggregation pilot programs.
Netherlands
Enexis and Stedin distribution system operators scale vehicle-to-grid frequency regulation contracts with commercial fleet operators. EU Green Deal implementation frameworks mandate interoperability standards that shape product roadmaps. The Rotterdam-The Hague corridor concentrates high-power charging hub deployment for European logistics operators.
Electric Vehicle Grid Integration Solutions Market Competitive Landscape
Player mix skews toward automotive incumbents with captive vehicle fleets and utility-backed energy platforms with grid orchestration expertise. Market structure concentrates around firms possessing simultaneous ISO 15118-20 certification capabilities and utility telemetry integration experience. Three archetypes dominate: integrated automaker-energy divisions, power electronics specialists with automotive heritage, and utility-scale virtual power plant operators. Competitive moves center on energy-as-a-service contract restructuring and silicon carbide supply chain captive arrangements.
Within the integrated automaker tier, Tesla Inc. and Nissan Motor Corporation exemplify players leveraging proprietary charging networks and vehicle fleet scale to anchor home-grid-fleet offerings. Among utility-backed platform operators, EDF Group and Enel X occupy positions shaped by European regulatory frameworks for distributed energy resource aggregation. Power electronics specialists include ABB Ltd., representing firms with embedded grid-tied inverter and high-power charging hardware capabilities.
| Leading Market Players |
|---|
| Nuvve Corporation |
| Nissan Motor Corporation |
| EDF Group |
| Enel X |
| Tesla Inc. |
| BMW Group |
| Hyundai Motor Company |
| Renault Group |
| ABB Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with silicon carbide substrate suppliers lock in both supply access and price visibility for power electronics manufacturers, insulating qualified vendors from spot-market volatility while anchoring cost structures for fleet-scale charging deployments.
Pricing Analysis
Cost-plus contracts indexed to silicon carbide wafer pricing dominate high-power charging hardware procurement. Three-tier pricing structure across ISO 15118-20 certified, utility-integrated, and basic residential units separates premium fleet hubs from standard commercial depots and economy residential wallboxes. Cost compression in residential AC bidirectional systems is intensifying because hardware commoditization outpaces software value capture. Fleet operators show least price sensitivity due to energy-as-a-service contract structures, while residential installers face maximum pressure from consumer willingness-to-pay ceilings.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates and power semiconductor inventory prevails over just-in-time approaches, reflecting supply concentration risk and long qualification cycles for automotive-grade components. Manufacturing concentrates in China, South Korea, and Germany, drawing from Japanese silicon carbide wafer suppliers and Taiwanese foundry capacity. Supply chain risk centers on single-source vulnerability for 800V-rated MOSFET devices. Distribution runs through Tier 1 automotive suppliers and utility procurement channels with extended qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation around energy-as-a-service contracts shifts negotiating power toward large-scale buyers, fragmenting the integrator landscape and compressing margins for undifferentiated hardware vendors.
For Market Incumbents: Fortify positions through captive silicon carbide supply arrangements and ISO 15118-20 certification acceleration. Embedded software talent scarcity threatens competitive differentiation; vertical integration into grid-tied inverter design preserves margin pools against automotive supplier encroachment. Utility telemetry integration experience remains the critical lever for platform stickiness. For New Entrants and Emerging Players: Differentiate on automotive cybersecurity protocol expertise and German DSO aggregation platform compatibility. Vehicle-to-home residential segments in Japan and California present the most penetrable white space, with emergency backup functionality commanding premium positioning. Target municipal fleet pilot programs with turnkey hardware-software bundles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among utility-backed virtual power plant operators with established grid orchestration contracts. Long-term viability favors firms with simultaneous automotive OEM relationships and distribution network operator telemetry integration. Watch FERC Order 2222 implementation depth across US ISOs as inflection indicator for market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Captivity | Backward integration into substrate sourcing secures qualified supply for 800V fleet charging hardware against East Asian foundry concentration. |
| ISO 15118-20 Certification Acceleration | Early compliance unlocks bidirectional revenue streams in Netherlands and Denmark frequency regulation markets. |
| Utility Aggregation Platform Partnership | EDF and Enel X channel relationships provide virtual power plant orchestration access across EU Green Deal frameworks. |
| Energy-as-a-Service Contract Restructuring | Unbundled hardware-software models transfer capital burden while capturing recurring fees from California municipal fleets. |
| F-Gas Regulation Thermal Redesign | CO2 cooling loop adoption preserves German and Netherlands commercial depot market access ahead of compliance deadlines. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with utility planning officers, fleet procurement directors, power electronics engineers, and automotive platform architects; and secondary validation through FERC filings, EIA distributed resource databases, EU Clean Energy Package implementation documents, and State Grid Corporation pilot disclosures. Bottom-up installation forecasts triangulated against top-down utility capital expenditure projections.
Across the projection horizon, the analytical framework modeled technology adoption curves, product type cost tier evolution, end-user contract structure migration, and service type margin pool shifts. CAGRs derived from segment-level growth rate synthesis against regulatory mandate timelines and infrastructure deployment schedules. Silicon carbide device cost curves and ISO 15118-20 certification penetration rates served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FERC Order 2222 implementation, EU F-Gas Regulation enforcement continuity, or China GB/T standard evolution would require recalibration. Forecasts reflect assumptions regarding fleet electrification mandate adherence and utility procurement cycle stability. Revision becomes warranted when silicon carbide substrate supply constraints or multi-jurisdiction certification timeline divergence cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market