
 Yankauer Suction Tips Market | 2026-2036
Yankauer Suction Tips Market Size, Share, and Industry Trends Forecast 2026-2036
Yankauer Suction Tips Market Intelligence
Malaysia is narrowing its position as a cost-competitive manufacturing base for disposable suction instrumentation, drawing contract orders from multinational distributors. Cardinal Health leverages integrated hospital supply contracts to sustain volume throughput across North American acute care networks. Medtronic anchors its portfolio through R&D intensity in ergonomically optimized suction handle designs. Pennine Healthcare competes on specialized pediatric tip configurations for neonatal intensive care applications.
Yankauer suction tips are rigid, curved or straight oral suction instruments typically manufactured from polypropylene or PVC, featuring a large opening with a bulbous or vented tip designed to prevent tissue aspiration during oropharyngeal and tracheal suctioning procedures. Standard polypropylene tips dominate hospital procurement due to favorable unit economics and sterilization compatibility, while ventilated variants command premium positioning in emergency medicine where occlusion resistance proves critical. Silicone material adoption is gaining traction in pediatric and home care segments where biocompatibility and reduced mucosal trauma drive clinician preference.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while EU MDR technical documentation and clinical evaluation obligations extend conformity assessment timelines for European market access. ISO 13485 quality management certification has become a baseline procurement filter for hospital group purchasing organizations evaluating supplier qualification. Stakeholders must monitor evolving single-use plastic regulations across multiple jurisdictions, as material substitution mandates could force reformulation of conventional polypropylene tip construction.
Market Dynamics
Hospital procurement consolidation across the United States is compressing supplier margins and forcing volume commitments that favor disposable suction device manufacturers with integrated logistics networks. This buyer concentration is restructuring competitive positioning away from fragmented regional distributors toward national contract holders.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volume in United States freestanding surgery centers is accelerating demand for single-use suction instrumentation with streamlined turnover protocols.
- EU MDR technical documentation requirements:Extended conformity assessment timelines for reusable device reprocessing are tilting hospital procurement toward pre-sterilized disposable alternatives.
- Silicone material biocompatibility:Reduced mucosal trauma properties are driving clinician preference shifts in pediatric and home care segments where tissue preservation priorities dominate.
Market Restraints
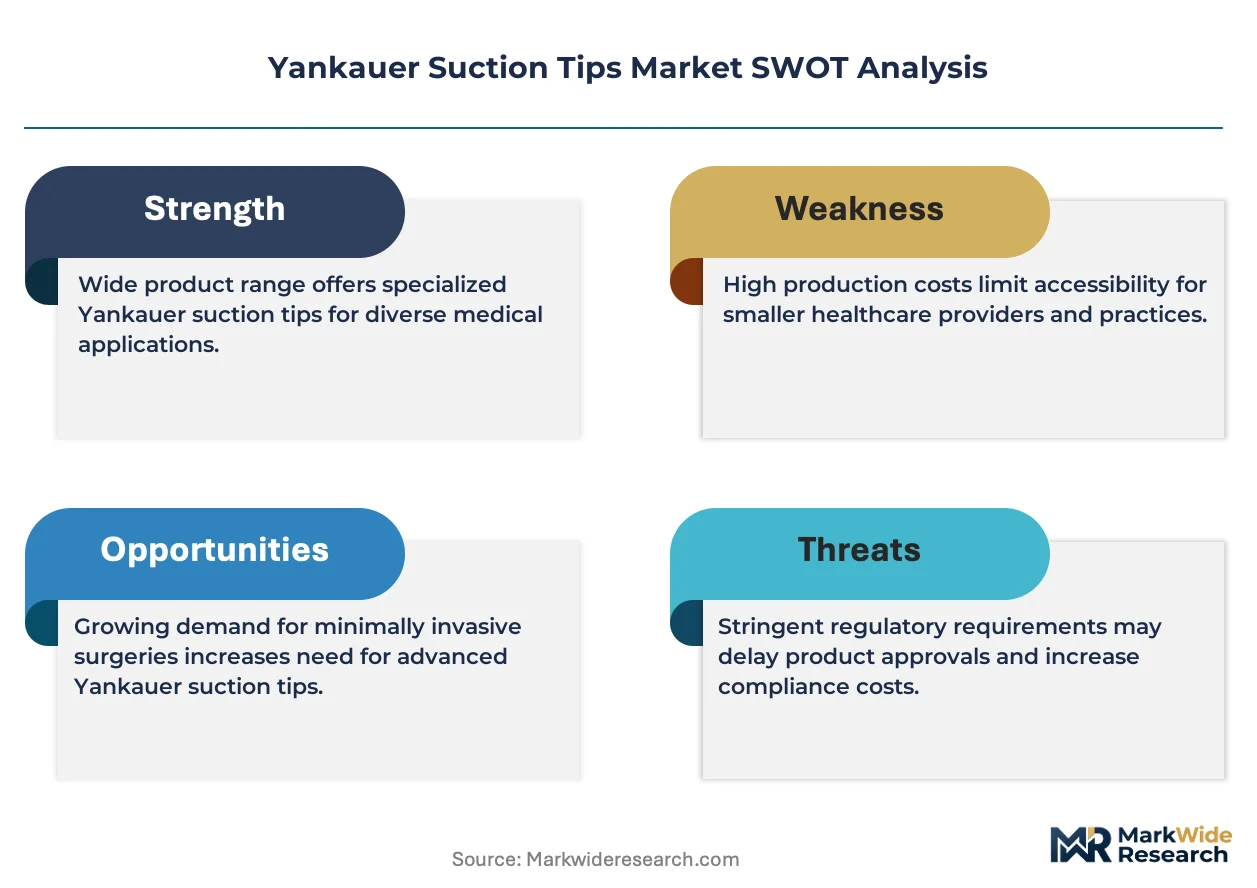
- Polypropylene feedstock volatility:Crude oil derivative price swings directly impact tip manufacturing economics and margin stability for molded disposable producers.
- Single-use plastic regulatory mandates:France's AGEC law and similar extended producer responsibility frameworks in Germany are forcing material reformulation investments without immediate cost recovery mechanisms.
- Reusable suction system substitution:Stainless steel Yankauer alternatives with validated sterilization cycles retain foothold in cost-constrained public hospital systems.
Strategic Opportunities
- Home respiratory care penetration:Tracheostomy patient discharge protocols in the United States are creating demand for retail-channel suction tip distribution.
- ISO 13485 certification arbitrage:Malaysian contract manufacturers are capturing original equipment manufacturer orders from multinational distributors seeking dual-source qualification.
- Emergency medicine ventilated tip premiumization:Occlusion-resistant bulbous designs command pricing power in ambulance and trauma bay applications where aspiration failure carries liability exposure.
Industry Challenges
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for ergonomic handle modifications require clinical data investments that strain mid-tier manufacturer R&D budgets.
- Supply chain reconfiguration friction:Reliance on Malaysian injection molding capacity creates logistics complexity for North American distributors managing just-in-time hospital inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yankauer Suction Tips Market |
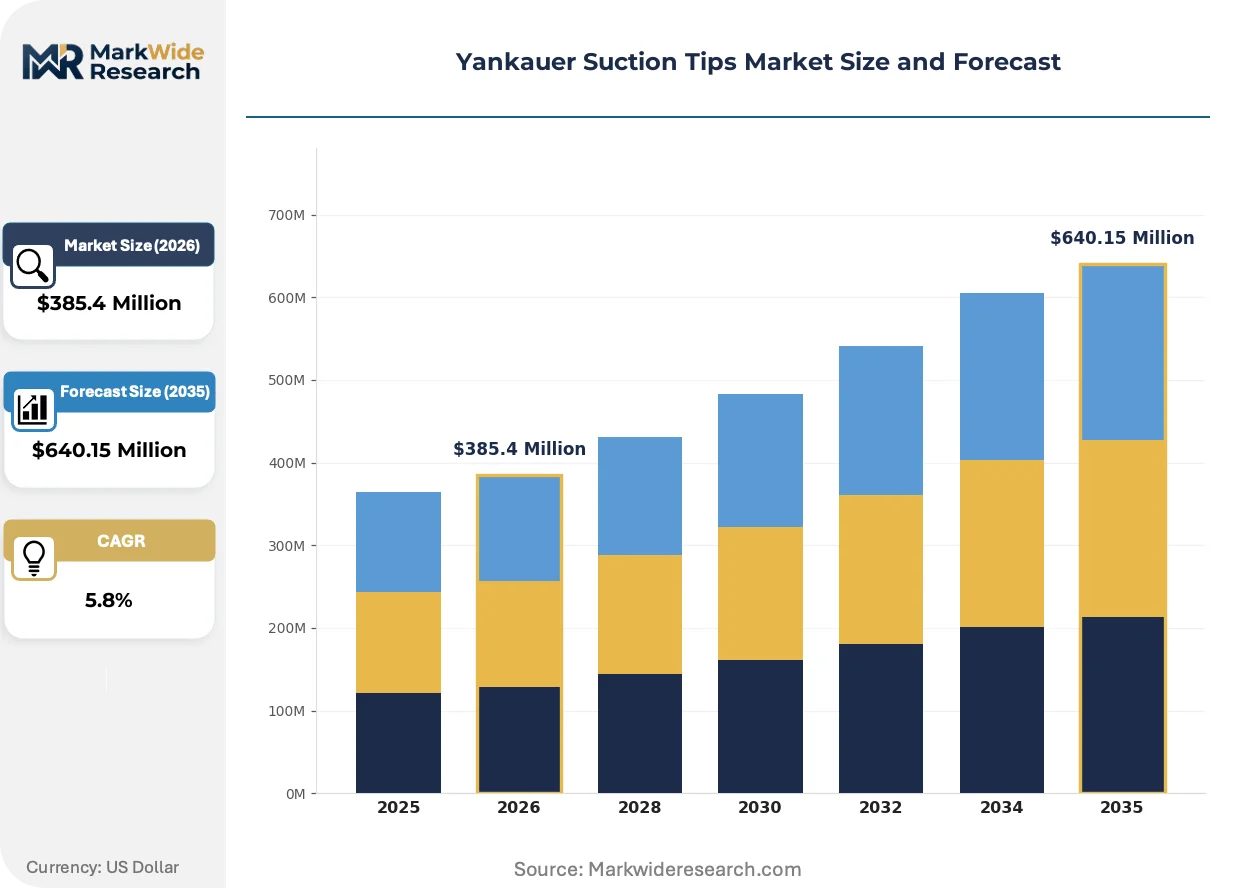
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tips, Ventilated Tips, Multi-Use Tips, Pediatric Tips Material: Polypropylene, PVC, Rubber, Silicone End User: Hospitals, Surgical Centers, Clinics, Home Care Application: Suctioning, Drainage, Emergency Procedures, Routine Care |
| Companies Covered | Cardinal Health, Conmed Corporation, Medtronic, Medline Industries, Mckesson, Pennine Healthcare, AliMed, ConvaTec Group, Flexicare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yankauer Suction Tips Market Strategic Shifts & Innovations
Material science advances and regulatory complexity are compressing traditional product lifecycles while opening differentiation pathways beyond commodity polypropylene construction. These forces are reshaping how suction instrumentation is specified, procured, and consumed across acute and non-acute settings.
Silicone-tipped Yankauer variants are collapsing the historical trade-off between rigidity and tissue safety in oropharyngeal suctioning. Neonatal intensive care units in tertiary United States hospitals are adopting these instruments at accelerating rates. The technology is collapsing competitive differentiation around trauma prevention and enabling premium positioning in pediatric segments previously served by standard polypropylene.
EU MDR clinical evaluation obligations are extending device registration timelines and documentation burdens for European market access. Manufacturers must now generate clinical evidence or systematic literature reviews for suction tip modifications previously cleared through predicate equivalence. Emergency medicine product lines face the steepest compliance cost escalation as notified bodies scrutinize ventilated tip performance claims.
Hospital group purchasing organization consolidation is compressing vendor panels and elongating contract renewal cycles. Integrated delivery networks in the United States are replacing fragmented department-level purchasing with centralized supply chain governance. This concentration is most visible in multi-hospital systems across Texas and Florida where Cardinal Health and Medline contract penetration has displaced independent distributor relationships.
Yankauer Suction Tips Market Segmentation
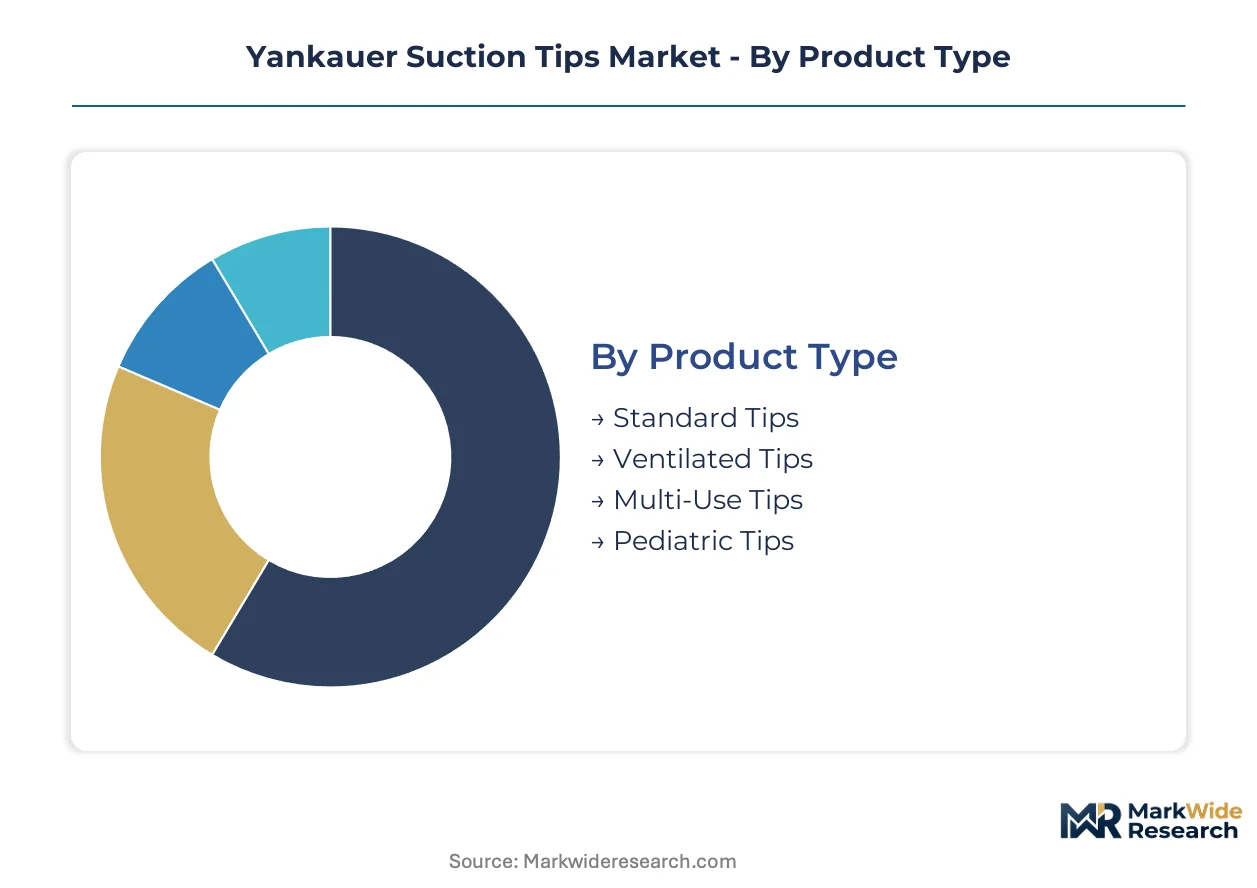
Segmentation in the Yankauer Suction Tips Market reveals distinct procurement patterns across material grades, clinical settings, and patient populations. Hospital supply chains negotiate separate contracts for standard polypropylene bulk orders versus premium silicone configurations, while ambulatory sites prioritize single-use disposables over multi-use alternatives.
Product Type:
Application urgency separates the four product configurations, with emergency medicine driving specification divergence from routine care protocols.
- Standard Tips:Non-ventilated rigid polypropylene instruments dominate hospital central supply procurement for general oropharyngeal suctioning. United States acute care networks specify these for operating room turnover efficiency where unit cost compression outweighs occlusion resistance requirements.
- Ventilated Tips:Bulbous or side-ported designs prevent tissue aspiration during high-volume fluid evacuation in trauma bays and emergency departments. Ambulance services and Level I trauma centers in Texas and Florida mandate these for liability protection against airway occlusion events.
- Multi-Use Tips:Reprocessable stainless steel variants serve cost-constrained public hospital systems with validated sterilization infrastructure.
- Pediatric Tips:Reduced-diameter configurations address neonatal airway anatomy in NICU settings.
Standard tips hold installed capacity. Ventilated tips is rotating up the share rankings.
Material:
Cost tier and biocompatibility performance define the four material options, with feedstock volatility creating margin pressure across petroleum-derived categories.
- Polypropylene:Molded homopolymer construction delivers favorable unit economics and gamma sterilization compatibility for high-volume disposable production. Hospital group purchasing organizations in the United States specify this material for 80-plus percent of suction tip procurement by volume.
- Silicone:Platinum-cured elastomer tips reduce mucosal trauma in pediatric and home care segments where tissue preservation priorities override cost constraints. United States NICU adoption is climbing fastest as liability concerns reshape procurement specifications.
- PVC:Plasticized vinyl compounds serve budget-sensitive clinic environments with lower throughput requirements.
- Rubber:Latex and synthetic elastomer variants persist in legacy reusable system compatibility.
Polypropylene anchors volume throughput. Silicone is gaining share fastest on trauma prevention differentiation.
End User:
Customer type determines packaging, sterilization status, and distribution channel requirements across the care continuum.
- Hospitals:Integrated delivery networks negotiate multi-year contracts for pre-sterilized disposable tips with just-in-time logistics integration. United States health system consolidation favors suppliers with national distribution infrastructure and ISO 13485 certification.
- Surgical Centers:Freestanding ambulatory sites prioritize streamlined turnover protocols and single-use disposables over reprocessing investments. Outpatient procedure volume expansion in United States freestanding surgery centers is accelerating demand for bulk-packaged standard tips.
- Clinics:Lower-acuity settings balance cost constraints against intermittent suctioning needs.
- Home Care:Tracheostomy patient discharge protocols in the United States are creating retail-channel demand for individually packaged sterile tips with patient instruction inserts.
Hospitals hold installed capacity. Surgical centers is rotating up the share rankings.
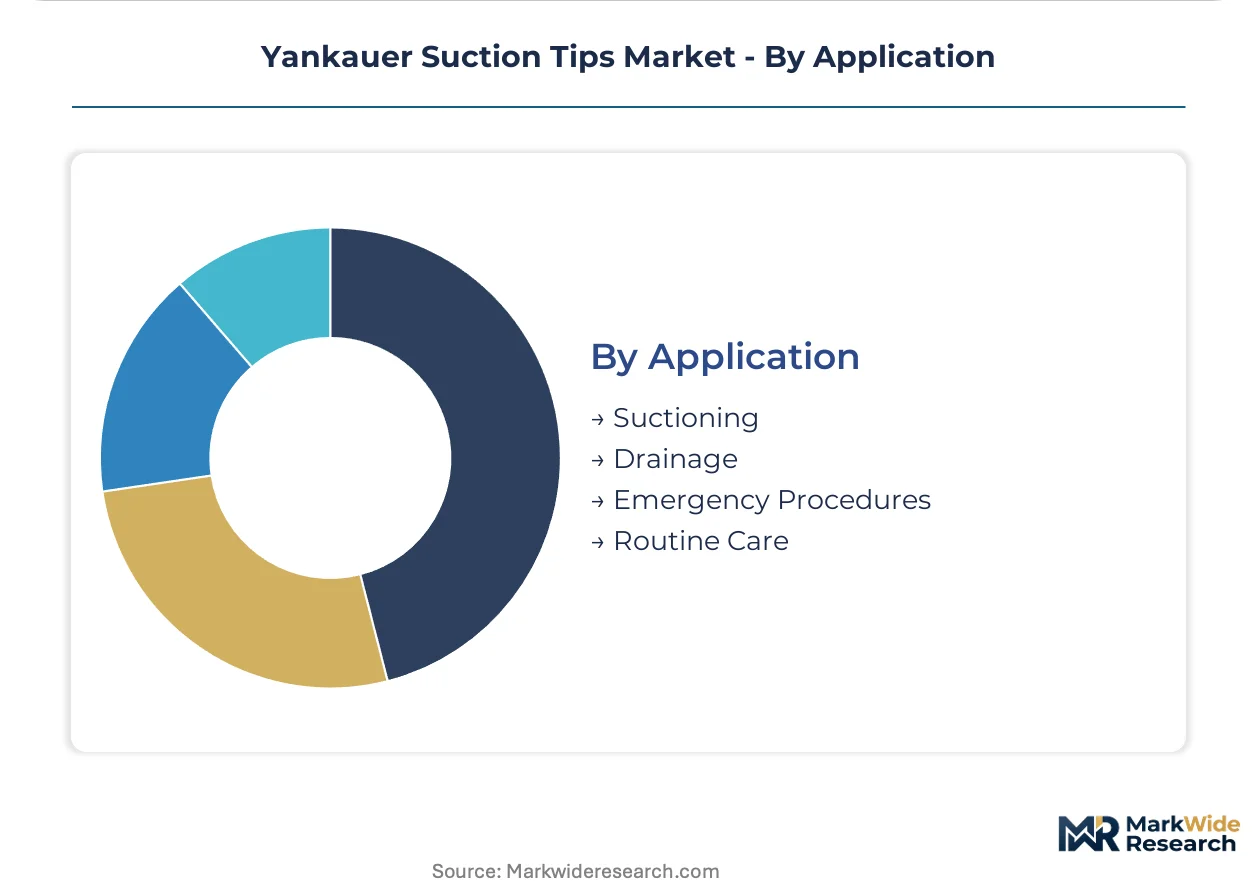
Application:
Clinical context dictates tip specification, with emergency protocols demanding occlusion-resistant designs unavailable in routine care configurations.
- Emergency Procedures:Ventilated bulbous tips command premium positioning in ambulance and trauma applications where aspiration failure carries severe liability exposure. United States EMS system specifications increasingly mandate side-ported designs for airway management protocols.
- Suctioning:Standard oropharyngeal and tracheal evacuation represents the core use case across all care settings. Operating room utilization in United States ambulatory surgical centers is expanding demand for single-use suction devices with rapid turnover compatibility.
- Drainage:Post-operative fluid management applications specify larger-bore tips with enhanced flow rates.
- Routine Care:Scheduled suctioning protocols in long-term acute care hospitals accept non-ventilated standard configurations.
Suctioning holds installed capacity. Emergency procedures is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States establish the regulatory baseline that shapes product validation timelines for manufacturers serving hospital procurement networks across multiple geographies.
United States
Hospital procurement consolidation and ambulatory surgical center expansion drive suction tip demand. FDA 510(k) premarket notification requirements govern device clearance pathways. Texas and Florida health systems concentrate contract awards with national distributors possessing ISO 13485 certification and just-in-time logistics infrastructure.
Germany
EU MDR conformity assessment obligations extend registration timelines for reusable device alternatives. France's AGEC law and extended producer responsibility frameworks force material reformulation investments. The Rhine-Ruhr industrial corridor hosts injection molding capacity serving multinational distributors seeking dual-source qualification.
Malaysia
Contract manufacturing orders from multinational distributors concentrate in cost-competitive production zones. The country's national medical device regulator enforces quality management standards aligned with ISO 13485. Penang and Selangor industrial zones capture original equipment manufacturer orders through certification arbitrage.
United Kingdom
Pediatric and neonatal intensive care applications drive specification divergence toward silicone-tipped variants. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical documentation requirements. Greater Manchester and West Midlands medical device clusters specialize in pediatric tip configurations for export markets.
Japan
PMDA quality management oversight shapes sterilization compatibility requirements for polypropylene disposable production. Aging demographics expand home respiratory care penetration among tracheostomy patients. Osaka-based fabricators supply ergonomic handle designs optimized for clinician hand fatigue reduction.
Yankauer Suction Tips Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where integrated health system contracts favor national distributors while specialized configurations sustain regional niches. Hospital group purchasing organization consolidation compresses vendor panels and elongates contract renewal cycles. Three archetypes dominate: integrated supply chain operators, ergonomic design specialists, and pediatric configuration experts. Competitive moves concentrate on strategic partnerships with contract manufacturers and portfolio diversification into silicone material variants.
Among United States-based integrated distributors, Cardinal Health and Medline Industries exemplify the scale-driven archetype through national contract penetration. Medtronic occupies a position within the R&D-intensive tier, representing ergonomic optimization specialists. Pennine Healthcare sits within the pediatric specialization segment, exemplifying configuration expertise for neonatal intensive care applications.
| Leading Market Players |
|---|
| Cardinal Health |
| Conmed Corporation |
| Medtronic |
| Medline Industries |
| Mckesson |
| Pennine Healthcare |
| AliMed |
| ConvaTec Group |
| Flexicare |
| Others |
Cost & Logistics Intelligence
Polypropylene feedstock volatility tethered to crude oil derivative markets compresses margin stability across molded disposable production while simultaneously widening price spreads between standard and silicone-tipped configurations. This commodity exposure forces manufacturers to absorb cost swings in high-volume contract tiers while transferring premium positioning to biocompatible material variants.
Pricing Analysis
United States hospital procurement contracts command unit economics roughly fifteen percent below European acute care network pricing due to consolidated GPO leverage and just-in-time logistics integration. Three-tier pricing structure across premium silicone, standard polypropylene, and economy PVC levels separates clinical-grade biocompatibility from bulk disposable throughput. Pricing pressure stems from Malaysian contract manufacturers capturing OEM orders through ISO 13485 certification arbitrage. Surgical centers exhibit highest price sensitivity as turnover protocol efficiency overrides material performance specifications.
Supply Chain Analysis
Extended payment terms from United States integrated delivery networks now stretch ninety to one hundred twenty days, forcing mid-tier manufacturers toward supply-chain finance facilities anchored by distributor credit lines. Production gravity centers on Malaysia, China, and Germany with Penang injection molding capacity serving North American distributor dual-qualification strategies. Raw material flows draw from Saudi petrochemical feedstocks, German polymer compounding, and Japanese platinum-cured silicone elastomers. Single-source vulnerability concentrates in Malaysian port logistics handling gamma-sterilized disposable export volumes. Distribution runs through Cardinal Health and Medline national warehouse networks with hospital dock-direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement digitization and GPO platform consolidation are reconstituting Yankauer suction tips as interoperable supply-chain SKUs within integrated delivery network ecosystems rather than standalone disposable instruments.
For Market Incumbents: Harden contract renewal positioning through backward integration into Malaysian injection molding capacity and captive silicone compounding partnerships that insulate against feedstock volatility. FDA 510(k) predicate device navigation costs are accelerating; consolidate ergonomic handle R&D across portfolio tiers to amortize clinical data investments. Channel control through exclusive distributor financing programs locks out emerging competitors from hospital system vendor panels. For New Entrants and Emerging Players: Home respiratory care retail channels in United States tracheostomy patient discharge protocols represent the most penetrable entry point for individually packaged sterile tips with patient instruction inserts. Malaysian ISO 13485-certified contract manufacturers seeking direct hospital system relationships offer white-label partnership angles bypassing established distributor markups. Pediatric silicone-tipped configurations in tertiary NICU settings command premium positioning with lower competitive density than commoditized polypropylene standard tips. For Investors and Strategic Acquirers: Ergonomic design specialists with validated FDA 510(k) clearances and hospital system pilot data represent the highest-conviction acquisition archetype for platform consolidation plays. Long-term viability hinges on material science differentiation capabilities that outpace commodity polypropylene substitution. The signal to watch is EU MDR notified body backlog resolution timelines, which would accelerate disposable tipping point adoption away from reusable stainless steel alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Malaysian contract manufacturers capture OEM orders from multinational distributors seeking dual-source qualification. |
| Silicone Material Portfolio Diversification | Platinum-cured elastomer tips reduce mucosal trauma in pediatric segments where liability concerns reshape procurement. |
| Hospital System Partnership Deepening | Integrated delivery network contracts displace fragmented regional distributors through just-in-time logistics integration. |
| Emergency Medicine Ventilated Tip Premiumization | Occlusion-resistant bulbous designs command pricing power in ambulance and trauma bay applications. |
| Home Care Retail Channel Development | Tracheostomy patient discharge protocols create demand for individually packaged sterile tips with patient instruction inserts. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital group purchasing organization contract award records preceded structured interviews with biomedical engineers, GPO contracts managers, sterile processing directors, and Malaysian contract manufacturing executives. Secondary validation drew from customs trade data, ISO 13485 certification registries, and polymer feedstock pricing indices. Bottom-up demand modeling across ambulatory surgical center expansion trajectories triangulated against top-down hospital procurement spend allocation estimates.
Assumptions held fixed include FDA 510(k) clearance pathway stability and continued EU MDR notified body capacity constraints, while variables tested encompassed polypropylene feedstock volatility scenarios and Malaysian logistics disruption probabilities. Segmentation dimensions modeled spanned material grade tier, clinical setting acuity, patient population age stratification, sterilization compatibility requirement, and regional regulatory cluster. CAGRs were derived from installed base turnover velocity and procedure volume elasticity coefficients across the projection horizon. Industry-specific forecast inputs incorporated ambulatory surgical center operating room utilization rates and silicone material adoption curves in neonatal intensive care.
Practitioners should monitor EU MDR notified body backlog resolution, single-use plastic regulatory mandate expansion, and polypropylene feedstock price volatility for early signals of demand trajectory revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Global Surgical Kits Market