
 Intravenous Transportation System Market | 2026-2036
Intravenous Transportation System Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Transportation System Market Analytics
ISO 80369-7 small-bore connector compliance is bifurcating the competitive landscape between certified and non-certified suppliers. Baxter International leverages its integrated pump-set ecosystem to sustain hospital contracts across North America. Fresenius Kabi anchors European demand through specialized oncology infusion workflows. B. Braun Medical competes on manufacturing scale, operating multiple sterile production sites that reduce supply chain risk for critical IV sets.
An intravenous transportation system comprises the apparatus that conveys fluids, medications, or blood products directly into a patient's venous circulation, typically incorporating tubing with luer-lock connectors, drip chambers calibrated to 10-20 drops per milliliter, and roller clamp flow control. These systems serve the essential clinical purpose of ensuring precise, contamination-free delivery of therapeutics in acute and ambulatory settings. Smart Pumps command the highest margin pool due to software-integrated dose error reduction systems, while Gravity Systems retain volume leadership in emerging markets where capital constraints limit electronic device procurement. Home Care represents the fastest-growing end-user channel as payors push infusion therapy outside institutional walls.
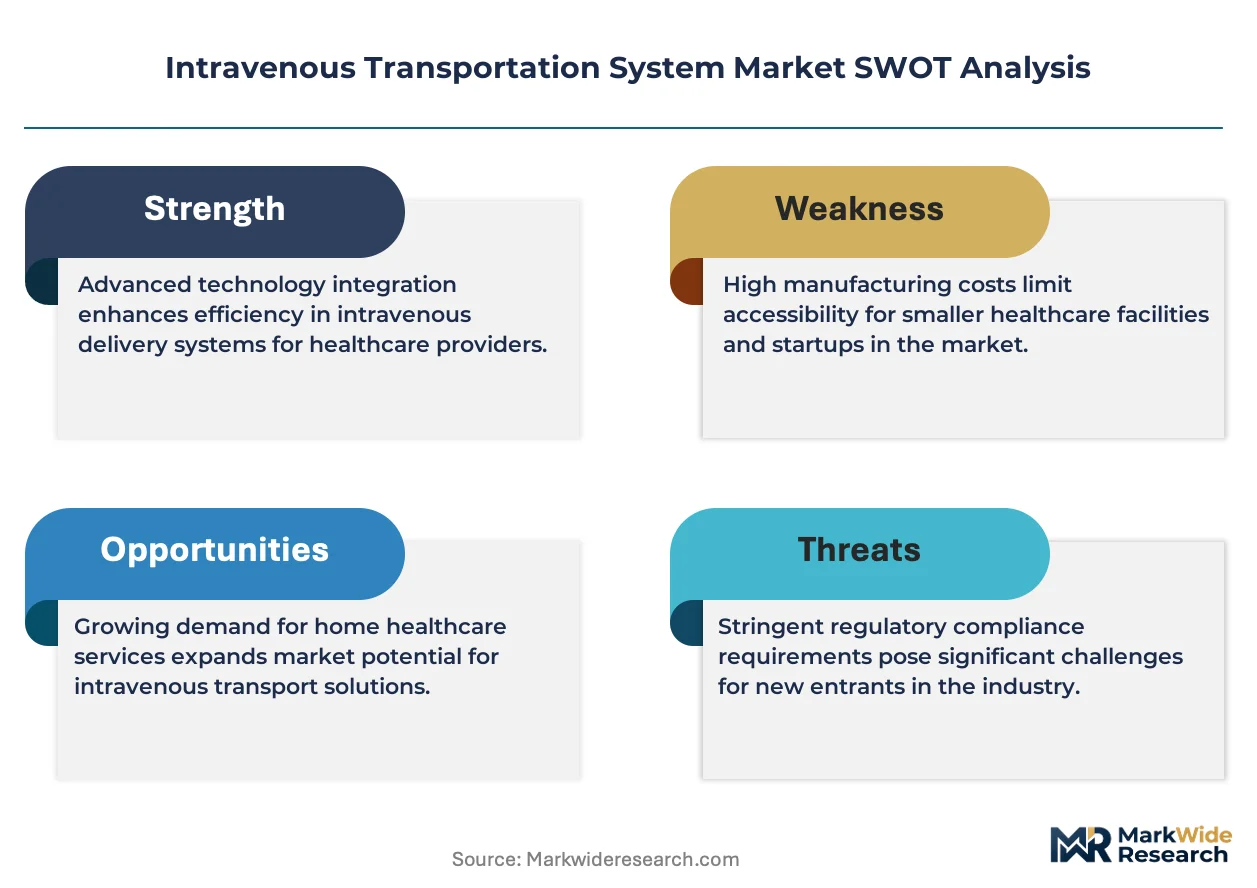
FDA 510(k) clearance timelines and EU MDR technical documentation requirements are extending product commercialization cycles and raising barriers for new entrants. The EPA regulates ethylene oxide sterilization emissions from IV component manufacturing facilities, pushing suppliers toward alternative terminal sterilization methods. Stakeholders must monitor evolving interoperability standards between smart pumps and electronic health record systems as connectivity becomes a procurement gate.
Market Dynamics
ISO 80369-7 small-bore connector mandates are bifurcating the competitive landscape between certified and non-certified suppliers, forcing hospital procurement teams to requalify entire product portfolios while sterilization facilities confront EPA ethylene oxide emission caps.
Growth Catalysts
- EU MDR compliance deadlines:European hospitals are accelerating replacement cycles for legacy IV sets to meet technical documentation requirements, creating pull-through demand for next-generation closed-system transfer devices.
- Home infusion therapy expansion:United States payors are pushing chemotherapy and immunoglobulin administration outside institutional walls, requiring portable IV transportation systems with ambulatory-grade durability.
- Japan's super-aging demographic:METI projections indicate sustained volume expansion for infusion therapy as the 75-plus population concentrates chronic disease management in acute care and long-term care facilities.
Market Restraints
- Medical-grade polymer cost volatility:Polyvinyl chloride and thermoplastic elastomer feedstock prices fluctuate with petrochemical indices, compressing margins for standard gravity IV set manufacturers.
- Sterilization capacity concentration:Ethylene oxide terminal sterilization facilities cluster in the United States Gulf Coast and select European industrial zones, exposing supply chains to single-point environmental regulatory actions.
- Gravity system substitution ceiling:Smart pump dose error reduction software limits addressable market expansion for basic roller-clamp systems in tertiary care settings.
Strategic Opportunities
- India's hospital infrastructure buildout:CDSCO streamlined medical device registration pathways under the 2017 Rules attract multinational IV set manufacturers to establish localized sterile production.
- Closed-system drug transfer device convergence:Integration of IV transportation tubing with hazardous drug containment technology opens oncology pharmacy workflows previously served by separate device categories.
- United States 340B program expansion:Eligible covered entities multiplying under federal drug pricing policies generate dedicated procurement channels for high-volume IV set suppliers.
Industry Challenges
- FDA 510(k) clearance timeline extension:Substantial equivalence determinations for novel connector designs now require extended bench testing and human factors validation, delaying product commercialization.
- Legacy pump interoperability gaps:Smart IV transportation systems face integration friction with heterogeneous electronic health record architectures across United States health system networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Transportation System Market |
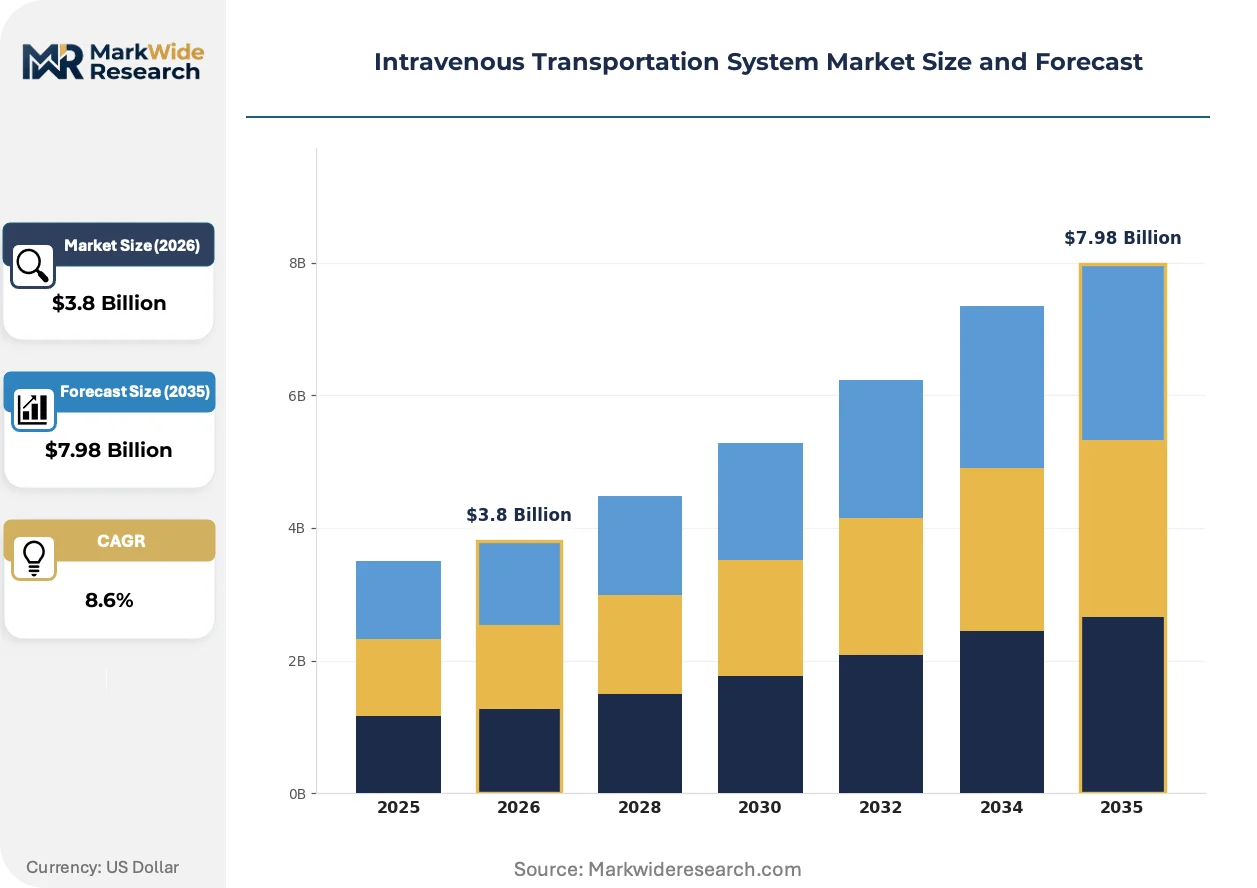
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, IV Sets, Flow Regulators, Accessories End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Technology: Smart Pumps, Gravity Systems, Electronic Devices, Mechanical Devices Application: Medication Administration, Nutritional Support, Blood Transfusion, Pain Management |
| Companies Covered | Baxter International, B. Braun Medical, Fresenius Kabi, ICU Medical, Medtronic, Cardinal Health, Terumo Corporation, Becton Dickinson and Company, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Transportation System Market Evolving Landscape
Software-integrated safety systems and alternative sterilization modalities are actively reshaping product development roadmaps and manufacturing investment priorities across the IV transportation system value chain.
Needle-free connector technology is fragmenting the luer-lock dominant design that has governed IV set architecture for decades. Pediatric and oncology units in German university hospitals are piloting swabable disinfection-cap connectors at replacement rates exceeding general medical-surgical floors. This connector transition is fragmenting supplier relationships as hospitals dual-source legacy and next-generation platforms during extended qualification periods.
EPA ethylene oxide emission regulations are forcing sterilization infrastructure reconfiguration across United States medical device manufacturing zones. Alternative terminal sterilization methods including gamma irradiation and vaporized hydrogen peroxide are capturing share for IV tubing components previously processed with EtO. Component suppliers with captive gamma capacity in Illinois and California are securing multi-year contracts with pump-set integrators seeking supply assurance.
Consolidated purchasing organizations are unbundling IV set procurement from historical pump vendor lock-in arrangements. United States hospital systems with centralized supply chain functions now issue separate RFPs for smart pump hardware, proprietary disposable sets, and third-party compatible tubing. This unbundling is most visible in the Southeast and Midwest regions where health system merger activity has concentrated buying power under single governance structures.
Intravenous Transportation System Market Segmentation
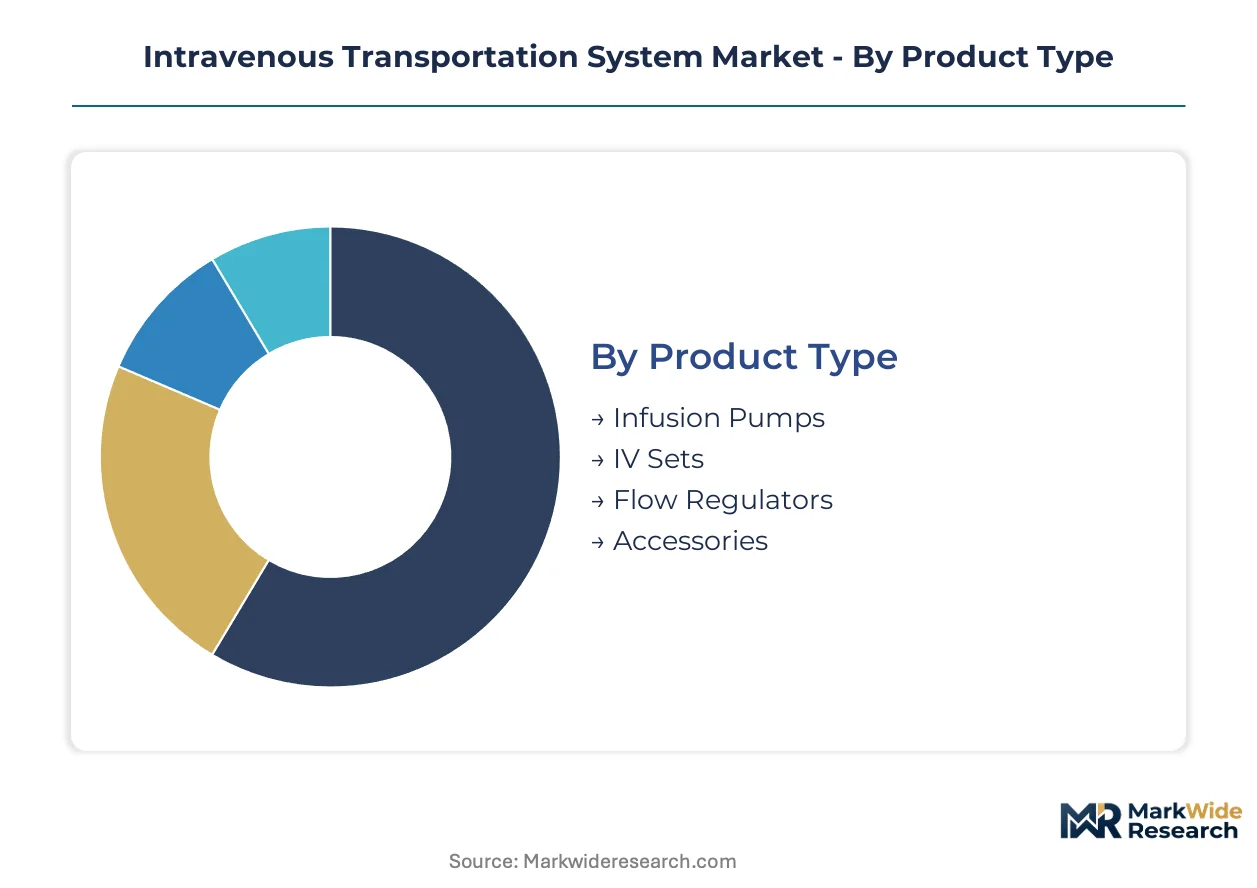
Segmentation in the intravenous transportation system market reveals how procurement channels, reimbursement pathways, and clinical workflows fragment demand across distinct product configurations and care settings. Understanding these divides allows suppliers to align manufacturing scale with volume concentration and margin profiles.
Product Type:
Channel flow splits sharply between capital equipment sold through GPO-negotiated contracts and disposable sets replenished via distributor stock programs.
- Infusion Pumps:Programmable electromechanical devices with software-integrated dose error reduction systems dominate tertiary care capital budgets. Demand concentrates in United States academic medical centers where FDA-cleared smart pump interoperability with electronic health records drives replacement cycles.
- IV Sets:Single-use tubing assemblies with luer-lock connectors and drip chambers constitute the highest-volume disposable category. German university hospitals are accelerating ISO 80369-7 small-bore connector conversions, pulling through next-generation closed-system designs.
- Flow Regulators:Roller clamps and precision dial controllers attach to gravity or pump-driven lines for manual rate adjustment.
- Accessories:Needle-free connectors, extension sets, and stopcocks complete circuit configurations.
By volume, IV Sets lead. By growth pace, Infusion Pumps are climbing the fastest.
End User:
Cost tier stratification separates capital-intensive institutional purchasers from price-sensitive ambulatory channels.
- Hospitals:Integrated delivery networks with centralized supply chain functions command tiered pricing through consolidated purchasing organization contracts. United States health systems in the Southeast and Midwest unbundle pump hardware from disposable set procurement.
- Home Care:Portable IV transportation systems with ambulatory-grade durability serve chemotherapy and immunoglobulin administration outside institutional walls. United States payor pressure on site-of-care shifting fuels steepest expansion trajectory among all end-user channels.
- Clinics:Outpatient infusion centers balance capital constraints against throughput requirements.
- Long-Term Care Facilities:Skilled nursing and assisted living settings utilize simplified gravity systems for hydration and antibiotic therapy.
By installed base, Hospitals dominate. By volume shift, Home Care is gaining share fastest.
Technology:
Application criticality determines whether facilities invest in software-integrated safety systems or rely on mechanical alternatives.
- Smart Pumps:Drug library-enabled devices with wireless connectivity to electronic medication administration records command premium positioning. Japan's super-aging demographic concentrates demand in acute care facilities managing complex polypharmacy.
- Gravity Systems:Basic roller-clamp and drip-chamber configurations retain dominance where capital constraints limit electronic device procurement. India's hospital infrastructure buildout under CDSCO streamlined registration attracts multinational manufacturers to localize production.
- Electronic Devices:Non-programmable flow meters and alarm-equipped pumps occupy mid-tier positioning.
- Mechanical Devices:Elastomeric balloon pumps and spring-driven syringes serve ambulatory chemotherapy.
By margin pool, Smart Pumps lead. By unit expansion, Gravity Systems are ahead.
Application:
Customer type fragmentation separates oncology pharmacy workflows from general medical-surgical floors with distinct containment and precision requirements.
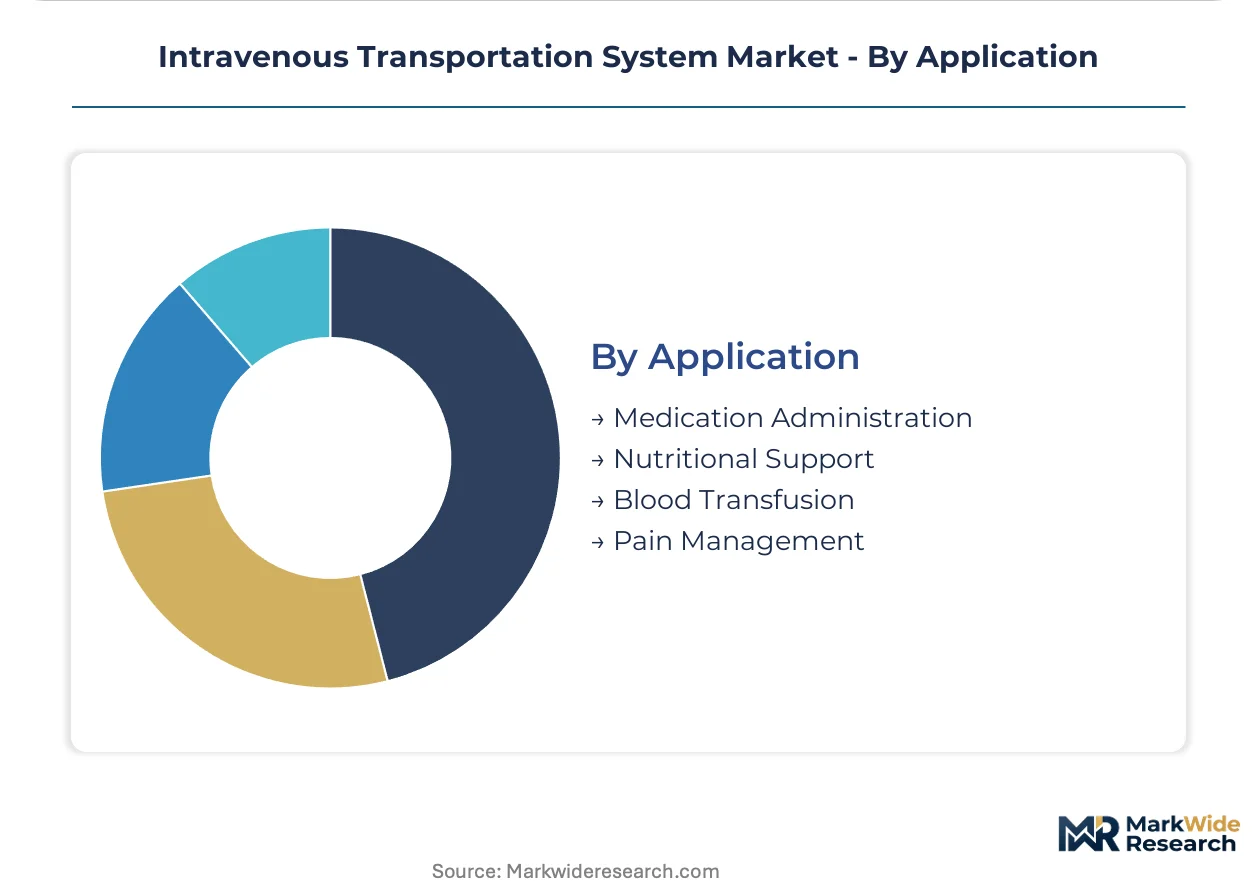
- Medication Administration:Chemotherapy, antibiotics, and biologics delivery demands closed-system transfer device integration for hazardous drug containment. United States 340B program expansion generates dedicated procurement channels for high-volume IV set suppliers serving eligible covered entities.
- Nutritional Support:Parenteral nutrition formulations require lipid-compatible tubing and dedicated enteral avoidance protocols.
- Blood Transfusion:Filter-equipped sets with specialized drip chambers handle cellular products.
- Pain Management:Patient-controlled analgesia pumps and epidural sets serve perioperative and palliative protocols.
By procedure volume, Medication Administration leads. By safety regulation intensity, Blood Transfusion is tightening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in the United States, Germany, and Japan command the highest contract values, while India's infrastructure buildout and China's domestic manufacturing expansion reshape supply-side geography.
United States
Academic medical centers in Boston and the Research Triangle drive smart pump replacement cycles. FDA 510(k) clearance timelines for novel connector designs now require extended human factors validation. Sterilization capacity concentrates on the Gulf Coast, where EPA ethylene oxide emission caps force facility reconfiguration.
Germany
University hospitals in Bavaria and Baden-Württemberg pilot ISO 80369-7 small-bore connector conversions at replacement rates exceeding general medical-surgical floors. EU MDR technical documentation requirements accelerate legacy IV set obsolescence. The Stuttgart industrial corridor hosts specialized oncology infusion workflow suppliers.
Japan
METI projections indicate sustained volume expansion for infusion therapy as the 75-plus population concentrates chronic disease management in acute care. PMDA regulatory pathways maintain stringent quality benchmarks for imported devices. The Kansai region around Osaka anchors domestic production of precision flow regulators.
India
CDSCO streamlined medical device registration pathways under the 2017 Rules attract multinational manufacturers to establish localized sterile production. Maharashtra and Gujarat host emerging hospital infrastructure clusters demanding gravity systems. Mumbai-Pune pharmaceutical corridors generate pull-through demand for closed-system drug transfer devices.
China
NMPA domestic approval pathways favor local manufacturers of basic IV sets serving tier-two and tier-three hospitals. Yangtze River Delta medical device clusters scale thermoplastic elastomer component production. Shanghai's procurement centralization experiments unbundle pump hardware from disposable set purchasing.
Intravenous Transportation System Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with integrated pump-set ecosystems. Three multinational suppliers capture dominant share in North American and European hospital contracts. Tiered competitive dynamics separate premium smart pump integrators from high-volume gravity set manufacturers. Strategic moves concentrate on sterilization capacity security and software interoperability certification.
Within the diversified conglomerate tier, Baxter International, B. Braun Medical, and Fresenius Kabi occupy positions shaped by manufacturing scale and regional contract density. Baxter exemplifies the integrated ecosystem archetype through hospital contract sustainability. B. Braun represents manufacturing footprint diversification with multiple sterile production sites. Fresenius Kabi anchors European demand concentration through specialized workflow positioning.
| Leading Market Players |
|---|
| Baxter International |
| B. Braun Medical |
| Fresenius Kabi |
| ICU Medical |
| Medtronic |
| Cardinal Health |
| Terumo Corporation |
| Becton Dickinson and Company |
| Teleflex |
| Others |
Value Network & Pricing Analysis
Gamma irradiation's displacement of ethylene oxide sterilization is redrawing manufacturing geography across Illinois and California while compressing cost structures for IV tubing suppliers seeking EPA compliance. This substitution dynamic simultaneously concentrates sterilization capacity under component makers with captive gamma facilities and fragments pricing power between EtO-dependent legacy producers and certified alternatives.
Pricing Analysis
Cost-plus contracts indexed to polyvinyl chloride and thermoplastic elastomer feedstock prices dominate procurement between pump-set integrators and tubing suppliers. Three-tier pricing structure across premium smart pumps, standard electronic devices, and economy gravity systems reflects certification grade and software integration depth. Cost compression in economy gravity sets is intensifying because Indian and Chinese manufacturers localize sterile production under streamlined regulatory pathways. Home care channels exhibit highest price sensitivity due to reimbursement pressure, while academic medical centers prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes are elevating inbound logistics costs for medical-grade polymer resin shipments. Manufacturing concentrates in the United States, Germany, and China, with sterile production sites clustering around Chicago, Stuttgart, and Shanghai. Supply chains rest on polyvinyl chloride resin, thermoplastic elastomer compounds, and precision-molded luer-lock components. Single-source vulnerability concentrates in Gulf Coast ethylene oxide sterilization facilities facing EPA emission caps. Distribution runs through consolidated purchasing organizations and specialized medical device distributors serving hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against oral and subcutaneous drug delivery formats that threaten to displace infusion therapy volumes in chronic disease management. Substitution defense requires locking in sterilization capacity and software interoperability certification before regulatory deadlines harden competitive moats.
For Market Incumbents: Secure captive gamma irradiation capacity in Illinois and California to eliminate EtO regulatory exposure while maintaining supply assurance for hospital contracts. Deepen backward integration into medical-grade polymer compounding to buffer feedstock volatility compressing gravity set margins. ISO 80369-7 certification investment is essential before EU MDR technical documentation deadlines disqualify legacy connector platforms. For New Entrants and Emerging Players: Oncology pharmacy workflow software integration represents the most penetrable service-layer gap where incumbent pump vendors under-serve hazardous drug containment requirements. Target India's Maharashtra and Gujarat hospital infrastructure clusters where CDSCO streamlined registration enables first-mover positioning against delayed multinational localization. Go-to-market through closed-system drug transfer device bundling with IV tubing captures pull-through demand from Mumbai-Pune pharmaceutical corridors. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors sterilization infrastructure owners over device-assembly specialists. Long-term viability across the next decade hinges on EPA compliance positioning and EU MDR certification completion. Acquisition targets should display captive terminal sterilization assets or gamma facility partnerships. The signal to watch is FDA 510(k) clearance timeline extension for novel connector designs, which will strand R&D-heavy entrants lacking manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80369-7 Certification Investment | EU MDR compliance deadlines in Germany and France disqualify legacy connector suppliers from hospital procurement. |
| Captive Gamma Sterilization Capacity | Illinois and California facilities secure supply assurance as EPA ethylene oxide emission caps force Gulf Coast reconfiguration. |
| Smart Pump-EHR Interoperability Development | FDA-cleared wireless connectivity to Epic and Cerner systems drives replacement cycles in Boston academic medical centers. |
| Closed-System Drug Transfer Device Convergence | Oncology pharmacy workflows in Stuttgart and Munich demand hazardous drug containment integrated with IV tubing. |
| India Localized Sterile Production | Maharashtra hospital infrastructure buildout under CDSCO 2017 Rules attracts multinational gravity set manufacturing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement database records. Primary interviews engaged biomedical engineers, GPO contracts managers, hospital purchasing committee members, and sterile manufacturing facility operators. Secondary sources included EPA emission compliance disclosures, CDSCO registration pathways, and CMS Medicare reimbursement data. Bottom-up volume modeling triangulated against top-down value estimates across product type, end user, technology, and application segments.
Segmentation dimensions modeled span infusion pumps, IV sets, flow regulators, and accessories by product type; hospitals, home care, clinics, and long-term care facilities by end user; smart pumps, gravity systems, electronic devices, and mechanical devices by technology; and medication administration, nutritional support, blood transfusion, and pain management by application. CAGRs were derived from procedure volume trajectories, replacement cycle analysis, and payor site-of-care shift policies. Forecast inputs incorporated Japan METI aging demographic projections and United States 340B program expansion eligibility.
Forecasts assume regulatory continuity in FDA, EPA, and EU MDR regimes; material policy shifts would require re-modeling. Specific risks include ethylene oxide sterilization facility closures, ISO 80369-7 mandate acceleration, and smart pump interoperability standard changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Biopsy Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Phoropters Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Asthma Device Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Morcellators Market