
 Global Medical Supplies Market | 2026-2036
Global Medical Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Supplies Market Outlook
Market Dynamics
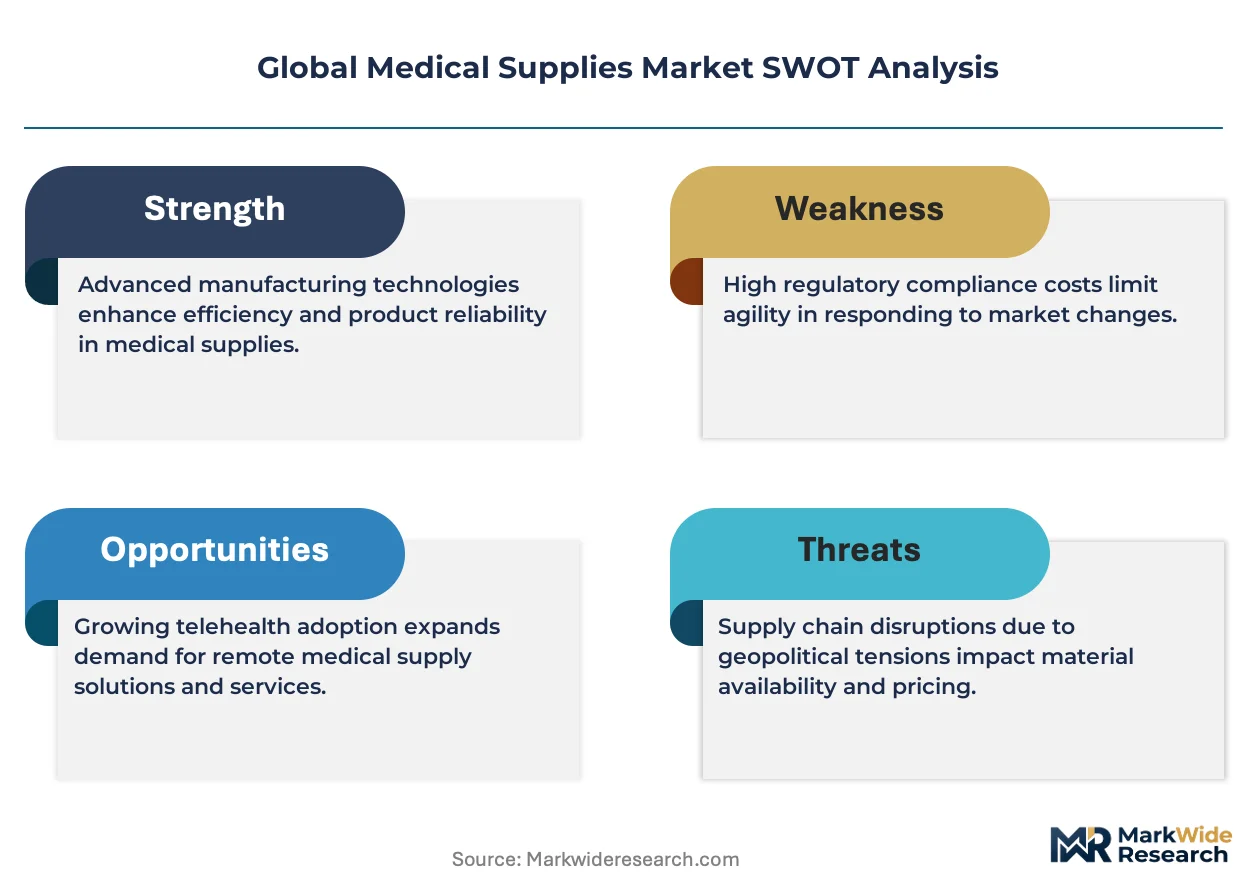
Hospital procurement channels is tilting toward consolidated purchasing agreements that favor large-scale distributors over fragmented suppliers. McKesson Corporation leverages its nationwide distribution network to secure multi-year contracts with integrated delivery networks. Cardinal Health anchors its position through direct-to-site logistics that reduce inventory carrying costs for acute care facilities. Medline Industries differentiates via private-label consumables that compete on price against branded alternatives in high-volume categories.
Medical supplies encompass single-use consumables, reusable instruments, implantable devices, and durable equipment manufactured from polymers, metals, ceramics, and biological materials to prevent infection, enable diagnosis, or restore physiological function. Consumables dominate transaction volume due to their recurring replacement cycle in surgical and wound care settings, while implants command premium margins supported by lengthy regulatory pathways and proprietary biomaterial formulations. Diagnostic testing applications are expanding fastest as point-of-care platforms displace centralized laboratory workflows for routine panels.
The FDA enforces quality system regulation and unique device identification requirements that elevate compliance costs for market entry, while the EU MDR imposes stricter clinical evidence standards on legacy products seeking CE mark renewal. China's NMPA accelerates review timelines for domestically manufactured innovative devices under its priority review pathway. Stakeholders must monitor divergence between FDA and EU MDR requirements as dual-market manufacturers face escalating documentation burdens.
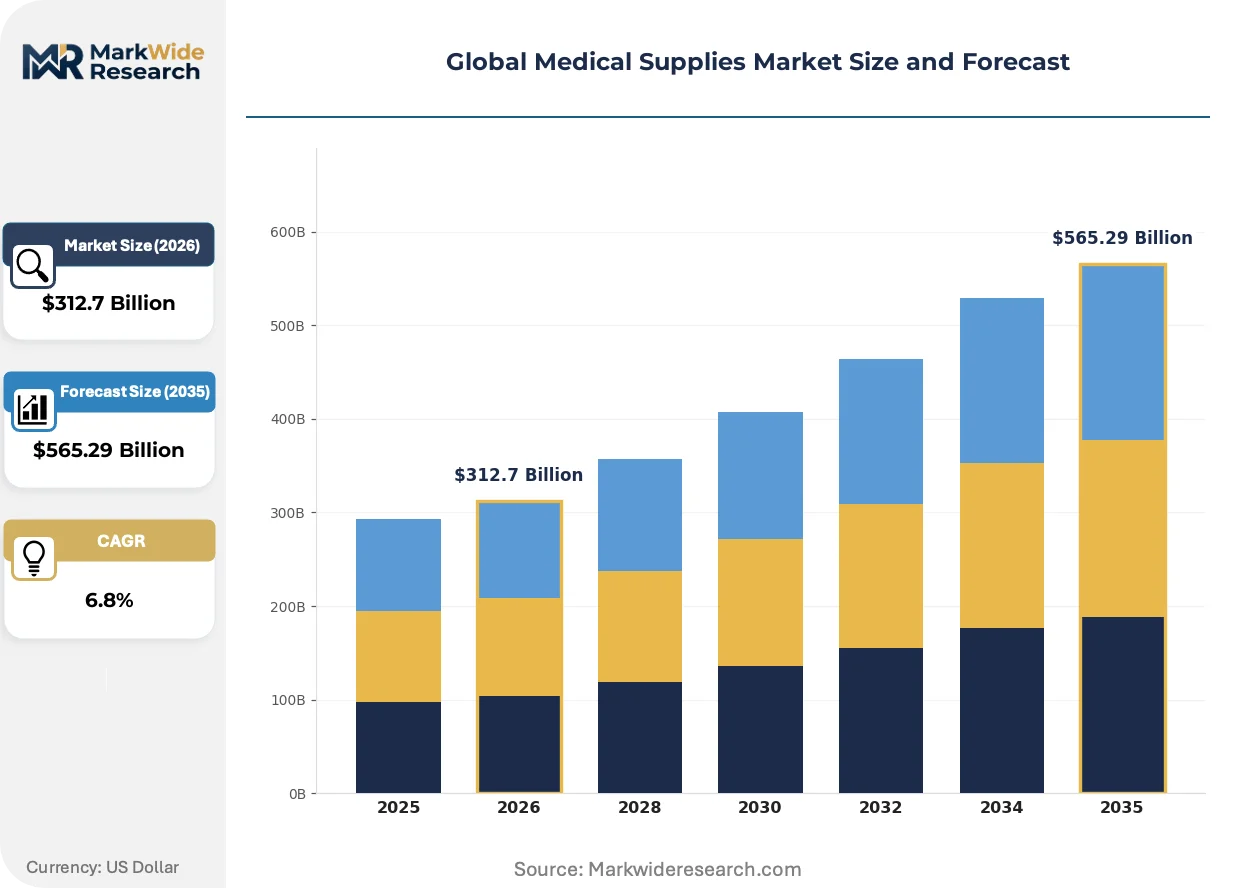
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while favoring distributors with national logistics footprints and private-label manufacturing capabilities.
Growth Catalysts
- EU MDR implementation:Stricter clinical evidence standards for CE mark renewal are accelerating replacement of legacy devices with next-generation alternatives across European acute care networks.
- Point-of-care diagnostic platforms:Decentralized testing workflows are expanding consumable demand in ambulatory settings and reducing laboratory infrastructure dependence.
- China's NMPA priority review pathway:Accelerated domestic device approvals are scaling local production capacity and redirecting supply chain gravity toward Shanghai and Shenzhen manufacturing clusters.
Market Restraints
- Polymer feedstock volatility:Medical-grade resin prices fluctuate with petrochemical markets, squeezing margin predictability for single-use consumable manufacturers.
- Duplicative documentation burdens:Divergent FDA quality system regulation and EU MDR technical file requirements force dual-market manufacturers to maintain parallel compliance infrastructures.
- Biologic sealant substitution:Advanced hemostatic agents are displacing traditional suture and staple applications in select surgical categories.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives are attracting contract manufacturing investment for export-oriented consumable production.
- Home-based chronic wound care:Aging demographics and reimbursement shifts are expanding durable dressing demand outside institutional settings.
- AI-enabled inventory forecasting:Machine learning integration with hospital ERP systems is creating subscription revenue streams for distributors with data capabilities.
Industry Challenges
- Biomaterials engineering talent scarcity:Specialized polymer-ceramic composite expertise concentrates in Boston, Stuttgart, and Singapore, constraining R&D expansion for mid-tier manufacturers.
- Unique device identification serialization:FDA-mandated UDI compliance requires capital-intensive labeling infrastructure upgrades across legacy product lines.
- Legacy ERP integration friction:Hospital consolidated purchasing platforms demand real-time API connectivity that smaller suppliers struggle to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Supplies Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Instruments, Implants, Equipment Delivery Mode: Direct, E-commerce, Retail, Wholesaler End User: Clinics, Hospitals, Diagnostic Labs, Nursing Homes Application: Wound Care, Surgical Procedures, Diagnostic Testing, Patient Monitoring |
| Companies Covered | McKesson Corporation, Medline Industries, Cardinal Health, Henry Schein, Medtronic, Johnson & Johnson Services, Abbott, BD, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Supplies Market Strategic Shifts
Digital supply chain integration and biomaterial advances are restructuring how medical consumables are specified, procured, and replenished across acute and non-acute settings.
Surgical planning software is virtualizing preoperative instrument selection and sterilization workflows. Integrated delivery networks in Texas and Bavaria are deploying these platforms to reduce case cart errors and reprocessing costs. The technology is virtualizing traditional clinical engineering functions into centralized remote monitoring operations.
China's NMPA is tightening adverse event reporting requirements for imported implantable devices under revised post-market surveillance rules. Domestic manufacturers gain review timeline advantages while foreign suppliers face extended inspection backlogs. Cardiovascular implant suppliers are restructuring China market entry strategies around local clinical trial partnerships.
Consolidated purchasing agreements are displacing fragmented supplier relationships in US hospital systems. Multi-year contracts with integrated delivery networks now specify compliance dashboards and inventory guarantees that smaller distributors cannot match. This concentration is most visible in California and New York health systems with mature centralized procurement functions.
Global Medical Supplies Market Segmentation
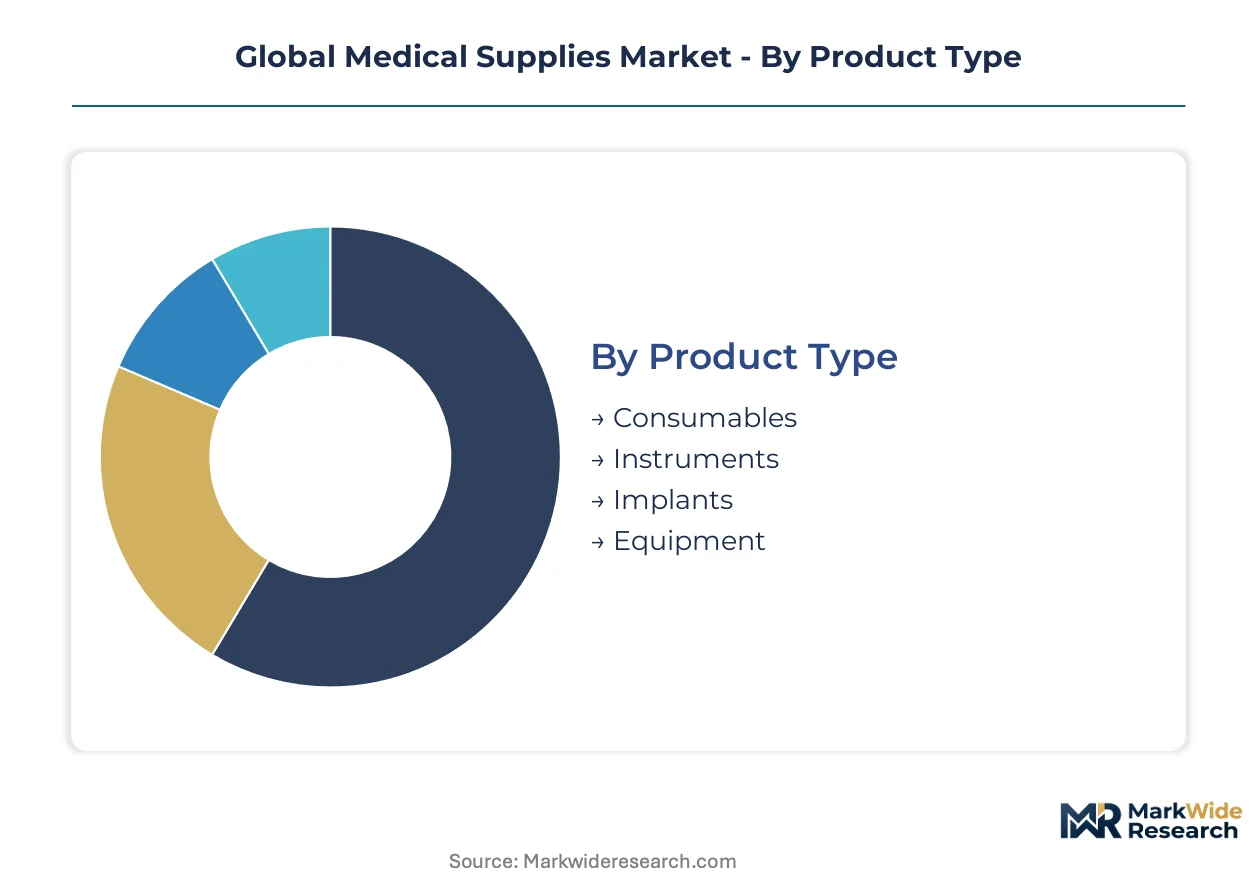
Medical supplies segmentation reveals divergent margin profiles and service intensity requirements across product categories. Procurement patterns vary sharply by delivery channel and end-user sophistication, with hospital systems demanding integrated inventory management while ambulatory settings prioritize transaction speed.
Product Type:
After-sales service intensity escalates from consumables through equipment tiers, with implantable devices requiring specialized clinical support and equipment demanding preventive maintenance contracts.
- Consumables:Single-use polymers, textiles, and disposables engineered for sterility assurance and biocompatibility. Demand concentrates in United States hospital systems scaling centralized purchasing programs, constrained by polymer feedstock price volatility squeezing manufacturer margins.
- Instruments:Reusable surgical tools and diagnostic apparatus fabricated from medical-grade stainless steel and advanced ceramics. German acute care networks drive specification standards, favoring instruments with validated reprocessing protocols that reduce per-procedure costs.
- Implants:Prosthetic and therapeutic devices integrating proprietary biomaterial formulations with lengthy regulatory pathways.
- Equipment:Capital-intensive diagnostic and therapeutic systems requiring installation, training, and multi-year service agreements.
Consumables hold the largest share; momentum sits with implants as EU MDR clinical evidence standards accelerate next-generation device adoption.
Delivery Mode:
Cost tier stratification separates premium direct relationships from economy-oriented retail channels, with distributor scale determining contract eligibility.
- Direct:Manufacturer-to-institution contracts specifying volume commitments, compliance dashboards, and consignment inventory arrangements. United States integrated delivery networks dominate this channel, leveraging multi-year agreements to secure price guarantees and dedicated logistics support.
- E-commerce:Digital procurement platforms enabling spot purchasing with transparent pricing and rapid fulfillment. China's hospital procurement reforms are expanding this channel, redirecting transaction volume toward Alibaba Health and JD Health marketplaces.
- Retail:Pharmacy and medical supply storefronts serving individual consumers and small practices.
- Wholesaler:Regional distributors aggregating fragmented demand from independent clinics and nursing facilities.
Direct distribution commands premium pricing; e-commerce is climbing the fastest as procurement digitization accelerates across Asian health systems.
End User:
Customer type segmentation aligns product complexity with institutional capability, from sophisticated hospital supply chains to resource-constrained residential care.
- Hospitals:Acute care facilities with centralized purchasing functions, clinical engineering departments, and sterilization infrastructure. Demand concentrates in United States, Germany, and China as these countries scale domestic production capacity and tighten procurement consolidation.
- Diagnostic Labs:Centralized and point-of-care testing facilities with specialized consumable requirements and quality control protocols.
- Clinics:Outpatient settings prioritizing inventory turnover and space-efficient storage solutions.
- Nursing Homes:Long-term care facilities with chronic wound care and patient mobility equipment needs.
Hospitals retain dominant procurement volume; diagnostic labs are gaining share fastest as decentralized testing platforms expand consumable demand.
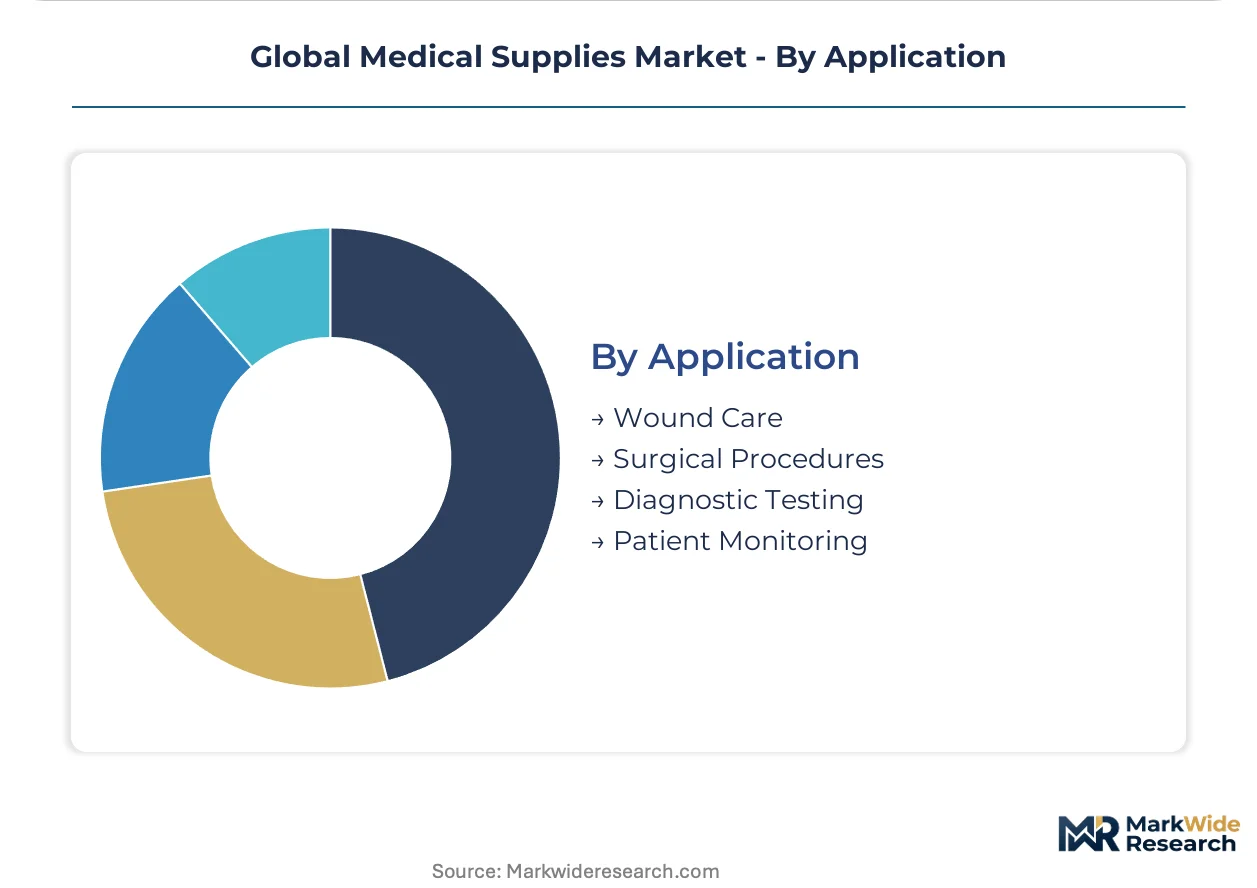
Application:
Volume concentration varies by clinical setting maturity, with established surgical workflows contrasting against rapidly scaling diagnostic testing applications.
- Diagnostic Testing:Reagents, collection devices, and point-of-care platforms enabling decentralized laboratory workflows. United States ambulatory networks and Chinese primary care clinics are expanding demand fastest as rapid panels displace centralized processing.
- Surgical Procedures:Sterile drapes, sutures, staplers, and specialty instruments supporting operative interventions. German and Japanese hospital systems maintain stringent specification standards, favoring suppliers with validated supply continuity.
- Wound Care:Dressings, bandages, and negative pressure therapy systems for acute and chronic lesion management.
- Patient Monitoring:Sensors, electrodes, and disposable interfaces for continuous physiological assessment.
Surgical applications hold the largest share; diagnostic testing shows the steepest expansion trajectory as point-of-care platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution efficiency for temperature-sensitive medical consumables. Rail connections from Hamburg to Warsaw accelerate Central European replenishment cycles. Shanghai's Yangshan deep-water port anchors Asia-Pacific supply chain gravity with dedicated medical cargo terminals.
United States
Integrated delivery networks in Texas and California are consolidating procurement through multi-year distributor contracts with compliance dashboards. FDA quality system regulation updates and unique device identification mandates are elevating documentation requirements for domestic manufacturers. Boston's Route 128 corridor concentrates biomaterials R&D talent for advanced polymer-ceramic composites.
Germany
Acute care networks in Bavaria and North Rhine-Westphalia maintain stringent instrument specification standards favoring validated reprocessing protocols. EU MDR implementation imposes stricter clinical evidence standards on legacy devices seeking CE mark renewal. Stuttgart's industrial cluster houses specialized surgical instrument fabricators serving European hospital systems.
China
Primary care clinics and ambulatory networks are expanding point-of-care diagnostic consumable demand under procurement reform programs. NMPA priority review pathways accelerate domestic device approvals while tightening adverse event reporting for imported implants. Shenzhen and Shanghai manufacturing clusters are scaling production capacity for export-oriented consumables.
India
Government hospital procurement reforms are expanding centralized purchasing for single-use consumables and diagnostic reagents. PLI scheme production-linked incentives attract contract manufacturing investment for export-oriented medical device production. Gujarat and Karnataka industrial corridors concentrate cleanroom manufacturing infrastructure for polymer-based disposables.
Japan
Aging demographics are expanding chronic wound care and patient mobility equipment demand outside institutional settings. PMDA regulatory frameworks maintain rigorous quality standards for implantable devices and diagnostic platforms. Osaka-Kansai manufacturing bases specialize in precision surgical instruments with advanced ceramic formulations.
Global Medical Supplies Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fragmented supply positions. The vendor base organizes around three structural tiers: national distributors with logistics footprints, private-label manufacturers competing on price, and branded device makers with proprietary biomaterial formulations. Strategic archetypes include scale-driven procurement consolidators, specialty distributors with clinical support capabilities, and vertically integrated manufacturers with captive resin supply. Competitive moves concentrate on multi-year contract capture with integrated delivery networks and backward integration into polymer compounding operations.
Within the distributor tier, McKesson Corporation and Cardinal Health exemplify scale-driven platform operators with nationwide logistics infrastructure. Medline Industries occupies a position as a private-label specialist competing on price in high-volume consumable categories. These three entities represent the dominant competitive archetypes reshaping hospital procurement consolidation across United States health systems.
| Leading Market Players |
|---|
| McKesson Corporation |
| Medline Industries |
| Cardinal Health |
| Henry Schein |
| Medtronic |
| Johnson & Johnson Services |
| Abbott |
| BD |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's cold-chain corridors anchor European distribution economics, with refrigerated container rates compressing margin structures for temperature-sensitive consumables while amplifying price differentiation between integrated distributors and fragmented regional suppliers. Polymer feedstock volatility feeds directly into procurement tiering, as hospital systems leverage volume scale to extract cost guarantees that smaller ambulatory settings cannot secure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hospital procurement contracts, with FDA-validated sterile barrier systems commanding certification premiums against private-label alternatives. Price differentiation hinges on compliance tier—EU MDR technical file completeness versus legacy CE mark status—and volume commitment scale, with integrated delivery networks extracting 15-20 point discounts through multi-year offtake agreements. Cost compression in the consumables tier is intensifying because polymer resin indices remain tethered to petrochemical volatility, while diagnostic labs show highest price sensitivity due to reimbursement compression and acute care facilities demonstrate lowest sensitivity given patient outcome liability.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Foxconn Health Technology, Jabil Healthcare, and Flex Medical holding dominant cleanroom infrastructure for polymer-based disposables across Shenzhen, Penang, and Guadalajara clusters. Medical-grade resin supply draws from Saudi petrochemical complexes, Texas Gulf Coast crackers, and Rotterdam refining hubs, with specialized ceramic feedstock sourcing from Japan's Kyushu industrial zone. Single-source vulnerability persists in hemostatic biologic precursors derived from controlled fermentation processes. Distribution runs through national platform operators with consignment inventory capabilities, displacing fragmented wholesaler networks in consolidated procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution defense imperatives as advanced hemostatic biologics displace traditional mechanical closure devices in laparoscopic and cardiovascular surgical categories. Market positioning requires active portfolio management against these biologic entrants.
For Market Incumbents: Harden supply continuity credentials through backward integration into medical-grade polymer compounding operations in Texas and Rotterdam corridor locations. Lock multi-year distributor contracts with integrated delivery networks specifying FDA UDI compliance dashboards and inventory guarantee terms. Prioritize CE mark renewal investments ahead of EU MDR technical file deadlines to defend European hospital system positioning against next-generation device substitution.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridors for export-oriented consumable production, leveraging Gujarat cleanroom infrastructure to serve European and Middle Eastern procurement channels. Target diagnostic reagent white space in Chinese primary care clinics where NMPA priority review accelerates domestic approval timelines. Pursue hospital system partnership models with software-enabled inventory forecasting capabilities as differentiated entry mechanism against established distributors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors private-label manufacturers with captive resin supply and established GPO contract relationships over pure-brand device makers facing EU MDR clinical evidence reinvestment cycles. Long-term viability centers on procurement consolidation beneficiaries with data integration capabilities across hospital ERP systems. Watch NMPA adverse event reporting enforcement intensity as signal for China market restructuring toward domestic manufacturing preference.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Renewal | CE mark continuity secures European hospital system access against next-generation device displacement. |
| FDA UDI Serialization Infrastructure | Compliance mandates capital-intensive labeling upgrades that filter smaller competitors from institutional channels. |
| Hospital System Data Partnership | AI-enabled inventory forecasting creates subscription revenue streams and procurement lock-in with IDNs. |
| India PLI Contract Manufacturing | Production-linked incentives attract export-oriented capacity for polymer-based disposables serving European demand. |
| Biomaterials R&D Cluster Expansion | Boston and Stuttgart talent concentration limits mid-tier manufacturer R&D scaling without geographic proximity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical file databases, hospital GPO contract disclosures, and NMPA priority review pathway announcements. Primary interviews engaged hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at implantable device manufacturers. Secondary validation drew from customs trade data, SEC 10-K supply chain disclosures, and CMS Medicare reimbursement schedules. Bottom-up demand modeling triangulated against top-down macro allocation across product categories.
Forecast inputs span consumables, instruments, implants, and equipment segments across direct, e-commerce, retail, and wholesaler delivery modes. Modeled dimensions include product type complexity, end-user institutional capability, and application-specific regulatory pathway intensity. CAGRs were derived from logistic diffusion curves fitted to procurement digitization adoption patterns and biomaterial substitution trajectories. Supply-side capacity assumptions incorporated NMPA review timeline acceleration and EU MDR implementation compliance cost burdens.
Macroeconomic conditions sit as an overlay; deviation in polymer feedstock indices, healthcare reimbursement policy, or trade corridor tariff structures would shift the trajectory. Forecasts reflect documented assumptions regarding procurement consolidation velocity and regulatory harmonization progress. Quarterly review of hospital capital expenditure commitments, GPO contract renewal volumes, and NMPA inspection backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Sterile Container Market
Medical Supplies
Lab Trays Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Veterinary Syringes Market