
 Healthcare Logistics Market | 2026-2036
Healthcare Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Logistics Market Analysis
European cold storage capacity is rebalancing after pandemic-era overbuild in southern hubs. DHL Supply Chain leverages its Frankfurt temperature-controlled campus to anchor pharmaceutical distribution across the continent. FedEx Supply Chain competes through Memphis-controlled express lanes that sustain next-day biologics delivery to East Coast hospitals. Kuehne + Nagel differentiates via its Basel proximity to Novartis and Roche, dominating Swiss pharma exports.
Healthcare logistics encompasses the specialized movement, storage, and handling of temperature-sensitive pharmaceuticals, biologics, medical devices, and clinical supplies through validated cold chain infrastructure maintaining 2-8°C or cryogenic conditions. Its primary commercial purpose is preserving product efficacy from manufacturer to patient administration while meeting serialization and chain-of-custody documentation requirements. Cold chain logistics leads delivery mode segmentation due to biologics volume expansion, while third-party logistics captures margin pools through outsourced compliance management. Warehousing within service type segmentation concentrates investment in automated picking and real-time inventory visibility systems.
FDA drug supply chain security mandates and EMA falsified medicines directives reshape serialization infrastructure spending across manufacturer and distributor tiers. WHO temperature excursion guidelines and EU GDP standards further constrain permissible handling protocols for international vaccine shipments. Stakeholders must monitor evolving pharmacovigilance reporting obligations tied to distribution records as regulatory convergence between FDA and EMA accelerates.
Market Dynamics
FDA and EMA serialization mandates are compressing compliance timelines across biopharmaceutical distribution networks, forcing wholesale infrastructure replacement before 2027 deadlines. Cold chain validation requirements now extend to last-mile handoffs, reshaping capital allocation across temperature-controlled warehousing and transport assets.
Growth Catalysts
- Biologics Volume Expansion:Cell and gene therapy pipelines require cryogenic logistics infrastructure that commands premium service margins. Manufacturers are outsourcing end-to-end cold chain custody to specialized 3PL providers.
- EU Falsified Medicines Directive:EMA track-and-trace mandates are accelerating serialization hardware deployment across European distribution centers. Wholesalers must upgrade line-level scanning capabilities to maintain operating licenses.
- mRNA Platform Proliferation:Vaccine modalities requiring ultra-low temperature storage are driving demand for validated -70°C container fleets. Logistics providers are expanding dry ice production capacity near major manufacturing clusters.
Market Restraints
- Energy Cost Volatility:Refrigerated warehousing faces margin compression from electricity price spikes in European markets. Temperature-controlled facilities consume three to five times baseline industrial power loads.
- Specialized Fleet Concentration:Qualified refrigerated truck capacity concentrates with a limited pool of certified carriers in Germany and the Netherlands. New entrants face eighteen to twenty-four month qualification timelines.
- Reusable Packaging Substitution:Phase-change material shippers are displacing single-use expanded polystyrene in international vaccine lanes. Legacy packaging manufacturers face stranded asset risk in molded cooler production lines.
Strategic Opportunities
- Indian Cold Chain Modernization:CDSCO good distribution practice enforcement is creating compliant storage demand in Mumbai and Hyderabad pharmaceutical hubs. International logistics operators can partner with domestic cold storage developers.
- Real-Time Visibility Convergence:IoT sensor networks combined with blockchain custody records enable autonomous temperature excursion documentation. Biopharmaceutical shippers are piloting integrated platforms for customs pre-clearance.
- Home Infusion Channel Expansion:Specialty pharmacy direct-to-patient delivery bypasses hospital procurement consolidation. Logistics providers are building nurse-coordinated last-mile networks for temperature-sensitive biologics administration.
Industry Challenges
- Qualified Personnel Scarcity:GDP-certified warehouse operators and cold chain engineers command wage premiums exceeding thirty percent above general logistics salaries. Training programs struggle to match regulatory knowledge requirements.
- Multi-Modal Integration Complexity:Pharmaceutical shipments require seamless temperature documentation across air, ocean, and road legs. Data format incompatibilities between carrier systems create audit trail gaps.
- Serialization System Interoperability:FDA drug supply chain security requirements mandate aggregation at pallet and case levels. Legacy warehouse management systems require expensive middleware upgrades to exchange EPCIS events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Logistics Market |
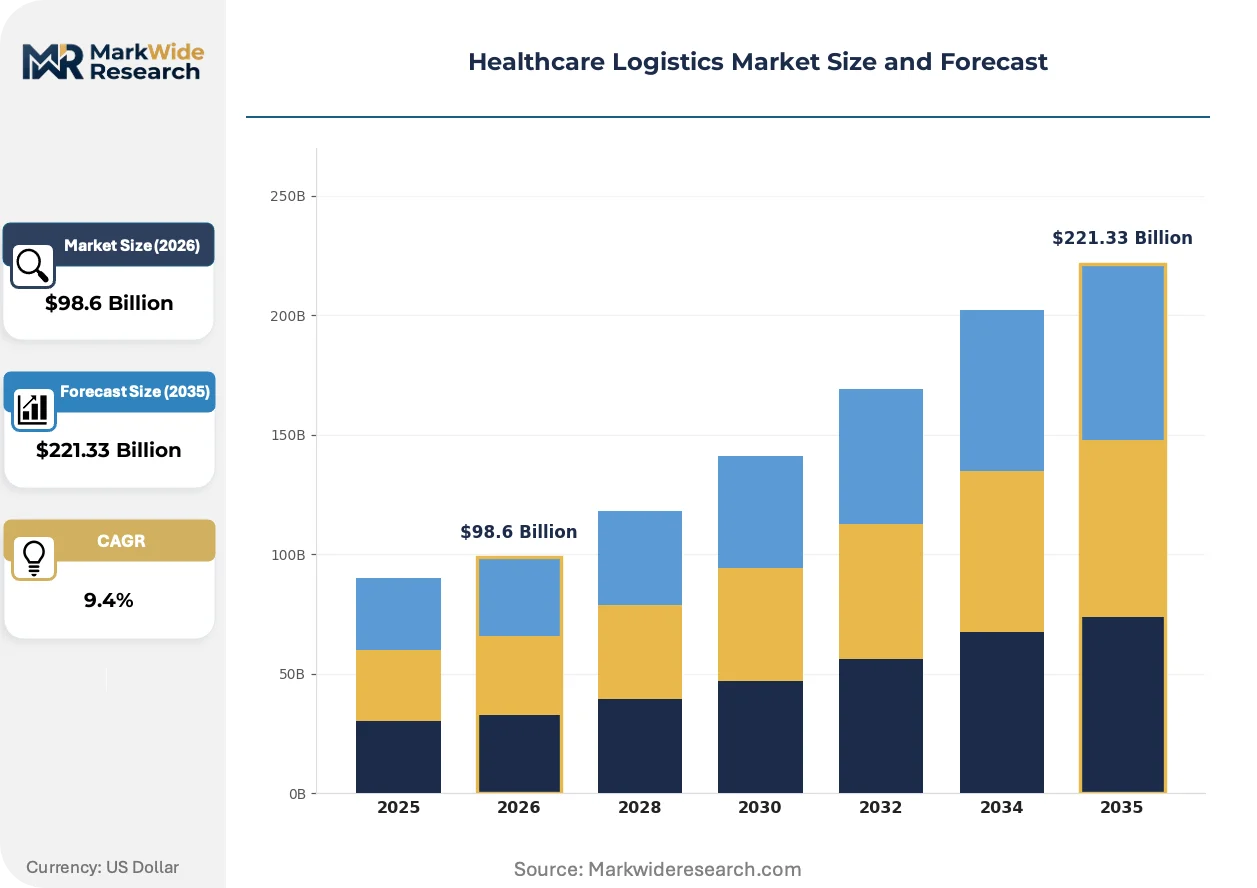
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Direct Delivery, Third-Party Logistics, Cold Chain Logistics, Non-Emergency Medical Transport End User: Pharmacies, Hospitals, Clinics, Rehabilitation Centers Service Type: Warehousing, Distribution Management, Inventory Management, Packaging Solutions Product Type: Medical Supplies, Pharmaceuticals, Medical Equipment, Consumables |
| Companies Covered | DHL Supply Chain, UPS Healthcare, FedEx Supply Chain, Kuehne + Nagel, Cardinal Health, DB Schenker, CEVA Logistics, AmerisourceBergen, GEODIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Logistics Market Emerging Trajectories
Digital twin platforms are compressing validation cycles for new cold chain lanes by simulating thermal performance before physical qualification runs. Biopharmaceutical manufacturers are demanding predictive risk analytics that anticipate temperature excursions before product degradation occurs.
Autonomous mobile robots equipped with temperature-controlled compartments are unifying warehouse picking and transport staging in pharmaceutical distribution centers. DHL Supply Chain has deployed these systems at its Frankfurt campus to reduce human touchpoints in 2-8°C zones. The technology is enabling same-day fulfillment for clinical trial materials without breaking validated environmental conditions.
EMA good distribution practice revisions are mandating risk-based qualification of shipping lanes rather than seasonal revalidation. Pharmaceutical distributors must now maintain continuous temperature monitoring across all transport modes and document corrective actions for every deviation. Small and mid-sized wholesalers in Southern Europe are consolidating to share compliance infrastructure costs.
Hospital procurement consolidation is compressing vendor lists for temperature-controlled distribution to three to five approved logistics partners per therapeutic area. Specialty pharmacy buyers now require lane-level performance scorecards with temperature excursion rates and on-time delivery metrics. This concentration is most visible in German university hospital networks, where centralized purchasing favors 3PLs with integrated European warehouse networks.
Healthcare Logistics Market Segmentation
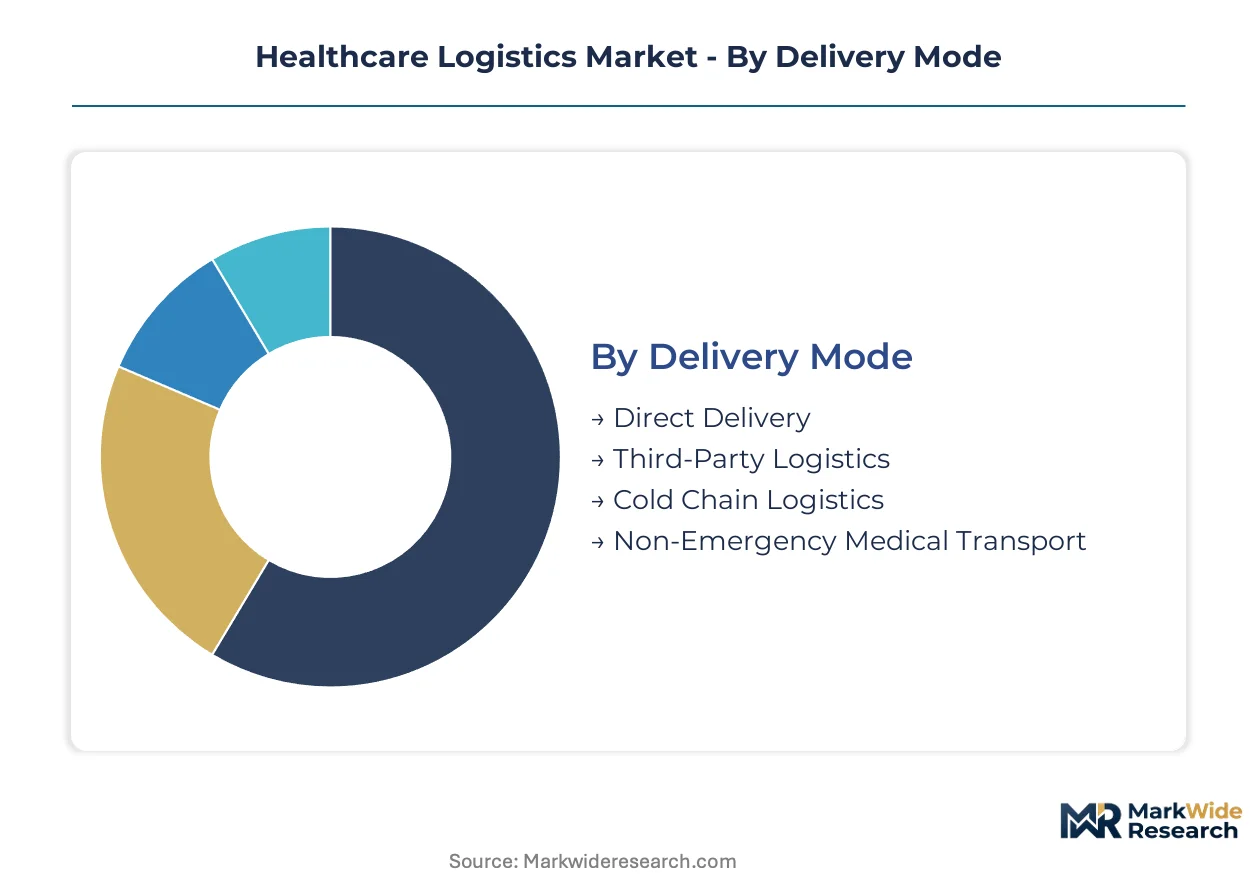
Healthcare logistics segmentation reveals how regulatory complexity fragments service requirements across temperature zones, custody handoffs, and serialization protocols. Each dimension carries distinct compliance burdens that reshape capital allocation and margin structures.
Delivery Mode:
Cold chain logistics demands GDP certification and validated thermal packaging, while direct delivery requires manufacturer-controlled serialization infrastructure.
- Cold Chain Logistics:Maintains 2-8°C or cryogenic conditions through qualified refrigerated vehicles, thermal containers, and continuous temperature monitoring. Demand concentrates in German pharmaceutical clusters serving EMA-regulated vaccine distribution, driven by mRNA platform proliferation requiring -70°C validated lanes.
- Third-Party Logistics:Outsourced custody management combining warehousing, transport, and compliance documentation under single-provider accountability. Hospital procurement consolidation in Kassel and Frankfurt favors 3PLs with integrated European networks and real-time visibility platforms.
- Direct Delivery:Manufacturer-controlled distribution bypassing wholesale intermediaries for high-value biologics. Requires in-house GDP certification and serialization aggregation capabilities.
- Non-Emergency Medical Transport:Scheduled movement of temperature-stable supplies and equipment using standard freight protocols. Serves rehabilitation centers and clinics with lower compliance thresholds.
Cold chain logistics sits at the top of the volume ranking, with third-party logistics climbing the fastest as manufacturers outsource compliance infrastructure.
End User:
Hospital networks impose the most stringent lane-performance scorecards, while pharmacies drive last-mile complexity through direct-to-patient channels.
- Hospitals:Centralized purchasing departments demand temperature excursion documentation and on-time delivery metrics at therapeutic-area level. German university hospital networks favor logistics partners with multi-country warehouse footprints.
- Pharmacies:Specialty pharmacy direct-to-patient delivery requires nurse-coordinated last-mile networks for home biologics administration. CDSCO enforcement in Mumbai and Hyderabad is modernizing compliant storage demand.
- Clinics:Smaller volume receivers dependent on regional distribution hubs for consolidated shipments. Cost sensitivity limits premium cold chain adoption.
- Rehabilitation Centers:Consumables-focused procurement with standardized delivery windows and minimal temperature-controlled requirements.
Hospitals command the highest service premiums, with specialty pharmacy channels expanding most quickly into home infusion logistics.
Service Type:
Warehousing absorbs capital through automated picking systems, while distribution management captures margin through multi-modal integration.
- Warehousing:Temperature-controlled facilities with automated inventory visibility and validated 2-8°C zones. Energy cost volatility in European markets compresses margins for refrigerated assets consuming three to five times baseline industrial power loads.
- Distribution Management:End-to-end custody coordination across air, ocean, and road legs with seamless temperature documentation. Blockchain-integrated IoT networks are piloting autonomous excursion documentation for customs pre-clearance.
- Inventory Management:Real-time stock visibility and demand forecasting for serialization-tracked pharmaceuticals. Requires EPCIS event exchange capabilities.
- Packaging Solutions:Phase-change material shippers and reusable thermal containers displacing single-use expanded polystyrene. Legacy molded cooler manufacturers face stranded asset risk.
Warehousing represents the largest capital deployment, with distribution management gaining share fastest through visibility technology integration.
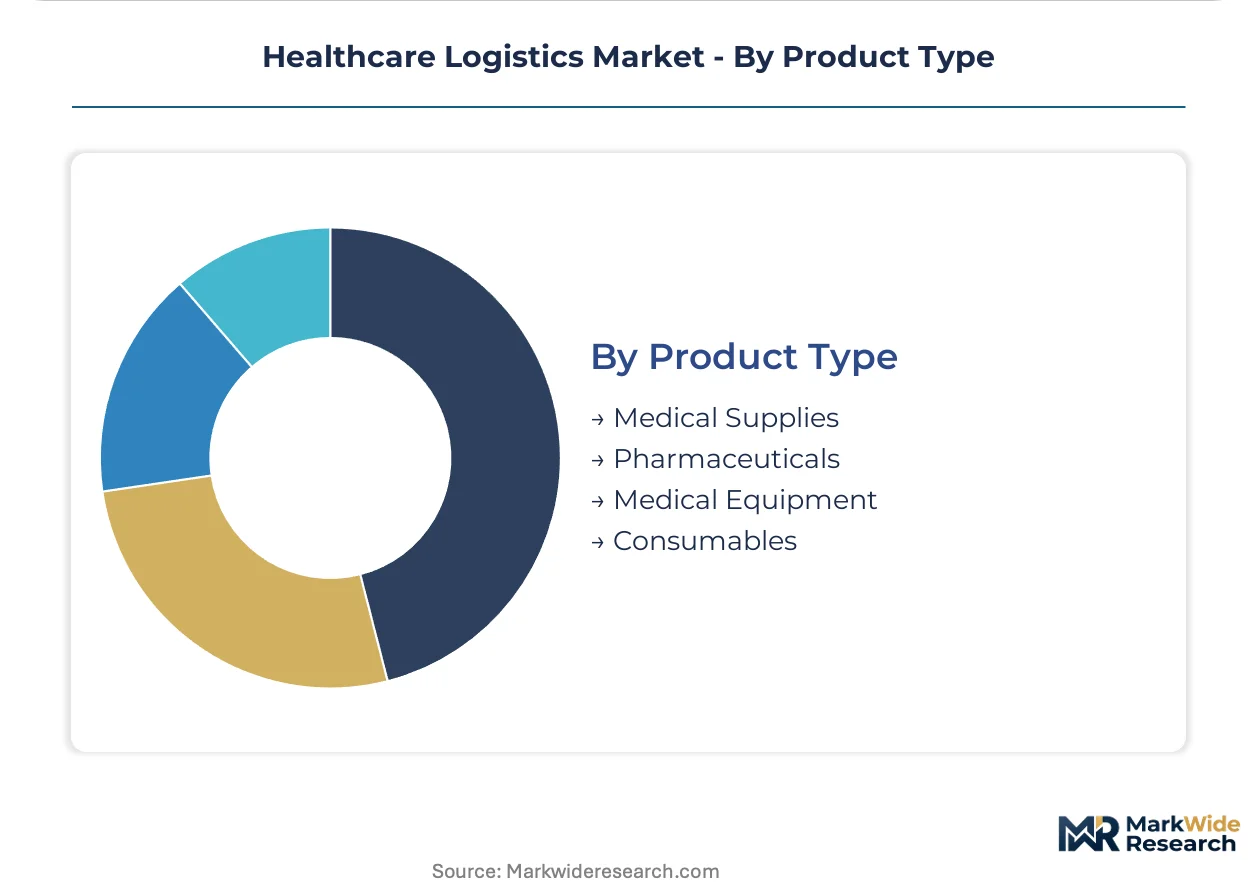
Product Type:
Biologics and cell therapies impose cryogenic handling protocols, while medical equipment permits standard freight with shock protection.
- Pharmaceuticals:Temperature-sensitive small molecules and biologics requiring validated cold chain custody from manufacturer to patient. FDA drug supply chain security mandates and EMA falsified medicines directives force serialization infrastructure replacement before compliance deadlines.
- Medical Supplies:Sterile and non-sterile consumables with varying temperature stability. Demand clusters in pandemic-preparedness stockpiling and routine hospital replenishment.
- Medical Equipment:Diagnostic and therapeutic devices requiring shock-resistant transport and humidity control. Permits standard freight protocols with specialized handling.
- Consumables:Single-use disposables with high turnover and consolidated shipment economics. Price-sensitive procurement favors regional distribution density.
Pharmaceuticals dominate value concentration, with medical supplies expanding most quickly through pandemic-era inventory rebuilding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping pharmaceutical production geography as manufacturers relocate to jurisdictions with lower compliance-cost burdens. FDA and EMA serialization mandates compress margins in mature markets, while CDSCO enforcement in India and NMPA streamlining in China attract cold chain investment. This divergence concentrates high-value biologics logistics in Germany and the United States, with emerging hubs capturing contract manufacturing spillover.
United States
FDA drug supply chain security mandates drive serialization infrastructure replacement across wholesale distributors before 2027 deadlines. Memphis anchors express biologics delivery to East Coast hospitals through temperature-controlled air corridors. Hospital procurement consolidation favors logistics partners with multi-state warehouse networks and real-time visibility platforms.
Germany
The Kassel pharmaceutical cluster anchors European vaccine distribution, with EMA falsified medicines directives accelerating hardware deployment across distribution centers. Energy cost volatility compresses margins for refrigerated warehousing consuming three to five times baseline industrial power loads. Frankfurt temperature-controlled campuses serve as consolidation points for cross-border pharmaceutical movements.
Switzerland
Swissmedic oversight of gene therapy exports demands cryogenic logistics infrastructure commanding premium service margins. Basel proximity to Novartis and Roche dominates Swiss pharma exports through validated -70°C container fleets. Small and mid-sized wholesalers face eighteen to twenty-four month qualification timelines for GDP-certified operations.
India
CDSCO good distribution practice enforcement creates compliant storage demand in Mumbai and Hyderabad pharmaceutical hubs. International logistics operators partner with domestic cold storage developers to capture contract manufacturing organization spillover. Phase-change material shippers displace single-use expanded polystyrene in international vaccine lanes from Indian manufacturing clusters.
China
NMPA serialization requirements converge with FDA and EMA standards, reducing regulatory arbitrage for export-oriented biopharmaceutical manufacturers. Yangtze River Delta cold storage developers expand automated picking systems for 2-8°C pharmaceutical zones. Domestic logistics providers build nurse-coordinated last-mile networks for specialty pharmacy direct-to-patient delivery.
Healthcare Logistics Market Vendor Landscape
German and Swiss operators anchor one tier of pharmaceutical logistics; United States-based express carriers hold another through Memphis and Louisville air hubs. The market structure concentrates around integrated third-party logistics providers with multi-country warehouse footprints and GDP-certified operations. Three archetypes dominate: global integrators with owned air networks, regional specialists with pharma-proximate real estate, and healthcare-dedicated divisions of diversified logistics conglomerates. Competitive moves center on automated warehouse deployment and strategic partnerships with biopharmaceutical manufacturers for end-to-end custody contracts.
Within the global integrator tier, DHL Supply Chain and FedEx Supply Chain exemplify scale-driven positioning through temperature-controlled campuses and express lane networks. Kuehne + Nagel occupies a position among European specialists leveraging Basel and Frankfurt proximity to major pharmaceutical manufacturers. These three entities represent contrasting geographic and service-model archetypes: German-owned global networks, United States-based express infrastructure, and Swiss-anchored regional dominance.
| Leading Market Players |
|---|
| DHL Supply Chain |
| UPS Healthcare |
| FedEx Supply Chain |
| Kuehne + Nagel |
| Cardinal Health |
| DB Schenker |
| CEVA Logistics |
| AmerisourceBergen |
| GEODIS |
| Others |
Supply Flow & Price Mechanics
Energy cost volatility in German refrigerated warehousing cascades through pharmaceutical logistics pricing tiers, compressing margins for temperature-controlled facilities consuming three to five times baseline industrial power loads while hospital procurement consolidation favors 3PLs with integrated European networks commanding service premiums.
Pricing Analysis
Distributor margins in pharmaceutical logistics stratify across GDP certification tiers, with premium pricing attached to validated -70°C cryogenic lanes versus standard 2-8°C cold chain services. Price differentiation hinges on serialization compliance infrastructure and real-time visibility platform integration. Cost compression in European warehousing intensifies pricing pressure because electricity price spikes erode refrigerated asset returns. Generic pharmaceutical distributors exhibit highest price sensitivity, while cell and gene therapy manufacturers accept premium service margins for cryogenic custody.
Supply Chain Analysis
GDP certification gates qualified carrier capacity to an eighteen to twenty-four month qualification timeline, concentrating specialized refrigerated truck fleets with certified operators in Germany and the Netherlands. Raw material dependencies center on dry ice production capacity, phase-change material thermal containers, and IoT temperature sensors. Single-source vulnerability runs through limited pools of GDP-certified warehouse operators commanding wage premiums exceeding thirty percent above general logistics salaries. Distribution runs through multi-modal integration across air, road, and ocean legs with seamless temperature documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare logistics offers margin expansion through automation-driven cost reduction in warehouse picking and premium-tier capture via cryogenic logistics infrastructure for cell and gene therapies.
For Market Incumbents: Anchor market position through automated mobile robot deployment in 2-8°C zones to reduce human touchpoints and labor cost exposure. Expand dry ice production capacity near Kassel and Frankfurt manufacturing clusters to capture mRNA platform logistics demand. Defend against emerging cold chain specialists by deepening upstream control over thermal packaging production. For New Entrants and Emerging Players: CDSCO good distribution practice enforcement in India opens a window for compliant storage partnerships in Mumbai and Hyderabad pharmaceutical hubs. Target specialty pharmacy direct-to-patient channels where nurse-coordinated last-mile networks remain underdeveloped. Enter through white-label distribution management services for mid-sized biopharmaceutical manufacturers lacking in-house serialization aggregation capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where small and mid-sized wholesalers in Southern Europe face shared compliance infrastructure cost burdens. Five-to-ten year viability favors 3PLs with multi-country warehouse footprints and real-time visibility platform integration. Watch EMA-FDA regulatory convergence as inflection indicator for serialization middleware upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Deployment | DHL Supply Chain's Frankfurt campus demonstrates mobile robot integration reducing human touchpoints in validated cold zones. |
| Cryogenic Infrastructure Expansion | Dry ice production capacity near German manufacturing clusters captures mRNA vaccine platform logistics demand. |
| Real-Time Visibility Platform Integration | Blockchain-IoT sensor networks enable autonomous temperature excursion documentation for customs pre-clearance. |
| Specialty Pharmacy Last-Mile Buildout | Nurse-coordinated networks bypass hospital procurement consolidation for home biologics administration. |
| Indian Cold Storage Partnership | CDSCO enforcement in Mumbai and Hyderabad creates compliant storage demand for contract manufacturing spillover. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cold chain engineers, GDP-certified warehouse operators, hospital procurement managers, and biopharmaceutical supply chain directors with secondary validation against FDA filings, EMA submissions, WHO temperature excursion guidelines, and EU GDP standards. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions.
Segment-weighting approaches modeled delivery mode, end user, service type, and product type dimensions across the analysis window, with temperature zone requirements and serialization protocol complexity as healthcare-specific forecast inputs. CAGRs derived from historical trend extrapolation adjusted for regulatory mandate acceleration and biologics pipeline expansion rates.
Revisions become necessary when energy cost volatility, qualified personnel scarcity, or serialization system interoperability failures materialize beyond modeled assumptions. Forecasts reflect documented assumptions about EMA-FDA regulatory convergence timelines and cold chain validation requirement extensions. A model refresh is warranted upon material change in biologics volume expansion rates or hospital procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Canada Senior Living Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
US Care Services Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
US Medical Billing Outsourcing Market
Healthcare Services
Michigan Urgent Care Center Market