
 France Diabetes Drugs Market | 2026-2036
France Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
France Diabetes Drugs Market Foresight
A shortage of certified diabetologists is redrawing prescribing authority across France's regional hospital networks. Sanofi leverages its entrenched insulin portfolio to sustain manufacturing presence in suburban Paris. Novo Nordisk anchors the GLP-1 segment through specialized endocrinology channel control. Eli Lilly and Company competes on once-weekly formulation technology leadership.
France diabetes drugs comprise pharmaceutical agents designed to modulate blood glucose homeostasis through insulin replacement, secretion enhancement, or renal glucose excretion inhibition, typically formulated as injectable biologics or oral small molecules with defined pharmacokinetic profiles for HbA1c reduction. Their primary purpose is preventing microvascular and macrovascular complications in chronic diabetes management. GLP-1 receptor agonists and SGLT2 inhibitors now command the fastest expansion as cardiorenal outcome data reshapes prescribing hierarchies. Insulin retains structural dominance in Type 1 diabetes applications where absolute deficiency mandates exogenous replacement. Hospital pharmacies and retail pharmacies split distribution influence, with hospital tender processes governing high-cost biologic access.
ANSM enforces post-market cardiovascular safety surveillance that elevates evidence thresholds for new molecular entities seeking reimbursement under France's statutory health insurance. EMA centralized marketing authorization procedures streamline pan-European access while preserving national HTA discretion through HAS therapeutic value assessments. Stakeholders must monitor HAS transparency commission rulings on innovation premium eligibility, as these determinations directly shape commercial viability for next-generation combination therapies entering French reimbursement lists.
Market Dynamics
ANSM pharmacovigilance requirements for cardiovascular outcome data are compressing development timelines and elevating evidence thresholds for new molecular entities entering French reimbursement lists.
Growth Catalysts
- GLP-1 receptor agonist expansion:Endocrinology departments in public hospitals are expanding prescribing authority for these agents as cardiorenal outcome data reshapes treatment hierarchies.
- HAS innovation premium eligibility:Transparency commission rulings on therapeutic value assessments create direct commercial incentives for next-generation combination therapies.
- Île-de-France specialized center concentration:Clustering of academic hospitals around Paris generates referral density that accelerates adoption of novel biologic formulations.
Market Restraints
- Certified diabetologist scarcity:Regional hospital networks face structural shortages of specialists, redrawing prescribing authority toward general practitioners with limited biologic familiarity.
- Hospital tender concentration:High-cost biologic access depends on centralized hospital pharmacy procurement processes that create access bottlenecks outside major urban centers.
- Statutory health insurance reimbursement rigidity:Fixed pricing frameworks under France's national health insurance limit premium capture for novel formulations despite superior clinical profiles.
Strategic Opportunities
- Once-weekly formulation penetration:Extended-release injectable technologies offer adherence advantages in Type 2 diabetes management outside insulin-dependent populations.
- SGLT2 inhibitor cardiorenal positioning:Heart failure and chronic kidney disease label expansions create new prescriber touchpoints beyond endocrinology into cardiology and nephrology.
- Retail pharmacy channel development:Orally administered agents with established safety profiles can bypass hospital tender barriers through community pharmacy distribution networks.
Industry Challenges
- Post-market surveillance infrastructure:ANSM cardiovascular safety monitoring requirements demand ongoing outcome data collection that strains pharmacovigilance resources.
- EMA-HAS regulatory misalignment:Centralized marketing authorization procedures sometimes conflict with national health technology assessment timelines, delaying commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Diabetes Drugs Market |
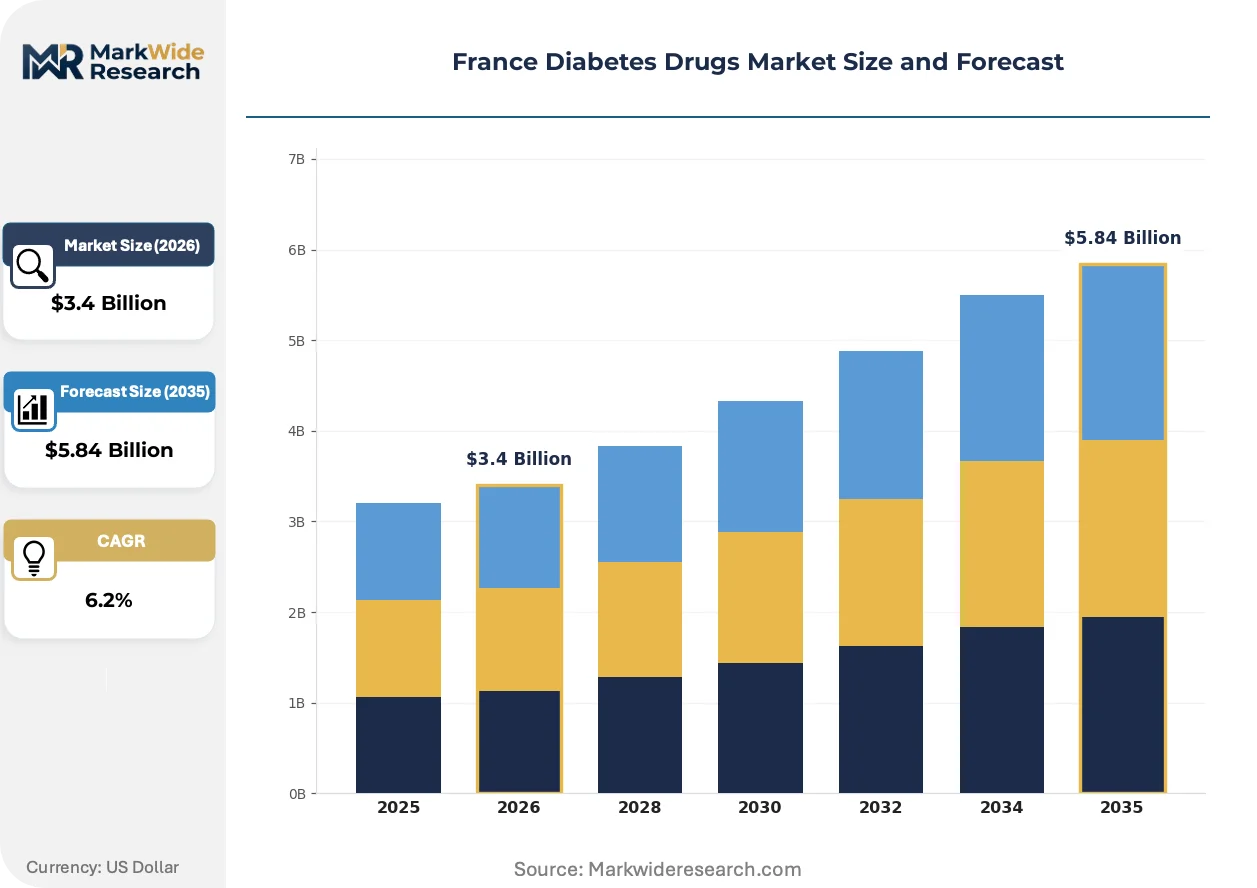
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Biguanides, Sulfonylureas, DPP-4 Inhibitors, GLP-1 Receptor Agonists, SGLT2 Inhibitors Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Diabetic Neuropathy, Diabetic Retinopathy, Diabetic Nephropathy End User: Hospitals, Diabetes Clinics, Research Institutes, Pharmacies, Home Care Providers, Diagnostic Centers Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Government Tender, Private Distributors, Direct Sales |
| Companies Covered | AstraZeneca, Merck and Co., Sanofi, Pfizer, Takeda, Novo Nordisk, Boehringer Ingelheim, Janssen Pharmaceuticals, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Diabetes Drugs Market Shifts & Advancements
Formulation technology and regulatory science are converging to redefine competitive advantage in French diabetes care, with evidence generation and channel strategy now inseparable from product design.
Once-weekly GLP-1 receptor agonist formulations are supplanting daily and twice-daily injectable regimens in Type 2 diabetes management. Hospital endocrinology departments in Parisian academic centers are prioritizing these agents for treatment-naïve patients. This shift is compressing market access timelines for legacy daily formulations while rewarding manufacturing scale in sustained-release delivery systems.
EMA centralized marketing authorization procedures are streamlining pan-European market entry while preserving HAS national discretion over reimbursement rates. French manufacturers must now synchronize clinical trial design with both cardiovascular outcome requirements and health economic modeling. Biologic developers with integrated evidence-generation capabilities are capturing disproportionate tender share in Île-de-France hospital networks.
Specialized diabetes centers are consolidating referral patterns around academic hospitals, compressing geographic variation in prescribing behavior. Regional hospital networks outside Paris are losing endocrinology capacity to urban concentration, shifting stable patients toward retail pharmacy channels. This geographic rotation is most visible in Provence-Alpes-Côte d'Azur and Auvergne-Rhône-Alpes, where satellite clinics now manage continuation therapy.
France Diabetes Drugs Market Segmentation
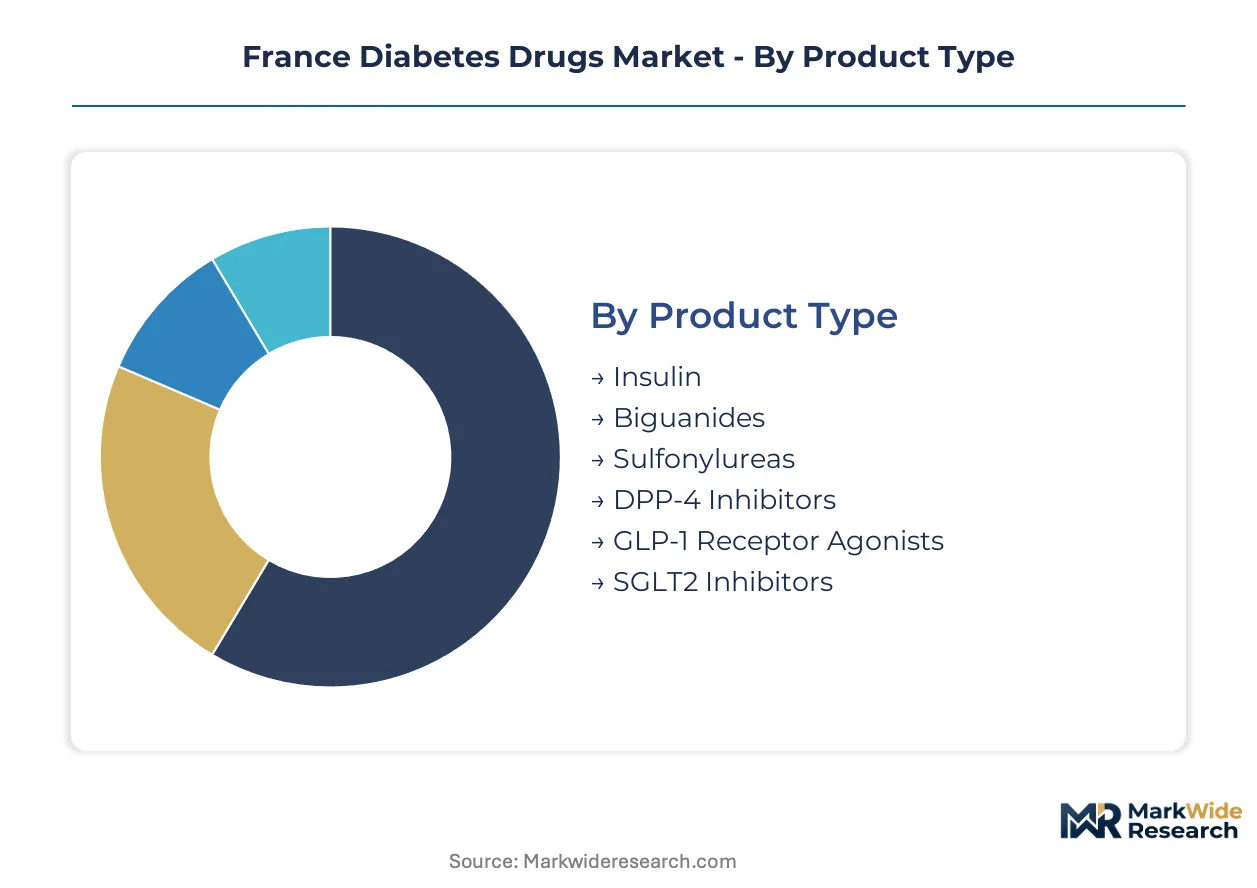
Channel configuration in France diabetes drugs varies sharply by segment, with hospital tenders governing biologic access while retail networks handle oral agents. Understanding these flow patterns enables targeted commercial strategy across the Île-de-France concentration and regional periphery.
Product Type:
Hospital pharmacy procurement controls high-cost biologics, whereas retail channels dominate oral small molecules with established safety profiles.
- Insulin:Recombinant human and analog formulations administered via subcutaneous injection remain mandatory for Type 1 diabetes management. Demand concentrates in pediatric and adult endocrinology departments at Assistance Publique-Hôpitaux de Paris facilities, where centralized tender processes favor manufacturers with suburban Paris manufacturing presence.
- GLP-1 Receptor Agonists:Injectable incretin mimetics with sustained-release formulations now anchor Type 2 diabetes protocols in academic hospital networks. Île-de-France specialized centers drive adoption of once-weekly variants, compressing market access timelines for legacy daily formulations.
- SGLT2 Inhibitors:Oral sodium-glucose cotransporter-2 blockers with cardiorenal outcome data are expanding into cardiology and nephrology prescribing.
- DPP-4 Inhibitors:Oral dipeptidyl peptidase-4 inhibitors occupy a middle tier in combination therapy protocols.
- Biguanides:Metformin-based first-line therapy remains volume-dominant through retail pharmacy channels.
- Sulfonylureas:Older insulin secretagogues face declining share amid cardiovascular safety concerns.
By volume, Biguanides leads. By growth pace, GLP-1 Receptor Agonists is expanding most quickly.
Application:
Cost tier stratification separates chronic maintenance indications from acute complication management, with reimbursement intensity varying accordingly.
- Type 2 Diabetes:The predominant addressable population drives pharmaceutical innovation investment and formulation technology competition. Prescribing authority is redrawing toward general practitioners outside Parisian academic centers due to certified diabetologist scarcity in regional hospital networks.
- Type 1 Diabetes:Absolute insulin deficiency mandates exogenous replacement with no oral alternative, creating captive demand for injectable biologics. Pediatric endocrinology departments at Necker-Enfants Malades and Robert Debré hospitals anchor specialized care concentration in Paris.
- Gestational Diabetes:Pregnancy-specific glycemic control requires tight monitoring protocols with limited pharmacologic options.
- Diabetic Neuropathy:Microvascular complication management extends prescribing into pain medicine and neurology channels.
- Diabetic Retinopathy:Ophthalmology crossover creates biologic opportunity in anti-VEGF adjunct therapy.
- Diabetic Nephropathy:Nephrology department engagement is climbing the fastest for SGLT2 inhibitor cardiorenal positioning.
By patient volume, Type 2 Diabetes dominates. By therapeutic innovation intensity, Type 1 Diabetes commands disproportionate R&D allocation.
End User:
Customer type fragmentation reflects the split between acute care settings and chronic disease management infrastructure across French territories.
- Hospitals:Public hospital endocrinology departments govern biologic initiation and high-cost therapy access through ANSM-mandated pharmacovigilance protocols. Tender concentration at AP-HP and regional university hospital centers creates procurement bottlenecks.
- Diabetes Clinics:Specialized outpatient facilities in Île-de-France academic hospital networks drive adoption of novel formulations and combination therapies.
- Pharmacies:Community retail networks handle continuation therapy for stable patients, particularly oral agents with established safety profiles.
- Home Care Providers:Nursing services support insulin-dependent patients in regional territories with limited endocrinology access.
- Research Institutes:Academic medical centers generate cardiovascular outcome data required for HAS reimbursement eligibility.
- Diagnostic Centers:HbA1c and continuous glucose monitoring facilities feed patient flow into prescribing channels.
By prescription volume, Pharmacies leads. By therapy complexity concentration, Hospitals is ahead.
Distribution Channel:
Supply concentration in hospital procurement creates access stratification between urban centers and regional territories.
- Hospital Pharmacies:Centralized procurement at public hospital networks governs access to GLP-1 receptor agonists and insulin analogs above reimbursement thresholds. ANSM pharmacovigilance requirements elevate evidence standards for formulary inclusion.
- Retail Pharmacies:Community-based distribution networks bypass tender barriers for oral agents with HAS-established therapeutic value ratings, enabling geographic reach into Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur satellite clinics.
- Government Tender:National procurement processes for statutory health insurance reimbursement create price compression on mature therapeutic categories.
- Online Pharmacies:Digital channels face regulatory constraints under CNIL data protection and ANSM traceability requirements.
- Private Distributors:Specialized logistics providers handle cold-chain biologics for hospital networks.
- Direct Sales:Manufacturer-to-institution arrangements concentrate in Parisian academic medical centers.
By transaction volume, Retail Pharmacies leads. By value concentration, Hospital Pharmacies is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Île-de-France exceeds that of Auvergne-Rhône-Alpes by a substantial margin, reflecting the concentration of specialized diabetes centers and academic hospital networks around Paris. This asymmetry shapes procurement patterns and reimbursement negotiations across French territories.
Île-de-France
Academic hospitals at Assistance Publique-Hôpitaux de Paris drive adoption of once-weekly GLP-1 receptor agonists through centralized tender processes. ANSM pharmacovigilance protocols mandate cardiovascular outcome data collection for formulary inclusion. The Paris cluster concentrates pediatric endocrinology capacity at Necker-Enfants Malades and Robert Debré hospitals, anchoring national Type 1 diabetes care standards.
Auvergne-Rhône-Alpes
Satellite clinics in Lyon and Grenoble manage continuation therapy for stable Type 2 patients as certified diabetologist scarcity shifts prescribing toward general practitioners. HAS transparency commission rulings on therapeutic value assessments determine reimbursement eligibility for novel oral agents. The Lyon metropolitan area maintains secondary referral capacity but loses complex biologic initiation cases to Parisian centers.
Provence-Alpes-Côte d'Azur
Retail pharmacy networks in Marseille and Nice handle substantial oral agent volume as hospital endocrinology departments face capacity constraints. Statutory health insurance reimbursement rigidity under France's national health insurance limits premium capture for novel formulations. The Aix-Marseille University Hospital network retains limited biologic tender authority compared to northern academic centers.
Hauts-de-France
Industrial pharmaceutical manufacturing presence in suburban Paris extends into this northern region, sustaining insulin production infrastructure. EMA centralized marketing authorization procedures streamline pan-European access while preserving HAS national discretion. Lille University Hospital maintains regional referral capacity for complex diabetes cases, though Paris remains the ultimate escalation pathway.
Nouvelle-Aquitaine
Bordeaux University Hospital anchors cardiorenal outcome research for SGLT2 inhibitor label expansion into heart failure indications. CNIL data protection requirements constrain digital pharmacy channel development for patient monitoring platforms. The southwestern region exhibits lower prescriber density in endocrinology, accelerating the shift toward retail pharmacy-managed oral therapy.
France Diabetes Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the France diabetes drugs market, creating a tiered competitive structure. The market consolidates around manufacturers with integrated evidence-generation capabilities and sustained-release formulation expertise. Three archetypes dominate: Big Pharma incumbents with entrenched insulin portfolios, GLP-1 specialists controlling endocrinology channel access, and cardiorenal outcome innovators expanding into nephrology and cardiology touchpoints. Competitive moves center on M&A for manufacturing scale and strategic partnerships for hospital tender positioning.
Among the established pharmaceutical manufacturers, Sanofi leverages its suburban Paris manufacturing presence to anchor insulin supply relationships with AP-HP networks. Novo Nordisk occupies the GLP-1 specialist position through specialized endocrinology channel control in Île-de-France academic centers. Eli Lilly and Company represents the formulation technology leader, competing on once-weekly injectable platforms that compress market access timelines for legacy daily regimens.
| Leading Market Players |
|---|
| AstraZeneca |
| Merck and Co. |
| Sanofi |
| Pfizer |
| Takeda |
| Novo Nordisk |
| Boehringer Ingelheim |
| Janssen Pharmaceuticals |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day tender cycles at Assistance Publique-Hôpitaux de Paris compress supplier negotiation windows while amplifying price leverage for high-volume biologic procurement. This lead-time compression concentrates purchasing power within Île-de-France hospital networks, forcing manufacturers to absorb cold-chain logistics costs into net pricing.
Pricing Analysis
Île-de-France commands a 15-20% premium over Auvergne-Rhône-Alpes for identical GLP-1 receptor agonist formulations, reflecting Parisian academic hospital concentration and tender density. The market operates on a contract-based long-term offtake model with HAS innovation premium eligibility creating tiered access. Price differentiation hinges on cardiovascular outcome data quality and endocrinology department formulary status. Pricing pressure stems from statutory health insurance reimbursement rigidity, with community pharmacies in Provence-Alpes-Côte d'Azur exhibiting highest price sensitivity due to capped margins on oral generics.
Supply Chain Analysis
Just-in-time inventory protocols dominate insulin distribution, with suburban Paris manufacturing sites maintaining 7-10 days of finished goods to serve AP-HP networks. Active pharmaceutical ingredient supply draws from Denmark, Germany, and Ireland for biologic fermentation and purification. Cold-chain biologics rest on temperature-controlled logistics infrastructure with single-source vulnerability at specialized courier networks. Distribution runs through hospital pharmacy procurement for high-cost agents, while retail channels handle oral small molecules with established stability profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from patient monitoring platforms and adherence coaching is expanding faster than molecule sales, creating recurring revenue architecture for manufacturers with data infrastructure. This service layer repositions diabetes management from transactional dispensing toward longitudinal care relationships.
For Market Incumbents: Consolidate manufacturing presence in suburban Paris to defend AP-HP tender share against Danish and US competitors with centralized European distribution. Backward integration into sustained-release formulation technology protects margin position as once-weekly regimens displace daily injectables. Channel control through specialized endocrinology relationships remains the priority lever against general practitioner prescribing expansion.
For New Entrants and Emerging Players: EMA centralized marketing authorization fast-track for cardiorenal outcome trials offers the most viable entry path for SGLT2 inhibitor innovators seeking HAS reimbursement eligibility. White-space concentrates in retail pharmacy-managed oral therapy for stable Type 2 patients outside Parisian referral networks. Geographic targeting of Auvergne-Rhône-Alpes satellite clinics with pharmacist-led adherence programs bypasses hospital tender barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a evidence-generation infrastructure play because cardiovascular outcome data requirements are elevating barriers for asset-light competitors. Acquisition targets with integrated pharmacovigilance capabilities and HAS negotiation track record command strategic premium. The signal to watch is ANSM post-market surveillance mandate expansion, which would accelerate consolidation around compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcome trials at Bordeaux University Hospital accelerate SGLT2 inhibitor label expansion into heart failure indications. |
| Regulatory Approval Pathway | EMA centralized procedures with synchronized HAS health economic modeling compress time-to-reimbursement for novel formulations. |
| Manufacturing Scale-Up | Sustained-release injectable capacity expansion in Île-de-France secures tender share for once-weekly GLP-1 variants. |
| Hospital System Partnership | Direct arrangements with AP-HP endocrinology departments bypass procurement bottlenecks for high-cost biologic initiation. |
| Reimbursement Strategy | HAS transparency commission engagement determines innovation premium eligibility for combination therapy market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANSM pharmacovigilance databases, EMA centralized marketing authorization submissions, HAS transparency commission rulings, and ClinicalTrials.gov cardiovascular outcome trial registrations. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers at AP-HP and regional university hospitals, and payer access specialists informed demand-side validation. Bottom-up patient volume modeling and top-down pharmaceutical sales triangulation anchored market sizing.
Segmentation dimensions modeled include product type, application, end user, and distribution channel across the analysis window, with regional regulatory clusters capturing ANSM, HAS, and CNIL compliance variations. CAGRs were derived from treatment protocol adoption curves and reimbursement list expansion timelines. Forecast inputs incorporated certified diabetologist supply constraints and hospital endocrinology capacity migration patterns.
Underlying assumptions cover stable statutory health insurance reimbursement frameworks and continued EMA-HAS regulatory alignment, with deviation risk concentrated in ANSM cardiovascular safety mandate intensification and regional hospital network restructuring. Revision becomes warranted when HAS innovation premium eligibility criteria cross thresholds that exclude current pipeline candidates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Stomach Cancer Drugs Market