
 European Union Cross Border Healthcare Market | 2026-2036
European Union Cross Border Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
European Union Cross Border Healthcare Market Foresight
Nursing workforce mobility across Schengen borders is unwinding capacity bottlenecks that long constrained patient throughput in destination clinics. MediBridge Europe leverages pan-European hospital networks to coordinate pre-authorization and post-procedure follow-up across jurisdictions. SalusConnect sustains digital patient records that comply with divergent national data-protection requirements. ClinRoute anchors its competitive position on ground logistics spanning ambulance transfers, accommodation, and interpreter services.
European Union cross-border healthcare encompasses the lawful provision of medical services to patients residing in one member state by providers established in another, governed by the Directive on Patients' Rights in Cross-Border Healthcare and subsequent implementing regulations that establish reimbursement frameworks, quality standards, and information transparency obligations. The system operates through prior authorization pathways for hospital care and simplified notification procedures for ambulatory services, with electronic health record interoperability emerging as a critical functional parameter for seamless continuity of care. Diagnostics and surgery dominate service-type revenue pools, reflecting high unit costs and established clinical tourism corridors into Poland, Hungary, and the Czech Republic. Orthopedics leads procedure-type demand as aging demographics in Germany, France, and the Netherlands drive elective joint replacement seekers toward cost-competitive Central European centers.
The European Commission, EMA, and national health technology assessment bodies such as NICE in the United Kingdom and HAS in France shape market access through divergent reimbursement catalogs and quality accreditation schemes that providers must navigate to attract foreign patients. GDPR and national medical-data sovereignty laws impose stringent cross-border data-transfer protocols that elevate compliance costs for digital health intermediaries while creating competitive moats for established operators. Stakeholders must monitor the evolution of EU-wide electronic health record standards and the European Health Data Space initiative to anticipate where regulatory harmonization will compress or expand arbitrage opportunities between member-state healthcare systems.
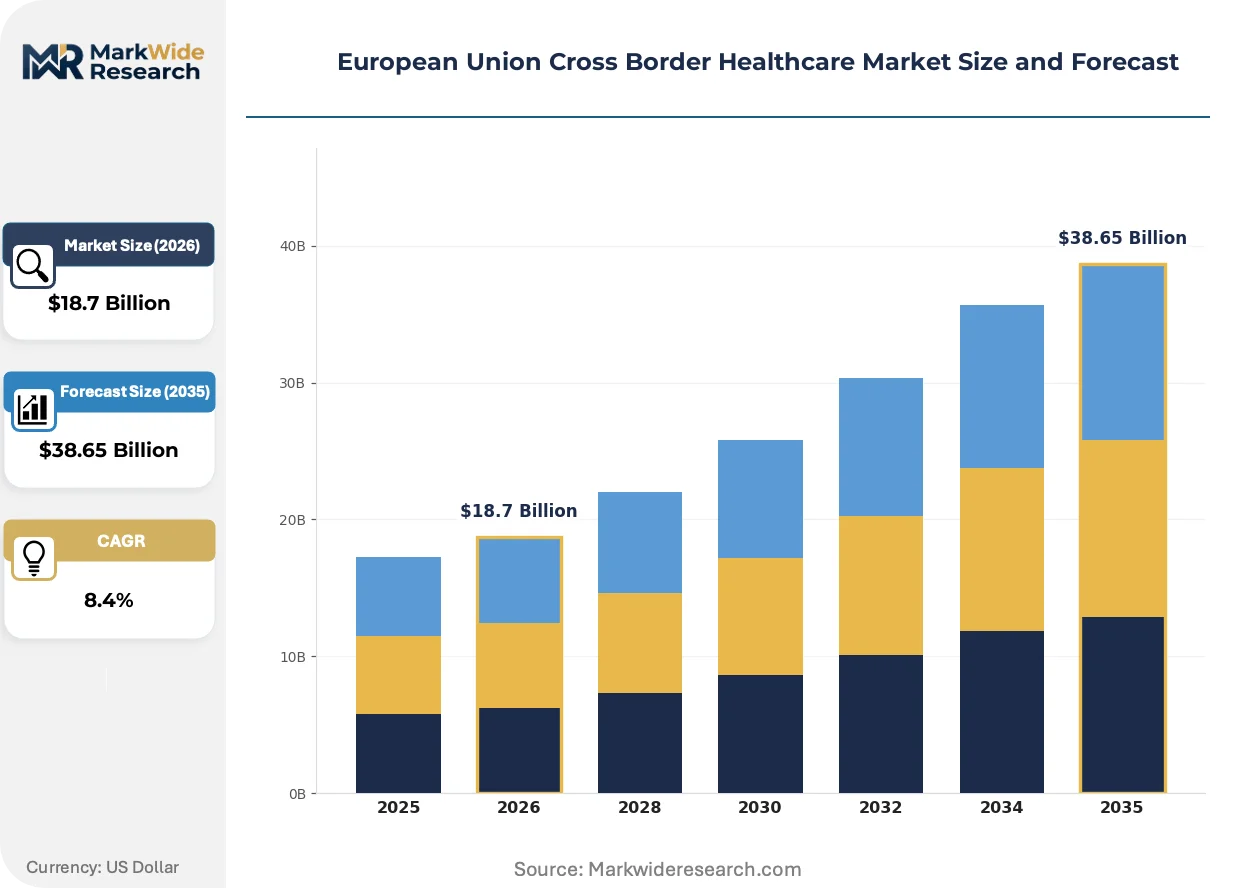
Market Dynamics
The Directive on Patients' Rights in Cross-Border Healthcare is dissolving long-standing administrative barriers that previously trapped patients within national health systems. Digital health record interoperability under the European Health Data Space initiative is now the decisive variable determining which intermediaries capture patient flow.
Growth Catalysts
- Nursing workforce mobility:Schengen labor mobility rules are unwinding capacity bottlenecks in Polish and Hungarian destination clinics, expanding patient throughput without proportional capital investment.
- Cost arbitrage corridors:Elective orthopedic procedures in Central European member states offer price differentials that attract aging German, French, and Dutch patient cohorts seeking joint replacements.
- GDPR-compliant data architectures:Standardized cross-border data-transfer protocols under EU medical-data sovereignty frameworks are reducing compliance friction for digital health intermediaries.
Market Restraints
- Reimbursement catalog divergence:National health technology assessment bodies such as NICE and HAS maintain divergent coverage catalogs that fragment patient eligibility across member states.
- Medical-data sovereignty compliance:GDPR and national medical-data laws impose stringent cross-border transfer protocols that elevate operating costs for pan-European record systems.
- Prior authorization bottlenecks:Hospital care pathways still require case-by-case pre-approval from home-country insurers, creating administrative drag that ambulatory services bypass.
Strategic Opportunities
- Romanian and Bulgarian clinic networks:These member states retain untapped cost-competitive capacity that Western European patient brokers have yet to systematically develop.
- Telemedicine-integrated follow-up:Remote post-procedure monitoring converges with mobile health platforms to reduce travel burdens for cross-border patients.
- European Health Data Space harmonization:Pending EU-wide electronic health record standards will compress regulatory arbitrage costs for early-compliant intermediaries.
Industry Challenges
- Interpreter and cultural competency staffing:Patient-facing services require multilingual clinical coordinators that destination clinics struggle to recruit at scale.
- Ground logistics coordination:Ambulance transfers, accommodation booking, and post-discharge transport demand operational capabilities that diverge from core clinical competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Union Cross Border Healthcare Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Surgery, Rehabilitation, Diagnostics Patient Type: Inpatients, Outpatients, Emergency Patients, Scheduled Patients Payment Model: Insurance-Based, Out-of-Pocket, Government-Funded, Employer-Sponsored Procedure Type: Cardiology, Orthopedics, Oncology, Neurology |
| Companies Covered | MediBridge Europe, SalusConnect, ClinRoute, CareWay Mobility Services, MedTour Direct, EuroHealth Access, TransMedic Pathways, VitaCross Europe, Panacea Mobility Solutions, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Union Cross Border Healthcare Market Shifts & Advancements
Digital intermediation is restructuring how patients discover, book, and manage cross-border care. Three forces are compressing the role of traditional referral networks while elevating platform-based coordination.
Interoperable electronic health record systems are fragmenting the patient data landscape that once favored incumbent hospital networks. Polish and Hungarian destination clinics are adopting HL7 FHIR standards at accelerating pace. This technology is fragmenting information monopolies that previously locked patients into domestic provider relationships.
REACH and the EU AI Act are imposing algorithmic transparency requirements on diagnostic tools used in cross-border telemedicine consultations. Medical device software now faces heightened scrutiny for bias and explainability. Radiology AI platforms serving German patients from Czech facilities are restructuring compliance teams to meet these mandates.
Patients are consolidating booking decisions through specialized comparison platforms that aggregate accreditation status, price, and outcome data. Traditional physician referral channels are losing share to digital intermediaries that bundle pre-authorization support with travel logistics. This behavioral shift is most visible among Dutch and Belgian patients seeking elective procedures in Budapest and Kraków.
European Union Cross Border Healthcare Market Segmentation
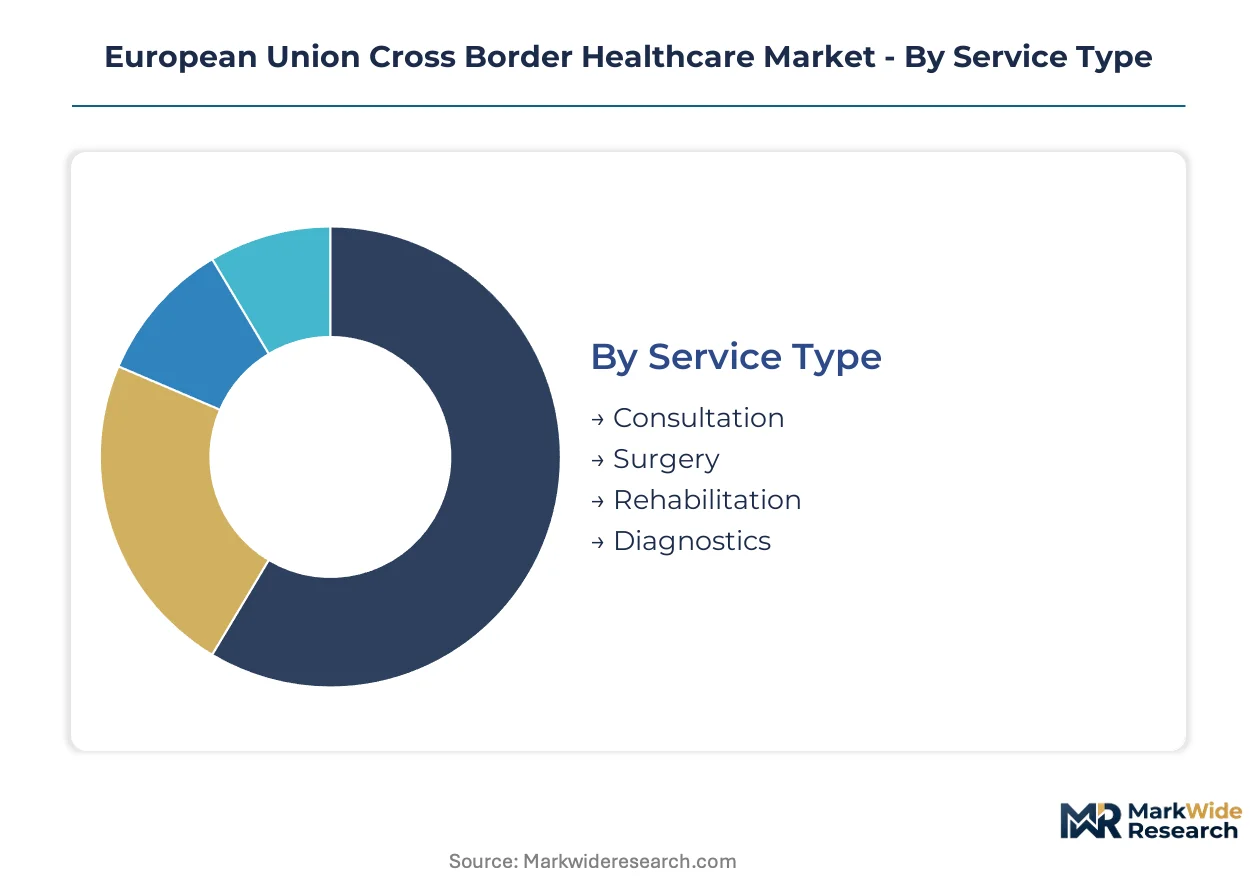
Cross-border healthcare flows concentrate around high-margin, schedulable interventions where price differentials justify travel friction. Segment boundaries are blurring as digital intermediaries bundle diagnostics, surgery, and rehabilitation into single-journey packages.
Service Type:
Margin pools concentrate in procedures requiring capital-intensive infrastructure and limited repeatability, where destination clinics can command premium positioning through accreditation density.
- Surgery:Elective orthopedic and cardiac interventions dominate revenue concentration. German and Dutch patient cohorts seeking joint replacements in Polish and Hungarian centers drive throughput at margins exceeding ambulatory services.
- Diagnostics:Advanced imaging and laboratory services function as both standalone offerings and surgical gatekeepers. Czech and Slovak radiology centers attract Western European referrals through shorter appointment queues and competitive MRI pricing.
- Consultation:Specialist second opinions delivered via telemedicine platforms reduce initial travel burdens for complex cases.
- Rehabilitation:Post-surgical physiotherapy and cardiac recovery programs extend patient stays in destination countries.
The dominant share belongs to Surgery, while Diagnostics is closing the gap fastest.
Patient Type:
Volume flows track administrative pathway complexity, with streamlined notification procedures capturing share from prior-authorization bottlenecks.
- Scheduled Patients:Elective procedure seekers with confirmed diagnoses and flexible timing dominate cross-border corridors. These patients complete pre-authorization documentation and align travel with clinic capacity.
- Outpatients:Same-day procedures and diagnostic services bypass hospital admission requirements entirely. Polish dental clinics and Hungarian ophthalmology centers specialize in high-volume, low-complexity outpatient flows.
- Inpatients:Multi-day admissions for complex interventions require coordinated bed management across jurisdictions.
- Emergency Patients:Acute care needs rarely align with cross-border logistics; this segment captures minimal deliberate traffic.
Scheduled Patients anchor volume leadership, yet Outpatients are expanding most quickly through simplified reimbursement pathways.
Payment Model:
Reimbursement certainty determines patient addressability, with guaranteed coverage expanding reachable demand pools beyond self-pay niches.
- Insurance-Based:Home-country statutory insurers covering cross-border care under EU Directive provisions represent the largest addressable population. German sickness funds and Dutch health insurers have established systematic prior-authorization workflows for Polish and Hungarian providers.
- Out-of-Pocket:Self-pay patients bypass administrative friction entirely, concentrating in cosmetic and dental services excluded from statutory coverage. British patients post-Brexit transition increasingly populate this segment.
- Government-Funded:Bilateral agreements between member states finance specific high-complexity referrals outside domestic capacity.
- Employer-Sponsored:Corporate health schemes and expatriate coverage provide supplementary access channels.
Insurance-Based mechanisms retain structural dominance, though Out-of-Pocket is climbing the fastest as statutory coverage gaps persist.
Procedure Type:
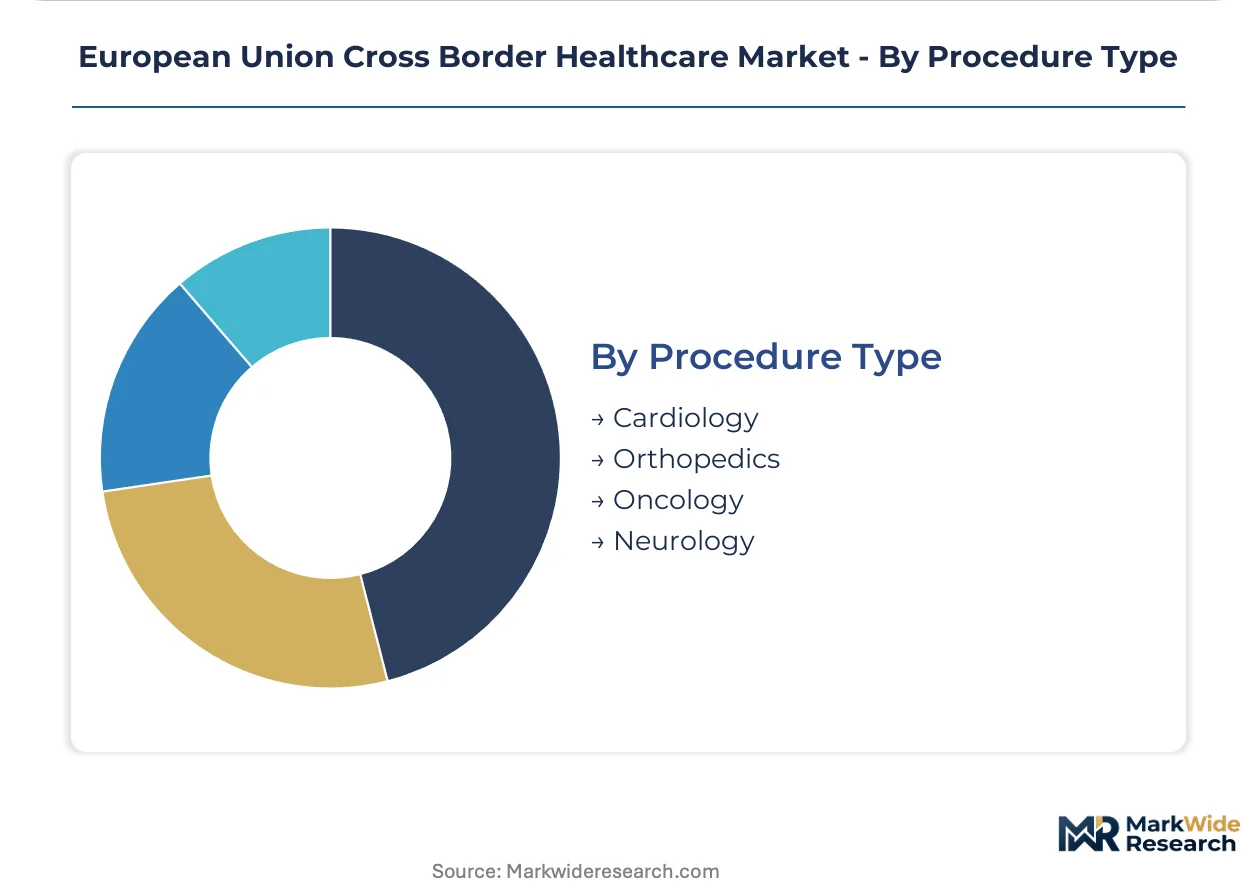
Clinical specialization density in destination markets shapes where patient brokers concentrate marketing investment and accreditation efforts.
- Orthopedics:Joint replacement and spinal surgery procedures generate the highest per-case revenue in cross-border flows. Hungarian centers in Budapest and Pecs have built reputations for hip and knee arthroplasty among aging Dutch and Belgian demographics.
- Cardiology:Elective angioplasty and pacemaker implantation attract patients from systems with procedural queues. Polish cardiac surgery units in Kraków and Wrocław report rising German referrals.
- Oncology:Complex cancer treatment requires continuity protocols that cross-border logistics complicate; volume remains constrained.
- Neurology:Specialized interventions for movement disorders and epilepsy surgery occupy niche positioning.
Orthopedics commands the dominant revenue share, while Cardiology is gaining share fastest through shortened waiting lists and competitive bundled pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA harmonization directives and the EU Directive on Patients' Rights in Cross-Border Healthcare anchor patient mobility frameworks across member states. National health technology assessment bodies maintain divergent reimbursement catalogs that fragment eligibility corridors. Destination clinics in Central and Eastern European member states capture Western European patient flows through cost-competitive positioning.
Germany
German sickness funds process systematic prior-authorization workflows for Polish and Hungarian orthopedic providers. The German Social Code (SGB V) mandates reimbursement for cross-border hospital care under EU Directive provisions. Berlin and Munich-based patient brokers coordinate elective joint replacement referrals to Budapest and Kraków centers.
Poland
Polish destination clinics attract Dutch and Belgian aging demographics seeking hip and knee arthroplasty at compressed price points. The Polish Ministry of Health implements national quality accreditation schemes aligned with EU patient safety frameworks. Kraków and Wrocław cardiac surgery units report rising German referrals for elective angioplasty procedures.
Hungary
Hungarian centers in Budapest and Pecs built reputations for orthopedic excellence among Western European patient cohorts. GDPR-compliant data architectures under Hungarian National Authority for Data Protection and Freedom of Information oversight reduce compliance friction for digital intermediaries. The Budapest medical corridor specializes in bundled pricing for joint replacement and spinal surgery interventions.
Netherlands
Dutch health insurers established streamlined notification procedures for ambulatory services in Central European member states. The Dutch Healthcare Authority (NZa) monitors cross-border care volumes under EU reimbursement frameworks. Dutch patient brokers concentrate marketing investment on Hungarian ophthalmology and Polish dental clinic networks.
Czech Republic
Czech radiology centers attract Western European referrals through shorter MRI appointment queues and competitive diagnostic pricing. The State Institute for Drug Control (SÚKL) oversees medical device registration for cross-border telemedicine platforms. Prague and Brno facilities specialize in advanced imaging services that function as surgical gatekeepers for incoming patient flows.
European Union Cross Border Healthcare Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the European Union cross-border healthcare coordination space. MediBridge Europe and SalusConnect occupy positions that span pan-European hospital network coordination and digital health record interoperability. Three strategic archetypes dominate: digital intermediation platforms, ground logistics coordinators, and telemedicine-integrated follow-up providers. Competitive moves concentrate on strategic partnerships with destination clinic networks and technology licensing for GDPR-compliant data architectures.
Within the integrated platform tier, MediBridge Europe and SalusConnect exemplify archetypes that bundle pre-authorization support with cross-jurisdictional care continuity. ClinRoute occupies a distinct position as a ground logistics specialist spanning ambulance transfers, accommodation booking, and interpreter services. These three entities represent the dominant competitive configurations that emerging entrants must navigate.
| Leading Market Players |
|---|
| MediBridge Europe |
| SalusConnect |
| ClinRoute |
| CareWay Mobility Services |
| MedTour Direct |
| EuroHealth Access |
| TransMedic Pathways |
| VitaCross Europe |
| Panacea Mobility Solutions |
| Others |
Supply & Pricing Matrix
Capacity utilization in Polish and Hungarian orthopedic centers creates scale economies that compress per-procedure costs while elevating price floors for Western European intermediaries. Destination clinics leverage high throughput from German and Dutch patient flows to amortize fixed accreditation investments across larger volumes, tightening margins for smaller competitors unable to match patient capture rates.
Pricing Analysis
Geographic price spreads between Budapest joint replacement centers and comparable German facilities reach multiples that justify travel friction for aging Dutch and Belgian cohorts. Three-tier pricing structure across premium, standard, and economy levels segments patients by accommodation bundled with surgical care. Price differentiation hinges on ISO 9001 certification density and interpreter service tiers. Cost compression in economy tiers intensifies as Romanian and Bulgarian entrants undercut established Polish networks. Self-pay British patients exhibit highest price sensitivity; German statutory fund patients least.
Supply Chain Analysis
Inventory lead times for orthopedic implants and cardiac stents stretch 4-8 weeks from German and Swiss manufacturers to Central European destination clinics. Supply concentration in Poland, Hungary, and the Czech Republic draws from Johnson & Johnson, Zimmer Biomet, and Medtronic distribution hubs. Raw material dependencies span titanium alloys, cobalt-chromium, and biocompatible polymers. Single-source vulnerability concentrates in specialized spinal hardware. Distribution runs through hospital procurement consortia and GPO contracts rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
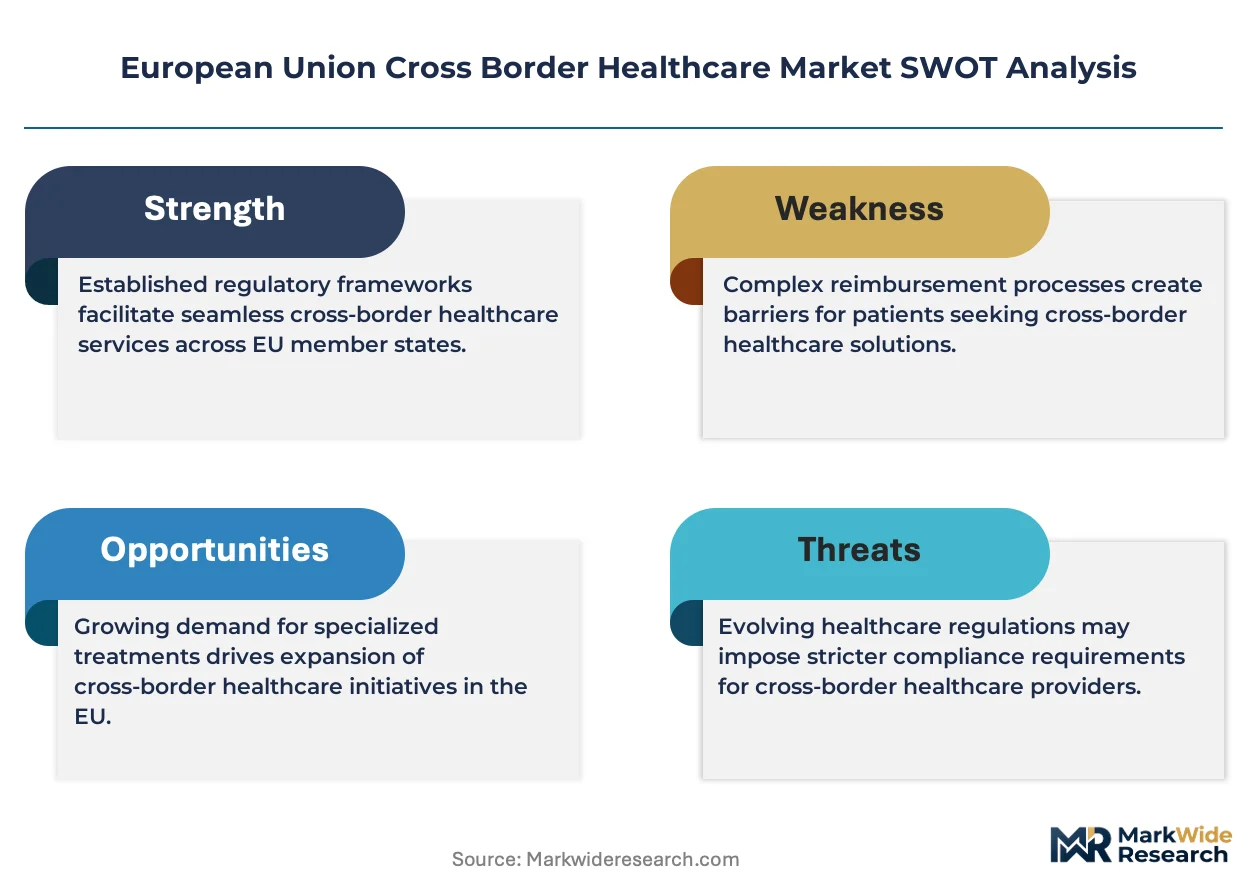
Defensive moats in EU cross-border healthcare rest on regulatory entrenchment through GDPR-compliant data architectures and prior-authorization relationships with German sickness funds. Switching costs for patient brokers escalate as clinic network density and insurer accreditation deepen.
For Market Incumbents: Consolidate through exclusive contracts with emerging Romanian and Bulgarian clinic networks before Western European brokers establish presence. Deepen vertical integration into telemedicine follow-up platforms to capture recurring post-procedure revenue streams. Counter threat from digital-native entrants by embedding AI-powered pre-authorization tools that accelerate insurer workflows beyond standalone platform capabilities.
For New Entrants and Emerging Players: Ground logistics coordination gaps in ambulance transfers and multilingual patient support expose white-space opportunities outside core clinical competencies. Romanian clinic networks represent most penetrable geography given untapped cost-competitive capacity and limited incumbent broker presence. Target employer-sponsored corporate health schemes with bundled executive screening and elective procedure packages as differentiated go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telemedicine-integrated follow-up providers with multi-year insurer contracts. Long-term viability favors platforms with embedded European Health Data Space compliance roadmaps and pan-European hospital network density. Acquisition target archetype: mid-size Polish or Hungarian clinic groups with ISO accreditation and underdeveloped patient broker relationships. Watch EU-wide electronic health record standard adoption velocity as inflection indicator for regulatory arbitrage compression.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Data Architecture Investment | Reduces compliance friction for pan-European record systems under Hungarian and Polish data protection authority oversight. |
| Prior-Authorization Workflow Automation | Accelerates German sickness fund approvals through AI-powered documentation matching SGB V reimbursement requirements. |
| Romanian Clinic Network Partnership | Captures untapped cost-competitive capacity before Western European patient brokers establish systematic presence. |
| Telemedicine Follow-Up Platform Integration | Extends patient relationship duration beyond single procedures through remote monitoring under EU AI Act transparency mandates. |
| European Health Data Space Early Compliance | Positions intermediaries for regulatory harmonization that compresses cross-border data transfer costs across member states. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, cross-border patient coordinators, health insurer prior-authorization specialists, and GDPR compliance officers and refined through secondary validation. Primary interviews combined with regulatory filing analysis from EMA submissions, national health technology assessment body coverage catalogs, and EU Directive implementing regulations. Secondary sources encompassed hospital procurement databases, GPO contracts, and CMS-equivalent European reimbursement data. Bottom-up clinic capacity modeling and top-down patient flow estimates underwent iterative triangulation.
Variance-decomposition across service type, patient type, payment model, and procedure type segmentation dimensions anchored the analytical framework. CAGRs were derived from patient volume trajectories and reimbursement rate evolution across the analysis window. Modeled inputs included Schengen nursing workforce mobility rates, digital health record interoperability adoption curves, and orthopedic procedure queue lengths in origin markets.
Forecasts assume regulatory continuity in EU Directive on Patients' Rights implementation and GDPR enforcement regimes; material policy shifts would require re-modeling. Specific risks encompass reimbursement catalog divergence hardening, prior-authorization bottlenecks expanding, and European Health Data Space timelines slipping. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
Aged Care Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Hospice Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
US Hospice Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Healthcare Transportation Services Market