
 Global Surgical Catheters Market | 2026-2036
Global Surgical Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Catheters Market Analysis
The EU Medical Device Regulation is realigning the cost-of-entry calculus for surgical catheter manufacturers across Europe, forcing extensive clinical evidence packages and notified body recertification. Medtronic Plc leverages its vertically integrated silicone supply chain to sustain margin resilience under these compliance burdens. Boston Scientific Corporation anchors its European position through specialized hemodialysis catheter portfolios that navigate the new quality management system requirements. Abbott Laboratories differentiates via cardiovascular application focus, controlling premium segments where MDR traceability mandates favor established players with robust post-market surveillance infrastructure.
Surgical catheters are flexible tubular devices inserted into body cavities, ducts, or vessels to drain fluids, administer therapeutics, or enable diagnostic monitoring, typically manufactured through extrusion of medical-grade polymers with lumen diameters ranging from 3 French to 36 French depending on anatomical target. Their primary commercial purpose centers on enabling minimally invasive procedures that reduce patient recovery time and hospitalization duration compared to open surgical alternatives. Foley catheters occupy the largest volume position due to persistent urology demand, while hemodialysis catheters represent the fastest-expanding product category as chronic kidney disease prevalence escalates dialysis infrastructure investment. Silicone material formulations command premium pricing in long-dwell applications, whereas polyurethane dominates acute care settings where tensile strength and thinner wall profiles enable higher flow rates.
FDA 510(k) clearance pathways, EMA MDR implementation timelines, and Japan PMDA quality system regulations collectively shape product development cycles and geographic launch sequencing for catheter manufacturers. These frameworks elevate barriers for new entrants while consolidating advantage among incumbents with dedicated regulatory affairs capabilities and established quality management certifications. Stakeholders must monitor evolving biocompatibility testing standards and reimbursement coding changes as determinants of competitive positioning in catheter-based intervention markets.
Market Dynamics
The EU Medical Device Regulation is compressing supplier margins through clinical evidence mandates while simultaneously concentrating procurement volume among manufacturers with captive silicone extrusion capabilities and established notified body relationships.
Growth Catalysts
- Cardiovascular intervention expansion:Hospital systems in the United States are expanding catheter-based electrophysiology labs to reduce open-heart surgery backlog, directly pulling multi-lumen diagnostic catheters into inventory.
- Chronic kidney disease infrastructure:Japan PMDA reimbursement coding changes for tunneled hemodialysis catheters are accelerating dialysis center capital equipment procurement cycles.
- REACH-compliant material substitution:German medical device manufacturers are reformulating polyurethane blends to meet ECHA phthalate restrictions, creating specification refresh demand across European supply chains.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone monomer production clusters in Germany and Japan, exposing catheter manufacturers to geopolitical logistics disruptions and force majeure allocation protocols.
- Notified body capacity constraints:EU MDR recertification queues at BSI Group and TÜV SÜD extend product launch timelines by 18-24 months for mid-tier manufacturers lacking legacy CE mark grandfathering.
- Bioresorbable stent substitution:Drug-eluting bioresorbable vascular scaffolds from Abbott and Boston Scientific are displacing certain diagnostic catheter applications in coronary revascularization protocols.
Strategic Opportunities
- India dialysis infrastructure buildout:CDSCO streamlined import licensing for hemodialysis catheters under the 2023 Medical Device Rules is opening procurement channels for foreign manufacturers in tier-2 hospital networks.
- Antimicrobial surface technology convergence:Silver-ion coating integration with silicone extrusion processes is creating premium catheter SKUs for intensive care units with extended indwelling requirements.
- Direct-to-hospital distribution platforms:Group purchasing organizations in the United States are consolidating catheter procurement through cloud-based inventory management systems that bypass traditional distributor markups.
Industry Challenges
- Polymer extrusion technician scarcity:Medical device manufacturing regions in Massachusetts and Minnesota face acute shortages of operators qualified in multi-lumen catheter tip forming and bond strength validation.
- ISO 13485:2016 transition complexity:Small-to-mid catheter manufacturers struggle with documented risk management file maintenance under updated quality system requirements, delaying audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Catheters Market |
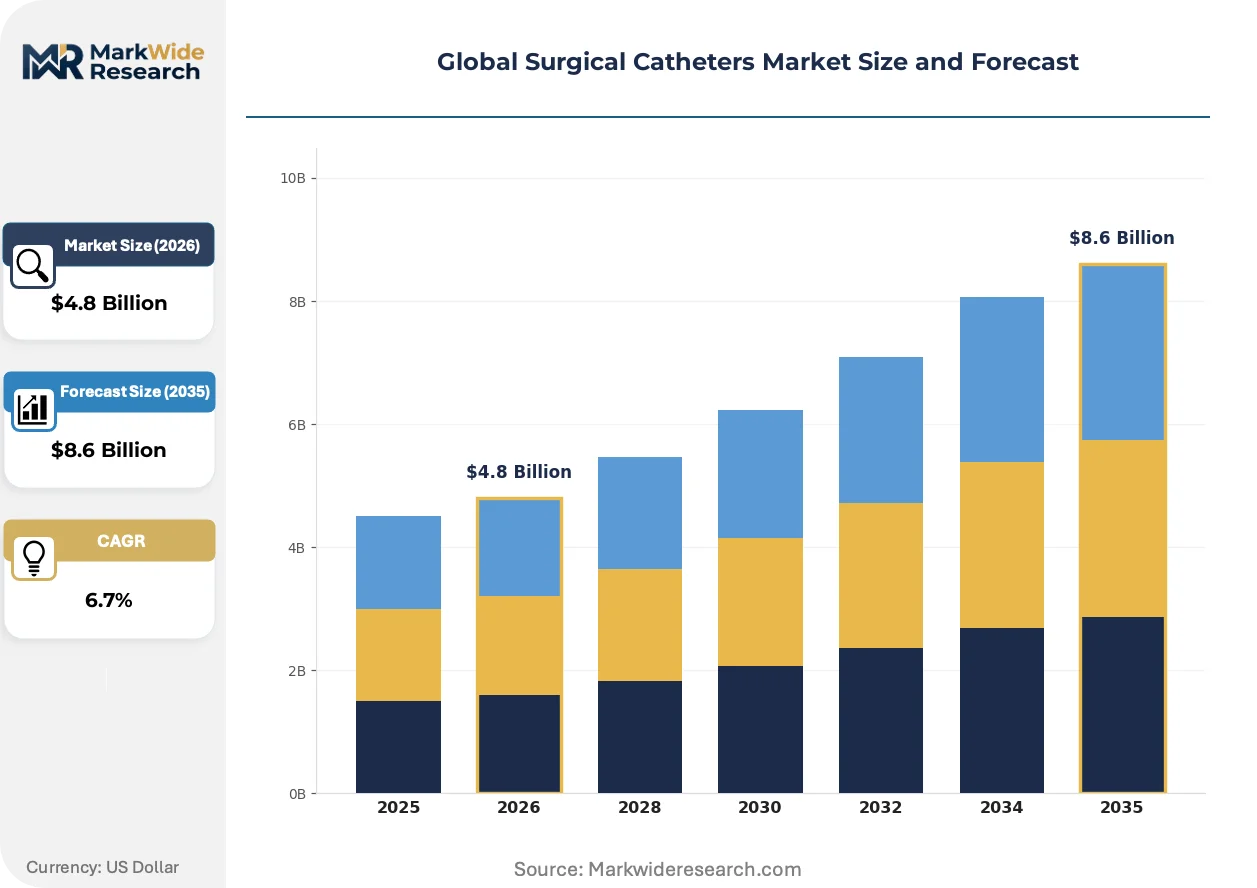
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foley Catheters, Intravenous Catheters, Hemodialysis Catheters, Pressure Monitoring Catheters Material: Silicone, Polyurethane, Latex, PVC End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Settings Application: Urology, Cardiology, Gastroenterology, Neurology |
| Companies Covered | Medtronic Plc, Boston Scientific Corporation, Abbott Laboratories, B. Braun Melsungen AG, Teleflex Incorporated, Johnson & Johnson Services, Inc., Becton, Dickinson and Company, Edwards Lifesciences Corporation, Hollister Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Catheters Market Emerging Trajectories
Catheter manufacturing is undergoing precision automation while regulatory traceability mandates and procurement consolidation reshape competitive differentiation around post-market surveillance infrastructure rather than raw innovation speed.
Robotic laser micromachining is automating catheter tip geometry production with sub-10-micron precision for neurovascular access devices. Academic medical centers in the United States are early-adopting these components for stroke thrombectomy protocols. The technology is automating quality consistency previously requiring manual operator judgment, compressing rejection rates and enabling thinner wall profiles.
EMA MDR Unique Device Identification implementation is forcing catheter manufacturers to serialize production lots at the unit level with direct-part-marked laser codes. This mandate is extending quality management system documentation requirements through distribution channels. Hemodialysis catheter portfolios face the steepest compliance burden due to higher patient contact duration and corresponding vigilance reporting obligations.
Hospital value analysis committees are consolidating catheter supplier rosters to three preferred vendors per category, unbundling traditional distributor service bundles. Integrated delivery networks in Texas and California are piloting consignment inventory models where manufacturers retain ownership until point-of-use. Germany exhibits the most advanced adoption of this procurement pattern among European hospital systems.
Global Surgical Catheters Market Segmentation
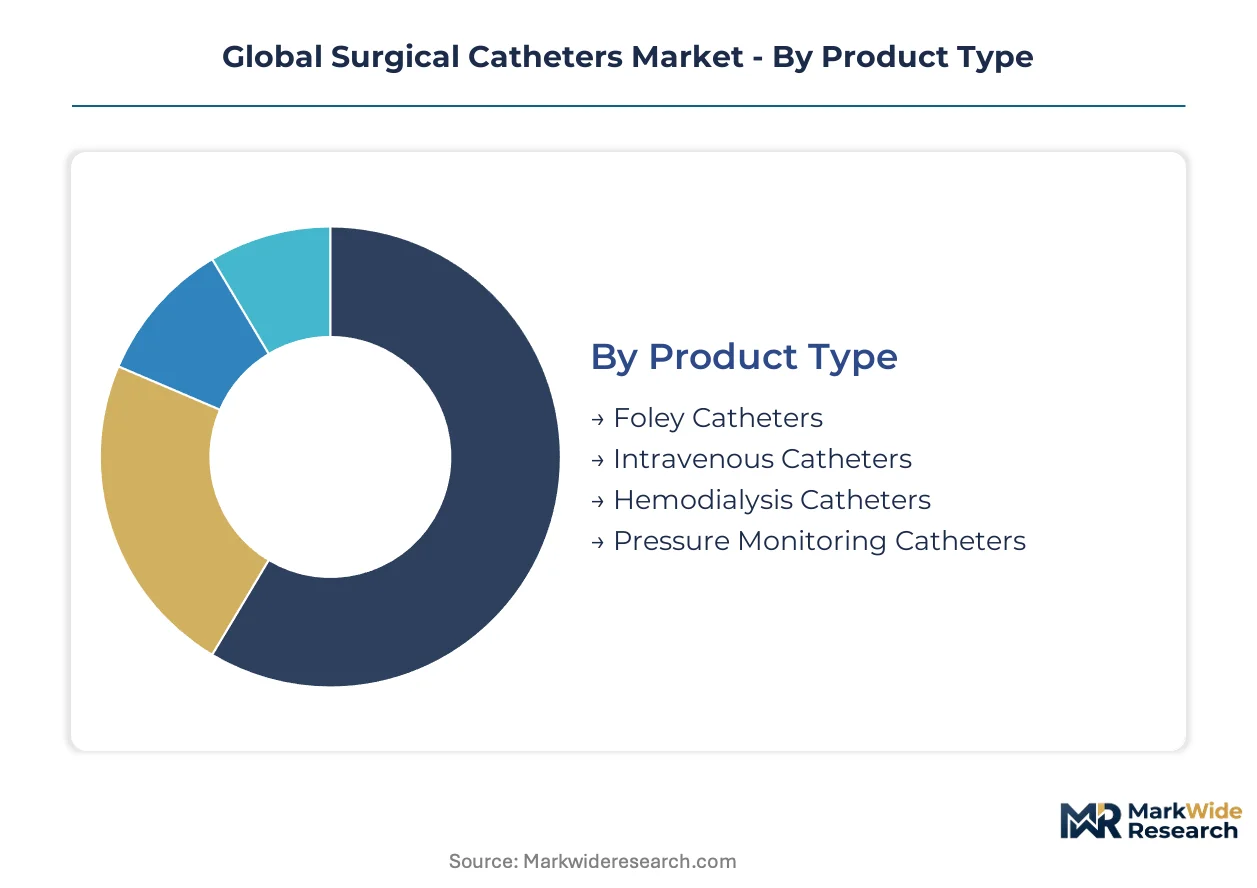
Surgical catheter segmentation reveals how material science, clinical setting economics, and procedure-specific performance requirements fragment procurement patterns across hospital systems. Manufacturers configure product portfolios around dwell time, flow rate demands, and reimbursement coding rather than pursuing universal platform strategies.
Product Type:
Catheter architecture varies by lumen count, tip geometry, and indwelling duration to match anatomical access requirements and drainage volumes.
- Foley Catheters:Triple-lumen designs with temperature-sensing capabilities dominate tertiary hospital urology departments. United States hospital systems standardize on 16-18 French sizes for post-operative drainage, with silicone elastomer coatings reducing encrustation rates in extended indwelling protocols.
- Hemodialysis Catheters:Dual-lumen tunneled configurations with Dacron cuffs command premium positioning in dialysis center procurement. Japan PMDA reimbursement coding revisions for tunneled cuffed catheters are accelerating replacement cycles in independent dialysis facilities.
- Intravenous Catheters:Peripheral short-term access devices manufactured from polyurethane blends dominate acute care infusion therapy.
- Pressure Monitoring Catheters:Fluid-filled transducer systems with disposable pressure domes serve cardiac catheterization lab hemodynamic assessment.
Mature deployment sits with Foley catheters. Newer deployment is concentrated in hemodialysis catheters.
Material:
Polymer selection trades off tensile strength, biocompatibility certification costs, and dwell time economics across acute versus chronic applications.
- Silicone:Platinum-cured elastomer formulations with Shore A 50-60 hardness ratings enable thin-walled high-flow designs for long-term implantation. German manufacturers favor silicone for hemodialysis catheter bodies under ECHA phthalate restriction compliance pathways.
- Polyurethane:Aromatic ether-based formulations provide superior abrasion resistance and kink recovery for acute care settings. United States emergency departments specify polyurethane peripheral IV catheters for rapid infusion trauma protocols where tensile strength outweighs long-term biostability concerns.
- Latex:Natural rubber formulations persist in cost-sensitive drainage applications with shorter indwelling requirements.
- PVC:Plasticized polyvinyl chloride remains common in single-use diagnostic catheters where material cost minimization drives specification.
Silicone commands the steepest price escalation curve. PVC maintains the most compressed margin structure.
End User:
Procurement authority and inventory management sophistication vary sharply across facility types, reshaping distribution economics and supplier relationship models.
- Hospitals:Integrated delivery networks in Texas and California consolidate catheter purchasing through value analysis committees that unbundle distributor service components. These systems negotiate direct manufacturer contracts for high-volume Foley and hemodialysis catheter categories.
- Ambulatory Surgical Centers:Procedure-specific stocking with limited SKU breadth favors pre-sterilized single-use kits. United States ASC chains prioritize hemodialysis catheter trays with integrated insertion accessories to minimize sterile processing overhead.
- Clinics:Outpatient urology and cardiology practices source smaller lot sizes through distributor intermediaries.
- Home Care Settings:Patient or caregiver-administered catheterization drives demand for lubricious hydrophilic coatings and simplified insertion aids.
Hospital procurement is consolidating toward direct manufacturer engagement. Home care channels are expanding most quickly.
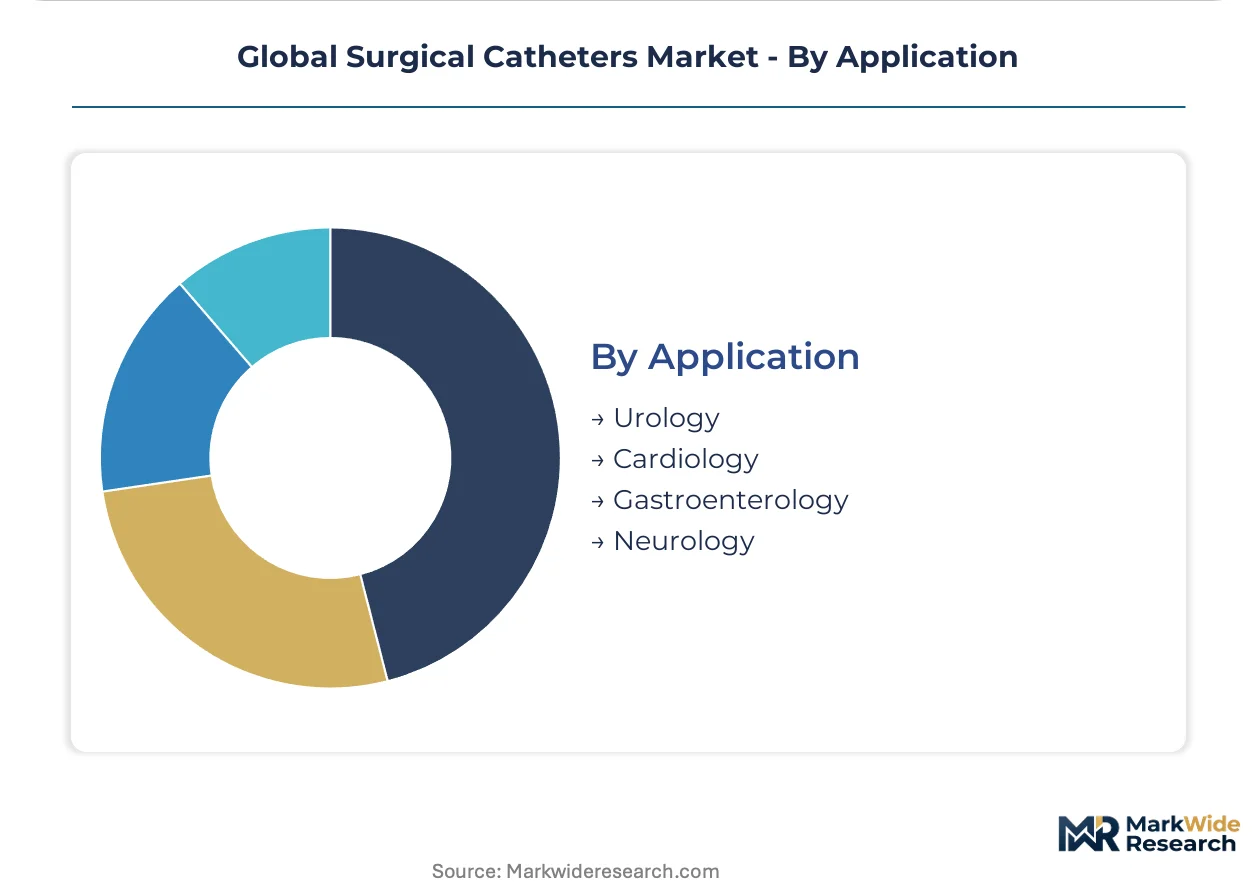
Application:
Clinical specialty requirements dictate catheter performance specifications, reimbursement pathways, and regulatory evidence thresholds.
- Urology:Chronic urinary retention management and post-surgical drainage sustain the highest procedure volumes. United States Medicare reimbursement for indwelling catheter changes creates recurring revenue streams for Foley catheter manufacturers serving long-term care facilities.
- Cardiology:Electrophysiology mapping and hemodynamic monitoring demand multi-lumen configurations with torque response and radiopacity. Japan's expansion of catheter-based ablation lab accreditation is pulling diagnostic electrophysiology catheters into inventory buildouts.
- Gastroenterology:Enteral feeding and biliary drainage applications require compatibility with endoscopic placement techniques.
- Neurology:Cerebrospinal fluid diversion and intracranial pressure monitoring utilize specialized ventricular access devices.
Urology represents the highest volume foundation. Cardiology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate catheter manufacturing for North American supply chains, while Singapore's Biopolis precinct anchors Asia-Pacific regulatory approval pathways for Western manufacturers seeking regional market entry.
United States
Integrated delivery networks in Texas and California are consolidating catheter procurement through direct manufacturer contracts, bypassing traditional distributor markups. FDA 510(k) clearance timelines shape product launch sequencing, with cardiovascular catheter submissions facing heightened scrutiny for predicate device equivalence. The Minneapolis-St. Paul corridor hosts dense clusters of polymer extrusion specialists serving diagnostic catheter tip forming requirements.
Germany
Hospital procurement departments are reformulating polyurethane specifications to meet ECHA phthalate restrictions under REACH compliance pathways. The EU Medical Device Regulation recertification queues at BSI Group and TÜV SÜD extend timelines for mid-tier manufacturers lacking legacy CE mark grandfathering. The Stuttgart and Freiburg regions concentrate specialty silicone monomer production for long-dwell catheter applications.
Japan
PMDA reimbursement coding revisions for tunneled hemodialysis catheters are accelerating replacement cycles in independent dialysis facilities. METI subsidies for domestic catheter manufacturing aim to reduce import dependency for critical care consumables. The Kansai region around Osaka maintains precision polymer processing capabilities for neurovascular access devices.
India
CDSCO streamlined import licensing for hemodialysis catheters under the 2023 Medical Device Rules is opening procurement channels for foreign manufacturers in tier-2 hospital networks. State-level production-linked incentive schemes in Gujarat and Karnataka are attracting contract manufacturing investments for export-oriented catheter assembly. The Delhi-NCR corridor serves as the primary distribution hub for northern India dialysis center supply chains.
China
NMPA quality system regulations for imported catheters require in-country testing protocols that extend registration timelines for Western manufacturers. Provincial health procurement platforms in Jiangsu and Zhejiang are consolidating tender awards for single-use cardiovascular catheters under volume-based purchasing reforms. The Suzhou Industrial Park hosts multiple joint ventures focused on hemodialysis catheter localization.
Global Surgical Catheters Market Vendor Landscape
United States producers anchor one tier with vertically integrated silicone supply chains; German and Swiss specialists hold certification-advantaged positions under EU MDR transition timelines. Market structure concentrates among incumbents with dedicated regulatory affairs capabilities and established quality management certifications. Three archetypes dominate: diversified medical technology conglomerates, cardiovascular-focused device specialists, and urology-centric consumables manufacturers. Competitive moves center on notified body relationship deepening and captive polymer extrusion capacity expansion.
Within the diversified technology tier, Medtronic Plc and Johnson & Johnson Services, Inc. occupy positions defined by scale-driven procurement consolidation and integrated delivery network direct contracting capabilities. Boston Scientific Corporation exemplifies the cardiovascular-focused archetype, sitting within premium segments where electrophysiology lab expansion drives diagnostic catheter demand. Among European specialists, B. Braun Melsungen AG represents the urology-centric consumables model, with its German manufacturing base aligning with ECHA-compliant material substitution requirements. These three anchors illustrate how geographic regulatory positioning and clinical application focus stratify competitive positioning rather than raw manufacturing scale alone.
| Leading Market Players |
|---|
| Medtronic Plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Johnson & Johnson Services, Inc. |
| Becton, Dickinson and Company |
| Edwards Lifesciences Corporation |
| Hollister Incorporated |
| Others |
Supply Flow & Price Mechanics
Robotic laser micromachining adoption is compressing per-unit production costs while simultaneously concentrating manufacturing capability among capital-intensive producers with precision automation infrastructure. This technology transition simultaneously reshapes cost economics and supply concentration, rewarding incumbents with captive extrusion capacity while squeezing mid-tier competitors dependent on manual tip-forming labor.
Pricing Analysis
Short lead-time premiums command pricing power in hemodialysis catheter procurement, with spot inventory discounts emerging for standard Foley configurations with extended shelf availability. Three-tier pricing structure across premium, standard, and economy levels stratifies by silicone purity grade and FDA 510(k) clearance tier, with platinum-cured formulations extracting brand premiums over peroxide-cured alternatives. Pricing pressure stems from EU MDR compliance cost absorption, with notified body recertification fees compressing margins for non-vertically integrated manufacturers. Ambulatory surgical centers exhibit highest price sensitivity due to procedure-volume volatility, while integrated delivery networks leverage direct-contract scale for least sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with specialty silicone monomer production clustered in Germany and Japan, exposing catheter manufacturers to force majeure allocation protocols during geopolitical logistics disruptions. Raw material dependencies center on medical-grade silicone elastomers, aromatic ether-based polyurethane precursors, and platinum catalyst systems for curing operations. Supply chain risk manifests as regulatory restriction exposure from ECHA phthalate restrictions under REACH compliance pathways. Distribution runs through group purchasing organization platforms in the United States and hospital procurement consortia in Germany, bypassing traditional distributor markups through cloud-based inventory management integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into silicone monomer production and forward integration into direct-hospital contracting determine sustainable margin capture.
For Market Incumbents: Cement notified body relationship depth through dedicated EU MDR recertification investment at BSI Group and TÜV SÜD, insulating against 18-24 month queue delays that threaten mid-tier competitors. Expand captive polymer extrusion capacity in Massachusetts and Minnesota clusters to offset polymer extrusion technician scarcity and secure bond strength validation expertise. Bioresorbable stent substitution from Abbott and Boston Scientific threatens diagnostic catheter volumes in coronary applications; counter through electrophysiology mapping catheter portfolio expansion. For New Entrants and Emerging Players: Capture CDSCO streamlined import licensing pathways for hemodialysis catheters in India tier-2 hospital networks, where dialysis infrastructure buildout outpaces domestic manufacturing capacity. Target antimicrobial surface technology convergence as the most penetrable white-space, integrating silver-ion coating capabilities with silicone extrusion processes for intensive care unit premium SKUs. Pursue direct-to-hospital distribution platform partnerships with cloud-based inventory management providers to bypass established distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in cardiovascular-focused device specialists with electrophysiology lab expansion exposure and established FDA 510(k) predicate device libraries. Long-term viability over the projection horizon hinges on post-market surveillance infrastructure depth under EMA MDR vigilance reporting obligations, favoring targets with documented risk management files and ISO 13485:2016 transition completion. Watch PMDA reimbursement coding revisions for tunneled hemodialysis catheters as the signal indicating Japan dialysis center capital equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Deepening | BSI Group and TÜV SÜD queue priority secures EU MDR recertification timelines against 18-24 month delays. |
| Captive Silicone Extrusion Expansion | In-house platinum-cured elastomer production insulates margin resilience under REACH phthalate restriction compliance. |
| Antimicrobial Surface Technology Integration | Silver-ion coating convergence with silicone extrusion creates premium SKUs for extended indwelling intensive care protocols. |
| Direct-to-Hospital Distribution Platform | Cloud-based inventory management bypasses traditional distributor markups in Texas and California integrated delivery networks. |
| CDSCO Import Licensing Acceleration | Streamlined 2023 Medical Device Rules pathways open procurement channels in India tier-2 dialysis center networks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across catheter manufacturing executives, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and dialysis center procurement leads. FDA 510(k) databases, EMA MDR submission records, PMDA reimbursement coding archives, and CDSCO import licensing registries provided secondary validation. Bottom-up demand modeling from procedure volumes and top-down market sizing from manufacturer revenue disclosures underwent triangulation for consistency.
Granularity-level modeling proceeded at product type, material formulation, end-user facility tier, and clinical application dimensions across the analysis window. CAGRs derived from logarithmic trend fitting to historical volume trajectories, adjusted for regulatory timeline impacts and reimbursement coding revision effects. Forecast inputs incorporated chronic kidney disease prevalence projections, electrophysiology lab expansion schedules, and REACH-compliant material substitution adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, silicone monomer supply disruptions, and bioresorbable stent substitution rates in coronary revascularization. Forecasts reflect documented assumptions regarding reimbursement stability and notified body capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market