
 Assisted Living Market | 2026-2036
Assisted Living Market Size, Share, and Industry Trends Forecast 2026-2036
Assisted Living Market Analysis
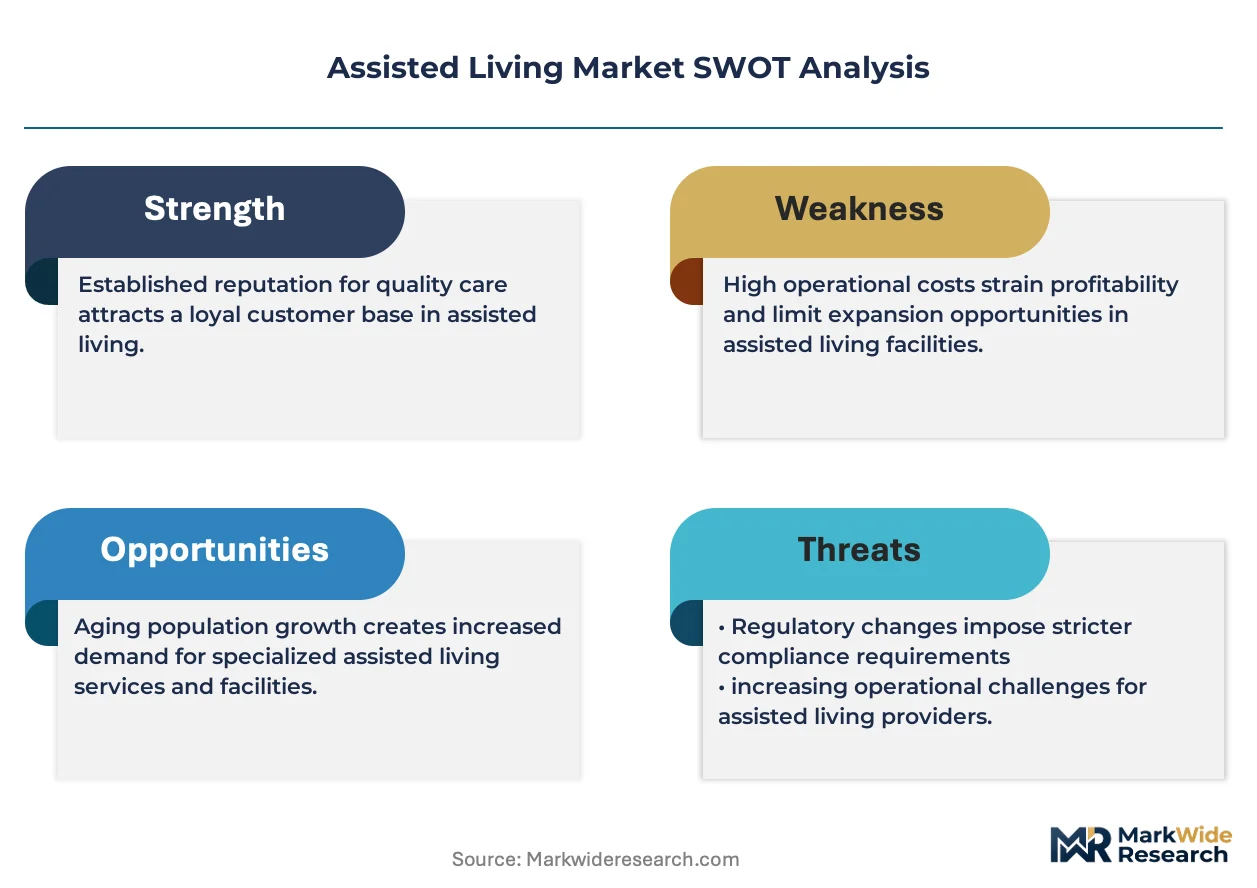
Aftermarket wellness programming revenue is rewriting profitability expectations for operators who previously relied on room-and-board margins. Brookdale Senior Living leverages its national footprint to standardize care protocols across hundreds of communities. Sunrise Senior Living anchors its model on chef-prepared dining and life-enrichment calendars that justify premium rate structures. Benchmark Senior Living competes through concentrated New England density that reduces per-unit overhead.
Assisted living denotes residential care for older adults requiring help with activities of daily living but not continuous skilled nursing, typically involving 24-hour supervision, medication administration, and mobility assistance in purpose-built or retrofitted properties. The primary commercial purpose centers on extending independent living duration while capturing spend from families seeking alternatives to institutional nursing homes. Memory care within facility type commands the highest daily rates due to specialized staffing ratios and secured-environment capital requirements. Residential delivery model properties dominate transaction volume, though home care segments attract technology-enabled entrants seeking lower capital intensity. Personal care services generate recurring revenue streams with lower staff turnover than clinical service lines.
FDA oversight of digital health devices used in remote monitoring intersects with state-level Medicaid agency rate-setting that determines operator reimbursement across US markets. CMS Conditions of Participation for skilled nursing facilities create compliance benchmarks that adjacent assisted living operators voluntarily adopt to attract hospital discharge referrals. OSHA workplace safety standards and state nurse aide training mandates shape labor availability and training costs. Stakeholders must monitor evolving CMS guidance on home and community-based services waivers and state budget appropriations that directly determine addressable demand pools.
Market Dynamics
Medicaid waiver expansion for home and community-based services is redirecting state reimbursement toward residential care alternatives, forcing operators to restructure census mixes and care protocols to capture public-payer volume without eroding private-pay margins.
Growth Catalysts
- Aging-in-place technology integration:Remote patient monitoring systems are extending resident eligibility for assisted living by flagging health declines before skilled nursing becomes necessary.
- Florida retiree migration clusters:Concentrated inbound population flows to Tampa, Orlando, and Phoenix metro areas are pre-leasing new construction before certificate-of-need approvals finalize.
- CMS HCBS waiver expansion:State Medicaid agencies are broadening eligibility criteria for residential care settings, converting previously institutional-bound beneficiaries into addressable demand.
Market Restraints
- Direct care worker wage compression:Competing employers in retail and logistics are absorbing the same labor pool, elevating turnover costs above 40% annually in many markets.
- Construction debt service coverage:Floating-rate construction financing from regional banks is compressing development yields below operator hurdle rates in high-cost metros.
- Certificate-of-need moratoria:States including Kentucky and North Carolina have frozen new bed approvals, protecting incumbent occupancy but blocking greenfield entry.
Strategic Opportunities
- Texas Medicaid managed care carve-outs:Privatized long-term care programs are creating preferred provider networks that reward scale and quality metrics with volume guarantees.
- AI-powered fall detection:Computer vision systems deployed in common areas are reducing liability exposure while generating data assets for predictive care planning.
- Arizona certificate-of-need exemption counties:Rural designation loopholes permit unlicensed bed expansion in fast-growing exurban corridors surrounding Phoenix and Tucson.
Industry Challenges
- Licensed practical nurse pipeline collapse:Community college program closures in the Northeast are constraining supervisory staffing ratios required for memory care licensure.
- Electronic health record interoperability:Point solutions for medication management lack bidirectional data exchange with hospital discharge systems, fragmenting care continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assisted Living Market |
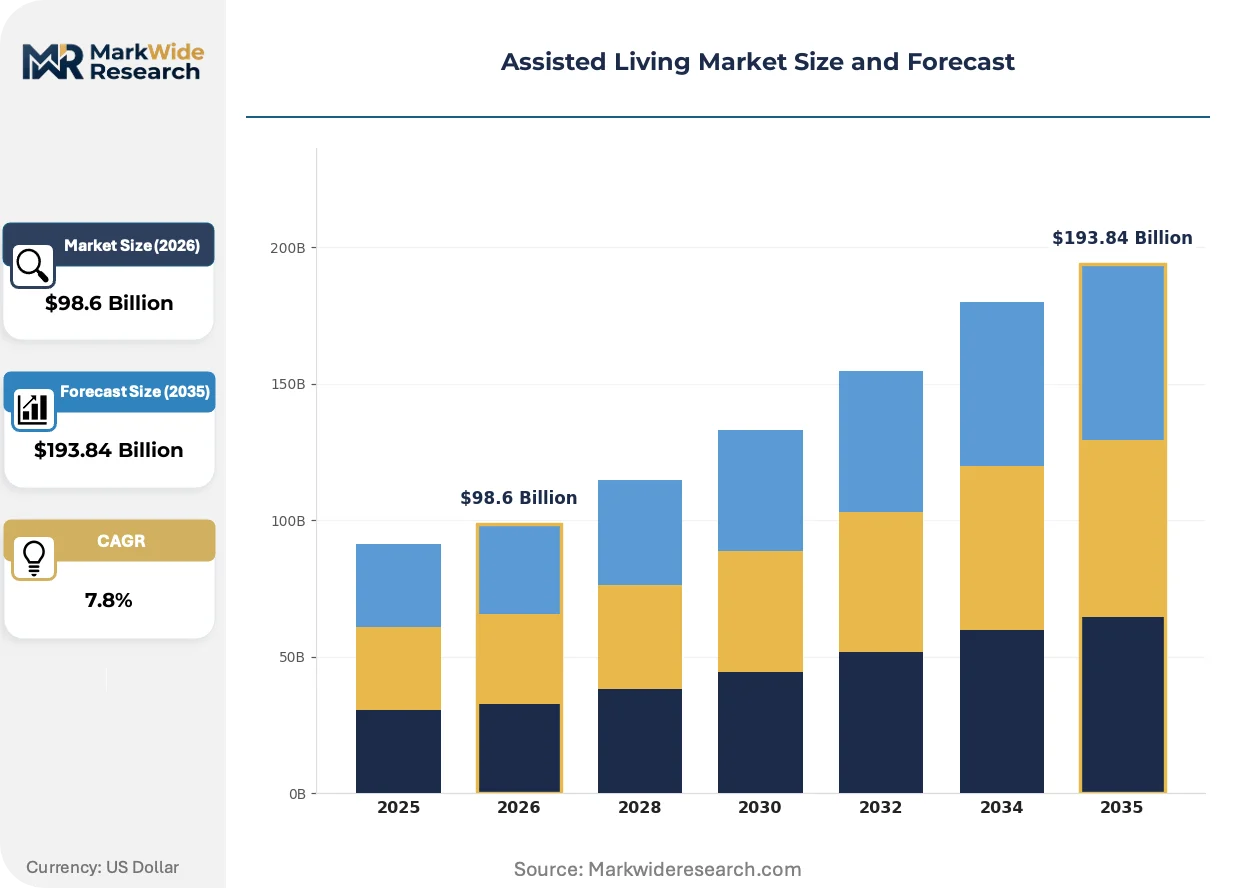
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $193.84 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Care, Medication Management, Recreational Activities, Health Monitoring Delivery Model: Residential, Community-based, On-site, Home Care Facility Type: Independent Living, Memory Care, Skilled Nursing, Continuing Care End User: Elderly, Adults with Disabilities, Caregivers, Families |
| Companies Covered | Brookdale Senior Living, Atria Senior Living, Sunrise Senior Living, LCS, Five Star Senior Living, Genesis HealthCare, Erickson Senior Living, Benchmark Senior Living, Senior Lifestyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assisted Living Market Emerging Trajectories
Technology-enabled care delivery is compressing the boundary between independent living and assisted living, while regulatory pressure on staffing transparency is forcing operational disclosure that reshapes competitive positioning.
Telehealth infrastructure is virtualizing routine physician consultations that previously required transportation coordination or third-party clinic visits. Large operators with centralized IT departments are deploying tablet-based exam rooms across portfolios, capturing specialist revenue that formerly leaked to external providers. This virtualization is compressing the traditional skilled nursing admission threshold by resolving acute episodes within the residential setting.
OSHA workplace violence prevention mandates are requiring assisted living operators to implement comprehensive safety programs covering resident-to-staff aggression incidents. The standard obligates hazard assessment, incident reporting, and engineering controls that elevate administrative burden but reduce workers compensation exposure. Memory care units with elevated behavioral incident rates face the steepest compliance cost escalation.
Family decision-making is migrating toward digital discovery platforms that aggregate quality ratings, pricing transparency, and virtual tour access before physical site visits occur. Third-party referral agencies are disintermediating traditional discharge planner relationships, capturing placement fees that operators previously directed toward hospital outreach staff. This channel shift concentrates volume with operators maintaining robust online reputation management and instant availability data.
Assisted Living Market Segmentation
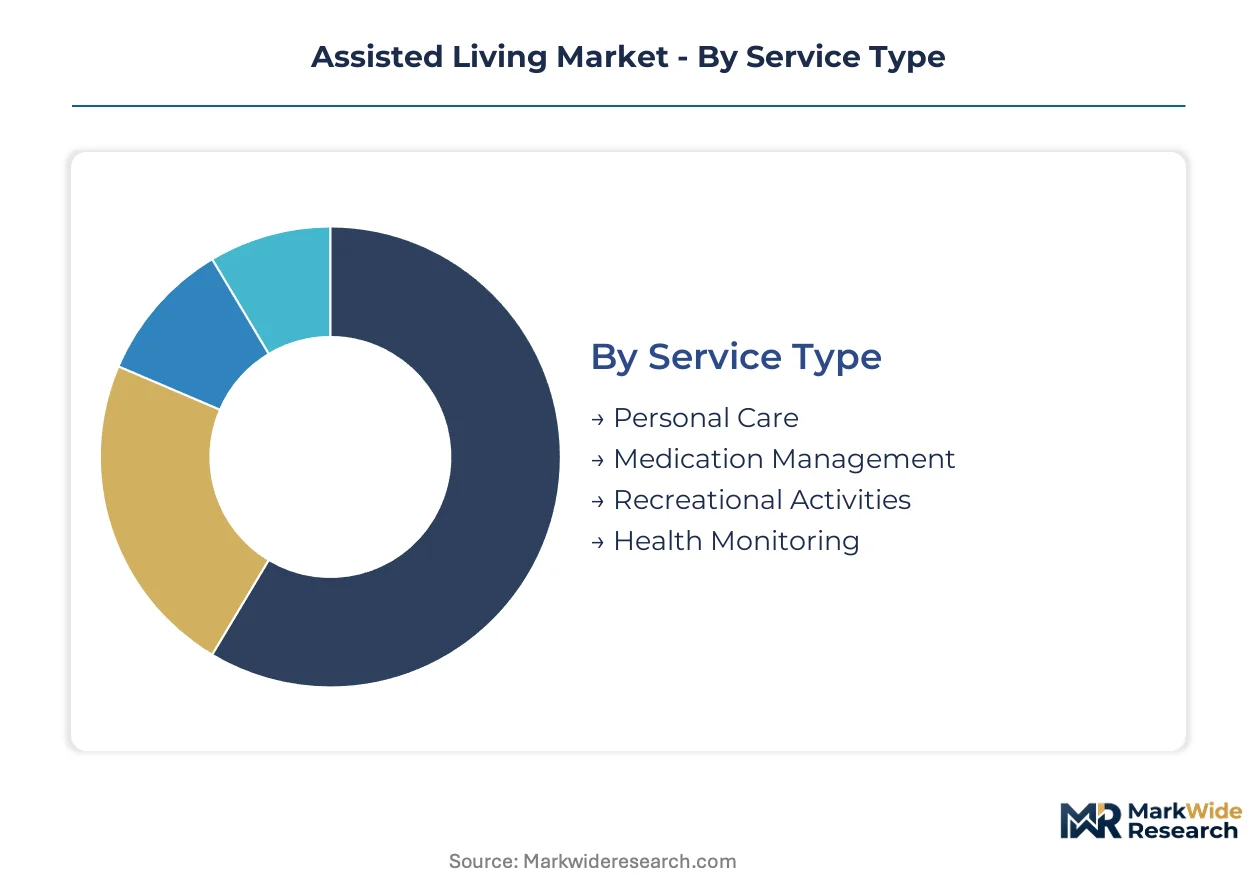
Assisted living operators configure service bundles and property formats to match acuity levels, payer sources, and family preferences across fragmented demand pools. Segmentation discipline determines capital allocation between high-touch clinical services and lower-intensity residential offerings.
Service Type:
Mature service lines dominate census mix while emerging digital health integrations reshape labor deployment.
- Personal Care:Bathing, dressing, and mobility assistance delivered by certified nursing assistants constitutes the baseline service tier. Demand concentrates in Florida and Texas where retiree migration supports private-pay census; wage compression in these markets elevates labor costs above national averages.
- Medication Management:Licensed nursing staff administer prescriptions, monitor polypharmacy interactions, and coordinate pharmacy deliveries. This segment commands premium rate add-ons in memory care settings where behavioral medications require specialized protocols and documentation.
- Recreational Activities:Structured programming addresses social isolation and cognitive maintenance through scheduled events.
- Health Monitoring:Vital sign tracking and remote patient monitoring systems extend resident eligibility thresholds.
Personal Care handles the majority of throughput; Health Monitoring is expanding most quickly on share.
Delivery Model:
Cost tier separation between capital-intensive residential assets and variable-cost home-based alternatives defines competitive positioning.
- Residential:Purpose-built or retrofitted properties with 24-hour staffing and shared common areas represent the traditional assisted living format. Arizona and Florida markets lead development volume where certificate-of-need exemptions or streamlined approvals accelerate project timelines.
- Community-based:Adult day centers and respite programs offer non-residential support for family caregivers seeking daytime coverage.
- On-site:Embedded clinics within senior housing campuses deliver primary care and specialist consultations without transportation logistics.
- Home Care:Agency-deployed aides provide services in private residences, competing directly with residential assisted living for lower-acuity demand.
Residential properties absorb the largest capital deployment; Home Care is gaining share fastest among delivery alternatives.
Facility Type:
Application-based differentiation separates independent living extensions from clinically intensive memory care environments.
- Independent Living:Age-restricted housing with minimal services targets self-sufficient seniors seeking social infrastructure and maintenance-free arrangements. Texas markets show elevated demand where active-adult communities cluster around Austin and Dallas exurbs.
- Memory Care:Secured units with specialized staffing ratios serve Alzheimer's and dementia populations through structured routines and behavioral interventions. CMS HCBS waiver expansion is redirecting previously institutional-bound beneficiaries toward these residential alternatives.
- Skilled Nursing:Post-acute and long-term care facilities with 24-hour licensed nursing provide the highest acuity tier adjacent to assisted living.
- Continuing Care:Campus-based models integrating independent living, assisted living, and skilled nursing through single-entry contracts.
Independent Living handles the majority of unit count; Memory Care shows the steepest expansion trajectory.
End User:
Customer type segmentation distinguishes direct residents from decision-making proxies and informal support networks.
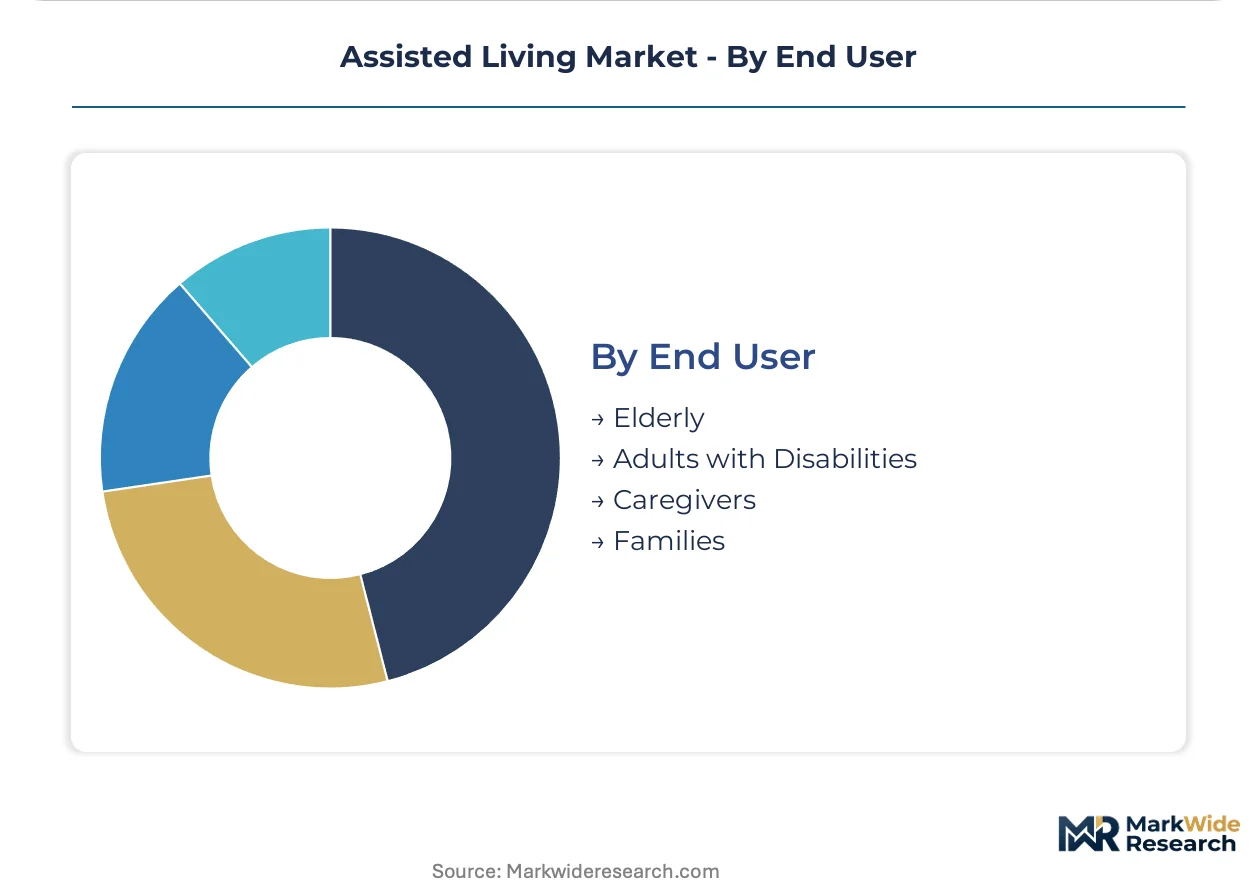
- Elderly:Adults aged 75 and older with functional limitations in activities of daily living constitute the core resident population. Arizona's retiree migration corridors concentrate demand where warm climates and tax-advantaged retirement income treatment attract inbound migration.
- Adults with Disabilities:Younger populations with physical or developmental disabilities access assisted living through Medicaid waiver programs.
- Caregivers:Family members and informal supports drive placement decisions and often subsidize private-pay rates.
- Families:Adult children coordinate site selection, contract negotiation, and ongoing care monitoring across dispersed geographic arrangements.
Elderly residents generate the dominant revenue share; Adults with Disabilities represent the fastest-climbing eligibility category through Medicaid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private-pay buyers in Sun Belt markets absorb rate increases with minimal elasticity, while Medicaid-dependent regions constrain operator pricing power through state rate-setting authority.
United States
Retiree migration to Florida, Texas, and Arizona concentrates addressable demand where certificate-of-need exemptions or streamlined approvals accelerate project timelines. CMS Conditions of Participation for skilled nursing facilities create compliance benchmarks that adjacent assisted living operators voluntarily adopt to attract hospital discharge referrals. Tampa and Orlando metro areas are pre-leasing new construction before approvals finalize.
Germany
Aging demographics and statutory long-term care insurance (Pflegeversicherung) sustain residential care demand with predictable reimbursement streams. Federal Ministry of Health regulations mandate minimum staffing ratios and quality reporting that elevate operating costs. Bavaria and North Rhine-Westphalia host dense networks of municipally subsidized facilities competing with private operators for census.
Japan
Super-aged society status drives demand for community-based integrated care systems that blend residential and home-based services. Ministry of Health, Labour and Welfare (MHLW) long-term care insurance (Kaigo Hoken) sets standardized reimbursement rates that compress margins. Tokyo and Osaka metropolitan corridors concentrate premium private-pay developments targeting affluent seniors.
United Kingdom
Local authority funding constraints create a bifurcated market between self-funded residents and state-supported placements with widening rate differentials. Care Quality Commission (CQC) inspection ratings increasingly determine occupancy velocity as digital discovery platforms amplify reputation effects. Southeast England and Greater London sustain the highest private-pay rate structures.
Canada
Provincial health authority waitlists for subsidized long-term care redirect demand toward private assisted living with limited public reimbursement. Health Canada oversight of digital health devices intersects with provincial rate-setting for continuing care. Ontario and British Columbia lead development activity where urban density supports clustered campus models.
Assisted Living Market Vendor Landscape
Capability concentration sits with specialized memory care operators; scale advantage sits with national platforms standardizing protocols across hundreds of communities. The market structure tiers between premium-positioned lifestyle brands, Medicaid-optimized value operators, and clinically intensive dementia specialists. Strategic archetypes include: national consolidators capturing referral network economies, regional density players optimizing overhead absorption, and vertical integrators controlling development-to-operations pipelines. Dominant competitive moves encompass portfolio diversification into adjacent care continuums and technology-enabled care delivery partnerships.
Within the national consolidator tier, Brookdale Senior Living and Sunrise Senior Living exemplify scale-driven positioning, while Benchmark Senior Living anchors the regional density archetype concentrated in New England markets. These operators occupy positions that reflect divergent capital allocation strategies—national footprint standardization versus geographic clustering for operational efficiency.
| Leading Market Players |
|---|
| Brookdale Senior Living |
| Atria Senior Living |
| Sunrise Senior Living |
| LCS |
| Five Star Senior Living |
| Genesis HealthCare |
| Erickson Senior Living |
| Benchmark Senior Living |
| Senior Lifestyle |
| Others |
Supply Flow & Price Mechanics
I-95 freight corridors connecting Florida construction materials to Sun Belt development sites concentrate supply-side leverage among regional distributors, compressing development yields while enabling premium rate capture in retiree migration corridors where private-pay buyers absorb cost pass-through with minimal elasticity.
Pricing Analysis
Contract structures in assisted living stratify across long-term residency agreements, month-to-month spot arrangements, and project-based pre-leasing for new construction. Three-tier pricing structure across premium, standard, and economy levels separates memory care secured units from general assisted living and independent living extensions, with certification tier and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from direct care worker wage compression elevating operating costs above 40% annual turnover thresholds in competitive labor markets. Medicaid-dependent census segments exhibit highest price sensitivity while private-pay Florida and Arizona retirees demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration for senior housing construction materials rests with regional millwork fabricators in Mexico, engineered flooring specialists in Canada, and modular component assemblers in the southeastern United States. Raw material dependencies center on lumber composites, specialized fall-resistant flooring substrates, and smart sensor hardware for remote monitoring integration. Single-source vulnerability concentrates in semiconductor-dependent monitoring devices subject to FDA oversight delays. Distribution runs through national building supply chains serving fragmented regional developer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Assisted living operators navigate a cyclical recovery anchored to retiree migration waves and Medicaid waiver expansion cycles that redirect demand between institutional and community-based settings.
For Market Incumbents: Pre-empt margin erosion by consolidating regional density in certificate-of-need protected markets like Kentucky and North Carolina, while backward integrating into technology-enabled care delivery platforms to capture specialist revenue leaking to external providers. Defensive positioning against home care technology entrants requires standardized care protocol deployment across portfolios to maintain hospital discharge referral relationships. For New Entrants and Emerging Players: Build out white-space presence in Arizona certificate-of-need exemption counties surrounding Phoenix and Tucson, where rural designation loopholes permit unlicensed bed expansion in fast-growing exurban corridors. Target Texas Medicaid managed care carve-outs through preferred provider network qualification, leveraging quality metrics and scale guarantees to secure volume commitments from privatized long-term care programs. For Investors and Strategic Acquirers: Carve-out targets emerge from hospital system real estate portfolios and distressed regional operators facing floating-rate construction debt service coverage compression in high-cost metros. Long-term viability centers on operators with demonstrated census stability across economic cycles and technology integration capabilities reducing labor intensity. Monitor state budget appropriations for home and community-based services waivers as inflection indicator for addressable demand pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Memory Care Unit Expansion | Secured environments with specialized staffing ratios command highest daily rates and attract institutional capital. |
| Telehealth Infrastructure Deployment | Tablet-based exam rooms capture specialist revenue previously leaking to external transportation-dependent providers. |
| AI-Powered Fall Detection Integration | Computer vision systems reduce liability exposure while generating predictive care planning data assets. |
| Medicaid Waiver Network Participation | State HCBS expansion converts institutional-bound beneficiaries into addressable residential care demand. |
| Regional Density Consolidation | Concentrated geographic presence reduces per-unit overhead and strengthens referral network economies. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of CMS Medicare cost reports, state Medicaid waiver enrollment data, and senior housing transaction databases. Facility operators, state licensing officials, hospital discharge planners, and institutional investors provided operational perspective on census trends and capital deployment patterns. SEC 10-K filings from publicly traded operators, NIC MAP investment data, and state certificate-of-need records furnished secondary validation. Bottom-up unit-level revenue modeling triangulated against top-down market size estimates derived from demographic projection overlays.
Forecast inputs incorporate aging-in-place technology penetration curves, retiree migration flow intensities, and Medicaid reimbursement rate trajectories across the projection horizon. Segmentation dimensions modeled include service type acuity tier, delivery model capital intensity, facility type licensure requirements, and payer source mix. CAGRs were derived from historical transaction velocity and forward supply pipeline analysis. Workforce availability indices and construction financing cost movements served as industry-specific forecast sensitivity parameters.
Sensitivities concentrate around CMS guidance revisions on home and community-based services, state budget appropriation cycles, and interest rate movements affecting development yields. Quarterly review of certificate-of-need approval velocity, pre-leasing absorption rates, and direct care wage indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Hospital Resource Management Market