
 Health Care Supply Chain Management Market | 2026-2036
Health Care Supply Chain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Health Care Supply Chain Management Market Foresight
Subscription-based analytics dashboards are pivoting how vendors monetize health care supply chain platforms, shifting buyers from perpetual licenses to recurring revenue models. Oracle Corporation leverages cloud infrastructure to anchor enterprise deployments across integrated delivery networks. McKesson Corporation dominates pharmaceutical distribution with proprietary visibility tools that extend into hospital inventory management. SAP SE competes through ERP-native modules that synchronize procurement with clinical workflows.
Health care supply chain management encompasses the planning, sourcing, logistics, and information systems that coordinate the flow of pharmaceuticals, medical devices, and biologics from manufacturer to point of care, typically operating under temperature-controlled conditions, lot-level traceability, and 48-hour replenishment cycles for critical supplies. The primary purpose is to reduce stockouts, minimize waste from expired products, and ensure regulatory compliance across multi-tier distribution networks. Pharmaceutical segments command the largest share of platform spending due to serialization mandates and cold-chain complexity, while AI-enabled demand forecasting represents the fastest-expanding technology category as hospitals seek to automate replenishment for surgical supplies. Biologics distribution remains a specialized margin pool where specialty logistics providers occupy niche positions.
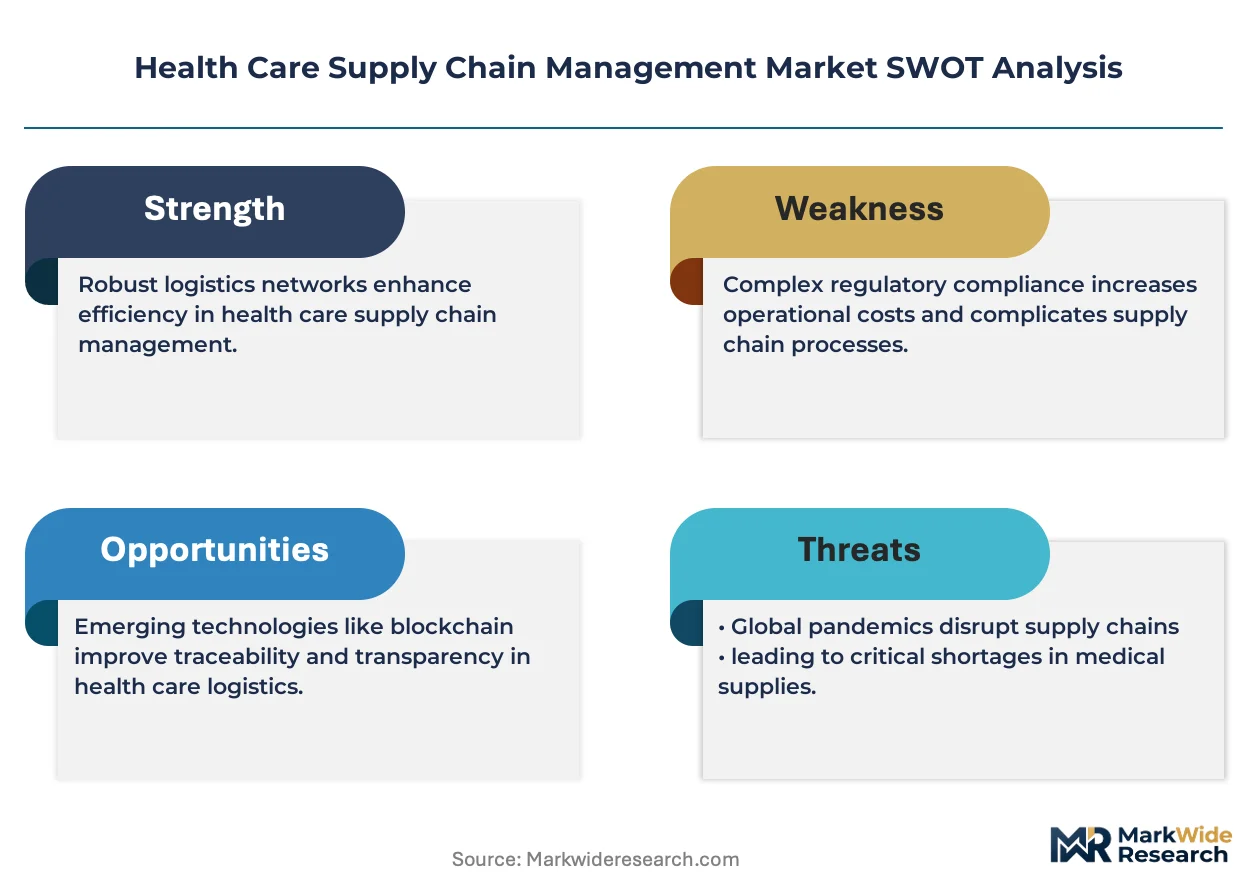
FDA DSCSA requirements for interoperable track-and-trace systems are forcing wholesalers and manufacturers to upgrade serialization infrastructure, while the EU Falsified Medicines Directive and REACH chemical compliance standards shape product data formats accepted across European distribution channels. HIPAA privacy rules further constrain how patient-linked utilization data feeds into supply chain algorithms, creating compliance costs for cloud-hosted platforms. Stakeholders must monitor how regulatory divergence between the FDA and EMA affects platform architecture decisions and whether interoperability investments will transfer across jurisdictions.
Market Dynamics
Interoperable serialization mandates are forcing wholesale infrastructure replacement across pharmaceutical distribution tiers, compressing upgrade timelines from five-year cycles to eighteen-month compliance sprints.
Growth Catalysts
- FDA DSCSA Interoperability Mandate:The 2023 enforcement deadline for electronic track-and-trace data exchange compels wholesalers to deploy cloud-native verification systems, creating immediate demand for serialization platforms across United States distribution networks.
- Cold-Chain Biologics Expansion:Cell and gene therapy manufacturers require temperature-controlled logistics with real-time monitoring, pulling investment into IoT-enabled visibility infrastructure for ultra-low temperature distribution lanes.
- AI Demand Forecasting:Hospital systems deploy machine learning models to predict surgical supply consumption, reducing carrying costs for implantable devices and automating replenishment triggers based on procedure scheduling data.
Market Restraints
- Legacy ERP Integration Costs:Hospital procurement systems built on 1990s architectures require expensive middleware layers to connect with modern cloud platforms, extending deployment timelines and inflating total cost of ownership.
- Specialized Talent Scarcity:The intersection of pharmaceutical regulatory knowledge and supply chain engineering expertise concentrates in Boston, Basel, and Singapore, creating recruitment bottlenecks for platform vendors.
- Input Cost Volatility in Cold-Chain Packaging:Phase-change materials and vacuum-insulated panels face price swings tied to petrochemical feedstocks and rare earth thermal coatings, compressing margins for specialty logistics providers.
Strategic Opportunities
- EU Falsified Medicines Directive Expansion:The 2025 rollout of end-to-end verification requirements across European hospital pharmacies creates white space for serialization vendors to penetrate previously exempt institutional settings.
- Point-of-Care Inventory Robotics:Automated dispensing cabinets with RFID-enabled restocking are unifying pharmacy and nursing floor supply management, opening deployment opportunities in academic medical centers.
- India PLI Scheme for Medical Devices:Domestic manufacturing incentives are attracting contract manufacturers to Ahmedabad and Hyderabad, requiring localized supply chain platforms that bridge multinational ERP systems with Indian distribution networks.
Industry Challenges
- HIPAA-Compliant Data Architecture:Cloud-hosted platforms must implement patient de-identification pipelines before utilization data feeds demand algorithms, adding engineering complexity and audit costs.
- Multi-Jurisdiction Serialization Format Harmonization:FDA EPCIS standards diverge from EU EMVO data formats, forcing vendors to maintain parallel verification engines and complicating cross-border product returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Care Supply Chain Management Market |
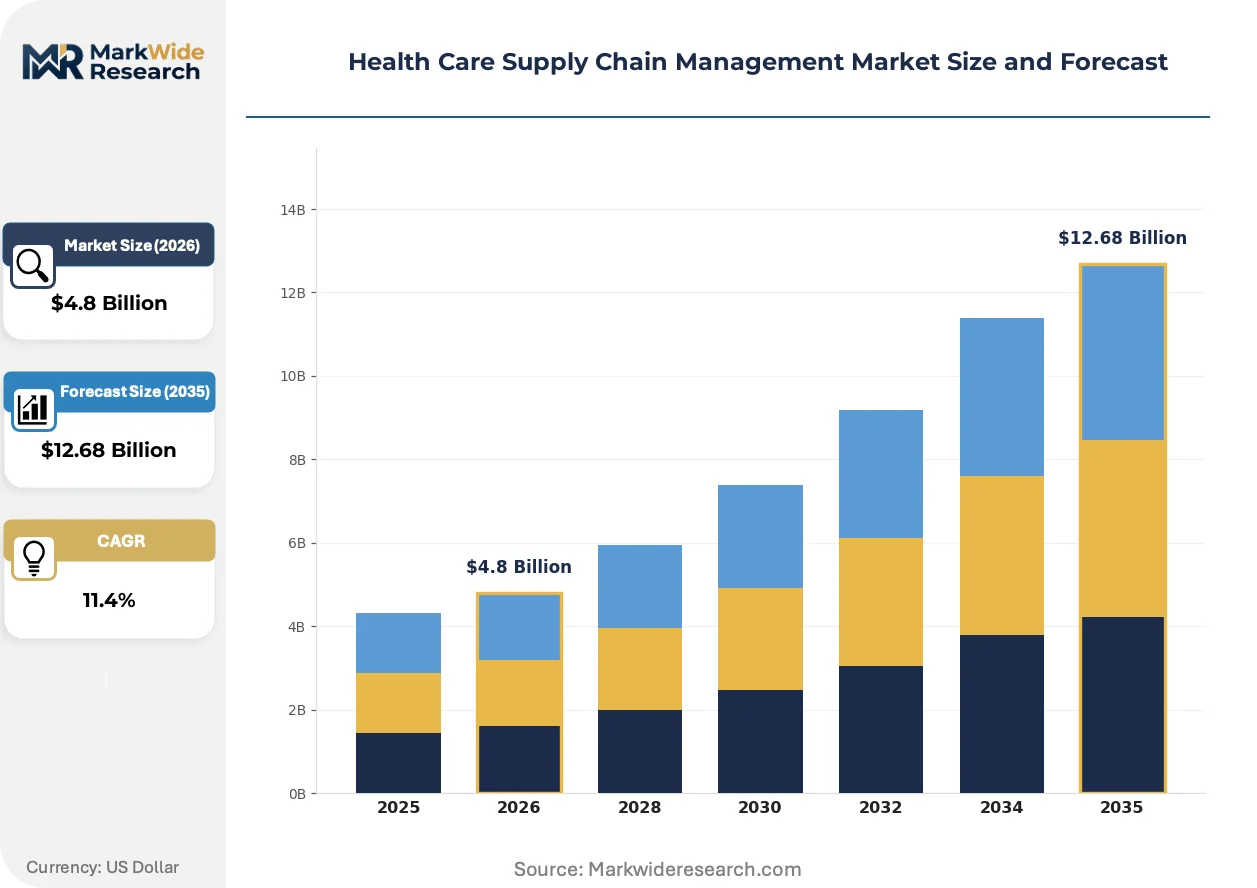
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Medical Devices, Biologics, Surgical Supplies End User: Hospitals, Pharmacies, Clinics, Distributors Technology: Blockchain, IoT, RFID, AI Delivery Mode: Direct Delivery, Drop Shipping, Third-Party Logistics, Specialty Distribution |
| Companies Covered | Oracle Corporation, Global Healthcare Exchange, McKesson Corporation, Infor, SAP SE, Cencora, Tecsys Inc., Henry Schein Inc., Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Care Supply Chain Management Market Shifts & Advancements
Digital twin technology is compressing planning horizons across health care supply chains, enabling real-time simulation of disruption scenarios that previously required quarterly business continuity reviews.
Blockchain-enabled verification networks are unifying manufacturer, wholesaler, and dispenser data into immutable ledgers. Pharmaceutical distributors in the United States are piloting these systems ahead of FDA DSCSA enforcement. The technology is unifying previously siloed transaction records into single-source-of-truth architectures that accelerate suspect product investigations from weeks to hours.
The EU Medical Device Regulation (MDR) Unique Device Identification requirements are mandating serialized labeling for implantable devices. Manufacturers serving European markets must upgrade labeling lines and master data management systems. Cardiovascular implant suppliers face the steepest compliance curves due to high product variety and existing legacy catalog structures.
Consolidated procurement consortia are displacing hospital-level purchasing autonomy. Multi-hospital systems in Germany and Japan are centralizing supplier negotiations through shared service organizations. This concentration is most visible in orthopedic implant categories, where volume aggregation is compressing vendor margins and privileging suppliers with direct-to-manufacturer EDI integration capabilities.
Health Care Supply Chain Management Market Segmentation
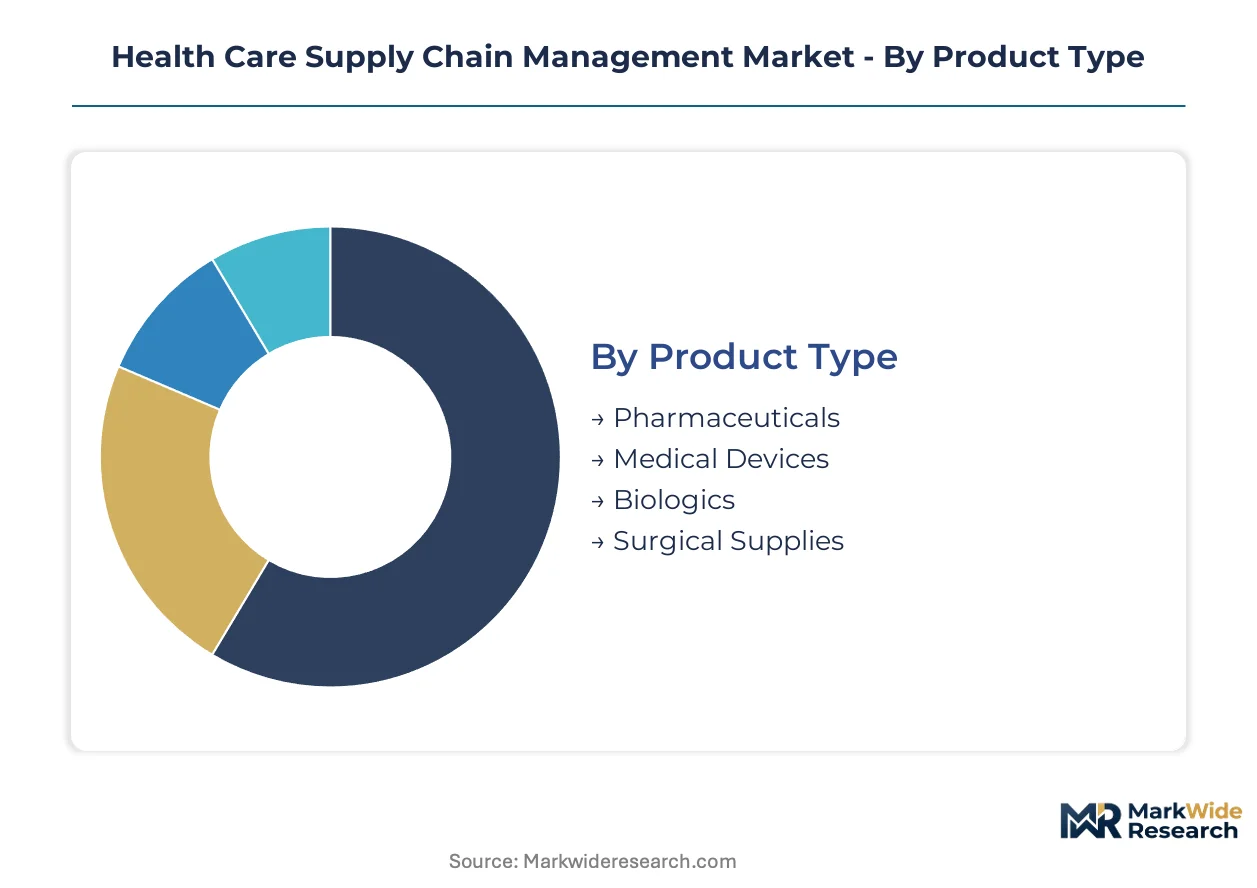
Health care supply chain platforms must accommodate divergent regulatory regimes, temperature requirements, and traceability standards across product categories. Segmentation reveals where platform complexity concentrates and which technology investments deliver differentiated returns.
Product Type:
Platform configuration varies sharply by product risk classification and serialization burden.
- Pharmaceuticals:Small-molecule drugs require lot-level traceability under FDA DSCSA and EU Falsified Medicines Directive mandates. Cold-chain vaccines and controlled substances drive investment in temperature monitoring and chain-of-custody documentation across United States and German distribution networks.
- Biologics:Cell and gene therapies demand ultra-low temperature logistics with real-time IoT monitoring and contingency routing. Manufacturers in Boston and Basel clusters require specialized platforms that integrate with cryogenic storage infrastructure and courier handoff protocols.
- Medical Devices:Implantable devices face EU MDR Unique Device Identification requirements and FDA UDI rules, necessitating master data management upgrades for cardiovascular and orthopedic suppliers.
- Surgical Supplies:Disposable instruments and consumables operate on high-velocity replenishment cycles, with hospital systems automating par-level restocking through RFID-enabled cabinet systems.
Pharmaceuticals lead volumes today; biologics is gaining share fastest.
End User:
Procurement sophistication and compliance exposure shape platform requirements across buyer types.
- Hospitals:Integrated delivery networks in the United States and Germany deploy enterprise-wide platforms synchronizing pharmacy, surgical services, and materials management. Academic medical centers in Japan pilot AI demand forecasting for implantable devices.
- Distributors:Pharmaceutical wholesalers bear primary serialization compliance responsibility, requiring verification engines that interoperate with manufacturer EPCIS data and dispenser authentication systems.
- Pharmacies:Hospital and retail pharmacies implement verification systems for suspect product quarantine and returns processing under tightening FDA enforcement timelines.
- Clinics:Ambulatory surgery centers and specialty practices adopt lightweight cloud platforms with limited ERP integration, prioritizing mobile replenishment alerts over enterprise workflow orchestration.
Hospitals command the largest platform spend; distributors face the steepest compliance cost curves.
Technology:
Technology selection reflects trade-offs between proven interoperability and emerging capability.
- AI:Machine learning models predict surgical supply consumption and automate replenishment triggers based on procedure scheduling data, with hospital systems in the United States deploying predictive analytics for orthopedic and cardiac implant categories.
- Blockchain:Distributed ledger pilots unify manufacturer, wholesaler, and dispenser transaction records into immutable verification architectures, accelerating suspect product investigations from weeks to hours ahead of FDA enforcement deadlines.
- RFID:Item-level tagging enables automated dispensing cabinet restocking and operating room supply tracking, with academic medical centers in Germany and Japan standardizing on EPC Gen2 protocols for high-value implants.
- IoT:Temperature and location sensors monitor cold-chain integrity for biologics distribution, feeding real-time alerts into logistics control towers operated by specialty pharmaceutical couriers.
RFID dominates installed base; AI is climbing the fastest as hospitals automate demand planning.
Delivery Mode:
Channel structure determines platform integration depth and data exchange protocols.
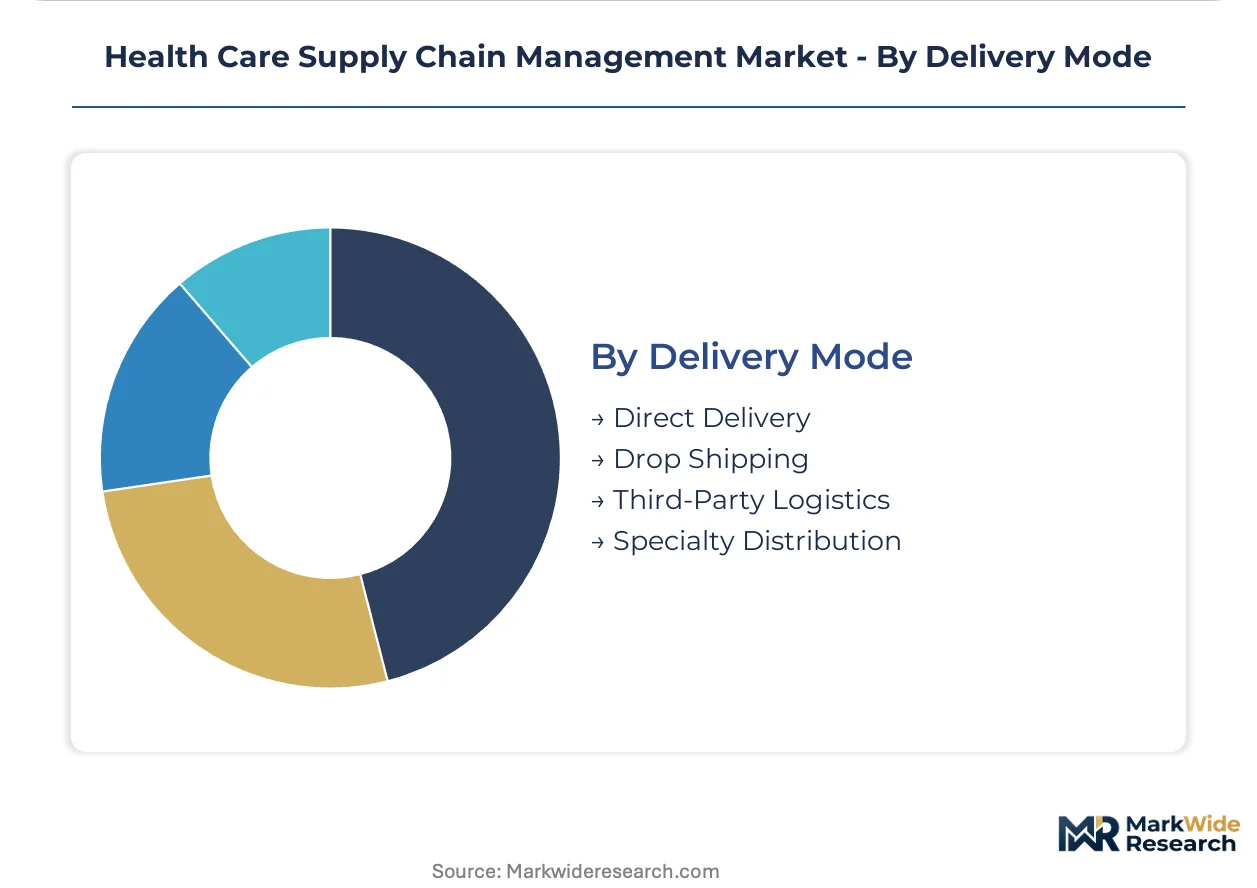
- Third-Party Logistics:Contract logistics providers operate multi-client pharmaceutical distribution centers with shared serialization infrastructure, requiring platforms that segregate tenant data while enabling regulatory audit trails.
- Specialty Distribution:Limited-distribution networks for cell therapies and orphan drugs combine white-glove handling with direct-to-patient delivery, necessitating platforms that coordinate manufacturer, hub, and home infusion site workflows.
- Direct Delivery:Manufacturer-to-hospital shipments for implantable devices bypass wholesale tiers, demanding EDI integration between supplier ERP systems and hospital procurement modules.
- Drop Shipping:Emergency and specialty pharmaceuticals move through distributor-orchestrated direct-to-pharmacy flows, complicating inventory visibility and returns processing under DSCSA verification requirements.
Third-party logistics handles the greatest transaction volume; specialty distribution carries the highest margin per shipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands platform spending through FDA serialization mandates, while Germany matches investment intensity via EU regulatory complexity. Japan concentrates demand forecasting adoption in academic medical centers. India attracts localized platform development through manufacturing incentives.
United States
Hospital networks and pharmaceutical distributors drive enterprise platform deployments under FDA DSCSA interoperability deadlines. The 2023 enforcement timeline compresses upgrade cycles to eighteen-month sprints. Boston and San Francisco clusters host specialty biologics logistics providers integrating cryogenic infrastructure with cloud-native visibility systems.
Germany
Integrated delivery networks centralize procurement through shared service organizations, privileging suppliers with direct EDI integration. EU Falsified Medicines Directive and MDR requirements shape serialization investments. The Rhine-Ruhr and Bavaria regions concentrate pharmaceutical distribution hubs upgrading verification engines for cross-border compliance.
Japan
Academic medical centers pilot AI demand forecasting for orthopedic and cardiac implant categories. METI guidelines influence supply chain digitization priorities. The Kanto and Kansai regions house hospital systems deploying machine learning models tied to procedure scheduling data for automated replenishment.
India
Domestic medical device manufacturing incentives under the PLI scheme attract contract manufacturers to Ahmedabad and Hyderabad. CDSCO traceability requirements intersect with multinational ERP integration challenges. The Maharashtra and Telangana clusters require localized platforms bridging global systems with Indian distribution networks.
Switzerland
Basel anchors biologics distribution specialization with ultra-low temperature logistics infrastructure. Swissmedic standards complement EU regulatory frameworks for cross-border product flows. The Basel-Land region hosts cell therapy manufacturers requiring cryogenic storage integration with real-time IoT monitoring platforms.
Health Care Supply Chain Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors and pharmaceutical distributors commanding distinct tiers. The market structure concentrates around cloud-native platform providers and ERP-integrated module suppliers. Three archetypes dominate: enterprise software conglomerates with health care verticals, pharmaceutical distributors extending visibility tools, and specialized logistics technology vendors. Competitive moves center on cloud infrastructure anchoring and serialization engine interoperability investments.
Among enterprise technology providers, Oracle Corporation and SAP SE occupy positions anchoring hospital network deployments through cloud and ERP-native architectures. McKesson Corporation exemplifies the distributor-extended archetype, leveraging pharmaceutical distribution infrastructure to penetrate hospital inventory management. These three represent the primary competitive vectors shaping platform architecture decisions and recurring revenue model transitions.
| Leading Market Players |
|---|
| Oracle Corporation |
| Global Healthcare Exchange |
| McKesson Corporation |
| Infor |
| SAP SE |
| Cencora |
| Tecsys Inc. |
| Henry Schein Inc. |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
Hospital procurement committee consolidation across United States integrated delivery networks is compressing vendor margins and forcing platform providers toward subscription-based recurring revenue models that embed professional services.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for health care supply chain platforms. Three-tier pricing structure across premium, standard, and economy levels separates enterprise deployments with full ERP integration from mid-market SaaS tiers and lightweight clinic solutions. Price differentiation rests on certification grade (FDA-validated vs. non-validated environments) and customization depth for serialization workflows. Cost compression in the standard tier is intensifying because distributor-extended vendors leverage existing pharmaceutical infrastructure to undercut pure-play software pricing. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with NIH funding demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Rhine-Ruhr and Bavaria anchor European pharmaceutical verification networks, with hub-and-spoke patterns extending into hospital pharmacy consortia. Manufacturing concentration clusters in United States, Germany, and Switzerland for platform development, while India supplies engineering talent and localized deployment capacity. Component dependencies include cryogenic storage vessels for biologics logistics, RFID inlays for item-level tracking, and cloud compute instances for real-time analytics. Single-source vulnerability in phase-change materials for cold-chain packaging exposes margins to petrochemical feedstock volatility. Distribution runs through pharmaceutical wholesalers with shared serialization infrastructure serving multi-client tenant environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as FDA DSCSA enforcement and EU Falsified Medicines Directive expansion shift procurement criteria toward interoperable, audit-ready platforms over point solutions.
For Market Incumbents: Anticipate margin compression from distributor-extended competitors by deepening vertical integration into cryogenic logistics infrastructure and accelerating cloud-native architecture transitions. Oracle Corporation and SAP SE should prioritize hospital system EDI integration capabilities as the priority lever against McKesson Corporation's pharmaceutical distribution leverage. Certification investment in EU MDR-compliant verification engines defends position against emerging logistics technology vendors. For New Entrants and Emerging Players: EU Falsified Medicines Directive expansion in Germany opens a window for serialization specialists to penetrate hospital pharmacy settings previously exempt from end-to-end verification. Target academic medical centers in Japan with AI demand forecasting modules for orthopedic implant categories. White space concentrates in India PLI scheme contract manufacturers requiring localized platforms bridging multinational ERP systems. Go-to-market through specialty pharmaceutical couriers with existing cryogenic infrastructure relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized logistics technology vendors possessing cryogenic handling protocols and real-time IoT monitoring platforms. Five-to-ten year viability favors vendors with FDA-validated verification engines and EU EMVO interoperability. Target acquisition archetype: mid-cap specialists with hospital system pilot contracts in Boston or Basel biologics clusters. Signal to watch: FDA enforcement action timelines accelerating wholesaler upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Oracle Corporation leverages infrastructure to anchor enterprise hospital network deployments. |
| Serialization Engine Interoperability Investment | FDA DSCSA and EU EMVO dual compliance creates technical moats for verification platform vendors. |
| AI Demand Forecasting Module Development | Hospital systems in Kanto region deploy machine learning for orthopedic implant replenishment automation. |
| Cryogenic Logistics Infrastructure Expansion | Cell therapy manufacturers in Basel require ultra-low temperature integration with real-time monitoring. |
| Hospital System EDI Integration Deepening | German shared service organizations privilege suppliers with direct-to-manufacturer procurement connectivity. |
Research Methodology
Direct dialogue with hospital supply chain executives, pharmaceutical distributor operations leads, GPO contracts managers, and regulatory affairs specialists anchored qualitative findings. Secondary validation drew from FDA DSCSA guidance documents, EU EMVO verification data, CMS Medicare hospital procurement records, and pharmaceutical wholesaler SEC disclosures. Bottom-up platform deployment estimates triangulated against top-down health care IT spending analyses.
Bottom-up modeling segmented the market by product type (pharmaceuticals, biologics, medical devices, surgical supplies), end user (hospitals, distributors, pharmacies, clinics), technology (AI, blockchain, RFID, IoT), and delivery mode (third-party logistics, specialty distribution, direct delivery, drop shipping). CAGRs were derived from regression analysis against regulatory enforcement timelines and hospital capital expenditure cycles. Forecast inputs included FDA interoperability deadline compliance rates and EU MDR Unique Device Identification adoption curves across the projection horizon.
Revisions become necessary when FDA enforcement timelines shift, EU regulatory divergence accelerates, or cold-chain input cost volatility disrupts specialty logistics margins. Forecasts reflect documented assumptions regarding hospital procurement centralization rates and cloud infrastructure pricing trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Audiology Services Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Medical Case Management Services Market