
 Global Cord Blood Banking Services Market | 2026-2036
Global Cord Blood Banking Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cord Blood Banking Services Market Foresight
A capital-intensity divergence between cryogenic infrastructure owners and marketing-heavy brokers is unwinding competitive stability in cord blood banking. CBR Systems Inc. leverages its vertically integrated collection-to-storage network to sustain pricing power across North American maternity wards. Cryo-Cell International anchors its position through proprietary cryopreservation protocols that extend viable cell retention timelines. Global Cord Blood Corporation dominates licensed operations across multiple Chinese provinces, navigating regulatory complexity that smaller entrants cannot match.
Cord blood banking services encompass the collection, processing, testing, cryopreservation, and long-term storage of hematopoietic stem cells derived from umbilical cord blood, maintained at temperatures below minus 150 degrees Celsius in liquid nitrogen vapor-phase systems. These services supply matched allogeneic and autologous stem cell units for transplantation in hematologic malignancies, bone marrow failure syndromes, and inherited metabolic disorders. Autologous storage commands premium pricing from expectant parents seeking biological insurance, while public banking operates on donation models subsidized by health systems and research grants. Regenerative medicine applications are expanding fastest as clinical trials explore cord blood derivatives for neurological and cardiovascular conditions, though stem cell transplantation remains the revenue core. Long-term storage contracts generate recurring fee streams that stabilize operator cash flows against cyclical birth-rate fluctuations.
The FDA enforces current Good Tissue Practice standards and licensure requirements under Section 351 of the Public Health Service Act, elevating compliance costs for processors while screening out subscale competitors. AABB accreditation and FACT-NetCord standards further constrain market access by mandating validated cryopreservation protocols and sterility assurance systems. China's NMPA imposes dual carbon goals on biorepository energy consumption, reshaping facility location decisions toward renewable-powered industrial zones. Stakeholders must monitor how CAR-T manufacturing expansion competes for liquid nitrogen supply chains and specialized logistics capacity.
Market Dynamics
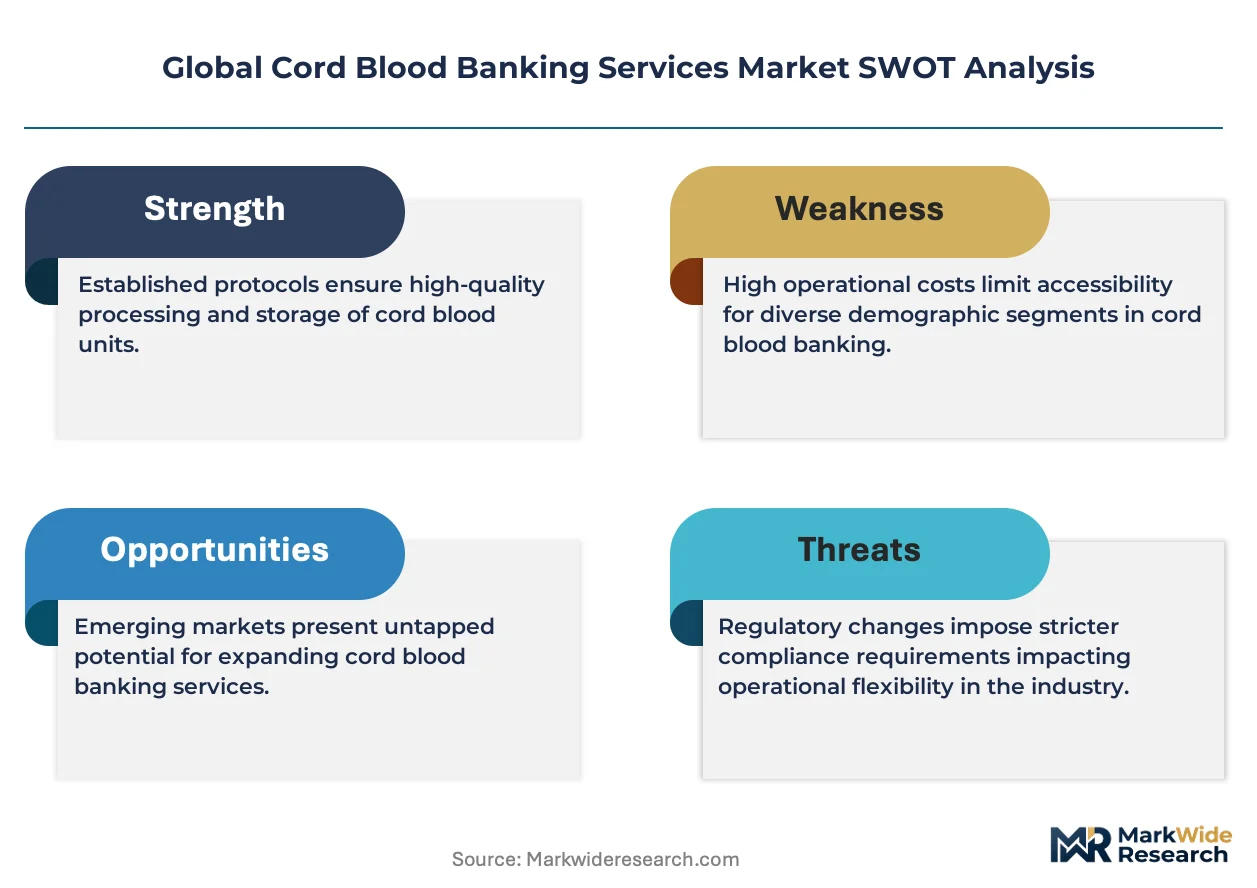
The FDA's licensure requirements under Section 351 of the Public Health Service Act are compressing the competitive field by elevating compliance costs beyond the reach of subscale operators. This regulatory tightening favors vertically integrated incumbents with validated cryopreservation protocols and captive laboratory networks.
Growth Catalysts
- Regenerative medicine pipelines:Clinical trials exploring cord blood derivatives for neurological and cardiovascular conditions are expanding the addressable market beyond transplantation. Expectant parents in the United States are enrolling in private storage programs at accelerating rates.
- China's NMPA dual carbon goals:Biorepository energy consumption mandates are reshaping facility location decisions toward renewable-powered industrial zones, creating first-mover advantages for compliant operators.
- Liquid nitrogen supply chain competition:CAR-T manufacturing expansion is intensifying competition for cryogenic logistics capacity, prompting cord blood banks to secure long-term supply contracts.
Market Restraints
- Cryogenic infrastructure capex intensity:Vapor-phase liquid nitrogen systems and redundant backup generators require capital deployment that excludes new entrants with limited balance sheets.
- Birth rate cyclicality:Contracting fertility rates in Japan and South Korea are compressing addressable volume in historically high-penetration markets.
- Public banking subsidy dependency:Donation-model operations in France and the United Kingdom rely on health system grants that face periodic austerity pressures.
Strategic Opportunities
- India's underpenetrated maternity sector:Private hospital networks in Maharashtra and Karnataka are establishing collection partnerships with minimal incumbent competition.
- EU Green Deal alignment:Renewable-powered cryogenic facilities qualify for CSRD-adjacent sustainability financing instruments.
- Allogeneic expansion protocols:Automated cell expansion technologies are enabling small-volume cord blood units to achieve therapeutic thresholds previously requiring multiple donors.
Industry Challenges
- FACT-NetCord certification timelines:Validation of sterility assurance systems and cryopreservation protocols extends facility commissioning by 18-24 months.
- Cross-border sample transport complexity:Temperature excursion risks during international logistics require redundant monitoring infrastructure that fragments operational scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cord Blood Banking Services Market |
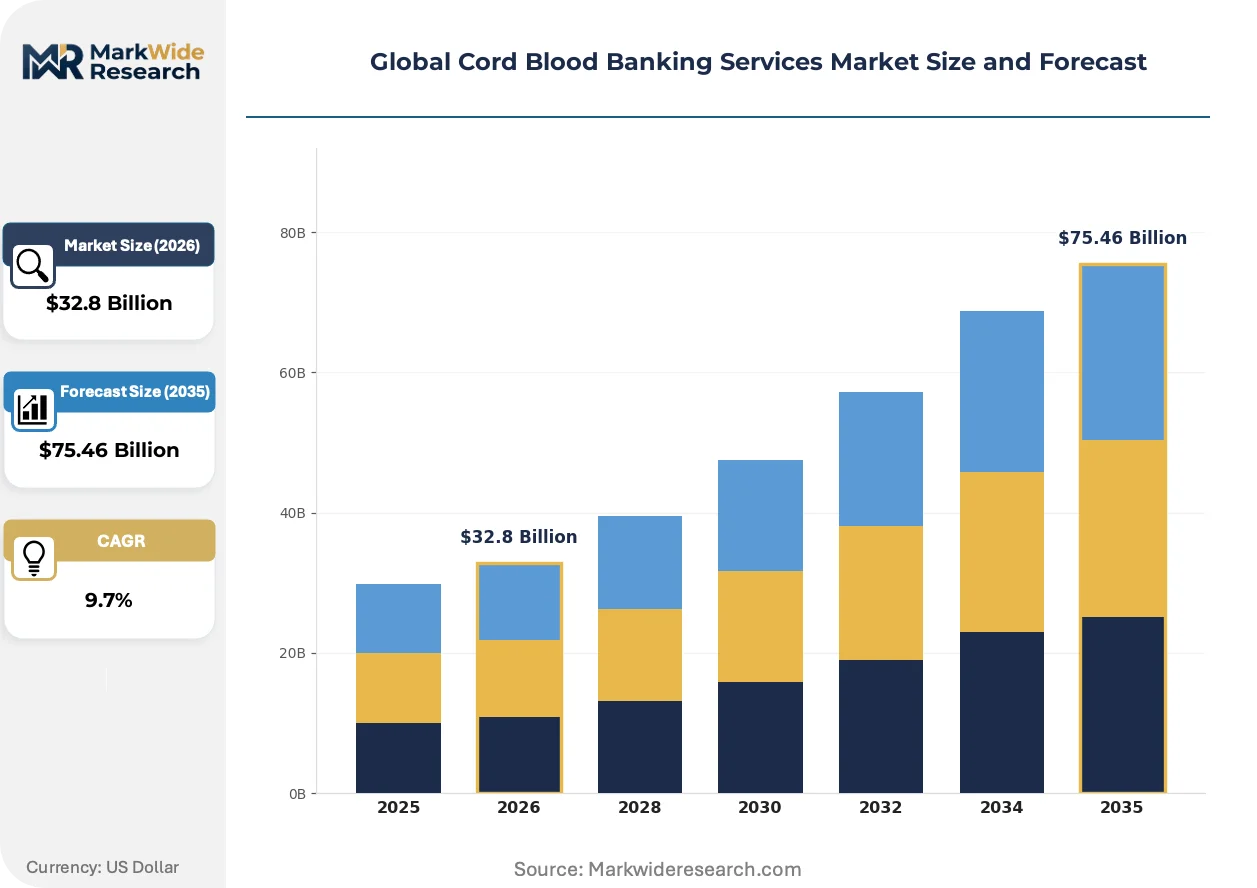
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $75.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Autologous Storage, Allogenic Storage, Directed Donation, Public Banking Application: Stem Cell Transplantation, Regenerative Medicine, Immunotherapy, Genetic Disorder Treatment End User: Hospitals, Research Institutes, Fertility Clinics, Biotechnology Firms Delivery Model: Onsite Collection, Mobile Collection, Cryopreservation, Long-term Storage |
| Companies Covered | Global Cord Blood Corporation, CBR Systems Inc., Cryo-Cell International, Cordlife Group Limited, PerkinElmer Inc. (ViaCord), AlphaCord LLC, California Cryobank Stem Cell Services LLC, Cord Blood Foundation (Smart Cells International), CSG-BIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cord Blood Banking Services Market Shifts & Advancements
Automation is penetrating cord blood processing workflows, displacing manual cell separation methods that introduced variability and contamination risk. This shift is compressing processing costs while tightening quality benchmarks across licensed facilities.
Automated cell separation platforms utilizing closed-system centrifugation and magnetic bead selection are supplanting manual density-gradient processing in high-throughput laboratories. European facilities under EMA oversight are adopting these systems fastest, driven by batch-record automation requirements. The technology is enabling single-technician processing of multiple concurrent collections, compressing labor cost structures by approximately 40 percent.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon-based cooling agents used in backup refrigeration systems. Cryogenic facilities must retrofit to natural refrigerant alternatives or liquid nitrogen redundancy by 2030. German and Dutch operators are accelerating capital deployment to avoid operational interruption during compliance windows.
Direct-to-consumer enrollment through obstetrician partnership programs is displacing hospital-based collection consents. Expectant parents in the United States are completing storage contracts via telehealth consultations before third-trimester appointments. This channel shift concentrates marketing spend toward digital patient education platforms and away from bedside counseling infrastructure.
Global Cord Blood Banking Services Market Segmentation
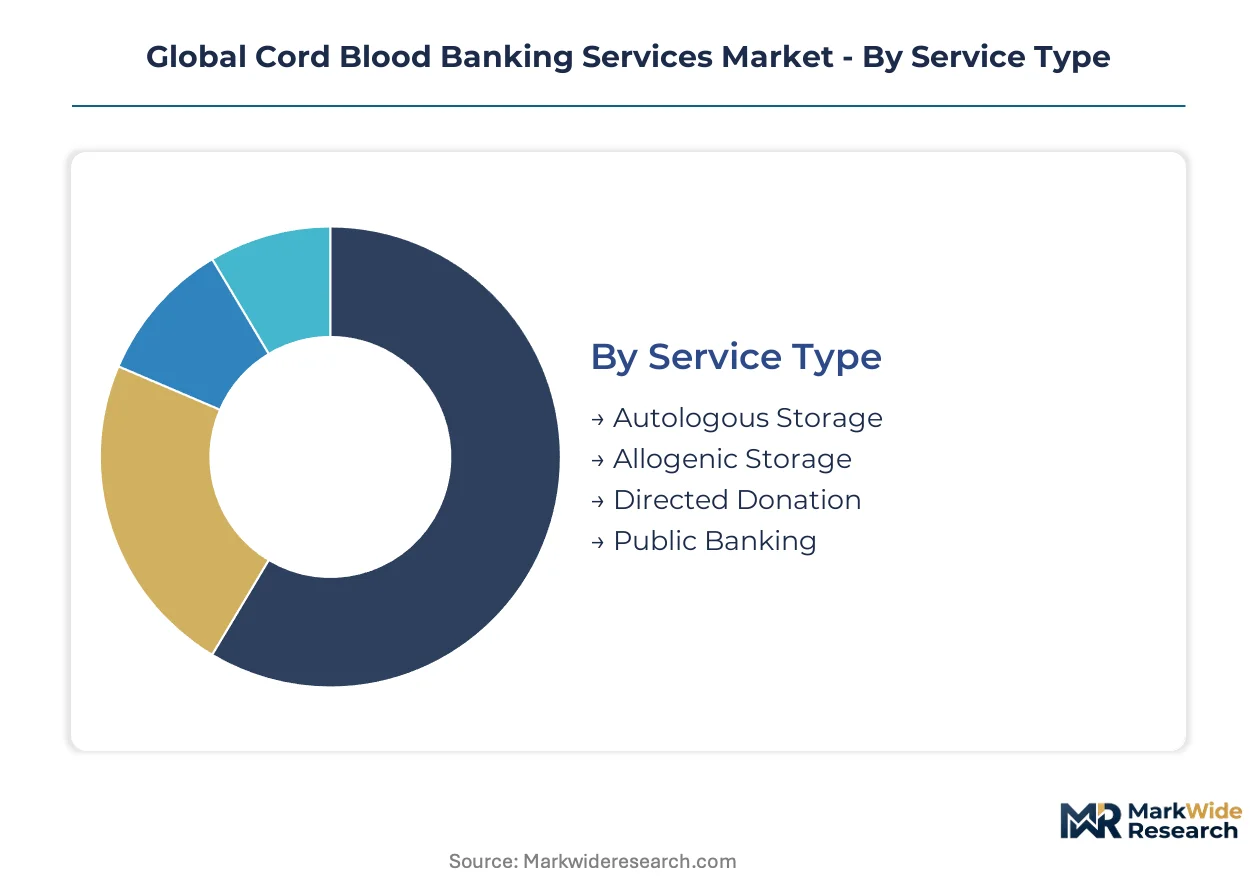
Cord blood banking operators configure service portfolios around biological ownership models and clinical application pathways. Segment boundaries determine pricing architecture, regulatory exposure, and customer acquisition economics across maternity networks and transplant centers.
Service Type:
Substitute pressure concentrates heaviest where public donation models compete against fee-based private storage, reshaping margin structures across ownership categories.
- Autologous Storage:Family-retained units collected at birth and cryopreserved for exclusive future use by the donor or siblings. United States maternity wards generate the densest enrollment as expectant parents purchase biological insurance against future malignancies or metabolic disorders.
- Allogenic Storage:Unrelated donor units processed for transplant registry matching and distributed through national marrow donor programs. Demand concentrates in Germany and the United Kingdom where public health systems underwrite donor recruitment and HLA-typing infrastructure.
- Directed Donation:Sibling-directed collections for families with known genetic conditions requiring hematopoietic stem cell rescue. Pediatric oncology centers in France and Italy drive utilization where thalassemia and sickle cell screening identifies at-risk pregnancies.
- Public Banking:Donation-model operations relying on health system grants and research subsidies without fee-for-service revenue. Budget pressures in Spain and Portugal are constraining collection site expansion despite registry demand growth.
Autologous storage retains volume leadership; directed donation holds the steepest expansion curve as prenatal genetic screening penetrates Southern European markets.
Application:
Clinical trial pipelines are redrawing segment boundaries as cord blood derivatives migrate beyond oncology into neurological and cardiovascular protocols.
- Stem Cell Transplantation:Established therapeutic use in leukemia, lymphoma, and bone marrow failure syndromes requiring myeloablative conditioning. Transplant centers in the United States and Japan maintain the highest procedure volumes with mature referral networks.
- Regenerative Medicine:Emerging applications in cerebral palsy, autism spectrum disorders, and hypoxic-ischemic encephalopathy through intravenous or intrathecal delivery. Duke University and Sungkyunkwan University clinical programs are accelerating parent demand for speculative storage.
- Immunotherapy:Natural killer cell expansion and CAR-engineered products derived from cord blood progenitors. Contract manufacturing organizations in Singapore and South Korea are building GMP capacity to serve biopharma sponsors.
- Genetic Disorder Treatment:Hurler syndrome, Krabbe disease, and other lysosomal storage disorders amenable to allogeneic stem cell gene correction. Newborn screening expansion in California and New York is identifying candidates for preemptive transplantation.
Stem cell transplantation commands revenue concentration; regenerative medicine claims the most aggressive enrollment growth as expectant parents hedge against developmental neurological conditions.
End User:
Procurement authority fragmentation across clinical and research settings creates divergent contracting requirements and validation standards.
- Hospitals:Maternity units performing collections and transplant centers receiving processed units for infusion. Academic medical centers in Massachusetts and Pennsylvania operate the largest dual-role programs integrating collection through transplantation.
- Research Institutes:Universities and government laboratories accessing cryopreserved samples for stem cell biology and developmental studies. NIH-funded consortia in Maryland and California maintain the deepest biorepository partnerships.
- Fertility Clinics:Assisted reproduction centers offering collection as an adjunct service to in-vitro fertilization patients. Private clinic networks in São Paulo and Mexico City are bundling storage with preimplantation genetic testing packages.
- Biotechnology Firms:Cell therapy developers sourcing starting material for allogeneic product manufacturing. Cambridge and Basel cluster companies are signing multi-year supply agreements with established banks.
Hospitals anchor procurement volume; biotechnology firms are expanding contract value fastest as allogeneic cell therapy pipelines mature.
Delivery Model:
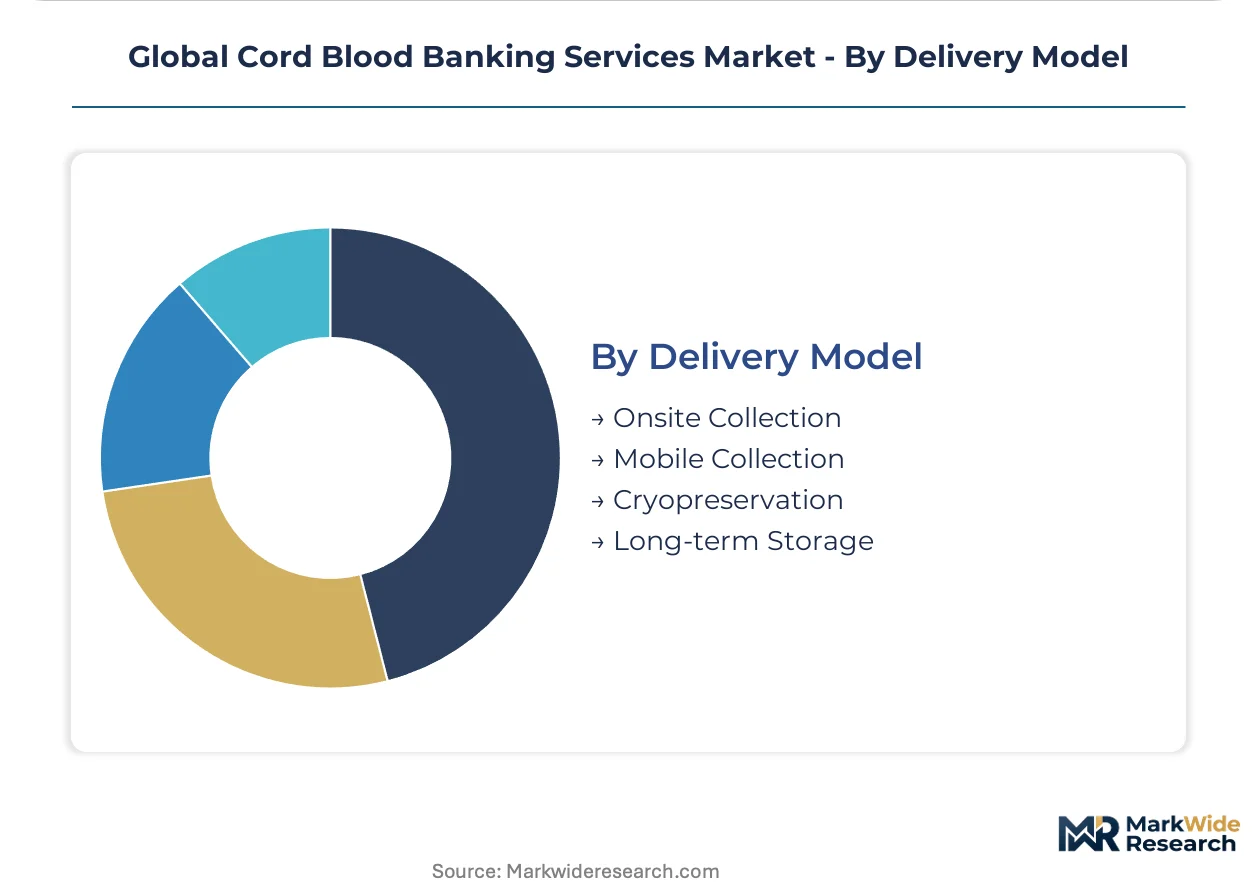
Capital deployment requirements vary sharply between fixed infrastructure and distributed logistics networks, filtering operator scale thresholds.
- Onsite Collection:Hospital-embedded procurement teams performing cord blood harvest immediately post-delivery. Major systems in Texas and Florida maintain dedicated collection staff across multiple delivery units.
- Mobile Collection:Courier-coordinated harvest at birthing centers or homes with subsequent transport to processing laboratories. Netherlands and Belgium operators have refined this model for rural and independent midwife practices.
- Cryopreservation:Controlled-rate freezing and vapor-phase liquid nitrogen storage maintaining cell viability across decades. Redundant backup generators and 24-hour monitoring systems concentrate in renewable-powered industrial zones under China's NMPA dual carbon mandates.
- Long-term Storage:Annual fee contracts extending 18-21 years with options for adult continuation. United States operators are testing lifetime prepayment structures to lock in customer lifetime value against birth rate volatility.
Long-term storage generates recurring revenue concentration; mobile collection is penetrating fastest where hospital consolidation has reduced independent maternity access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in cryopreserved biological materials favor net-importing jurisdictions with advanced transplant infrastructure over collection-heavy emerging markets. The United States absorbs processed units from multiple origins while maintaining minimal outbound shipment volume. Germany and China operate as regional processing hubs serving neighboring territories with limited domestic laboratory capacity.
United States
Expectant parents in Texas and Florida drive private storage enrollment through direct-to-consumer telehealth channels. FDA licensure under Section 351 of the Public Health Service Act restricts cross-border unit acceptance to validated facilities. Academic medical centers in Massachusetts and Pennsylvania maintain the largest integrated collection-to-transplantation networks.
China
Rising middle-class demand for biological insurance products concentrates in coastal provinces with advanced maternity infrastructure. NMPA dual carbon goals on biorepository energy consumption redirect facility investments toward renewable-powered industrial zones in Jiangsu and Zhejiang. Global Cord Blood Corporation operates licensed facilities across multiple provinces under this regulatory framework.
Germany
Public health system subsidies sustain allogeneic donation-model operations serving European transplant registries. EMA oversight and EU F-Gas Regulation compliance requirements accelerate automation adoption in processing laboratories. Frankfurt and Munich clusters host the continent's largest cryopreservation facilities with redundant liquid nitrogen supply contracts.
India
Private hospital networks in Maharashtra and Karnataka are establishing collection partnerships with minimal incumbent competition. CDSCO oversight of cellular therapy products remains less prescriptive than FDA or EMA frameworks, lowering barriers to facility commissioning. Mumbai and Bangalore emerge as collection coordination centers for mobile harvest operations.
Japan
Contracting fertility rates compress addressable birth volume despite high per-capita private storage penetration. METI industrial policy supports automated processing equipment deployment to offset labor cost pressures. Tokyo and Osaka metropolitan areas concentrate the remaining collection activity through consolidated maternity hospital networks.
Global Cord Blood Banking Services Market Competitive Landscape
Concentration sits with vertically integrated operators possessing captive laboratory networks and validated cryopreservation protocols. The competitive field compresses under FDA licensure cost burdens that exclude subscale entrants. Three archetypes dominate: North American marketing-heavy brokers, Asia-Pacific multi-province license holders, and European automation-focused processors. Dominant competitive moves include geographic expansion through provincial licensing and strategic partnerships with maternity hospital networks.
Among North American incumbents, CBR Systems Inc. and Cryo-Cell International exemplify the vertically integrated archetype with collection-to-storage infrastructure. Global Cord Blood Corporation occupies a distinct position as a multi-jurisdictional license holder navigating China's provincial regulatory complexity. These three entities represent contrasting strategic foundations: marketing-intensive patient acquisition, proprietary cryopreservation science, and regulatory navigation at scale.
| Leading Market Players |
|---|
| Global Cord Blood Corporation |
| CBR Systems Inc. |
| Cryo-Cell International |
| Cordlife Group Limited |
| PerkinElmer Inc. (ViaCord) |
| AlphaCord LLC |
| California Cryobank Stem Cell Services LLC |
| Cord Blood Foundation (Smart Cells International) |
| CSG-BIO |
| Others |
Supply & Pricing Matrix
Long-term storage contracts with prepayment structures lock in both cryogenic capacity access and price visibility for expectant parents across United States maternity networks. These arrangements stabilize operator cash flows against birth-rate volatility while committing families to 18-21 year fee schedules insulated from annual price adjustments.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Global Cord Blood Banking Services Market. Premium tiers bundle FACT-NetCord certification, automated processing protocols, and lifetime storage guarantees; standard tiers offer AABB-accredited processing with 20-year contracts; economy tiers provide basic cryopreservation without expansion-ready cell counts. Price differentiation rests on certification grade and processing automation level. Cost compression in economy tiers is intensifying because public banking subsidies in France and the United Kingdom constrain private storage penetration. Price-sensitive segments concentrate among first-time parents in underpenetrated Indian markets; least price-sensitive buyers populate high-income United States metropolitan areas seeking regenerative medicine hedges.
Supply Chain Analysis
Inventory buffers for liquid nitrogen vapor-phase systems extend 30-45 days across redundant backup generators, constraining facility location flexibility. Geographic supply concentrates in the United States, China, and Germany as regional processing hubs serving neighboring territories with limited domestic laboratory capacity. Raw material dependencies center on liquid nitrogen feedstock, cryogenic storage vessels, and automated cell separation platforms. Single-source vulnerability runs through specialized logistics providers for temperature-controlled sample transport. Distribution runs through hospital-embedded collection teams, mobile courier networks, and direct-to-consumer telehealth channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward expectant parents as direct-to-consumer enrollment platforms fragment hospital-based collection consents. Hospital consolidation in Texas and Florida has reduced independent maternity access, concentrating procurement leverage among remaining large health systems.
For Market Incumbents: Compound defensive positioning through FACT-NetCord certification investments and captive cryogenic infrastructure expansion in renewable-powered industrial zones. Automate processing workflows to compress labor cost structures by approximately 40 percent. Secure long-term liquid nitrogen supply contracts before CAR-T manufacturing expansion intensifies competition for cryogenic logistics capacity. For New Entrants and Emerging Players: AABB-accreditation fast-tracks facility commissioning in India's underpenetrated Maharashtra and Karnataka markets where CDSCO oversight remains less prescriptive than FDA frameworks. Target mobile collection partnerships with independent midwife practices in Netherlands-style distributed logistics models. Bundle storage with prenatal genetic screening packages through fertility clinic networks. For Investors and Strategic Acquirers: Multi-provincial license holders with validated cryopreservation protocols and automated processing infrastructure represent the most defensible acquisition archetype. Long-term viability hinges on regenerative medicine pipeline maturation and allogeneic cell therapy contract manufacturing expansion. Watch FDA Section 351 licensure enforcement intensity as inflection indicator for competitive field compression.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Deployment | Closed-system centrifugation platforms displace manual density-gradient methods in EMA-supervised European facilities. |
| Renewable-Powered Facility Expansion | NMPA dual carbon goals redirect Jiangsu and Zhejiang investments toward compliant biorepository zones. |
| Direct-to-Consumer Channel Development | Telehealth enrollment platforms concentrate marketing spend toward digital patient education before third-trimester appointments. |
| Long-Term Liquid Nitrogen Contracting | CAR-T manufacturing competition for cryogenic logistics capacity prompts supply security investments. |
| Regenerative Medicine Pipeline Partnership | Duke University and Sungkyunkwan University clinical programs accelerate speculative storage demand. |
Research Methodology
Operator-level perspectives from cord blood bank laboratory directors, maternity ward procurement managers, transplant center physicians, and cellular therapy manufacturing executives anchored the qualitative base. Primary interviews triangulated against secondary validation through FDA Section 351 licensure records, AABB and FACT-NetCord accreditation databases, CDSCO cellular therapy filings, and NMPA biorepository energy compliance disclosures. Bottom-up enrollment data from private storage contracts combined with top-down health system grant allocations across public banking operations.
Sensitivity analysis tested forecast robustness across birth-rate scenarios, regulatory enforcement intensity variations, and regenerative medicine pipeline progression rates. Segmentation dimensions modeled encompass service type, application pathway, end-user category, and delivery model complexity. CAGRs derived from installed cryogenic capacity expansion trajectories, processing automation penetration curves, and cross-border sample transport volume growth. Industry-specific inputs include liquid nitrogen supply contract pricing trends and FACT-NetCord certification timeline distributions.
Underlying assumptions cover sustained FDA licensure enforcement, stable NMPA dual carbon policy implementation, and regenerative medicine clinical trial advancement, with deviation risk concentrated in public banking subsidy austerity cycles and CAR-T manufacturing capacity competition for cryogenic infrastructure. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
India Senior Living Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Patient Throughput and Capacity Management Market