
 Hepatitis C Market | 2026-2036
Hepatitis C Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis C Market Outlook
Indian pharmaceutical manufacturers is broadening their active pharmaceutical ingredient output for sofosbuvir and velpatasvir. Gilead Sciences Inc. leverages its patent estate to sustain premium positioning across developed markets. AbbVie Inc. competes through glecaprevir-pibrentasvir combination therapies in reimbursed channels. Merck & Co., Inc. anchors its portfolio in government tenders where price sensitivity dominates procurement decisions.
Hepatitis C comprises a blood-borne viral infection caused by the HCV RNA virus, with genotypes 1 through 6 requiring nucleotide polymerase inhibitors, NS5A replication complex inhibitors, or NS3/4A protease inhibitors for sustained virologic response. Direct-acting antivirals now dominate prescription volume due to their ability to achieve cure rates exceeding ninety-five percent after eight to twelve weeks of oral administration. Specialty pharmacies capture disproportionate margin pools as benefit managers steer high-cost therapies through limited distribution networks. Hospitals retain structural importance in acute hepatitis C cases requiring interferon-based rescue protocols.
FDA approval pathways and EMA conditional marketing authorizations shape product entry sequencing across North American and European markets. WHO prequalification standards determine eligibility for Global Fund and government procurement in low-income countries. Stakeholders must monitor patent cliff dynamics and compulsory licensing pressures as generic manufacturers in India and Egypt scale production capacity.
Market Dynamics
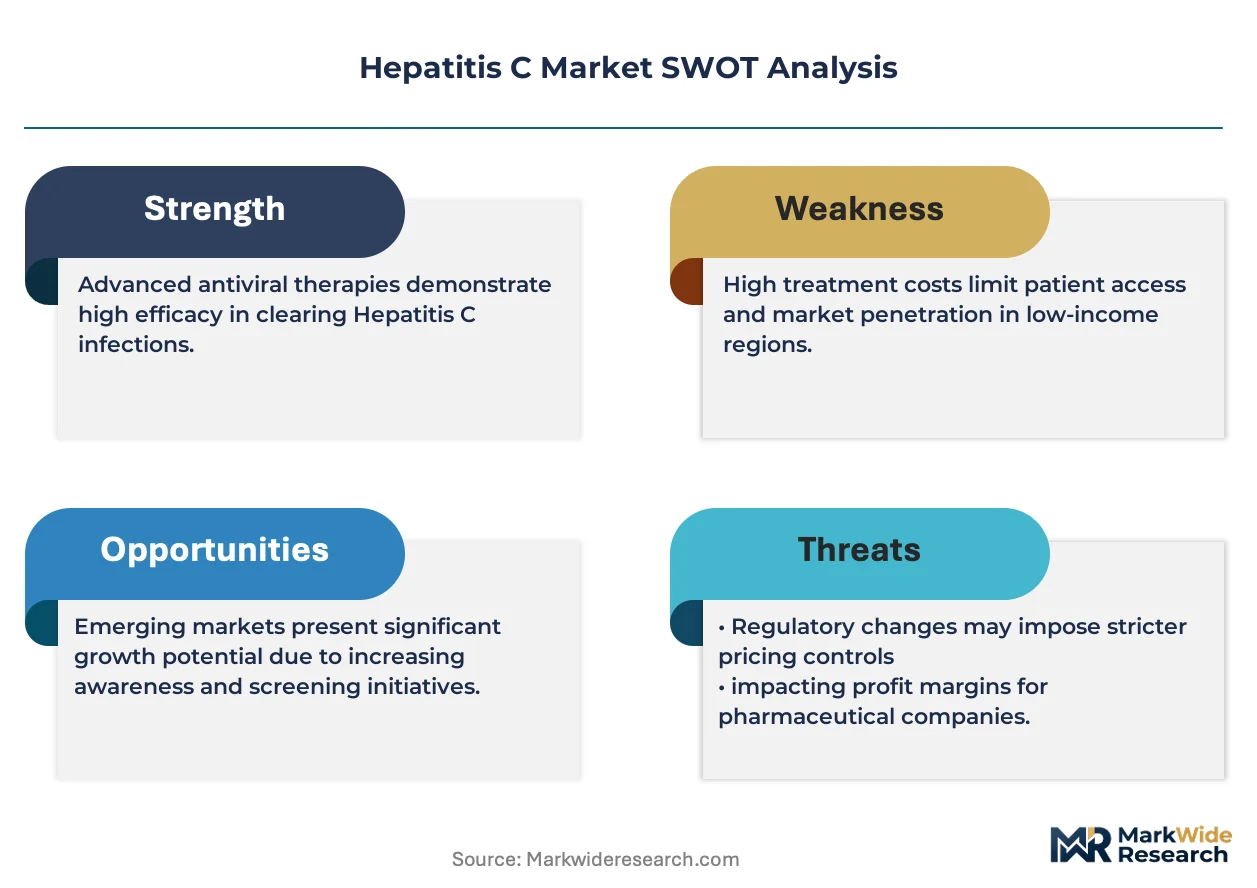
The Hepatitis C Market is absorbing the structural tension between patent-protected originator drugs and scaled generic production, with procurement patterns bifurcating between premium reimbursed channels and tender-driven volume markets.
Growth Catalysts
- WHO Elimination Targets:The WHO's 2030 hepatitis C elimination goals are compelling national governments to expand screening infrastructure and treatment access programs.
- Direct-Acting Antiviral Efficacy:Oral regimens achieving sustained virologic response above ninety-five percent are displacing interferon-based protocols in clinical guidelines.
- Egypt:Mass treatment campaigns targeting ten million patients have created the world's largest national procurement volume for sofosbuvir-based combinations.
Market Restraints
- API Concentration:Active pharmaceutical ingredient production for key nucleotide polymerase inhibitors concentrates among Indian manufacturers, creating supply vulnerability.
- Patent Estate Barriers:Gilead's composition-of-matter patents block generic entry in the United States, Japan, and Western Europe through 2028.
- Diagnostic Gap:HCV RNA testing infrastructure remains underdeveloped in sub-Saharan African markets, constraining treatment initiation.
Strategic Opportunities
- Micro-Elimination:Targeted interventions in incarcerated populations, people who inject drugs, and HIV-co-infected cohorts offer concentrated patient pools.
- Point-of-Care Diagnostics:Integration of HCV RNA testing with antenatal care and emergency departments is compressing time-to-treatment.
- Compulsory Licensing Pathways:Thailand and Malaysia have issued government-use licenses for sofosbuvir, creating precedent for middle-income market access.
Industry Challenges
- Reinfection Surveillance:Sustained virologic response does not confer sterilizing immunity, requiring costly longitudinal monitoring systems.
- Cold Chain Complexity:Temperature-sensitive direct-acting antivirals demand specialized logistics in tropical climates where disease burden concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis C Market |
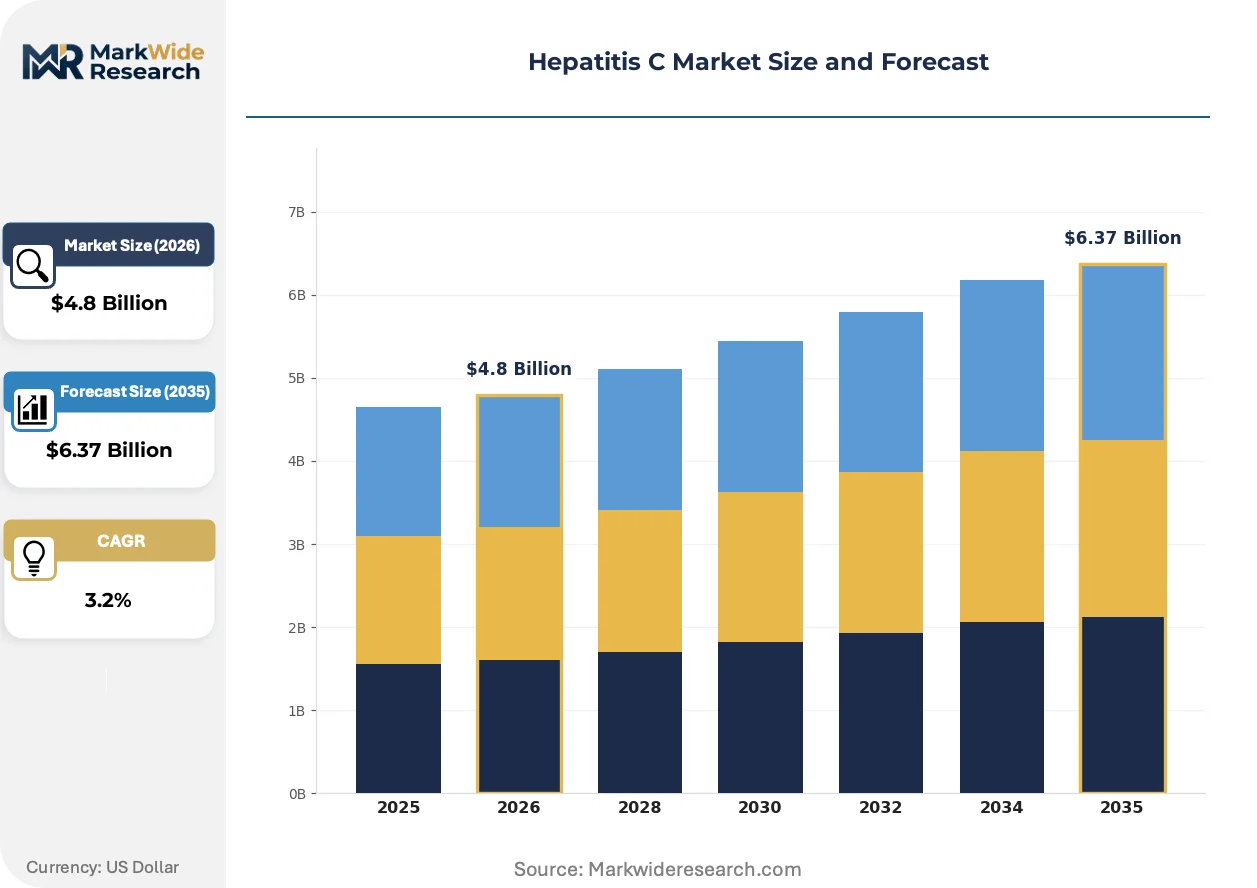
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-Acting Antivirals, Pegylated Interferon, Ribavirin, Combination Therapies End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Administration Route: Oral, Injectable, Intravenous, Topical Therapy Area: Chronic Hepatitis C, Acute Hepatitis C, Hepatitis C Re-infection, Prevention |
| Companies Covered | Gilead Sciences Inc., AbbVie Inc., Merck & Co., Inc., Bristol-Myers Squibb Co., F. Hoffmann-La Roche, Abbott Laboratories Inc., Janssen Pharmaceuticals, Inc., Vertex Pharmaceuticals Incorporated, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis C Market Strategic Shifts
Regulatory convergence around prequalification standards is compressing product entry timelines, while manufacturing technology shifts and procurement model evolution are restructuring competitive positioning across high-income and access markets.
Pan-genotypic fixed-dose combinations are absorbing development pipelines as developers pursue single-tablet regimens effective across HCV genotypes 1 through 6. Hospital formularies in the United States and Western Europe are consolidating procurement around glecaprevir-pibrentasvir and sofosbuvir-velpatasvir, compressing clinical trial investment for genotype-specific alternatives. This concentration is absorbing R&D resources toward hepatitis B and D co-infection applications.
EMA conditional marketing authorizations and FDA priority review vouchers are accelerating orphan-disease pathway adaptations for hepatitis C therapies in pediatric and cirrhotic populations. The industrial consequence is compressed Phase III trial design favoring real-world evidence supplementation. Pediatric formulations and decompensated liver disease indications are most affected, with sponsors responding through adaptive trial protocols.
Specialty pharmacy networks are capturing high-cost therapy distribution as benefit managers consolidate limited distribution contracts. Hospital outpatient departments and independent specialty pharmacies are being displaced by vertically integrated payer-owned channels in the United States. This consolidation is most visible in Medicare Part D and commercial managed care populations, where prior authorization requirements steer patients toward contracted dispensing sites.
Hepatitis C Market Segmentation
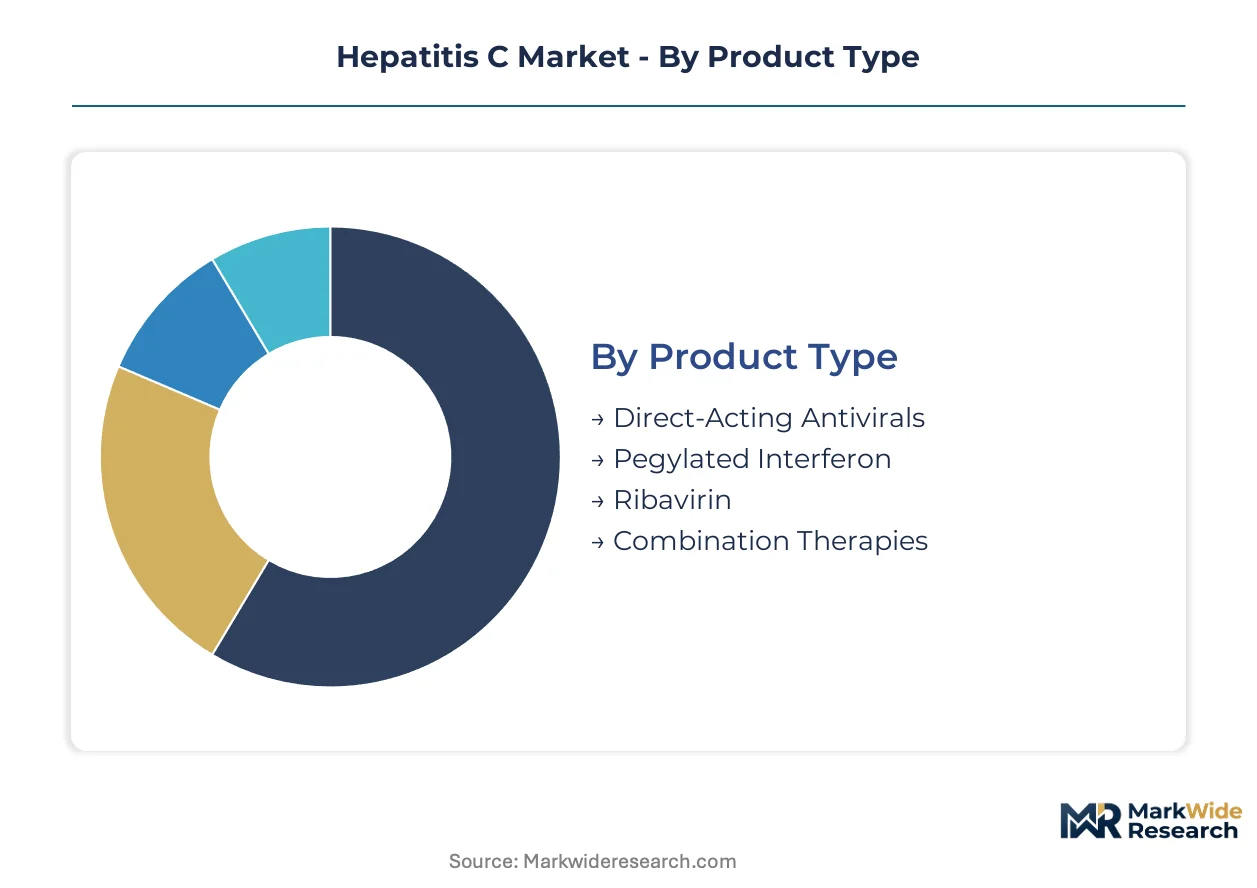
Hepatitis C treatment procurement splits sharply between patent-protected originator markets and tender-driven generic volumes, with each segment demanding distinct regulatory dossiers. Segmentation by product type, end user, administration route, and therapy area reveals how WHO prequalification, FDA approval, and EMA conditional authorizations gate access to divergent patient pools and reimbursement channels.
Product Type:
FDA new drug applications and WHO prequalification certificates determine which formulations reach reimbursed channels versus government tenders.
- Direct-Acting Antivirals:Nucleotide polymerase inhibitors, NS5A replication complex inhibitors, and NS3/4A protease inhibitors achieve sustained virologic response exceeding ninety-five percent. Demand concentrates in United States Medicare Part D and Egypt's mass treatment campaigns, where procurement scales through Gilead's sofosbuvir-velpatasvir and AbbVie's glecaprevir-pibrentasvir.
- Combination Therapies:Fixed-dose pan-genotypic regimens compress treatment duration to eight to twelve weeks. Brazil's SUS program and Thailand's compulsory licensing pathway drive volume, with Indian API manufacturers supplying active pharmaceutical ingredients for government tenders.
- Pegylated Interferon:Retains niche use in interferon-eligible rescue protocols for DAA failures.
- Ribavirin:Adjunct therapy in select genotypes, declining as DAA monotherapy advances.
Leading the category by volume: Combination Therapies. Growing fastest: Direct-Acting Antivirals.
End User:
Cost tier stratification separates acute care reimbursement from outpatient pharmacy dispensing, with prior authorization requirements steering patient flows.
- Specialty Pharmacies:Vertically integrated payer-owned channels capture Medicare Part D and commercial managed care populations through limited distribution contracts. CVS Caremark and Express Scripts steer high-cost DAA dispensing away from independent pharmacies.
- Hospitals:Acute hepatitis C cases requiring decompensated cirrhosis management retain structural importance. United States hospital outpatient departments and Egypt's national treatment centers anchor procurement for interferon-based rescue protocols.
- Clinics:Federally qualified health centers and prison health services target micro-elimination cohorts.
- Home Care:Oral DAA regimens enable self-administration, expanding through Brazil's community health worker programs.
Margin concentration sits with Specialty Pharmacies. Volume expansion is steepest in Clinics serving incarcerated and people-who-inject-drugs populations.
Administration Route:
Patient compliance and cold chain logistics differentiate oral tablet uptake from injectable requirements in tropical climates.
- Oral:Once-daily fixed-dose tablets dominate prescription volume across all genotypes. United States and Western European formularies have consolidated procurement exclusively around oral DAAs.
- Injectable:Pegylated interferon retains residual demand in treatment-experienced patients with DAA resistance.
- Intravenous:Limited to hospitalized acute liver failure cases requiring rescue therapy.
- Topical:No approved HCV indication; research-stage delivery systems only.
Oral administration commands nearly all commercial investment. Injectable routes persist solely in salvage indications.
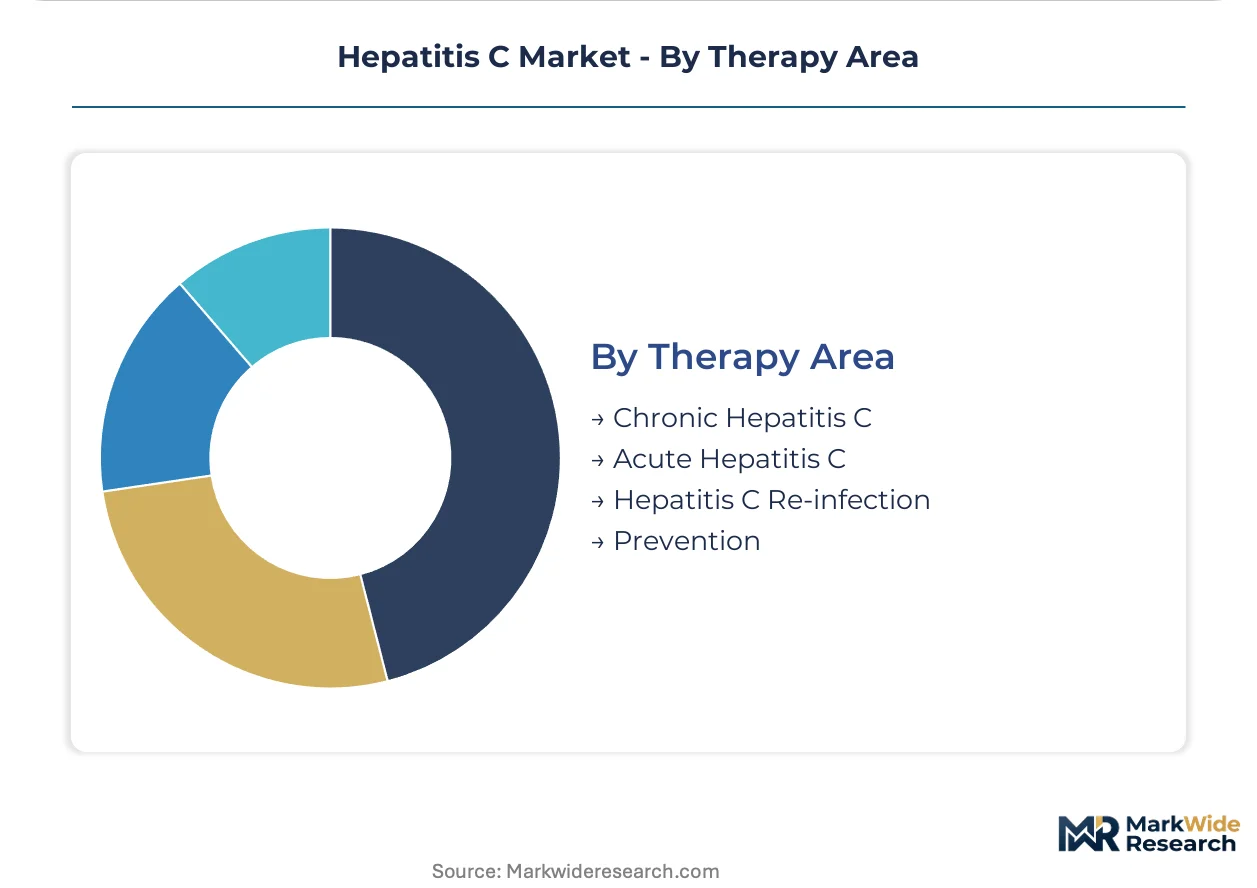
Therapy Area:
Maturity gradients separate established chronic treatment protocols from emerging reinfection surveillance and prevention modalities.
- Chronic Hepatitis C:Established eight-to-twelve-week DAA protocols absorb the overwhelming majority of procurement spend. Egypt's ten-million-patient campaign and Brazil's SUS expansion anchor global volume.
- Acute Hepatitis C:Point-of-care RNA testing integration with emergency departments and antenatal care is compressing time-to-treatment initiation.
- Hepatitis C Re-infection:Sustained virologic response absence of sterilizing immunity creates longitudinal monitoring demand among people who inject drugs and men who have sex with men.
- Prevention:Pre-exposure prophylaxis and vaccine development pipelines remain preclinical, with no approved products.
Chronic Hepatitis C generates current revenue. Re-infection surveillance represents the steepest expansion trajectory as elimination programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in Hyderabad and Ahmedabad supply nucleotide polymerase inhibitors to treatment programs worldwide. National procurement strategies diverge sharply between patent-protected markets and tender-driven volume channels.
United States
Medicare Part D and commercial managed care plans drive direct-acting antiviral demand through specialty pharmacy networks. FDA approval pathways gate access to reimbursed channels, with priority review vouchers accelerating pediatric and cirrhotic indications. Boston and San Francisco biotech clusters anchor clinical trial infrastructure for next-generation combination therapies.
Egypt
The world's largest national hepatitis C treatment campaign targets sustained virologic response across ten million patients. Government tenders for sofosbuvir-based combinations operate through centralized procurement by the country's national pharmaceutical regulator. Cairo and Giza treatment centers anchor mass screening and dispensing infrastructure.
Brazil
The SUS universal health system expansion drives pan-genotypic fixed-dose procurement through federal and state-level tenders. ANVISA regulatory standards determine eligibility for domestic manufacturing partnerships. São Paulo and Rio de Janeiro hospital networks anchor specialty pharmacy distribution for high-cost oral regimens.
Germany
EMA conditional marketing authorizations shape product entry sequencing for pan-genotypic combinations in reimbursed outpatient channels. The country's national pharmaceutical regulator enforces pharmacovigilance requirements for direct-acting antiviral dispensing. Berlin and Munich hospital outpatient departments retain structural importance in acute case management.
India
CDSCO manufacturing licenses and WHO prequalification standards determine API export eligibility for government tenders in low-income markets. Hyderabad and Ahmedabad production clusters scale output for sofosbuvir and velpatasvir active pharmaceutical ingredients. Maharashtra-based manufacturers supply compulsory licensing pathways in Thailand and Malaysia.
Hepatitis C Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biosimilar and compulsory licensing pathways in middle-income markets. The hepatitis C market structure concentrates around three archetypes: patent-protected originators defending premium positioning, Indian API manufacturers capturing tender volumes, and vertically integrated specialty pharmacy networks controlling distribution. Competitive moves center on M&A for pipeline assets and strategic partnerships for geographic expansion into WHO prequalification channels.
Within the originator tier, Gilead Sciences Inc. and AbbVie Inc. exemplify patent-estate defense strategies across developed markets. Merck & Co., Inc. occupies a position anchored in government tender participation where price sensitivity dominates procurement decisions. These three entities represent distinct competitive archetypes: premium positioning through intellectual property, pan-genotypic combination therapy leadership, and volume-scale participation in emerging market access programs.
| Leading Market Players |
|---|
| Gilead Sciences Inc. |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Co. |
| F. Hoffmann-La Roche |
| Abbott Laboratories Inc. |
| Janssen Pharmaceuticals, Inc. |
| Vertex Pharmaceuticals Incorporated |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Captive API production in Hyderabad and Ahmedabad anchors both supply security and pricing power for Indian manufacturers serving tender-driven markets. This backward integration into nucleotide polymerase inhibitor synthesis enables aggressive positioning in Egypt's mass treatment campaigns while originators defend premium tiers through patent-protected sofosbuvir-velpatasvir formulations in reimbursed channels.
Pricing Analysis
Warranty and service bundling separates originator from generic tiers, with Gilead and AbbVie packaging adherence monitoring and resistance testing into reimbursed pricing while unbundled tenders from Indian API manufacturers compete purely on tablet cost. Three-tier pricing structure across originator, licensed generic, and compulsory-licensed supply governs procurement, with differentiation driven by FDA approval status and WHO prequalification tier. Pricing pressure stems from Egyptian and Brazilian government tenders consolidating volume around lowest-compliant bids. Price-sensitive government procurement managers in middle-income markets drive commoditization, while Medicare Part D formularies retain lowest sensitivity due to prior authorization gatekeeping.
Supply Chain Analysis
Returns and expiry management flows concentrate in specialty pharmacy networks handling high-cost DAA inventories with temperature-controlled reverse logistics. Active pharmaceutical ingredient manufacturing concentrates in India, China, and Egypt, with nucleoside precursor synthesis drawing from Chinese chemical intermediate suppliers. Cold chain complexity for direct-acting antivirals creates single-source vulnerability in tropical distribution corridors. Distribution runs through vertically integrated payer-owned specialty pharmacies in the United States, while government central medical stores anchor tender fulfillment in Egypt and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hepatitis C market is becoming a vertical-integration race, with manufacturers pursuing backward control over API synthesis to escape margin compression in tender-driven procurement. Captive production of sofosbuvir intermediates represents the decisive lever separating profitable from distressed competitors.
For Market Incumbents: Extend patent estate leverage through pediatric formulation exclusivities and decompensated cirrhosis indications while building captive API capacity in India to serve emerging market tenders. Indian generic manufacturers threaten originator volume through WHO prequalification pathways; vertical integration into Hyderabad production clusters defends margin structure. For New Entrants and Emerging Players: Launch via compulsory licensing partnerships in Thailand and Malaysia to access middle-income procurement channels without originator litigation exposure. Micro-elimination programs targeting incarcerated populations and people who inject drugs offer the most penetrable entry points, with community health worker distribution models enabling lowest-cost go-to-market deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmacy network acquisitions and Indian API manufacturing assets with WHO prequalification status. Long-term viability hinges on reinfection surveillance service contracts as elimination programs mature. Watch for Egyptian tender renegotiation signals and Brazilian SUS formulary expansion announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Pan-Genotypic Fixed-Dose Development | Single-tablet regimens spanning HCV genotypes 1-6 consolidate hospital formulary procurement around AbbVie's glecaprevir-pibrentasvir. |
| WHO Prequalification Pathway | Indian manufacturers with CDSCO licenses and WHO certification unlock Global Fund and government tender eligibility across low-income markets. |
| Specialty Pharmacy Network Acquisition | Vertically integrated payer-owned channels capture Medicare Part D dispensing margins through limited distribution contracts. |
| Compulsory Licensing Partnership | Thailand and Malaysia government-use licenses create precedent for middle-income market access without patent litigation. |
| Point-of-Care Diagnostic Integration | HCV RNA testing embedded in emergency departments and antenatal care compresses time-to-treatment initiation. |
Study Parameters
FDA approval databases, EMA conditional marketing authorization records, and WHO prequalification certificates formed the secondary backbone, supplemented by customs trade data on API shipments from Indian export zones. Primary interviews with formulary directors at United States hospital systems, procurement managers at Egypt's national treatment centers, and regulatory affairs leads at Indian API manufacturers validated demand assumptions. Bottom-up patient volume estimates from national elimination programs triangulated against top-down pharmaceutical sales data across the analysis window.
Historical trendline analysis of DAA prescription volumes and tender award patterns informed the projection framework. Segmentation modeling incorporated treatment line, administration route, patient population severity, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted price-volume relationships, with forecast inputs including Egyptian screening campaign enrollment trajectories and Brazilian SUS expansion budgets.
Patent cliff timing, compulsory licensing issuance, and diagnostic infrastructure buildout pace are the dominant revision risks. Forecasts reflect assumptions about sustained virologic response durability and reinfection surveillance program adoption. Practitioners should monitor WHO elimination target revisions and Indian API manufacturing capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Q Fever Market
Infectious Disease
Human Immunodeficiency Virus Type 1 (HIV 1) Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Bronchitis Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Herpes Infection Treatment Market