
 Embedded Automation Computers Market | 2026-2036
Embedded Automation Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Automation Computers Market Intelligence
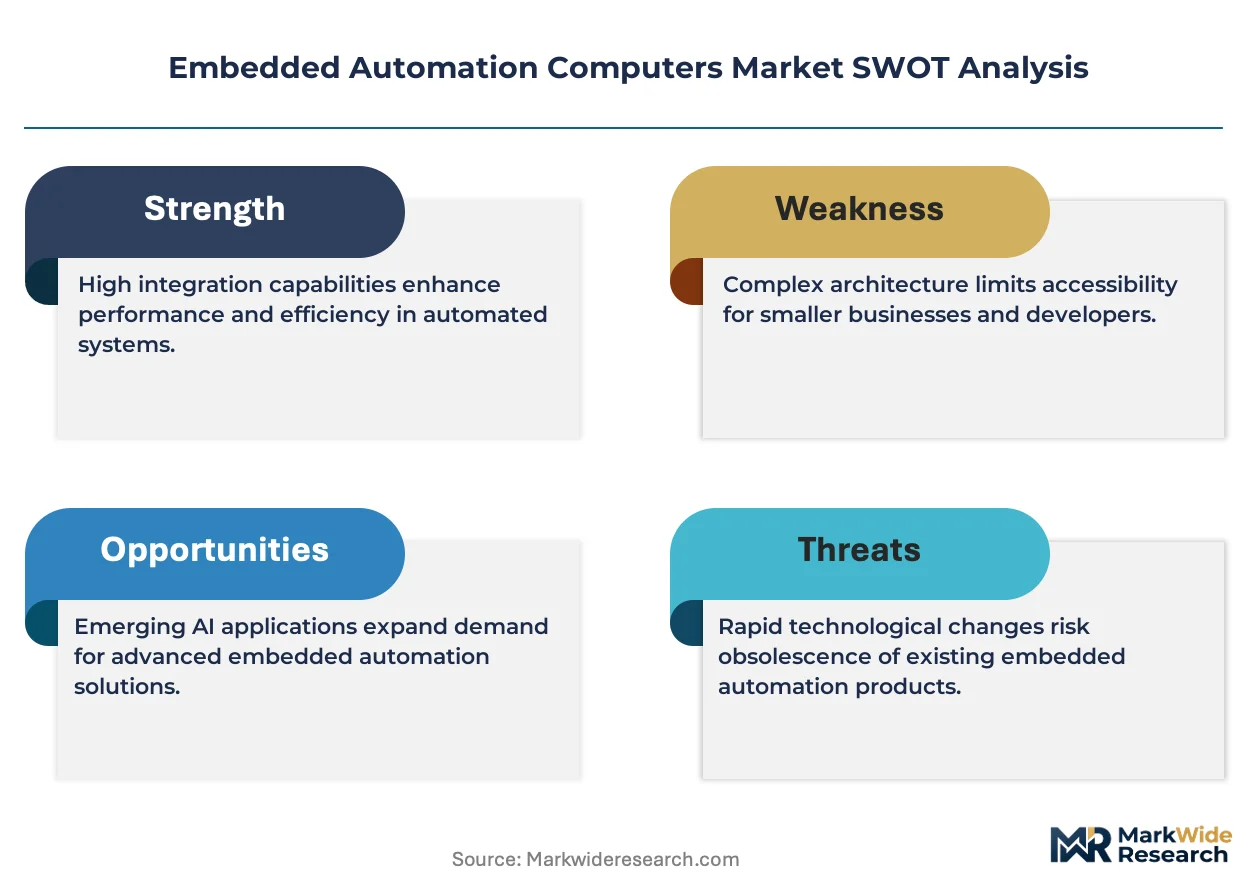
The rise of equipment-as-a-service (EaaS) financing models for industrial automation is narrowing the competitive field to vendors with significant capital access. Siemens AG leverages its extensive financing arm to offer integrated hardware and service packages. Advantech differentiates through its broad portfolio of application-specific hardware platforms. Meanwhile, Beckhoff Automation sustains its market position through PC-based control technology leadership.
Embedded automation computers are specialized, ruggedized computing systems designed for deterministic control and data processing within industrial machinery. These devices often feature fanless designs and extended temperature tolerance to ensure reliability in harsh manufacturing plant environments. While the x86 architecture continues to dominate high-performance process control applications, ARM architecture is rapidly gaining share in robotics and edge devices. Programmable Logic Controllers (PLCs) represent a mature product category, whereas demand for advanced Human Machine Interface (HMI) systems is accelerating.
Compliance with Europe's CE marking and RoHS directives dictates material selection and electromagnetic compatibility for all components. In the United States, product safety certification from bodies like UL is a prerequisite for market access in industrial settings. Vendors must now decide on the optimal balance between powerful on-device edge processing and seamless integration with cloud-based analytics platforms.
Market Dynamics
The primary force shaping the market is the architectural divergence between legacy x86 platforms for high-performance control and energy-efficient ARM designs, which are enabling smaller, more powerful edge devices for factory automation.
Growth Catalysts
- Smart Factory Initiatives:Germany’s Industry 4.0 framework accelerates demand in the automotive and machinery sectors for embedded computers to integrate production lines.
- Robotics in Manufacturing:The proliferation of industrial robots in Chinese factories requires rugged, real-time embedded controllers for motion and vision processing.
- Government Incentives:Policies like the US CHIPS Act stimulate domestic electronics manufacturing, creating demand for automation systems in new fabrication plants.
Market Restraints
- High Integration Cost:The capital expense of retrofitting legacy industrial machinery with modern embedded computers is a significant barrier for many operators.
- Real-Time OS Dependency:Reliance on specialized Real-Time Operating Systems limits software portability and the availability of qualified development talent.
- Component Sourcing:The market's dependence on a few key semiconductor foundries for processors creates supply chain vulnerability and price volatility.
Strategic Opportunities
- Emerging Industrial Hubs:Manufacturing growth in Southeast Asian nations like Vietnam offers greenfield opportunities for automation systems without legacy constraints.
- Edge AI Proliferation:The convergence of AI with embedded hardware enables new predictive maintenance applications, creating demand for specialized processing units.
- 5G in Factories:Integrating 5G wireless into embedded computers allows flexible factory layouts and reliable, low-latency communication for mobile robots.
Industry Challenges
- OT and IT Skill Gap:A persistent shortage of engineers with dual expertise in both operational technology and information technology hinders the integration and secure operation of connected factory systems.
- Legacy System Interoperability:Ensuring seamless data exchange and control between new embedded computers and decades-old PLCs from multiple vendors remains a significant and costly technical hurdle for adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Automation Computers Market |
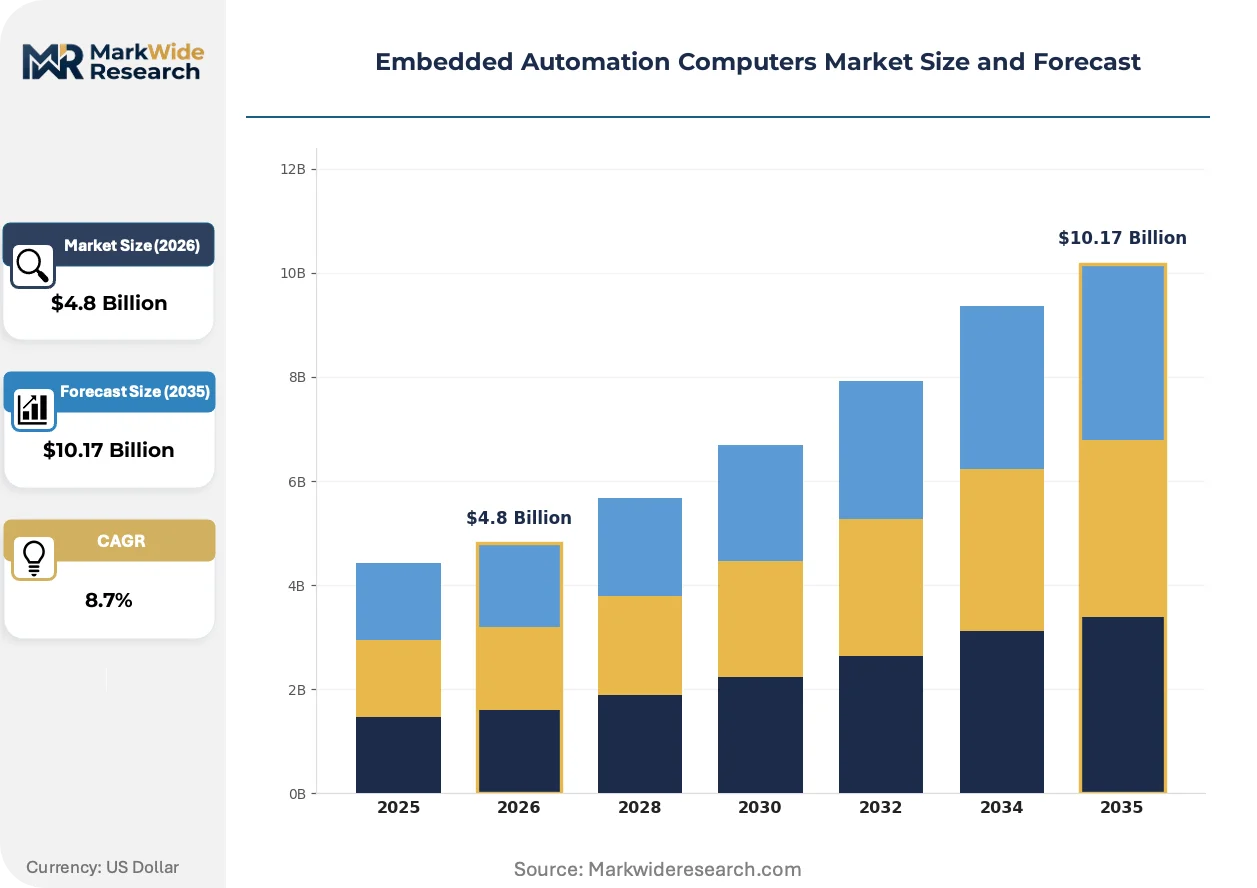
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Human Machine Interface, Motion Controllers, Safety Controllers, Distributed Control Systems Technology: Real-Time Operating Systems, FPGA-Based, ARM Architecture, x86 Architecture, PPC Architecture Application: Process Control, Factory Floor Automation, Robotics, Building Automation, Quality Inspection End User: Manufacturing Plants, Oil & Gas Facilities, Transportation Operators, Telecommunications Providers, Power Generation Stations |
| Companies Covered | Advantech, Axiomtek, Kontron, Beckhoff Automation, ADLINK Technology, AAEON Technology, IEI Integration Corporation, Siemens AG, B&R Industrial Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Automation Computers Market Strategic Shifts & Innovations
The market is defined by a fundamental shift from centralized, supervisory control architectures toward distributed intelligence. This move empowers individual machines and edge devices with greater autonomy and processing capability directly on the factory floor.
System-on-Chip (SoC) designs integrate CPU, GPU, and specialized AI accelerators onto a single piece of silicon. Manufacturers of machine vision systems and autonomous mobile robots are rapidly adopting these integrated platforms. This consolidation of processing functions is collapsing the traditional multi-board hardware architecture, reducing device size, cost, and power consumption for edge applications.
Europe's forthcoming AI Act establishes a risk-based framework for artificial intelligence systems used in industrial settings. The legislation mandates that vendors provide documentation on data governance, system accuracy, and cybersecurity for high-risk applications. Consequently, developers of embedded computers for safety-critical functions must now prioritize building auditable and explainable AI models.
A notable change in acquisition models is the move toward Equipment-as-a-Service (EaaS) contracts for industrial automation. This model disrupts the standard transactional sale of hardware, favoring suppliers who can package computers with ongoing software updates and remote management. The trend is most prominent in Germany’s capital goods sector, where it helps customers transition from capital to operational expenditures.
Embedded Automation Computers Market Segmentation
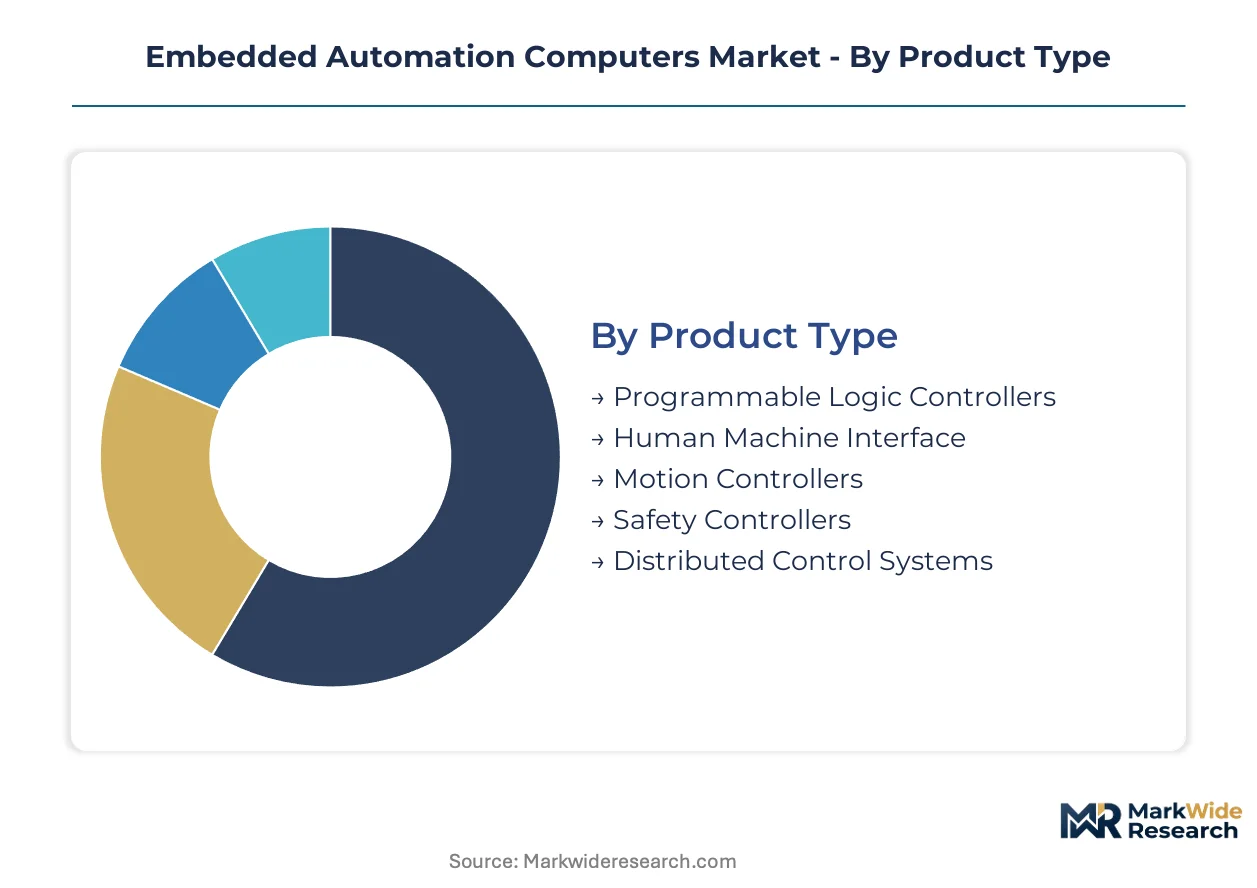
The Embedded Automation Computers Market's segmentation provides a detailed lens into the diverse requirements of industrial operations, highlighting where specific technologies and product types are gaining traction. Understanding these distinctions helps vendors tailor solutions to precise application needs and evolving end-user demands across various sectors. This granular view clarifies the market's structural dynamics and future growth vectors.
Product Type:
Segments within product type exhibit varied refresh cycles, with some requiring frequent upgrades while others maintain longer lifespans.
- Programmable Logic Controllers:These robust, industrial-grade digital computers automate electromechanical processes, offering high reliability and deterministic control. Demand for PLCs remains strong in Germany's automotive manufacturing for managing assembly lines due to their proven stability.
- Human Machine Interface:HMI systems provide graphical user interfaces for operators to monitor and control industrial machinery, improving operational efficiency and reducing human error. The accelerating demand for advanced HMI systems in Chinese factories supports complex robotics and visualization needs.
- Motion Controllers:These specialized devices manage the precise movement of industrial robots and automated machinery.
- Safety Controllers:Dedicated controllers ensure the safe operation of industrial equipment, complying with international safety standards like IEC 61508.
- Distributed Control Systems:DCS manages complex, continuous processes across large industrial plants, offering centralized control with distributed processing.
Programmable Logic Controllers dominate the installed base. Human Machine Interface is where expansion concentrates.
Technology:
Technology segments demonstrate varying levels of supply concentration from specialized vendors, influencing platform availability and innovation pace.
- Real-Time Operating Systems:RTOS provides deterministic timing and low-latency responses essential for critical control applications in industrial automation. Reliance on specialized RTOS limits software portability and the availability of qualified development talent.
- ARM Architecture:Energy-efficient ARM designs enable smaller, more powerful edge devices, rapidly gaining share in robotics and embedded vision systems. This architectural shift from legacy x86 platforms facilitates compact, high-performance computing in factory settings.
- x86 Architecture:This architecture continues to dominate high-performance process control applications requiring extensive computational power.
- FPGA-Based:Field-Programmable Gate Arrays offer reconfigurable hardware for custom logic, ideal for specialized high-speed data processing.
- PPC Architecture:PowerPC architecture finds niche applications in specific industrial and aerospace control systems due to its ruggedness.
Real-Time Operating Systems maintain a stable revenue base. ARM Architecture represents the fastest-growing trajectory.
Application:
Application segments vary significantly in the total volume of embedded computers deployed across diverse industrial settings.
- Factory Floor Automation:This application involves deploying embedded computers for controlling machinery, optimizing production lines, and integrating various manufacturing processes. Smart factory initiatives in Germany accelerate demand for embedded computers to integrate production lines.
- Robotics:Embedded computers provide real-time control, motion planning, and vision processing capabilities for industrial robots in manufacturing environments. The proliferation of industrial robots in Chinese factories requires rugged, real-time embedded controllers.
- Process Control:Embedded systems regulate continuous processes in industries such as chemicals, oil and gas, and pharmaceuticals.
- Building Automation:These systems manage environmental controls, security, and energy efficiency within commercial and industrial buildings.
- Quality Inspection:Embedded computers power machine vision systems for automated defect detection and quality assurance on production lines.
Factory Floor Automation drives the largest volume. Robotics is experiencing the steepest expansion trajectory.
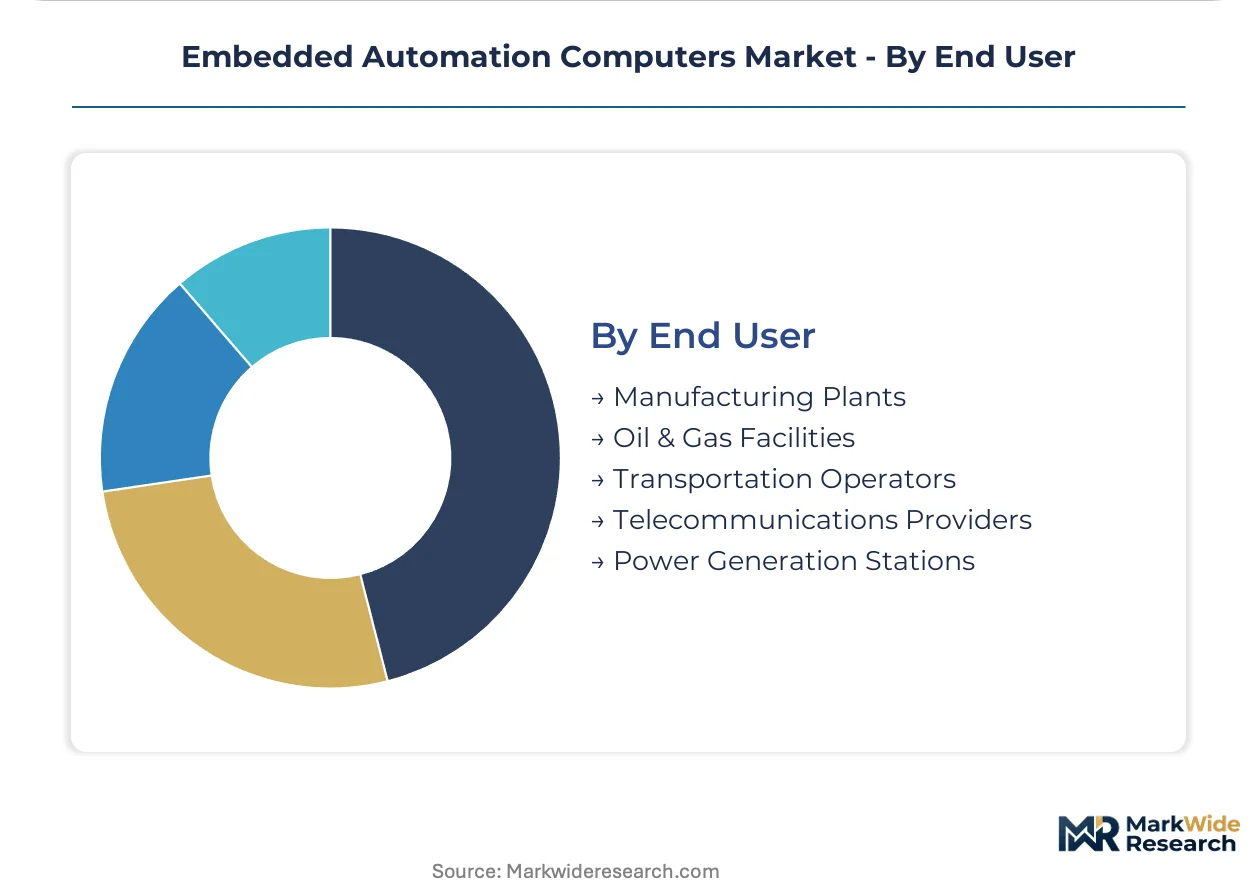
End User:
End-user segments present distinct margin profiles for embedded automation computer vendors, driven by procurement scale and customization needs.
- Manufacturing Plants:These facilities utilize embedded computers for production line automation, quality control, and machinery operation across various industries. Government incentives like the US CHIPS Act stimulate domestic electronics manufacturing, creating demand for automation systems in new fabrication plants.
- Oil & Gas Facilities:Embedded systems are crucial for monitoring and controlling drilling, extraction, and refining processes in harsh and remote environments. Compliance with safety standards in these facilities mandates robust and certified hardware.
- Transportation Operators:Embedded computers manage control systems for rail, maritime, and road infrastructure.
- Telecommunications Providers:These entities deploy embedded systems for network infrastructure and data center automation.
- Power Generation Stations:Embedded computers oversee critical control functions in nuclear, thermal, and renewable energy plants.
Manufacturing Plants constitute the largest customer base. Telecommunications Providers are rapidly expanding their adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives significantly influence the regional distribution of embedded automation computer demand. Policies like the US CHIPS Act and Germany’s Industry 4.0 framework drive substantial investments in advanced manufacturing capabilities. These initiatives accelerate the integration of smart factory solutions across diverse industrial sectors.
Germany
Germany’s automotive and machinery sectors generate substantial demand for embedded automation computers. The country's Industry 4.0 framework actively promotes the integration of advanced digital technologies into manufacturing. Key industrial clusters in Bavaria and Baden-Württemberg leverage these systems for sophisticated production line automation.
United States
The United States market sees demand driven by domestic electronics manufacturing and new fabrication plants. The US CHIPS Act provides significant federal funding to stimulate semiconductor production and associated automation. Silicon Valley and other tech hubs in California are integrating embedded systems into next-generation industrial processes.
China
China's industrial robot proliferation fuels strong demand for rugged, real-time embedded controllers. Government policies supporting automation and industrial upgrades foster extensive deployment across manufacturing facilities. The Yangtze River Delta region, a major manufacturing hub, rapidly adopts advanced embedded systems for factory modernization.
Vietnam
Manufacturing growth in Southeast Asian nations like Vietnam offers greenfield opportunities for automation systems. The Vietnamese government actively encourages foreign direct investment in high-tech manufacturing sectors. Industrial parks near Ho Chi Minh City are adopting modern embedded computers without legacy infrastructure constraints.
Embedded Automation Computers Market Key Industry Players
On the supply side, the industry is moderately consolidated, featuring established industrial giants alongside specialized technology providers. Archetypes include diversified automation conglomerates, niche PC-based control specialists, and hardware-agnostic solution integrators. Dominant competitive moves involve strategic partnerships to expand ecosystem reach and continuous portfolio diversification into application-specific hardware.
Among established industrial technology providers, Siemens AG, a Germany-based AG, exemplifies the strategy of offering integrated hardware and service packages, leveraging its extensive financing capabilities. This approach caters to customers seeking comprehensive solutions and predictable operational expenditures. Advantech, a Taiwan-based Co., Ltd., represents a contrasting strategy focused on differentiating through a broad portfolio of application-specific hardware platforms, addressing diverse industrial needs. Beckhoff Automation, a Germany-based GmbH, occupies a position of leadership in PC-based control technology, sustaining its market presence through specialized expertise. These players collectively anchor different segments of the embedded automation market, from broad-spectrum industrial control to highly specialized edge computing.
| Leading Market Players |
|---|
| Advantech |
| Axiomtek |
| Kontron |
| Beckhoff Automation |
| ADLINK Technology |
| AAEON Technology |
| IEI Integration Corporation |
| Siemens AG |
| B&R Industrial Automation |
| Others |
Cost & Logistics Intelligence
Component sourcing concentration within a few key semiconductor foundries directly influences pricing power and margin distribution in the embedded automation computers market. This structural dependency creates supply chain vulnerability.
Pricing Analysis
Certification level, including CE marking and UL product safety, creates the primary spread in embedded automation computer pricing. Pricing stratifies across performance tiers, with high-performance x86 systems commanding premiums over energy-efficient ARM designs. Integrated hardware and service packages, especially those incorporating EaaS models, differentiate offerings from transactional per-unit sales. Pricing softness stems from intense competition among hardware vendors in mature PLC segments, driven by cost-conscious operators. Manufacturing plants show high price sensitivity for large volume orders, while specialized applications tolerate higher costs.
Supply Chain Analysis
Supply chain vulnerability stemming from reliance on a few key semiconductor foundries dominates the embedded automation computer market. Processor manufacturing concentrates heavily in Taiwan and South Korea, drawing from specialized silicon and rare earth elements. Logistics chokepoints and geopolitical tensions pose structural risks to component availability, impacting lead times. Downstream distribution runs through direct sales channels for large industrial customers and value-added resellers for smaller integrators, influencing regional availability and support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded automation computers market is experiencing high-growth disruption, driven by the architectural shift towards energy-efficient ARM designs and the proliferation of Edge AI. This transformation redefines industrial computing capabilities.
For Market Incumbents: Build ecosystem resilience through strategic partnerships to counter competitive narrowing from EaaS models. Diversify hardware portfolios supporting both x86 and ARM architectures, mitigating architectural divergence risks. Invest in talent development to bridge the OT and IT skill gap, enabling seamless connected factory integration. Siemens AG leverages its financing arm to offer integrated hardware and service packages.
For New Entrants and Emerging Players: Greenfield opportunities in Southeast Asian nations like Vietnam represent the most penetrable entry point. Focus on application-specific hardware platforms for robotics and Edge AI, leveraging demand for specialized processing units. Offer flexible EaaS models to reduce initial capital expenditure for operators, providing an attractive go-to-market angle. Address legacy system interoperability challenges with modern, adaptable solutions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized technology providers focused on niche PC-based control or application-specific hardware. Long-term viability for this market spans a 5-10 year window, driven by continuous industrial automation upgrades. Target companies with strong intellectual property in Edge AI processing or 5G integration capabilities. The signal to watch is accelerating ARM architecture adoption in robotics and edge devices across manufacturing hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch ARM-based Edge AI Processors | Addresses demand for energy-efficient, powerful embedded computing in robotics and vision systems. |
| Form OT/IT Integration Partnerships | Bridges the critical skill gap, facilitating secure and seamless connected factory deployments. |
| Expand into Southeast Asian Markets | Captures greenfield opportunities in emerging industrial hubs without legacy infrastructure constraints. |
| Invest in Real-Time OS Development | Enhances deterministic control capabilities, crucial for high-performance industrial automation applications. |
| Develop Equipment-as-a-Service Models | Attracts customers by converting capital expenditures into operational expenses, narrowing the competitive field. |
Research Approach
Operator-level perspectives from plant engineers, automation specialists, and IT directors anchored the qualitative base for this analysis. Primary interviews with these industrial stakeholders were triangulated with secondary validation from company reports, regulatory filings like CE marking documentation, and industry association publications. A comprehensive bottom-up and top-down approach ensured robust data integrity.
Multiple scenario-based projections were developed, bracketing potential market outcomes across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user, alongside regional adoption patterns. Compound Annual Growth Rates were derived from historical trends and projected technological advancements. Key forecast inputs included industrial robot deployment rates and smart factory investment levels.
Macroeconomic conditions sit as an overlay; deviation in global manufacturing output or capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions regarding technological adoption and regulatory stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Intralogistics Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market