
 Internet of Things Enabled Industrial Wearables Market | 2026-2036
Internet of Things Enabled Industrial Wearables Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things Enabled Industrial Wearables Market Foresight
ISO 45001 occupational health and safety certification is redrawing competitive boundaries for industrial wearable vendors. Honeywell International Inc leverages its integrated safety platform to anchor positions across hazardous environment deployments. Bosch sustains technology leadership through precision sensor miniaturization for smart glove interfaces. Siemens AG dominates digital twin integration, linking wearable telemetry directly into plant control architectures.
Internet of Things enabled industrial wearables comprise sensor-embedded garments and accessories that stream biometric, positional, and environmental data via low-latency wireless protocols to edge or cloud analytics platforms. These devices typically integrate accelerometers, gyroscopes, and thermal sensors within IP-rated housings to withstand temperatures exceeding 60°C and particulate exposure in heavy industrial settings. Smart helmets currently lead product type adoption as facilities prioritize real-time location tracking and collision avoidance, while exoskeletons represent the fastest-expanding category where ergonomic injury prevention drives procurement decisions. Bluetooth and RFID together occupy the dominant technology share due to proven interoperability with existing plant infrastructure, though Wi-Fi segments capture margin pools in high-bandwidth video streaming applications such as wearable camera deployments.
OSHA mandates in the United States, EU machinery directives under CE marking requirements, and ISO 45001 frameworks collectively shape product certification timelines and channel access across major economies. Germany's Federal Institute for Occupational Safety and Health (BAuA) and Japan's Ministry of Economy, Trade and Industry (METI) impose additional testing protocols that filter out uncertified entrants. Stakeholders must monitor evolving cybersecurity standards for connected worker ecosystems as regulatory bodies integrate data protection requirements into industrial safety frameworks.
Market Dynamics
Connected worker ecosystems are restructuring procurement priorities as plant operators demand unified safety platforms rather than point-solution hardware. This consolidation pressure favors vendors with integrated sensor-to-cloud architectures over standalone device manufacturers.
Growth Catalysts
- OSHA workplace safety mandates:United States facilities face intensified inspection protocols for ergonomic injury prevention, accelerating exoskeleton deployments in automotive assembly plants.
- Smart helmet networks:German automotive and chemical producers pilot real-time location tracking systems at scale, validating collision-avoidance ROI in high-density manufacturing environments.
- Bluetooth and RFID interoperability:These wireless protocols reduce integration friction with legacy plant infrastructure, lowering deployment barriers for mid-sized manufacturing operations.
Market Restraints
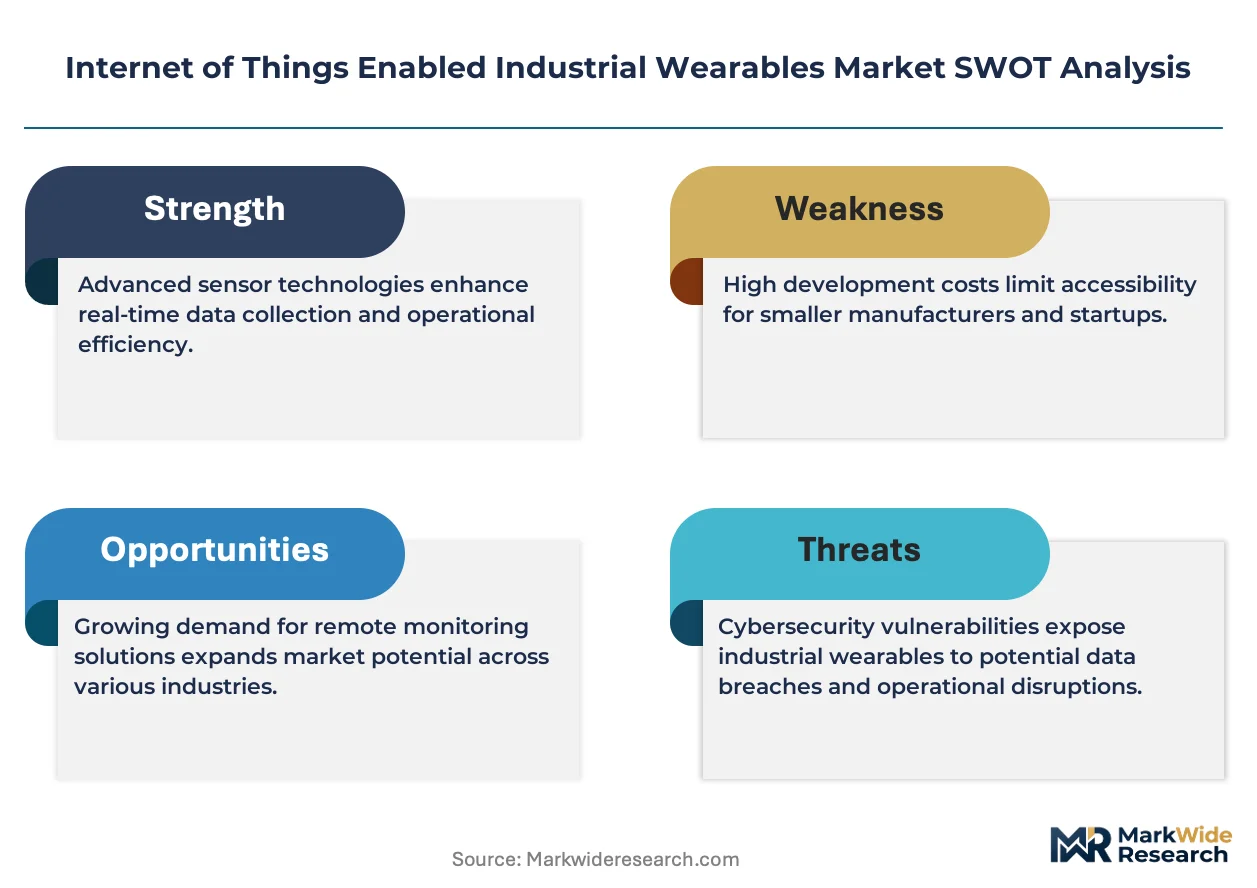
- Precision sensor supply concentration:Miniaturized MEMS accelerometer and gyroscope production clusters in East Asian foundries create single-source vulnerability for European wearable vendors.
- IP-rated housing material costs:Thermal-resistant polymers and particulate-sealing gaskets face petrochemical feedstock volatility, compressing hardware margins.
- Cybersecurity compliance friction:Evolving data protection requirements within industrial safety frameworks extend certification timelines and channel access delays.
Strategic Opportunities
- Japan's METI connected worker initiatives:Ministry pilot programs subsidize wearable telemetry adoption in precision manufacturing, creating first-mover advantages for platform-integrated vendors.
- Digital twin convergence:Wearable-to-control-architecture data streams enable predictive safety analytics, opening premium service revenue pools beyond hardware sales.
- Direct-to-plant procurement channels:Bypassing traditional industrial distribution, vendors establish embedded engineering teams within major automotive and chemical facilities.
Industry Challenges
- Cross-functional talent scarcity:Industrial IoT deployment requires simultaneous expertise in occupational safety engineering, wireless protocol integration, and cloud analytics architecture.
- ISO 45001 certification complexity:Occupational health and safety management system audits demand extensive documentation of wearable telemetry accuracy and data governance protocols.
- Legacy MES integration:Manufacturing execution systems in mature plants operate on proprietary data formats, requiring costly middleware development for wearable connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things Enabled Industrial Wearables Market |
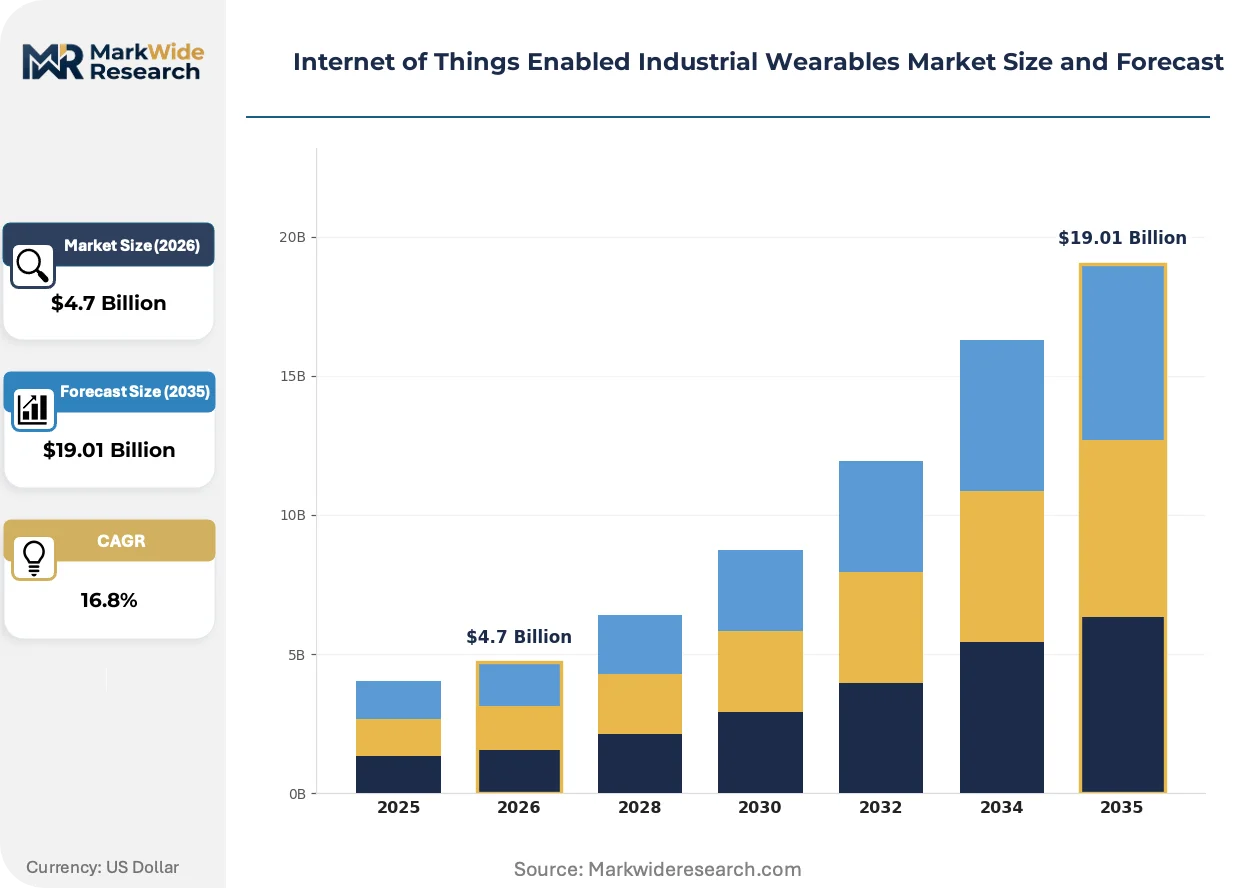
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Gloves, Wearable Cameras, Smart Helmets, Exoskeletons Technology: Bluetooth, RFID, NFC, Wi-Fi End User: Manufacturing, Logistics, Construction, Oil & Gas Application: Safety Management, Performance Monitoring, Training, Asset Tracking |
| Companies Covered | Honeywell International Inc, Bosch, Siemens AG, Intel, PTC, ABB Ltd, Schneider Electric, Samsara, Rockwell Automation Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things Enabled Industrial Wearables Market Shifts & Advancements
Edge-native processing architectures are redistributing computational load away from centralized cloud platforms, enabling sub-100-millisecond safety-critical response times in hazardous environments.
Ultra-wideband positioning chips are supplanting conventional RFID tags for indoor location tracking. Heavy industrial facilities in Germany and the United States adopt these systems for centimeter-grade worker positioning. The technology is compressing insurance premium differentials between connected and non-connected plants by validating real-time collision avoidance performance.
EU machinery directives under CE marking requirements now incorporate cybersecurity clauses for connected worker devices. Manufacturers must demonstrate encrypted data transmission and secure firmware update capabilities before market access. Smart helmet deployments face the steepest compliance burden due to integrated camera and audio streaming functions.
Buyer committees now mandate platform interoperability before purchase approval. Automotive assemblers in Bavaria and chemical processors along the US Gulf Coast reject vendor-locked ecosystems, instead requiring open API access for integration with existing plant control software. This specification shift disadvantages point-solution hardware vendors lacking software development resources.
Internet of Things Enabled Industrial Wearables Market Segmentation
Segmentation in the Internet of Things enabled industrial wearables market reveals how procurement priorities diverge across hardware form factors, wireless protocols, and operational use cases. Understanding these divisions exposes where vendors command pricing power and where standardization pressures erode margins.
Product Type:
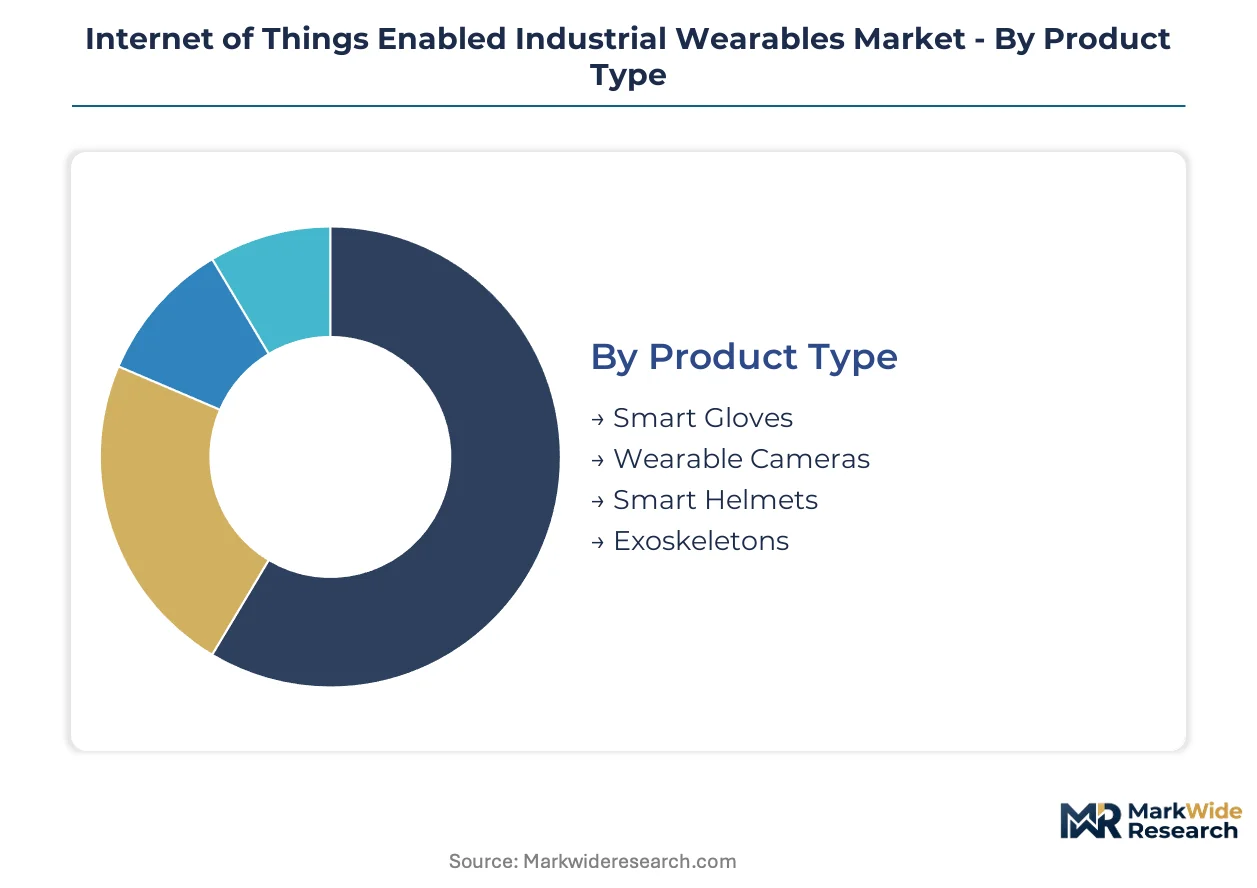
Premium margin pools concentrate in exoskeleton deployments where ergonomic injury prevention justifies six-figure unit investments, while smart helmet networks compete on volume scale with compressed hardware margins.
- Smart Helmets:Integrated headgear combines real-time location tracking, collision avoidance sensors, and environmental monitoring within IP-rated housings. German automotive producers in Bavaria deploy these at scale to validate insurance premium reductions through documented safety performance.
- Exoskeletons:Powered and passive mechanical frames reduce musculoskeletal strain during repetitive lifting and overhead assembly tasks. United States automotive plants facing intensified OSHA inspection protocols represent the fastest-expanding procurement channel for these systems.
- Smart Gloves:Precision sensor miniaturization enables haptic feedback and gesture recognition for quality control workflows in precision manufacturing environments.
- Wearable Cameras:Body-mounted video streaming devices support remote expert guidance and incident documentation in hazardous environment inspections.
The dominant share belongs to smart helmets, while exoskeletons are closing the gap fastest.
Technology:
Protocol selection directly determines integration costs with legacy plant infrastructure and shapes ongoing maintenance expenditure profiles.
- Bluetooth:Low-energy wireless standard dominates mid-sized manufacturing deployments through proven interoperability with existing sensor networks and minimal IT infrastructure demands.
- RFID:Passive and active radio-frequency identification tags anchor indoor positioning systems where battery-free operation and centimeter-grade accuracy justify infrastructure investment. Heavy industrial facilities in Germany and the United States adopt these for worker collision avoidance validation.
- Wi-Fi:High-bandwidth protocol captures premium positioning in video streaming applications including wearable camera deployments requiring real-time remote expert consultation.
- NFC:Near-field communication enables secure device authentication and localized data exchange in access-controlled hazardous zones.
Bluetooth and RFID together command the largest installed base, though Wi-Fi is expanding most quickly in high-bandwidth segments.
End User:
Industry-specific regulatory exposure and injury cost profiles create divergent willingness-to-pay thresholds across vertical markets.
- Manufacturing:Automotive and chemical production facilities drive bulk procurement of connected worker ecosystems, with German producers piloting smart helmet networks and United States plants accelerating exoskeleton adoption under OSHA ergonomic mandates.
- Construction:Project-based procurement patterns and fragmented contractor structures complicate platform standardization, though fall detection and lone worker monitoring applications show concentrated demand.
- Oil & Gas:Hazardous environment certifications and explosion-proof housing requirements sustain premium pricing for specialized deployments in upstream and downstream operations.
- Logistics:Warehouse automation convergence drives demand for wearable scanning and voice-picking interfaces, with integration pressure from warehouse management systems shaping vendor selection.
Manufacturing holds the dominant procurement volume, while oil and gas sustains the highest per-unit pricing.
Application:
Use case maturity determines whether buyers seek point-solution hardware or integrated platform subscriptions.
- Safety Management:Real-time hazard detection, emergency response coordination, and compliance documentation represent the most mature application category with established ROI measurement frameworks.
- Performance Monitoring:Biometric and positional telemetry enable workload optimization and fatigue prediction, with digital twin integration opening recurring service revenue streams for platform-integrated vendors.
- Asset Tracking:Tool and equipment location services reduce search time and inventory loss in large-scale industrial facilities, typically deploying as add-on modules to broader connected worker platforms.
- Training:Augmented reality overlays and motion-capture feedback accelerate skill transfer for complex assembly and maintenance procedures, though adoption remains concentrated in high-turnover workforce environments.
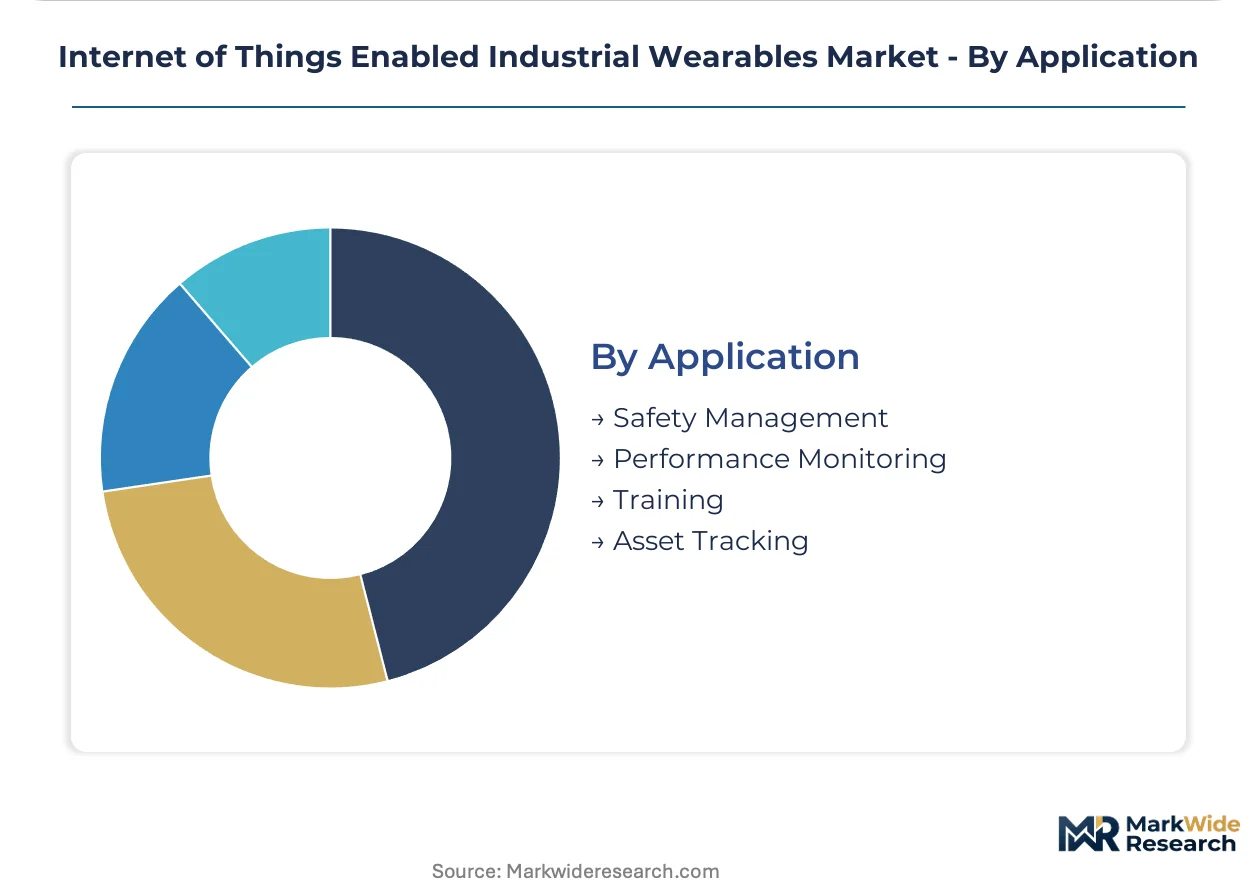
Safety management retains the largest deployment base, while performance monitoring is gaining share fastest through predictive analytics differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor's dense fiber-optic backbone underwrites Germany's dominance in connected worker platform deployment, while Japan's METI-funded 5G manufacturing testbeds accelerate wearable telemetry adoption across precision assembly lines.
United States
Automotive assembly plants in Michigan and Ohio drive exoskeleton procurement under intensified OSHA ergonomic inspection protocols. The Department of Labor's workplace safety mandates now require documented injury prevention systems in facilities exceeding 250 employees. Gulf Coast chemical processors in Texas deploy smart helmet networks for real-time gas detection and emergency response coordination.
Germany
Bavarian automotive producers pilot ultra-wideband positioning systems for centimeter-grade worker tracking in high-density manufacturing halls. BAuA certification requirements filter uncertified wearable vendors from federal procurement channels. The Rhine-Ruhr chemical corridor validates insurance premium reductions through documented collision-avoidance performance data.
Japan
Precision electronics manufacturers in the Chubu region adopt wearable telemetry under METI-connected worker subsidy programs. JIS standards for industrial IoT devices mandate encrypted data transmission and secure firmware update capabilities. Nagoya-based automotive suppliers integrate biometric fatigue monitoring into existing quality control workflows.
China
Guangdong Province's electronics assembly clusters deploy Bluetooth-enabled smart gloves for haptic quality inspection at scale. MIIT industrial internet initiatives subsidize edge-native processing architectures in state-owned heavy manufacturing facilities. Shenzhen-based vendors supply IP-rated sensor housings to domestic automotive and chemical producers.
South Korea
Busan-Ulsan shipyards implement wearable camera systems for remote expert guidance in confined-space welding operations. MFDS certification requirements for connected medical-industrial hybrid devices extend product approval timelines. Daegu-Gyeongbuk textile machinery producers pilot gesture-recognition interfaces for maintenance training applications.
Internet of Things Enabled Industrial Wearables Market Competitive Landscape
Listed leaders compete with private specialists across platform integration depth, with publicly traded industrial conglomerates commanding integrated sensor-to-cloud architectures while venture-backed hardware startups capture niche ergonomic applications. Market structure tilts toward consolidation as buyer committees mandate open API interoperability, favoring vendors with software development resources over standalone device manufacturers. Three archetypes dominate: diversified industrial technology conglomerates, precision sensor specialists, and cloud-native connected worker platforms. Competitive dynamics center on strategic partnerships with automotive OEMs and direct-to-plant engineering embedment.
Within the diversified industrial tier, Honeywell International Inc and Siemens AG exemplify platform-integrated positioning, while Bosch represents precision sensor miniaturization leadership. These three anchors demonstrate how geographic clustering—United States, Germany, and Germany respectively—maps to distinct competitive vectors in safety platform deployment, digital twin integration, and component-level innovation.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Bosch |
| Siemens AG |
| Intel |
| PTC |
| ABB Ltd |
| Schneider Electric |
| Samsara |
| Rockwell Automation Inc |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with precision MEMS foundries lock in both component supply and cost visibility for European wearable vendors facing OSHA and EU machinery directive compliance deadlines. These contracts insulate hardware margins from petrochemical feedstock volatility in thermal-resistant polymer sourcing while securing allocation priority during supply crunches.
Pricing Analysis
Certification level (ISO 45001/CE marking/FCC-grade) creates the primary spread between premium and economy tiers in industrial wearable procurement. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and digital twin integration depth. Cost compression in standard-tier exoskeletons is intensifying because automotive assemblers demand open API access without vendor lock-in. Mid-sized manufacturing operations show highest price sensitivity, while oil and gas facilities accept premium positioning for hazardous environment certifications.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for German and United States vendors sourcing miniaturized sensor components. Production clusters in Taiwan, South Korea, and Japan anchor precision MEMS accelerometer supply. IP-rated housing production draws from petrochemical feedstocks and thermal-resistant polymer formulations. Single-source vulnerability in East Asian foundries threatens component security. Distribution runs through direct-to-plant engineering embedment and traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from cloud-native connected worker platforms that disintermediate hardware-centric vendors through software-only deployment models.
For Market Incumbents: Fortify platform integration depth by embedding engineering teams within Bavarian automotive and Gulf Coast chemical facilities. Secure backward integration into precision sensor supply through capacity reservation agreements with Taiwanese foundries. ISO 45001 certification investment remains the priority defensive lever against uncertified entrants.
For New Entrants and Emerging Players: BAuA fast-track certification in Germany unlocks federal procurement channels currently filtering out non-compliant vendors. Target construction sector fall detection applications where fragmented contractor structures delay incumbent platform consolidation. METI subsidy-aligned pilot programs in Japan's Chubu region offer lowest competitive density for biometric fatigue monitoring entry.
For Investors and Strategic Acquirers: Cloud-native connected worker platforms with open API architectures represent the highest-conviction acquisition archetype for industrial IoT portfolio construction. Long-term viability hinges on recurring service revenue exceeding hardware sales ratios. Watch for buyer committee mandates of platform interoperability as inflection signal for consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open API architectures satisfy automotive buyer committee mandates in Bavaria and Texas. |
| Backward Integration | Captive MEMS sensor supply mitigates East Asian foundry concentration risk for European vendors. |
| Certification Investment | ISO 45001 and BAuA compliance unlocks federal procurement channels in Germany. |
| Direct-to-Plant Engineering | Embedded teams bypass industrial distribution and capture automotive OEM specification influence. |
| Digital Twin Convergence | Wearable-to-control-architecture data streams enable predictive safety analytics subscriptions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industrial safety certification databases across the analysis window. Primary interviews engaged plant safety managers, automotive OEM procurement leads, industrial IoT platform engineers, and aftermarket service directors. Secondary validation drew from OSHA enforcement records, EU machinery directive compliance registries, SEC 10-K disclosures, and METI subsidy program documentation. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Segmentation dimensions modeled span product type, wireless protocol, end-use vertical, and application use case across the projection horizon. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory mandate acceleration. Industry-specific forecast inputs incorporate OSHA inspection protocol intensification timelines and BAuA certification throughput capacity.
Decision-makers should treat outputs as directional under sustained OSHA enforcement and EU machinery directive cybersecurity clause implementation; material deviation would warrant model refresh. Forecasts reflect assumptions of continued Bluetooth and RFID interoperability dominance and stable petrochemical feedstock pricing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Utility Automation Market
Industrial Automation
Motion Control Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market