
 Vietnam Telecom Towers Market | 2026-2036
Vietnam Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Telecom Towers Market Insights
A chronic shortage of certified tower rigging technicians is unwinding project timelines across Vietnam's buildout cycle. Viettel Construction leverages its in-house workforce academy to sustain deployment velocity in remote provinces. OCK Group Berhad anchors its ASEAN expansion strategy on Vietnamese steel fabrication partnerships. EdgePoint Vietnam differentiates through build-to-suit models that compete on speed-to-permit rather than capital scale.
Vietnam telecom towers are steel or composite structures engineered to heights between 30 and 120 meters, designed to host multiple antenna arrays, transmission equipment, and power systems for wireless signal propagation. Lattice tower configurations dominate terrain-exposed installations where wind load tolerance exceeds 150 kilometers per hour. Monopole designs capture urban infill demand where zoning restricts footprint and visual impact. Stealth tower variants occupy premium positioning near heritage districts and airport approach corridors where aesthetic compliance overrides cost efficiency.
Vietnam's Ministry of Information and Communications and the national technical standards body govern tower spacing, electromagnetic exposure limits, and structural safety codes under evolving ICT master plans. The national regulator's tower-sharing mandate compresses site duplication and redirects capital toward densification. Stakeholders must monitor spectrum auction schedules and provincial land-use decrees to anticipate where build-permit backlogs will tighten or loosen.
Market Dynamics
Vietnam's Ministry of Information and Communications tower-sharing mandate is compressing site duplication and redirecting carrier capital toward densification rather than greenfield construction. This regulatory pivot is restructuring competitive positioning among tower companies and forcing speed-to-permit capabilities.
Growth Catalysts
- 5G Spectrum Allocation:Vietnam's national spectrum auction schedule is accelerating 4G LTE and 5G infrastructure rollouts across underserved provinces in the Mekong Delta and Central Highlands.
- Rural Connectivity Mandates:Revised ICT frameworks require universal service obligations that direct investment toward provinces with persistent coverage gaps.
- Steel Fabrication Partnerships:ASEAN-based manufacturing alliances are reducing import dependency for lattice tower components and monopole structures.
Market Restraints
- Certified Technician Scarcity:Vietnam's tower rigging workforce pipeline cannot match deployment velocity, creating project timeline slippage across remote provinces.
- Land-Use Decree Variability:Provincial permitting inconsistencies generate build-permit backlogs that differ sharply between Ho Chi Minh City and Central Highlands jurisdictions.
- Wind Load Engineering Costs:Terrain-exposed installations requiring 150+ kilometer per hour tolerance specifications inflate structural steel requirements.
Strategic Opportunities
- Edge Computing Convergence:Tower-mounted micro data centers combining 5G infrastructure with localized compute capacity are creating new revenue streams for build-to-suit operators.
- Heritage District Stealth Positioning:Aesthetic-compliant tower variants near airport approach corridors and protected zones command premium tenancy rates.
- Renewable Energy Integration:Solar-hybrid power systems for off-grid tower sites align with national electrification targets in mountainous provinces.
Industry Challenges
- Multi-Tenant Technical Integration:Co-location of competing mobile network operators on shared structures demands RF interference mitigation and power distribution reconfiguration.
- Electromagnetic Exposure Compliance:Field measurement protocols and public disclosure requirements under national technical standards extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Telecom Towers Market |
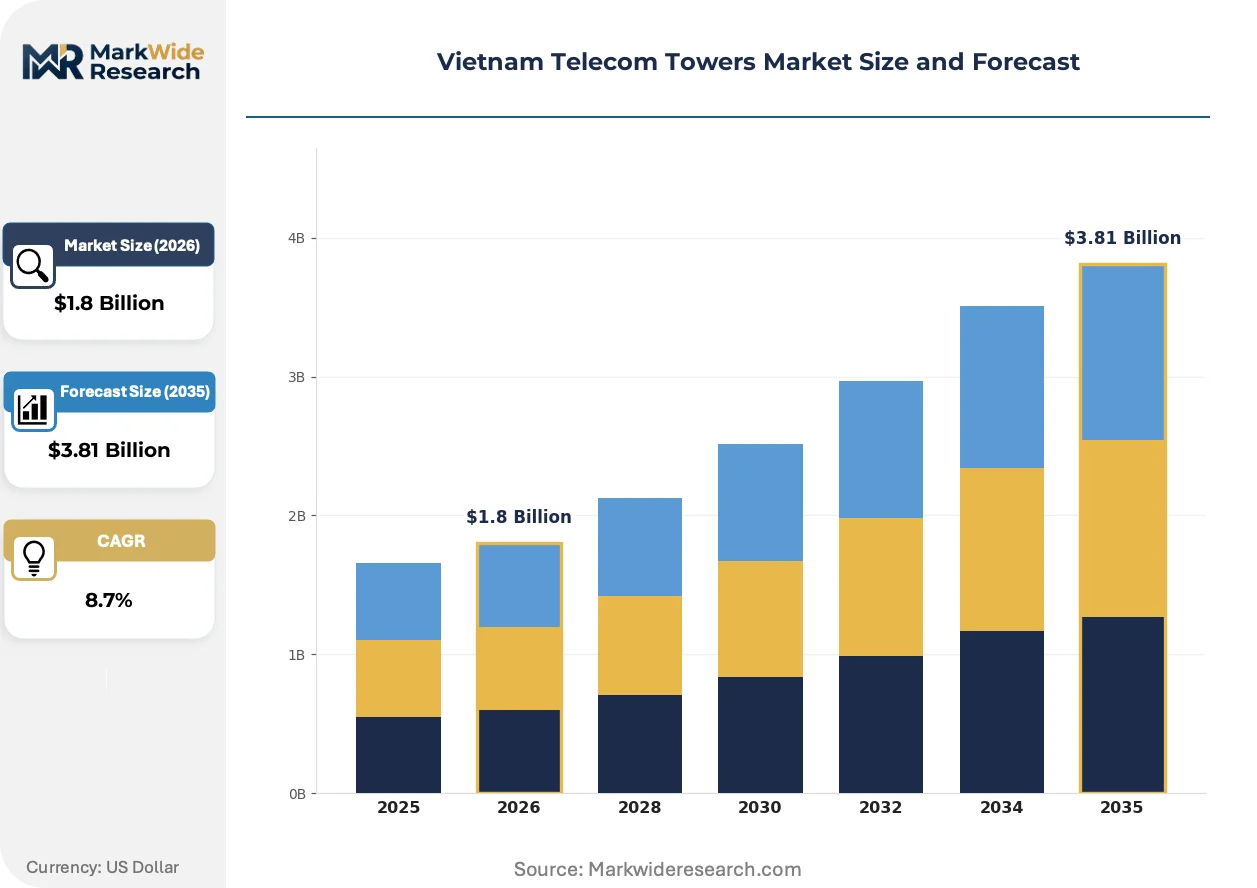
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice Tower, Stealth Tower, Guyed Tower Application: Mobile Networks, Broadcasting, Emergency Services, Rural Connectivity Technology: 4G LTE, 5G, Satellite, Wi-Fi End User: Telecom Operators, ISPs, Government Agencies, Enterprises |
| Companies Covered | Viettel Construction, OCK Group Berhad, VNPT Net Corporation, EdgePoint Vietnam, Vinaphone, MobiFone, Viettel Group, FPT Corp, CMC Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Telecom Towers Market Trends and Innovations
Deployment methodologies across Vietnam are pivoting from capital-heavy asset ownership toward speed-based competition. Tower companies now differentiate through permit acquisition velocity and technical workforce retention rather than balance sheet scale alone.
Composite materials are supplanting traditional galvanized steel in stealth tower applications where aesthetic compliance overrides pure cost efficiency. Heritage district planners and airport authorities are specifying these structures for premium positioning. This material shift is enabling tower companies to secure sites previously unavailable under zoning restrictions.
Vietnam's Ministry of Information and Communications tower-sharing standards are mandating structural modifications for multi-tenant readiness at initial construction. Mobile network operators must now pre-engineer capacity for competitor co-location. The policy is accelerating demand for lattice configurations with expanded loading platforms in rural provinces.
Service contracts are unbundling installation from long-term maintenance and power provision. Mobile network operators are separating tower tenancy from energy opex, creating specialized revenue lines for operators with captive electrical infrastructure. This procurement fragmentation is most visible in the Mekong Delta where grid reliability varies by district.
Vietnam Telecom Towers Market Segmentation
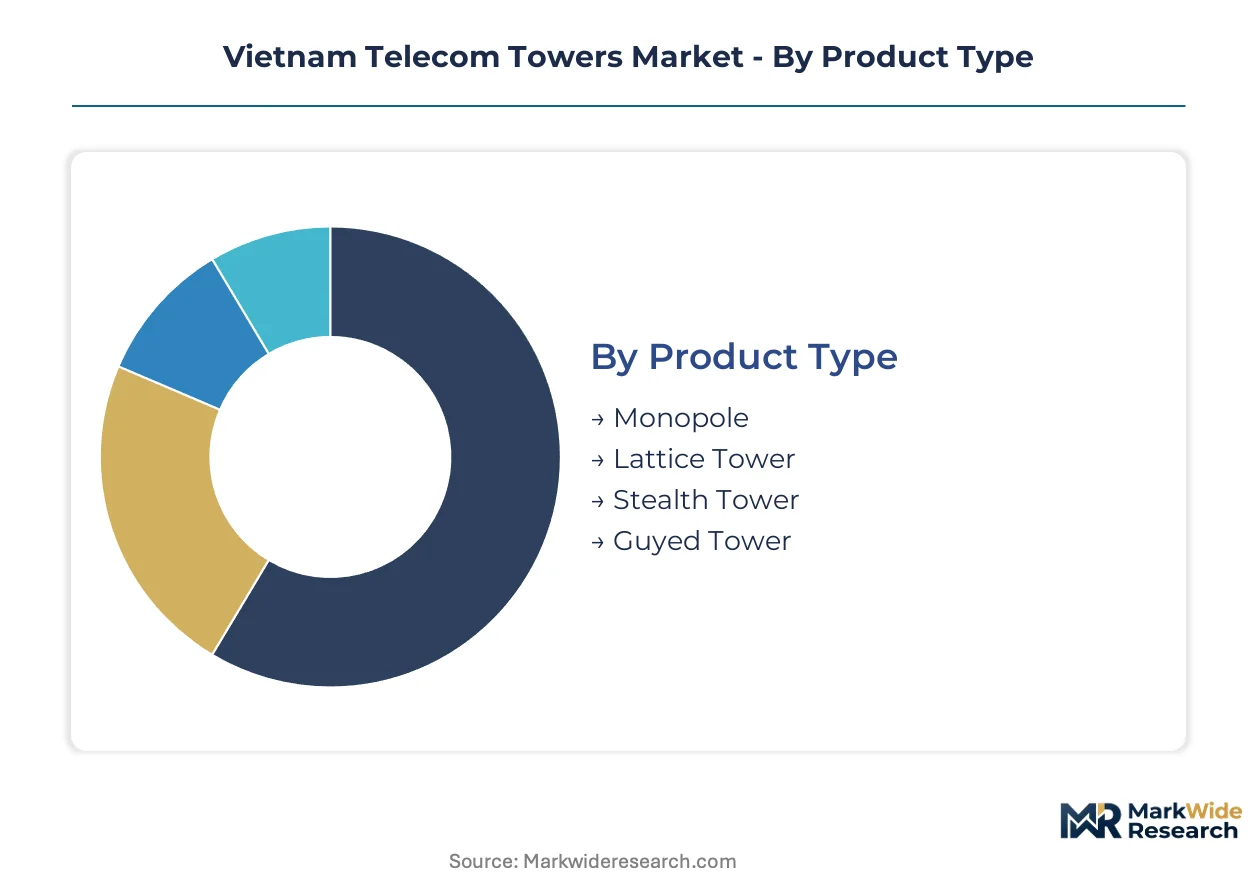
Vietnam's tower market fragments across structural designs, connectivity applications, and customer procurement patterns. Each segmentation axis reveals distinct margin dynamics shaped by regulatory mandates and terrain-specific engineering requirements.
Product Type:
Margin pools concentrate in specialized structural configurations where aesthetic compliance and wind-load engineering create pricing power.
- Monopole:Single-pipe steel structures with minimal ground footprint suit urban infill zones where Ho Chi Minh City zoning restricts visual impact. Demand clusters in dense metropolitan cores where permitting velocity determines contract awards.
- Lattice Tower:Triangular or four-legged steel frameworks engineered for 150+ kilometer per hour wind tolerance dominate terrain-exposed installations across Central Highlands provinces. Rural connectivity mandates are accelerating deployment where ground stability and guy-wire anchoring prove feasible.
- Stealth Tower:Composite or disguised structures command premium positioning near heritage districts and airport approach corridors where aesthetic compliance overrides cost efficiency.
- Guyed Tower:Cable-supported lightweight frameworks serve temporary or cost-constrained deployments in Mekong Delta districts with lower wind exposure specifications.
The dominant share belongs to Lattice Tower configurations, while Monopole designs are closing the gap fastest through urban densification projects.
Application:
Application-driven segmentation tracks where capital deployment aligns with spectrum auction schedules and universal service obligations.
- Mobile Networks:4G LTE and 5G infrastructure hosting for Viettel, VNPT, and mobile network operators absorbs the majority of new tower construction across underserved provinces.
- Rural Connectivity:Universal service mandate deployments targeting Mekong Delta and Central Highlands coverage gaps represent the steepest expansion trajectory as national ICT frameworks harden connectivity obligations.
- Broadcasting:Terrestrial television and radio transmission towers serve state media infrastructure with stable but slower-growth tenancy profiles.
- Emergency Services:Dedicated structures for disaster response and public safety communications occupy strategic positioning requirements near provincial coordination centers.
Mobile Networks retains the largest installed base, though Rural Connectivity is gaining share fastest through Ministry of Information and Communications mandate enforcement.
Technology:
Technology segmentation reveals where tenancy revenue scales with spectrum band density and equipment loading factors.
- 5G:Mid-band and millimeter-wave infrastructure demands denser tower spacing and upgraded power systems, concentrating investment in urban corridors and industrial zones.
- 4G LTE:Existing network expansion continues across provincial gaps where 5G economics remain unviable, sustaining steady tenancy demand for macro tower configurations.
- Satellite:Backhaul and remote coverage solutions serve mountainous terrain where fiber connectivity proves uneconomical.
- Wi-Fi:Hotspot aggregation towers support enterprise and municipal offload strategies in high-density districts.
5G infrastructure commands the highest revenue per site, while 4G LTE maintains volume leadership through rural completion timelines.
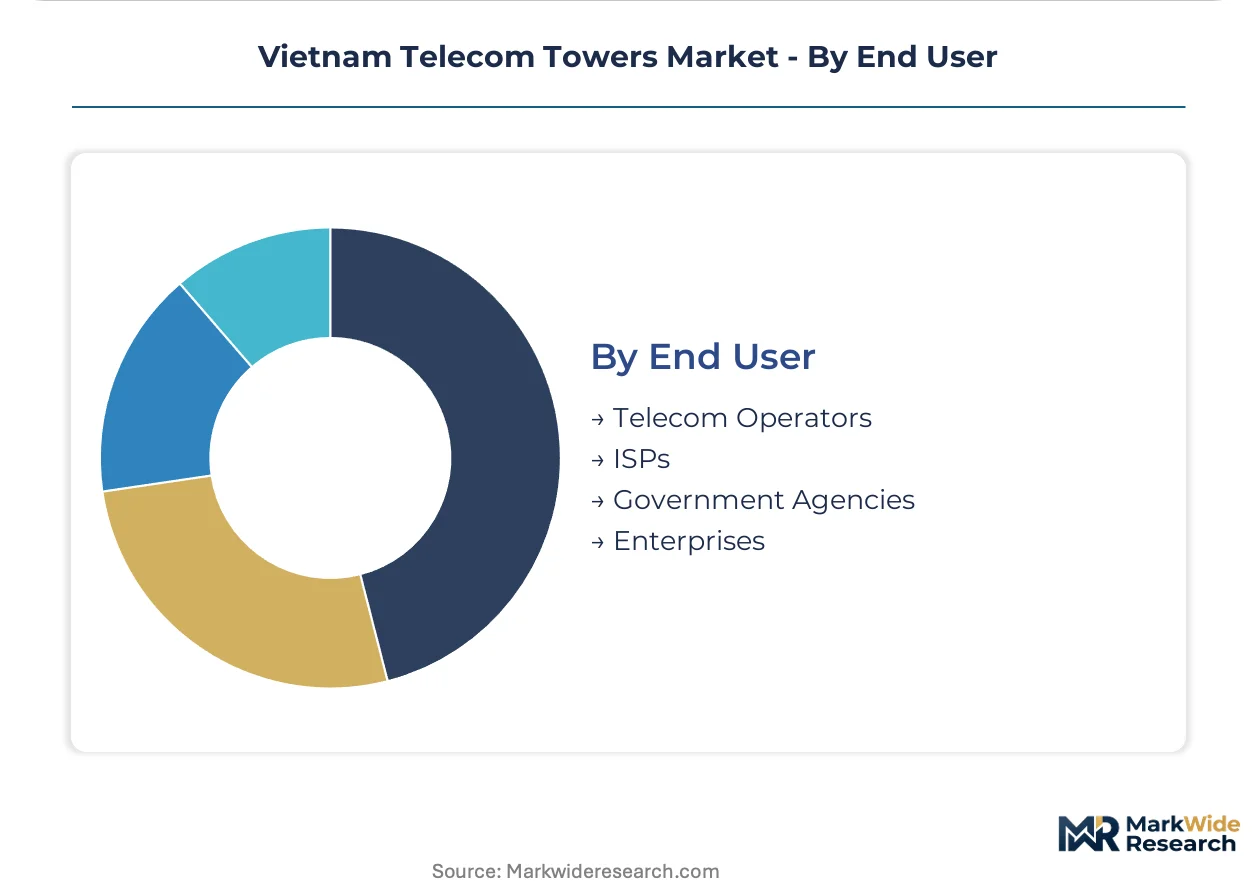
End User:
Customer-type segmentation exposes diverging procurement patterns between carrier-owned deployment and third-party tenancy models.
- Telecom Operators:Viettel, VNPT, and MobiFone drive greenfield construction through captive tower subsidiaries and long-term infrastructure commitments.
- ISPs:Fixed wireless and broadband providers lease capacity for last-mile distribution, expanding addressable tenancy beyond traditional mobile carriers.
- Government Agencies:Provincial administrations and defense entities procure dedicated structures for secure communications and emergency coordination networks.
- Enterprises:Private network deployments for mining, logistics, and industrial zones represent emerging demand as spectrum licensing evolves for vertical applications.
Telecom Operators account for the predominant share of contracted capacity, with ISPs expanding their tenancy footprint fastest through wholesale leasing arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Ho Chi Minh City and Hanoi where zoning scarcity accelerates permit premiums, while Central Highlands provinces compete on structural steel cost efficiency rather than site scarcity. This geographic asymmetry shapes how tower companies allocate fabrication partnerships and workforce training investments across Vietnam's provincial landscape.
Mekong Delta
Rural connectivity mandates and universal service obligations drive tower deployment across Ca Mau, An Giang, and Can Tho provinces. The Ministry of Information and Communications directs subsidy flows toward districts with persistent coverage gaps below national broadband targets. Steel fabrication partnerships with ASEAN suppliers cluster in Can Tho industrial zones where river transport reduces lattice component logistics costs.
Central Highlands
Terrain-exposed installations requiring 150+ kilometer per hour wind tolerance specifications dominate construction in Gia Lai, Dak Lak, and Lam Dong provinces. Provincial land-use decrees impose stricter environmental impact assessments on highland sites above 800 meters elevation. Viettel Construction operates dedicated rigging academies in Pleiku and Buon Ma Thuot to address certified technician scarcity in these remote jurisdictions.
Ho Chi Minh City Metro
Urban densification and 5G mid-band deployment compress tower spacing requirements across District 2, District 7, and Thu Duc City. Ho Chi Minh City zoning restrictions limit ground footprint and mandate stealth tower variants near heritage districts and Tan Son Nhat airport approach corridors. EdgePoint Vietnam competes on speed-to-permit velocity where municipal approval timelines determine contract awards.
Hanoi Capital Region
Government and defense communications infrastructure concentrates tower demand in Ba Dinh, Cau Giay, and Long Bien districts. National technical standards for electromagnetic exposure limits apply stringent field measurement protocols near sensitive installations. State-owned mobile network operators maintain captive tower subsidiaries to secure priority positioning for secure coordination networks.
North Central Coast
Industrial zone expansion and logistics corridor development generate enterprise private network demand in Thanh Hoa, Nghe An, and Ha Tinh provinces. Provincial electrification targets accelerate solar-hybrid power system integration for off-grid tower sites in mountainous districts. OCK Group Berhad anchors ASEAN expansion fabrication partnerships with steel suppliers in Vinh industrial clusters.
Vietnam Telecom Towers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Vietnam's tower market. State-affiliated operators with captive construction subsidiaries dominate greenfield deployment volume through spectrum license commitments and universal service obligations. Independent tower companies differentiate through build-to-suit speed and multi-tenant technical integration capabilities. Strategic moves concentrate on permit acquisition velocity, workforce academy investments, and steel fabrication partnership structures rather than balance sheet scale alone.
Among Vietnam-based state-affiliated operators, Viettel Construction and VNPT Net Corporation exemplify the integrated operator archetype combining spectrum holdings with captive tower deployment. EdgePoint Vietnam occupies the independent build-to-suit specialist position where speed-to-permit capabilities compete against capital scale. OCK Group Berhad represents the ASEAN regional fabricator archetype leveraging cross-border steel partnerships to reduce import dependency for lattice tower components.
| Leading Market Players |
|---|
| Viettel Construction |
| OCK Group Berhad |
| VNPT Net Corporation |
| EdgePoint Vietnam |
| Vinaphone |
| MobiFone |
| Viettel Group |
| FPT Corp |
| CMC Telecom |
| Others |
Pricing and Supply Chain Analysis
Composite material substitution for galvanized steel in stealth tower construction simultaneously relocates fabrication partnerships toward ASEAN composite suppliers and compresses margin structures for traditional steel fabricators serving heritage district and airport corridor projects.
Pricing Analysis
Ho Chi Minh City commands permit premiums three to four times Central Highlands structural steel costs. Three-tier pricing structure across premium stealth variants, standard lattice configurations, and economy guyed frameworks reflects aesthetic compliance burden and wind-load engineering intensity. Price erosion runs through economy tier deployments as ASEAN steel partnerships reduce import dependency. Rural connectivity mandates render government-subsidized provinces least price-sensitive, while enterprise private network buyers in industrial zones negotiate hardest on tenancy rates.
Supply Chain Analysis
Just-in-time lattice component delivery from Can Tho industrial zones clashes with strategic stockpiling of composite materials for stealth tower orders where aesthetic approval timelines remain unpredictable. Supply concentrates in Vietnam for steel fabrication, Malaysia for ASEAN regional component sourcing, and China for specialized composite resins. Raw material dependencies span structural steel grades, guy-wire zinc coatings, and RF-transparent composite polymers. Single-source vulnerability concentrates in certified tower rigging technician training pipelines. Distribution runs through Viettel Construction captive logistics and third-party heavy-haul contractors serving remote Central Highlands sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mobile network operators as tower-sharing mandates force multi-tenant procurement consolidation, compressing vendor negotiation leverage for independent tower companies.
For Market Incumbents: Fortify permit acquisition velocity through municipal relationship investments in Ho Chi Minh City and Hanoi where zoning scarcity accelerates approval premiums. Deepen captive workforce academy scale to offset certified technician scarcity threatening deployment timelines. Counter OCK Group Berhad's ASEAN fabrication partnerships by securing exclusive steel supply agreements with Vinh industrial cluster suppliers. For New Entrants and Emerging Players: Fast-track Ministry of Information and Communications multi-tenant certification to unlock rural connectivity mandate contracts where incumbent saturation remains lowest. Penetrate Mekong Delta provinces through solar-hybrid power system integration, addressing grid reliability fragmentation that state-affiliated operators underweight. Lead with build-to-suit speed guarantees rather than capital scale in Central Highlands terrain-exposed installations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed independent tower specialists holding concentrated Ho Chi Minh City and Hanoi permit portfolios but lacking workforce academy infrastructure. Long-term viability hinges on 5G densification economics and edge computing convergence tenancy expansion. Watch spectrum auction schedules as inflection signals for provincial deployment priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Workforce Academy Expansion | Viettel Construction's Pleiku and Buon Ma Thuot academies address certified technician scarcity constraining Central Highlands deployment velocity. |
| Composite Material Partnership | ASEAN composite supplier alliances enable stealth tower positioning in Tan Son Nhat airport approach corridors previously unavailable under steel-only specifications. |
| Permit Velocity Investment | EdgePoint Vietnam's municipal relationship infrastructure in Thu Duc City demonstrates speed-to-permit differentiation against balance-sheet-heavy state competitors. |
| Solar-Hybrid Power Integration | Renewable energy tenancy unbundling in Mekong Delta districts creates specialized revenue lines as grid reliability varies by province. |
| Multi-Tenant Structural Pre-Engineering | Ministry of Information and Communications mandate compliance at initial construction reduces retrofit costs for competitor co-location scenarios. |
Research Methodology
The analysis maps lattice tower, monopole, stealth tower, and guyed tower configurations, each validated through tower company procurement directors, mobile network operator infrastructure planners, provincial permitting officers, and steel fabrication plant managers. Primary fieldwork combined with secondary validation against Vietnam Ministry of Information and Communications regulatory filings, ASEAN customs trade data, and provincial land-use decree records. Bottom-up deployment volume estimates triangulated against top-down spectrum auction commitment disclosures.
Consistency checks validated volume and value outputs against external benchmarks including tower company tenancy disclosure patterns and national broadband target progress reports. Segmentation dimensions modeled encompass structural design type, connectivity application, technology generation, and end-user procurement archetype across the projection horizon. CAGRs derived from deployment run-rate analysis adjusted for provincial permitting backlog differentials and certified technician pipeline constraints.
Underlying assumptions cover spectrum auction schedule adherence, steel import tariff stability, and provincial electrification target achievement, with deviation risk concentrated in land-use decree variability between Ho Chi Minh City and Central Highlands jurisdictions. Revision becomes warranted when Ministry of Information and Communications mandate enforcement intensity crosses thresholds altering multi-tenant pre-engineering requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market