
 Latin America Cloud Computing Market | 2026-2036
Latin America Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Cloud Computing Market Insights
Market Context
ISO 27001 certification is reorganizing competitive access across the Latin America cloud landscape, filtering out providers lacking audited security management systems. Amazon Web Services leverages its early regional infrastructure investments to anchor enterprise workloads in Brazil and Mexico. Microsoft Azure sustains government cloud contracts through localized data residency commitments. Google Cloud Platform differentiates via specialized AI and analytics tooling for financial services clients.
Technical and Segment Structure
Latin America cloud computing denotes the delivery of on-demand compute, storage, and networking resources via geographically distributed data centers operated by third-party providers, typically accessed through APIs and web consoles with latency targets under 50 milliseconds for regional zones. Public cloud deployments capture the majority of current spending as enterprises prioritize capital expenditure reduction, while hybrid cloud architectures are expanding fastest among regulated industries seeking workload portability between on-premises and off-premises environments. SaaS consumption within the service model layer commands the deepest margin pools due to recurring subscription economics and lower customer acquisition costs relative to infrastructure provisioning.
Regulatory Environment and Outlook
Brazil's LGPD enforcement through its national data protection authority and Mexico's financial sector cloud guidelines issued by CNBV are reshaping procurement criteria toward certified compliance architectures. Argentina's personal data protection law and Chile's forthcoming digital infrastructure framework add layered jurisdictional complexity for cross-border data flows. Stakeholders must monitor evolving localization mandates and sovereignty requirements as policymakers balance innovation incentives against national security considerations.
Market Dynamics
Brazil's LGPD enforcement and Mexico's CNBV cloud guidelines are forcing financial institutions to re-architect legacy infrastructure, compressing procurement cycles toward certified compliance-first vendors.
Growth Catalysts
- LGPD Data Localization Mandates:Brazil's national data protection authority requires financial data residency within national borders, compelling banks to migrate from on-premises data centers to certified cloud infrastructure operated by domestic or regional providers.
- Financial Services:Open banking regulations across Brazil and Mexico mandate real-time API connectivity, driving demand for elastic compute and managed Kubernetes platforms that scale with transaction volumes.
- São Paulo Enterprise Corridor:Concentration of multinational headquarters and fintech unicorns in Brazil's financial capital generates sustained demand for low-latency edge computing and dedicated cloud connectivity.
Market Restraints
- Power Infrastructure Volatility:Unreliable grid supply in secondary Brazilian cities forces cloud operators to invest in redundant diesel generation, elevating operational expenditure and constraining margin expansion outside metropolitan zones.
- Cross-Border Data Friction:Argentina's personal data protection law and Chile's pending digital sovereignty framework impose jurisdictional complexity on multi-country deployments, extending legal review cycles and discouraging regional consolidation.
- Skilled Talent Scarcity:Shortage of certified cloud architects and DevOps engineers in Colombia and Peru limits service provider expansion into Andean markets, capping addressable market growth.
Strategic Opportunities
- Colombia's Underpenetrated Enterprise Segment:Mid-market manufacturers in Bogotá and Medellín remain below 20% cloud adoption, presenting first-mover advantage for providers offering industry-specific ERP migration services.
- AI-Analytics Convergence:Financial institutions in Mexico City's fintech cluster seek unified platforms combining generative AI with real-time fraud detection, creating demand for specialized GPU-as-a-service offerings.
- Peru's Regulatory Tailwind:Pending central bank guidelines on cloud risk management for payment processors will mandate external audit trails, opening compliance-as-a-service revenue streams.
Industry Challenges
- ISO 27001 Certification Timeline:Smaller domestic providers face 12-18 month audit cycles to achieve accredited security management systems, blocking participation in government and financial sector tenders.
- Hybrid Integration Complexity:Enterprises maintaining SAP and Oracle legacy cores struggle to orchestrate consistent security policies across on-premises and public cloud environments.
- Interconnection Standards Fragmentation:Absence of unified API standards between Brazilian and Mexican cloud exchanges forces redundant network provisioning, elevating customer switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Cloud Computing Market |
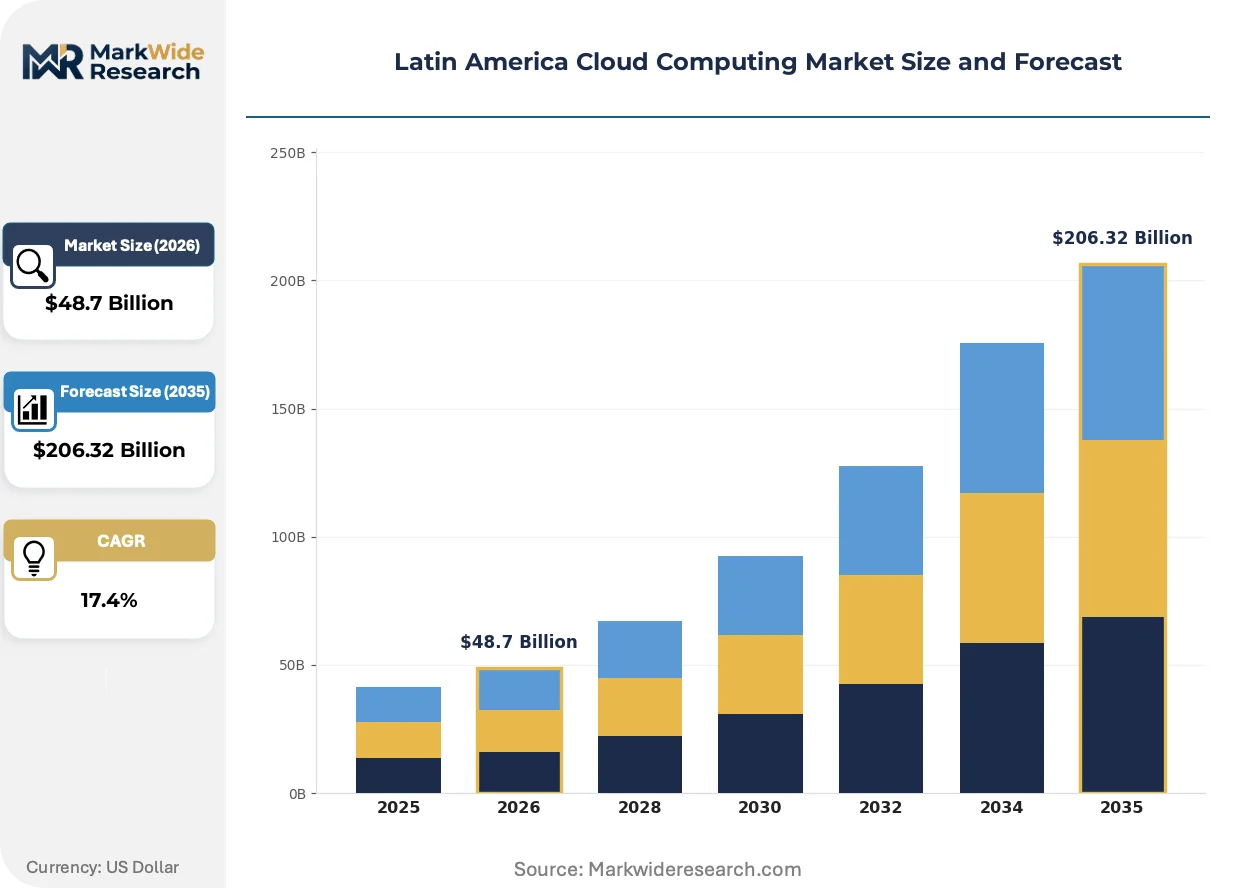
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $206.32 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Model: IaaS, PaaS, SaaS, FaaS Industry Vertical: Healthcare, BFSI, Manufacturing, Retail End User: Large Enterprises, SMEs, Government, Startups |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Cloud, Oracle Cloud, Alibaba Cloud, Huawei Cloud, Telefónica, SAP, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Cloud Computing Market Trends and Innovations
Latin American cloud infrastructure is pivoting toward sovereign-certified architectures as regulators tighten data residency requirements and financial institutions demand workload portability across hybrid environments.
Container orchestration platforms are bifurcating the infrastructure market. Kubernetes distributions enable banks to deploy identical workloads across on-premises data centers and public cloud regions. Large financial institutions in São Paulo and Mexico City are standardizing on cloud-native architectures for core banking systems. This technology shift is compressing traditional managed hosting margins while expanding platform-as-a-service revenue pools.
CNBV's financial sector cloud guidelines issued by Mexico's banking regulator mandate external audit capabilities and incident reporting protocols for institutions processing payment data. The framework requires documented business continuity procedures and encryption key management segregation. Smaller regional banks and payment fintechs face the steepest compliance burden, accelerating consolidation toward providers with pre-certified infrastructure stacks.
Consumption-based billing models are displacing fixed-term enterprise agreements across mid-market segments. Manufacturing and retail buyers in Brazil's interior states prefer pay-per-use compute tied to seasonal demand cycles rather than committed spend contracts. Channel partners in Campinas and Curitiba are restructuring compensation around customer utilization metrics rather than upfront license sales, aligning vendor incentives with actual workload growth.
Latin America Cloud Computing Market Segmentation
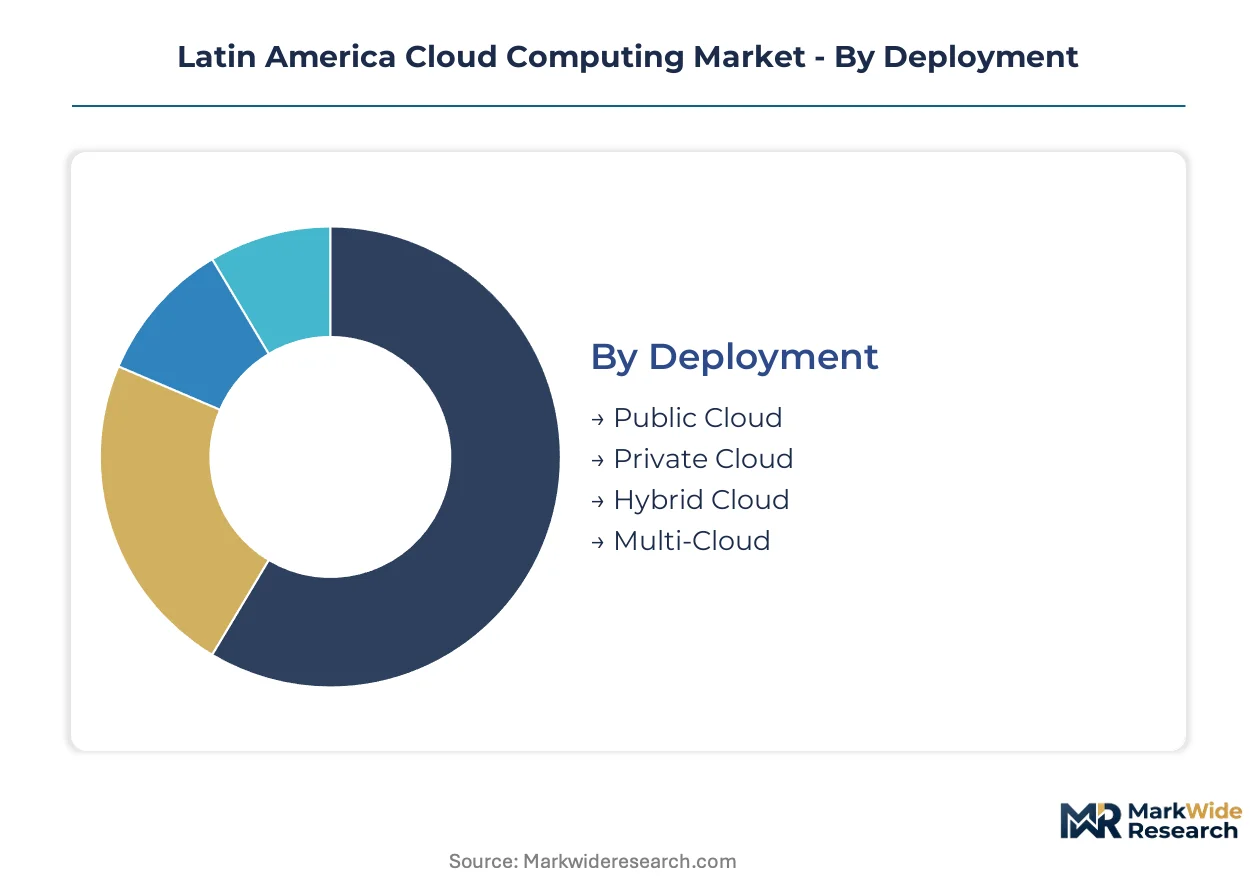
Cloud procurement patterns across Latin America fragment sharply by deployment architecture and regulatory exposure. Brazilian LGPD mandates and Mexico's CNBV guidelines force divergent infrastructure choices that reshape segment prioritization for vendors and enterprises alike.
Deployment:
Brazil's national data protection authority requires financial data residency within sovereign borders, compelling divergent deployment strategies between regulated and unregulated workloads.
- Public Cloud:Third-party operated infrastructure delivered over the internet with shared tenancy models. São Paulo's enterprise corridor concentrates demand from fintechs seeking elastic compute for open banking API traffic without capital-intensive data center builds.
- Private Cloud:Dedicated single-tenant environments with isolated compute and storage resources. Large Brazilian banks facing LGPD audit scrutiny are migrating core ledger systems to sovereign-certified private deployments to satisfy data localization mandates.
- Hybrid Cloud:Orchestrated workload portability between on-premises and off-premises environments. Manufacturing conglomerates in Mexico's industrial belt favor this architecture for seasonal capacity bursts while retaining sensitive IP on captive infrastructure.
- Multi-Cloud:Distributed workloads across two or more distinct cloud providers to mitigate vendor lock-in. Payment processors in Colombia's emerging fintech cluster adopt multi-cloud strategies to satisfy redundancy requirements under pending central bank guidelines.
Public Cloud handles the majority of throughput; Hybrid Cloud is the fastest mover on share.
Service Model:
Margin concentration varies dramatically by abstraction layer, with higher-level services capturing recurring revenue streams that infrastructure provisioning cannot match.
- IaaS:Raw compute, storage, and networking resources provisioned via API with metered consumption billing. Argentine enterprises recovering from currency volatility prefer IaaS for its capital expenditure reduction compared to depreciating owned hardware.
- PaaS:Managed development environments including container orchestration and database services. Mexico City's fintech cluster drives PaaS consumption for rapid application deployment without underlying infrastructure management.
- SaaS:Fully managed software applications accessed via subscription with vendor-controlled infrastructure. SaaS commands the deepest margin pools due to recurring economics and lower customer acquisition costs relative to infrastructure tiers.
- FaaS:Event-driven compute executing code in response to triggers without persistent server management. Peruvian payment startups leverage FaaS for sporadic transaction processing workloads with minimal baseline cost.
SaaS captures the dominant share of service revenue; FaaS is climbing the fastest as serverless architectures penetrate mid-market segments.
Industry Vertical:
Compliance burden intensity separates verticals, with financial services facing the steepest certification requirements and healthcare emerging from legacy infrastructure debt.
- BFSI:Banking, financial services, and insurance institutions with mission-critical transaction systems. Brazilian open banking regulations mandate real-time API connectivity, driving elastic compute demand that scales with payment volumes.
- Healthcare:Hospitals, clinics, and pharmaceutical distributors managing patient records and supply chains. Mexican healthcare networks are digitizing legacy paper systems, creating demand for HIPAA-aligned cloud storage with domestic data residency.
- Manufacturing:Industrial producers seeking predictive maintenance and supply chain visibility. Colombian mid-market manufacturers in Bogotá remain below 20% cloud adoption, presenting expansion opportunity for ERP migration specialists.
- Retail:Omnichannel merchants requiring inventory synchronization and customer analytics. Brazilian retail chains in Campinas and Curitiba prefer consumption-based billing tied to seasonal demand cycles rather than committed spend contracts.
BFSI generates the steepest infrastructure spend; Healthcare is expanding most quickly as digitization accelerates post-pandemic.
End User:
Procurement sophistication and compliance maturity create sharp segmentation between enterprise-scale buyers and emerging market entrants.
- Large Enterprises:Multinational corporations and domestic conglomerates with dedicated procurement functions. São Paulo-based headquarters of global firms anchor enterprise cloud demand with multi-year contracts and dedicated connectivity requirements.
- SMEs:Mid-market firms with 50-500 employees and limited IT staff. Chilean SMEs face the steepest talent scarcity, limiting self-managed cloud adoption and channeling demand toward fully managed service bundles.
- Government:Federal, state, and municipal agencies with sovereign data requirements. Mexico's government cloud contracts require localized data residency commitments that filter out uncertified providers.
- Startups:Venture-backed technology firms and bootstrapped innovators. Argentina's startup ecosystem leverages cloud credits and incubator programs to minimize burn rate while scaling infrastructure.
Large Enterprises dominate committed spend volumes; Startups are gaining share fastest as venture deployment into fintech and proptech accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo-Mexico City fiber corridor anchors regional cloud capacity, with submarine cables landing at Fortaleza and Boca Raton linking Latin American data centers to global backbone networks.
Brazil
ANPD enforcement of LGPD data localization rules compels financial institutions to migrate core systems to sovereign-certified facilities. São Paulo's enterprise corridor concentrates hyperscaler regions and domestic provider data centers serving open banking API workloads.
Mexico
CNBV cloud guidelines mandate external audit trails and encryption key segregation for payment processors. Mexico City's fintech cluster drives demand for GPU-as-a-service platforms supporting real-time fraud detection and generative AI workloads.
Argentina
Currency volatility and capital controls push enterprises toward consumption-based IaaS models over depreciating owned hardware. Buenos Aires-based software exporters leverage cloud credits to minimize burn rates while scaling infrastructure for regional markets.
Colombia
Pending central bank guidelines on cloud risk management for payment systems will mandate external audit capabilities. Bogotá and Medellín manufacturers below 20% cloud adoption present first-mover opportunity for ERP migration specialists.
Chile
Chile's forthcoming digital infrastructure framework adds jurisdictional complexity to cross-border data flows. Santiago's mining and logistics conglomerates favor hybrid architectures for seasonal capacity bursts while retaining sensitive operational data on captive infrastructure.
Latin America Cloud Computing Market Competitive Landscape
Listed hyperscalers compete with private specialists across compliance certification and data residency dimensions. The vendor base concentrates around three global platforms with established regional infrastructure, while domestic telecom operators and niche providers occupy sovereign-cloud and industry-vertical segments. Two strategic archetypes dominate: hyperscale platforms with pre-certified compliance stacks, and regional specialists with localized data center footprints. Competitive moves center on LGPD/CNBV certification acceleration and edge node expansion into secondary Brazilian cities.
Within the hyperscale tier, Amazon Web Services and Microsoft Azure occupy positions as infrastructure anchors with early regional investments and government contract access. Google Cloud Platform exemplifies the analytics-specialist archetype, targeting financial services clients with differentiated AI tooling. Among regional challengers, Telefónica represents the telecom-integrated model, leveraging existing fiber and data center assets to compete on latency and localized support.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Cloud |
| Oracle Cloud |
| Alibaba Cloud |
| Huawei Cloud |
| Telefónica |
| SAP |
| Others |
Pricing and Supply Chain Analysis
Hyperscale data center capacity utilization above 80 percent in São Paulo and Mexico City generates procurement leverage that compresses infrastructure-as-a-service margins while elevating platform-as-a-service price floors. This concentration dynamic filters downstream to enterprise buyers, where certified compliance architectures command persistent premiums over uncertified alternatives.
Pricing Analysis
Certification level creates the primary spread between hyperscale and regional provider offerings, with ISO 27001-accredited infrastructure sustaining 15-25 percent premiums over uncertified domestic alternatives. Consumption-based billing displaces fixed enterprise agreements across mid-market segments, particularly among Brazilian manufacturers with seasonal demand cycles. Pricing pressure stems from redundant diesel generation investments in secondary Brazilian cities, where grid volatility elevates operational expenditure and constrains margin expansion. SMEs exhibit highest price sensitivity, while large financial institutions prioritize compliance certification over unit cost minimization.
Supply Chain Analysis
Just-in-time capacity provisioning dominates hyperscale operations, though strategic stockpiling of GPU and specialized AI accelerators is emerging among Mexico City fintech clusters anticipating CNBV audit requirements. Supply concentration centers on Taiwan and South Korea for advanced semiconductors, with China anchoring server and networking equipment assembly. The chain rests on lithium-ion battery systems for uninterruptible power supply, fiber optic cable bundles, and precision cooling infrastructure. Single-source vulnerability in submarine cable landing points at Fortaleza creates chokepoint exposure. Distribution runs through direct hyperscaler sales organizations and telecom-integrated channel partners with localized data center footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container orchestration standardization is reconfiguring platform economics around Kubernetes interoperability, compressing traditional managed hosting margins while expanding API-driven service revenue pools across financial services verticals.
For Market Incumbents: Secure LGPD and CNBV certification moats before domestic challengers complete 12-18 month audit cycles. Anchor enterprise workloads through dedicated connectivity offerings in São Paulo's financial corridor. Capacity expansion into secondary Brazilian cities—Campinas, Curitiba, Porto Alegre—captures manufacturing demand outside hyperscaler zones. Vertical integration into edge computing nodes defends against latency-sensitive fintech requirements. For New Entrants and Emerging Players: ISO 27001 fast-track partnerships with accredited auditing bodies compress time-to-tender for government and BFSI procurement. Colombia's underpenetrated manufacturing segment in Bogotá and Medellín offers first-mover positioning below 20 percent cloud adoption. Peru's pending central bank cloud risk guidelines create compliance-as-a-service white space. Channel partner recruitment with utilization-based compensation aligns vendor incentives with actual workload growth. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with pre-certified sovereign cloud footprints over pure hyperscale exposure. Long-term viability hinges on data residency enforcement durability across Brazil, Mexico, and Chile. Acquisition targets include domestic telecom-integrated providers with localized edge infrastructure and established ANPD/CNBV audit relationships. Monitor CNBV guideline implementation velocity as inflection indicator for Mexico payment processor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Kubernetes standardization enables workload portability across hybrid environments for BFSI clients. |
| Geographic Expansion | Edge node deployment into Campinas and Curitiba captures manufacturing demand outside São Paulo corridor. |
| Strategic Partnership | Telecom-integrated channel partnerships accelerate compliance certification access for mid-market entrants. |
| Acquisition of Specialist Firm | GPU-as-a-service specialists address Mexico City fintech demand for real-time fraud detection infrastructure. |
| Product Launch | Sovereign-certified private cloud offerings satisfy LGPD core ledger migration requirements for Brazilian banks. |
Research Methodology
A standing panel of cloud infrastructure procurement officers, DevOps engineering leads, financial services CTOs, and regulatory compliance directors provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with secondary validation against hyperscaler capex disclosures, ANPD enforcement bulletins, CNBV regulatory filings, and submarine cable capacity databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler regional revenue disclosures and enterprise IT spending surveys. The analytical framework modeled deployment architecture, service model abstraction, industry vertical compliance intensity, and end-user procurement sophistication across the projection horizon. CAGRs derived from segment-level build-ups incorporating open banking transaction volume trajectories, LGPD enforcement timeline assumptions, and manufacturing digitization penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of data localization mandates or prolonged currency volatility in Argentina would require recalibration. Forecasts reflect documented assumptions regarding certification timeline completion and hyperscaler capacity expansion schedules. Revision becomes warranted when CNBV guideline implementation velocity or ANPD penalty enforcement crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Public Finance Cloud Market