
 South Korea Cloud Robotics Market | 2026-2036
South Korea Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Cloud Robotics Market Insights
Premium-tier AI algorithm specifications is unwinding competitive dynamics across the South Korea cloud robotics landscape. Samsung Electronics leverages its semiconductor foundry depth to sustain edge-to-cloud latency advantages. Rainbow Robotics anchors domestic demand through specialized quadruped platforms for industrial inspection. POSCO DX competes by extending its steel-plant automation expertise into cloud-native robot fleet management.
Cloud robotics fuses distributed computing architectures with physical automation systems, enabling real-time sensor fusion, remote task orchestration, and collective learning across robot networks via sub-50 millisecond latency thresholds. The primary commercial purpose centers on amortizing capital-intensive hardware through software-defined capability upgrades and centralized AI model refinement. Hybrid cloud deployment captures the dominant margin pool by balancing sensitive manufacturing data sovereignty with elastic compute scaling. Warehouse automation solutions lead solution-level demand as e-commerce fulfillment pressures intensify, while telepresence robots represent the fastest-expanding category amid persistent labor shortages in remote facility oversight.
MFDS safety certification requirements for healthcare service robots and METI-aligned intelligent robot standards constrain product entry timelines and elevate R&D compliance budgets. The Personal Information Protection Act and KISA cybersecurity frameworks further shape cloud data residency and cross-border model training protocols. Stakeholders must monitor evolving K-Battery and K-Semiconductor cluster policies that tie cloud robotics subsidies to domestic supply chain localization thresholds.
Market Dynamics
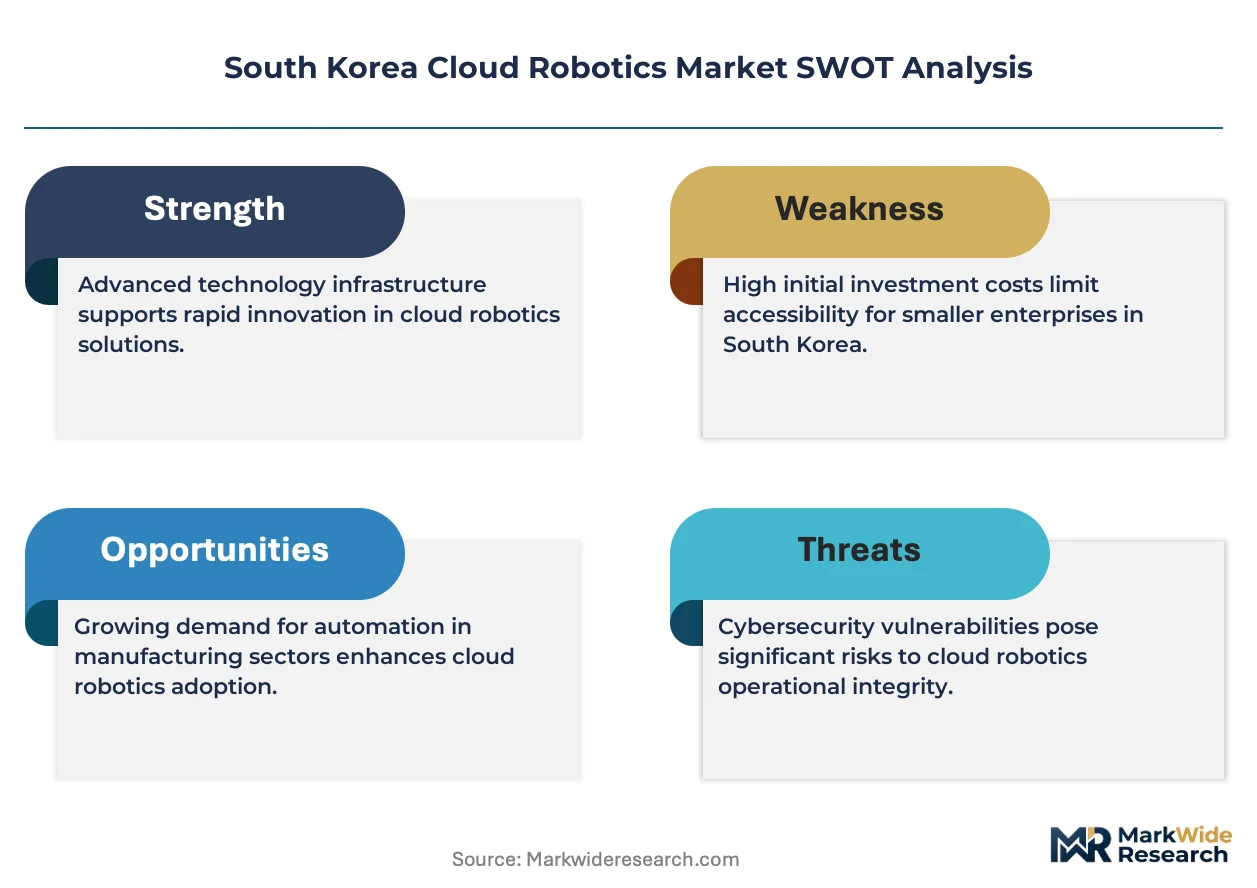
The MFDS safety certification framework and KISA cybersecurity mandates are compressing product development cycles while elevating compliance investment thresholds for domestic vendors.
Growth Catalysts
- Intelligent Robot Development and Supply Promotion Act:This legislation mandates domestic supply chain localization thresholds, channeling public R&D funding toward cloud-native fleet management platforms and edge computing modules.
- Warehouse automation solutions:E-commerce fulfillment centers in Gyeonggi Province are deploying cloud-connected AMR fleets to address persistent labor shortages in last-mile logistics operations.
- Sub-50 millisecond latency architectures:5G network slicing combined with edge data centers in Seoul's metropolitan cluster enables real-time collective learning across distributed robot networks.
Market Restraints
- Semiconductor supply concentration:Dependence on advanced GPU and AI accelerator imports creates vulnerability to foundry allocation constraints and export control fluctuations.
- Personal Information Protection Act data residency:Cross-border model training protocols face mandatory localization requirements that fragment cloud infrastructure economics.
- Legacy manufacturing system incompatibility:Brownfield steel and automotive plants require costly retrofitting to integrate cloud-native robot fleet orchestration layers.
Strategic Opportunities
- Telepresence robot deployment:Remote facility oversight applications in hazardous industrial environments represent underpenetrated demand within domestic process manufacturing.
- K-Battery cluster integration:Cell production automation subsidies tied to cloud robotics procurement create captive demand for vision-guided handling systems in Gwangju and Ulsan.
- Digital twin convergence:Fusion of physics simulation engines with live robot telemetry enables predictive maintenance contracts that shift revenue toward recurring software streams.
Industry Challenges
- Robot-AI systems integration specialists:Scarcity of engineers combining mechanical design, cloud architecture, and real-time control systems expertise constrains deployment velocity.
- MFDS healthcare certification timelines:Multi-stage safety validation for service robots in eldercare facilities extends commercialization cycles by 18-24 months.
- Interoperability standard fragmentation:Competing middleware protocols between ROS 2, OPC-UA, and vendor-proprietary stacks complicate multi-brand fleet management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Cloud Robotics Market |
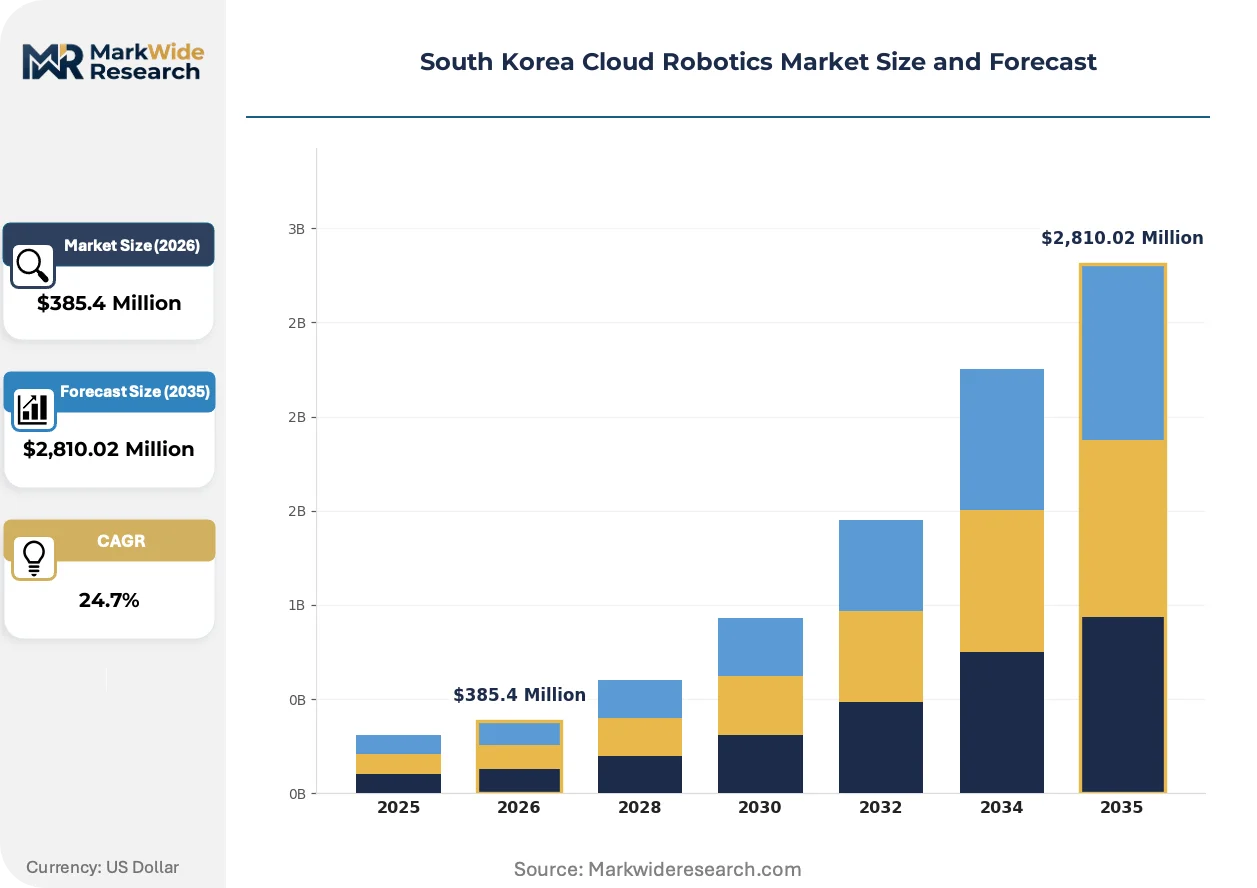
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,810.02 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Manufacturing, Healthcare, Retail, Logistics Solution: Warehouse Automation, Telepresence Robots, Delivery Robots, Service Robots Technology: AI Algorithms, Computer Vision, Machine Learning, IoT Integration |
| Companies Covered | LS Electric, CIMON, Samsung Electronics, LG Innotek, Rainbow Robotics, LG Electronics, Hyundai Motor, POSCO DX, Doosan Robotics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Cloud Robotics Market Trends and Innovations
Software-defined capability upgrades are displacing hardware refresh cycles as the primary value capture mechanism, while regulatory pressure on data sovereignty reshapes cloud architecture choices across industrial deployments.
Edge-native AI inference chips with on-device transformer execution are supplanting cloud-only processing pipelines for time-critical manufacturing tasks. Automotive tier-1 suppliers in Pyeongtaek and Hwaseong are piloting these modules for welding seam inspection at 10-millisecond response thresholds. This shift compresses bandwidth requirements while fragmenting compute economics between central cloud and distributed edge nodes.
METI-aligned intelligent robot standards are converging with South Korea's Intelligent Robot Development and Supply Promotion Act to create transnational certification reciprocity. Industrial robot vendors now engineer compliance documentation for both frameworks simultaneously, reducing duplicate testing costs. Healthcare service robots face the steepest compliance burden as MFDS and PMDA safety protocols diverge on human-robot collision force thresholds.
Subscription-based robot-as-a-service contracts are displacing capital purchase models among mid-market logistics operators. Third-party logistics providers in Incheon Free Economic Zone now procure AMR capacity on per-pallet-handled terms rather than equipment ownership. This shift concentrates fleet optimization expertise with platform vendors while transferring operational risk from end-users to robotics-as-a-service operators.
South Korea Cloud Robotics Market Segmentation
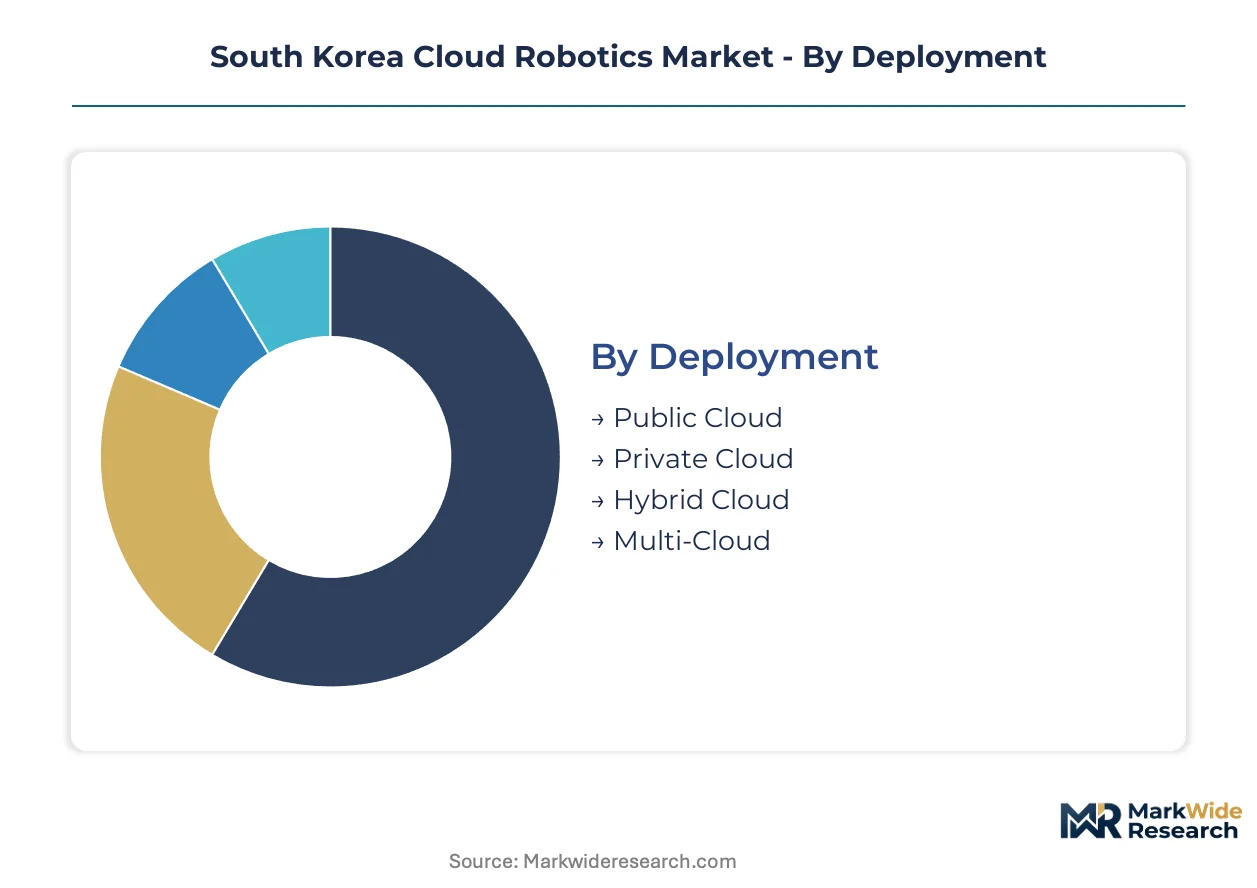
South Korea's cloud robotics market segments along deployment architecture, end-use vertical, solution type, and enabling technology. Each dimension channels through distinct procurement pathways—direct enterprise sales, systems integrator networks, or robotics-as-a-service platforms.
Deployment:
Channel mix varies sharply by deployment model: hybrid and multi-cloud configurations flow through systems integrators with vertical expertise, while private cloud deployments favor direct vendor relationships with large manufacturing conglomerates.
- Public Cloud:Shared infrastructure enables elastic compute scaling for pilot programs and seasonal demand spikes. Logistics operators in Incheon Free Economic Zone leverage this model for AMR fleet bursts during peak fulfillment windows.
- Private Cloud:Dedicated tenant environments satisfy MFDS and KISA data residency mandates for healthcare service robots. Seoul's metropolitan hospital networks require on-premises control planes for patient data protection.
- Hybrid Cloud:Split architectures balance sensitive manufacturing data sovereignty with burst compute for AI model training. Gyeonggi Province automotive plants deploy this model for welding inspection workloads.
- Multi-Cloud:Redundancy across hyperscaler platforms mitigages foundry allocation risk for GPU-dependent inference pipelines. Battery cell manufacturers in Ulsan adopt this approach for continuous production uptime.
Hybrid Cloud dominates installed base. Multi-Cloud is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive manufacturing deployments from subscription-driven healthcare and retail implementations.
- Manufacturing:Brownfield steel and automotive plants drive the highest per-site deployment values. POSCO DX and Hyundai Motor Group facilities in Pyeongtaek and Hwaseong anchor demand for cloud-native fleet orchestration layers.
- Healthcare:Eldercare facilities face 18-24 month MFDS certification timelines that compress procurement velocity. Post-certification, recurring software revenue streams exceed hardware margins.
- Retail:Mid-market logistics operators favor robotics-as-a-service contracts over capital purchase. Per-pallet-handled pricing models transfer operational risk to platform vendors.
- Logistics:E-commerce fulfillment pressures in Gyeonggi Province generate the steepest AMR deployment curves. Last-mile labor shortages accelerate cloud-connected fleet adoption.
Manufacturing captures the premium pricing tier. Logistics is climbing the fastest.
Solution:
Application maturity determines margin structure—warehouse automation commands established pricing benchmarks while emerging categories carry higher implementation risk premiums.
- Warehouse Automation:Cloud-connected AMR fleets with collective learning capabilities amortize hardware through software-defined route optimization. Gyeonggi Province fulfillment centers deploy these systems at scale.
- Telepresence Robots:Remote facility oversight in hazardous process manufacturing represents underpenetrated demand. Ulsan petrochemical complexes pilot these units for reactor inspection.
- Delivery Robots:Last-mile urban deployment faces sidewalk infrastructure variability and municipal permitting fragmentation. Seoul's dense metropolitan core constrains rollout velocity.
- Service Robots:Healthcare and hospitality applications require MFDS safety validation that extends commercialization timelines. Eldercare facilities in Busan drive post-certification demand.
Warehouse Automation dominates installed base. Telepresence Robots is where expansion concentrates.
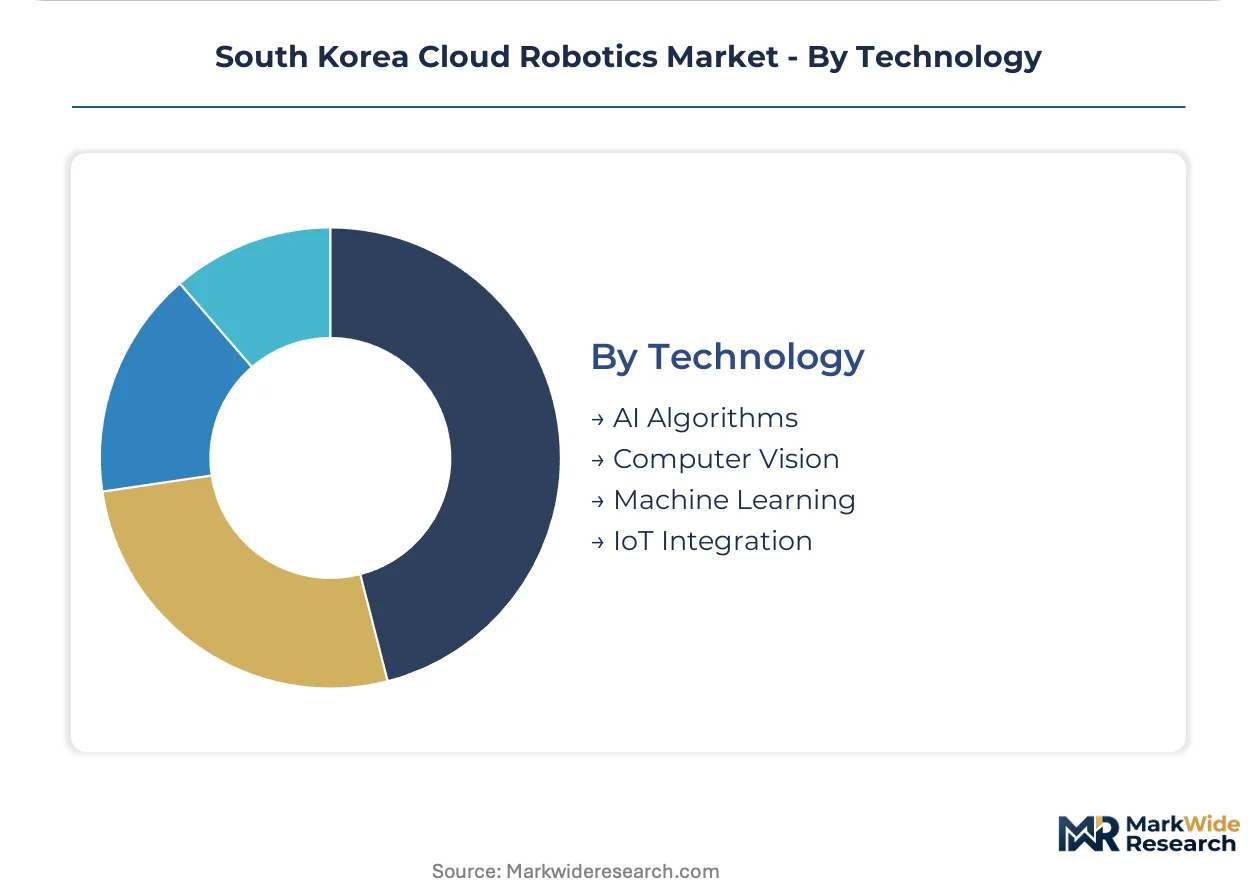
Technology:
Supply concentration in AI accelerators and edge inference chips shapes procurement patterns—domestic semiconductor foundry access determines vendor competitiveness.
- AI Algorithms:Transformer-based models with sub-50 millisecond latency requirements demand specialized GPU allocation. Samsung Electronics' foundry partnerships provide domestic vendors with supply security.
- Computer Vision:Welding seam inspection and battery cell quality control require 10-millisecond response thresholds. Edge-native inference chips displace cloud-only pipelines for these time-critical tasks.
- Machine Learning:Federated learning across robot networks enables collective improvement without centralizing sensitive manufacturing data. KISA cybersecurity frameworks shape implementation architecture.
- IoT Integration:Sensor fusion from distributed edge nodes feeds digital twin simulations for predictive maintenance. Steel plants in Pohang leverage this convergence for downtime reduction.
AI Algorithms dominates installed base. Computer Vision is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for advanced GPU and AI accelerator components shapes regional deployment patterns, while domestic foundry capacity determines vendor competitiveness across sub-national markets.
Seoul Capital Area
Metropolitan data centers and 5G network slicing enable sub-50 millisecond latency for cloud-native robot fleets. The Intelligent Robot Development and Supply Promotion Act channels public R&D funding toward edge computing modules here. Gangnam and Songdo clusters host the highest density of robotics-as-a-service platform headquarters.
Gyeonggi Province
E-commerce fulfillment centers deploy cloud-connected AMR fleets to address persistent labor shortages in last-mile logistics. KISA cybersecurity frameworks mandate data residency for cross-border model training protocols. Pyeongtaek and Hwaseong automotive corridors anchor demand for welding inspection workloads.
Busan-Ulsan
Petrochemical complexes pilot telepresence robots for hazardous reactor inspection applications. MFDS safety certification timelines extend commercialization cycles for eldercare service robots. Ulsan battery cell manufacturers adopt multi-cloud redundancy for continuous production uptime.
Daegu-Gyeongbuk
Steel plant automation expertise extends into cloud-native fleet management for brownfield retrofitting. The Personal Information Protection Act fragments cloud infrastructure economics through mandatory localization requirements. Pohang steel clusters leverage digital twin convergence for predictive maintenance contracts.
Gwangju-Honam
K-Battery cluster subsidies tie cloud robotics procurement to domestic supply chain localization thresholds. Vision-guided handling systems capture captive demand from cell production automation mandates. Regional vendors concentrate on federated learning implementations that avoid centralizing sensitive manufacturing data.
South Korea Cloud Robotics Market Competitive Landscape
Listed leaders compete with private specialists across semiconductor foundry access and edge computing module supply. Market structure tilts toward consolidation among conglomerate-affiliated entities with captive component sourcing, while independent robot manufacturers occupy specialized niches. Three archetypes dominate: electronics conglomerates with semiconductor depth, steel-automation spinoffs with industrial process expertise, and pure-play robotics specialists with quadruped platforms. Competitive moves center on backward integration into AI accelerator supply and strategic partnerships for 5G network slicing deployment.
Within the conglomerate tier, Samsung Electronics and LG Electronics occupy positions defined by semiconductor foundry depth and component ecosystem control. Rainbow Robotics exemplifies the pure-play specialist archetype, anchoring domestic demand through focused platform development. POSCO DX represents the industrial-process extension model, leveraging steel-automation heritage into cloud-native fleet management. These three entities collectively illustrate how vendor positioning traces back to upstream supply chain configuration and captive technology access.
| Leading Market Players |
|---|
| LS Electric |
| CIMON |
| Samsung Electronics |
| LG Innotek |
| Rainbow Robotics |
| LG Electronics |
| Hyundai Motor |
| POSCO DX |
| Doosan Robotics |
| Others |
Pricing and Supply Chain Analysis
MFDS safety certification gates both supplier qualification and price stratification across South Korea's cloud robotics landscape. Vendors bearing healthcare robot approvals command substantial premiums over industrial automation peers, while KISA cybersecurity mandates fragment procurement pools into compliant and non-compliant tiers.
Pricing Analysis
Industrial OEM buyers anchor subscription-based robotics-as-a-service contracts as the dominant pricing structure. Three-tier pricing separates MFDS-certified healthcare platforms from standard industrial fleets and economy-grade logistics AMRs. Cost compression in the economy tier intensifies because foundry allocation constraints squeeze GPU-dependent inference modules. Mid-market logistics operators exhibit highest price sensitivity, whereas Seoul metropolitan hospital networks prioritize certification compliance over unit economics.
Supply Chain Analysis
Advanced GPU foundry access in Taiwan, South Korea, and the United States underwrites vendor competitiveness. AI accelerators, edge inference chips, and 5G network slicing modules draw from concentrated semiconductor fabrication. Single-source vulnerability in EUV lithography equipment exposes procurement timelines to export control fluctuations. Distribution runs through systems integrator networks with vertical expertise in automotive and steel automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects through ROS 2 and OPC-UA interoperability convergence, collapsing middleware fragmentation into unified fleet orchestration standards. This shift concentrates value capture with vendors controlling edge-to-cloud latency architectures.
For Market Incumbents: Fortify backward integration into AI accelerator supply through domestic foundry partnerships, insulating against GPU allocation volatility. Secure channel control by embedding robotics-as-a-service platforms within Gyeonggi Province logistics networks before certification requirements tighten. Defensive consolidation around edge computing module production anchors margin protection.
For New Entrants and Emerging Players: Anchor in telepresence robot deployment for Ulsan petrochemical reactor inspection, the most penetrable white-space segment. Target federated learning implementations that satisfy KISA data residency without centralizing sensitive manufacturing telemetry. Pursue hospital system partnerships in Busan eldercare facilities as a go-to-market angle.
For Investors and Strategic Acquirers: METI-MFDS certification reciprocity reshapes the acquisition landscape by collapsing duplicate testing costs for transnational vendors. Long-term viability centers on software-defined capability upgrade revenue streams exceeding hardware depreciation cycles. Target pure-play robotics specialists with quadruped platform depth. Watch K-Battery cluster subsidy thresholds as the inflection signal for captive demand creation.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native AI Chip Development | Samsung Electronics foundry partnerships compress latency below 10 milliseconds for welding inspection. |
| Robotics-as-a-Service Platform Launch | Per-pallet-handled pricing transfers operational risk from Incheon logistics operators to vendors. |
| MFDS Certification Fast-Track Investment | Accelerated safety validation unlocks Seoul metropolitan hospital procurement cycles. |
| Multi-Cloud Redundancy Architecture | Ulsan battery manufacturers mitigate foundry allocation risk across hyperscaler platforms. |
| Digital Twin Integration Partnership | Pohang steel clusters shift revenue toward predictive maintenance software subscriptions. |
Research Methodology
A standing panel of robotics platform engineers, automotive procurement leads, hospital biomedical directors, and KISA compliance officers provided ongoing calibration throughout the study. Primary interview data combined with secondary validation against SEC filings, hyperscaler capex disclosures, and MFDS certification databases. Bottom-up deployment tallies across Seoul, Gyeonggi, and Busan-Ulsan corridors triangulated against top-down vendor revenue estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment architecture, end-use vertical, solution type, and enabling technology dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating 5G infrastructure rollout pace and foundry capacity expansion schedules. Edge inference chip adoption curves and robotics-as-a-service contract penetration shaped industry-specific forecast inputs.
Material uncertainties — semiconductor export control shifts, MFDS certification timeline revisions, and K-Battery subsidy threshold adjustments — sit outside the modeled envelope. Forecasts reflect documented assumptions about latency requirement stability and data residency regime continuity. Practitioners should keep alternative scenarios live as Intelligent Robot Development and Supply Promotion Act localization mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Warehouse Robotics Market