
 UK Data Center Rack Market | 2026-2036
UK Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
UK Data Center Rack Market Insights
UK-based rack fabricators and European OEM supply chains serving the island market is recalibrating output schedules to match hyperscale buildout cadence across Slough, London, and Manchester clusters. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale colocation contracts. Rittal GmbH & Co. KG sustains dominance in precision enclosure engineering for enterprise and industrial edge sites. Vertiv Group Corp. competes on thermal-optimized rack architectures that address rising kW-per-rack densities.
A data center rack is a standardized metal framework designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA width specifications and depths ranging from 600mm to 1200mm to accommodate varying IT loads. Its primary commercial purpose is to organize physical infrastructure, enable efficient cable management, and support airflow optimization for thermal regulation in compute environments. Enclosed rack configurations command premium positioning due to their physical security and containment advantages in multi-tenant facilities, while smart rack segments with embedded environmental sensors represent the fastest-expanding margin pool as operators pursue real-time operational visibility. Open frame variants retain cost leadership for controlled-access private data halls where security exposure remains minimal.
The Health and Safety Executive enforces workplace equipment standards that influence rack load-rating certifications and installation protocols across UK facilities. BSI Group administers structural and electrical safety benchmarks that shape product compliance requirements for domestic and imported rack systems. OFGEM's electricity grid connection policies directly constrain data center power allocation timelines, making rack power density specifications a critical planning variable for developers. Stakeholders must weigh thermal design choices against evolving carbon reporting obligations and connection queue uncertainty before committing to long-dated infrastructure contracts.
Market Dynamics
Hyperscale cloud operators are compressing deployment timelines across the Slough-London corridor, forcing rack fabricators to synchronize production cadence with connection queue uncertainty under OFGEM's grid allocation protocols.
Growth Catalysts
- Net-zero carbon mandates:The UK's legally binding 2050 net-zero target is accelerating liquid-cooled rack specifications in Greater London and Midlands facilities.
- Slough-London fiber concentration:Dense fiber interconnectivity in this corridor is concentrating hyperscale buildout decisions, pulling precision enclosure demand forward.
- BSI Group safety benchmarks:Structural load-rating certifications under these standards are creating procurement preference for certified fabricators in multi-tenant colocation contracts.
Market Restraints
- Steel input volatility:Cold-rolled steel price fluctuations are compressing margin buffers for UK-based metal fabricators serving rack OEM supply chains.
- OFGEM connection queues:Grid allocation timeline uncertainty is freezing long-dated rack power density commitments for developers awaiting power confirmation.
- Copper thermal interface constraints:High-purity copper sourcing bottlenecks are limiting liquid-cooled manifold production scaling for next-generation densities.
Strategic Opportunities
- Manchester edge expansion:Secondary cluster development outside London is creating white space for modular rack deployments in lower-cost power zones.
- Smart rack sensor convergence:Embedded environmental monitoring with DCIM platforms is opening premium-margin configurations for real-time operational visibility.
- Carbon reporting integration:Streamlined Energy and Carbon Reporting (SECR) obligations are creating procurement preference for racks with embedded power metering.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design expertise is concentrating among a narrow pool of specialists, inflating compensation and extending hiring cycles.
- Legacy air-cooled infrastructure retrofit:Existing raised-floor facilities in Slough and Docklands are forcing complex hybrid thermal architectures during phased upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Data Center Rack Market |
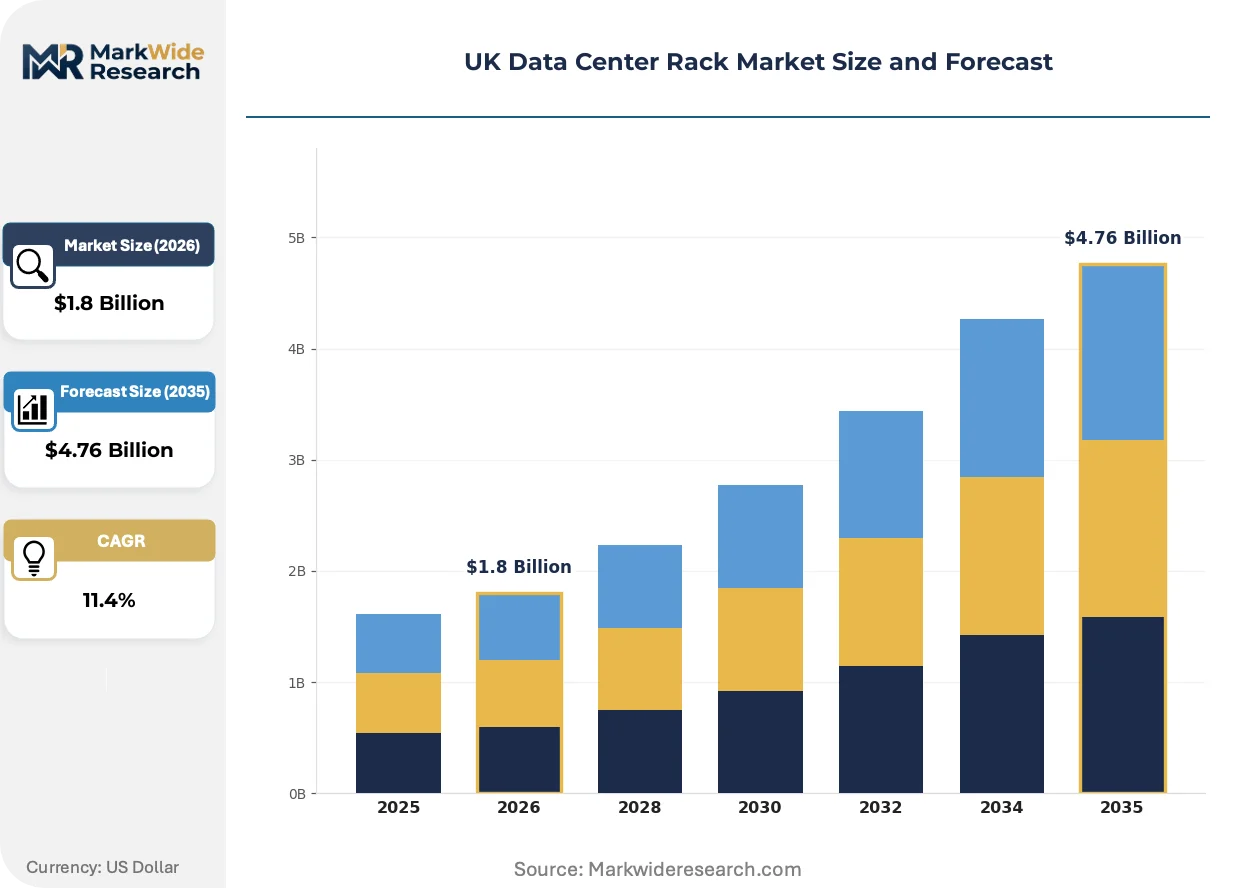
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Smart Rack Deployment Model: On-Premises, Colocation, Cloud, Hybrid End User: Telecommunications, IT Services, BFSI, Government Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Schneider Electric SE, Rittal GmbH & Co. KG, Eaton Corporation, Hewlett Packard Enterprise, Vertiv Group Corp., Black Box Corporation, Dell Inc., Cisco Systems, Inc., Chatsworth Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Data Center Rack Market Trends and Innovations
Rack architecture is bifurcating between ultra-high-density liquid-cooled hyperscale configurations and standardized air-cooled enterprise formats, with thermal design choices now preceding structural specifications in procurement workflows.
Direct-to-chip liquid cooling manifolds are absorbing thermal loads above 50kW per rack, a threshold air-cooled designs cannot sustain economically. Hyperscale operators in Slough and West London are specifying these systems as baseline requirements for new builds. This density absorption is compressing physical footprint requirements while concentrating power distribution complexity at the rack level.
The UK's Streamlined Energy and Carbon Reporting framework is mandating granular power disclosure from qualifying enterprises, including data center operators above consumption thresholds. Rack-level metering is becoming a procurement specification rather than an add-on feature. Colocation providers are responding by pre-installing intelligent power distribution units with embedded monitoring across their Slough-London inventory.
Specification authority is migrating from facilities engineering to IT procurement teams within hyperscale and enterprise buyers, compressing vendor evaluation cycles and unbundling after-sales service contracts. Traditional channel relationships with mechanical contractors are fragmentating as direct OEM engagement grows. This shift is most visible among cloud operators with dedicated infrastructure teams in the Thames Valley corridor.
UK Data Center Rack Market Segmentation
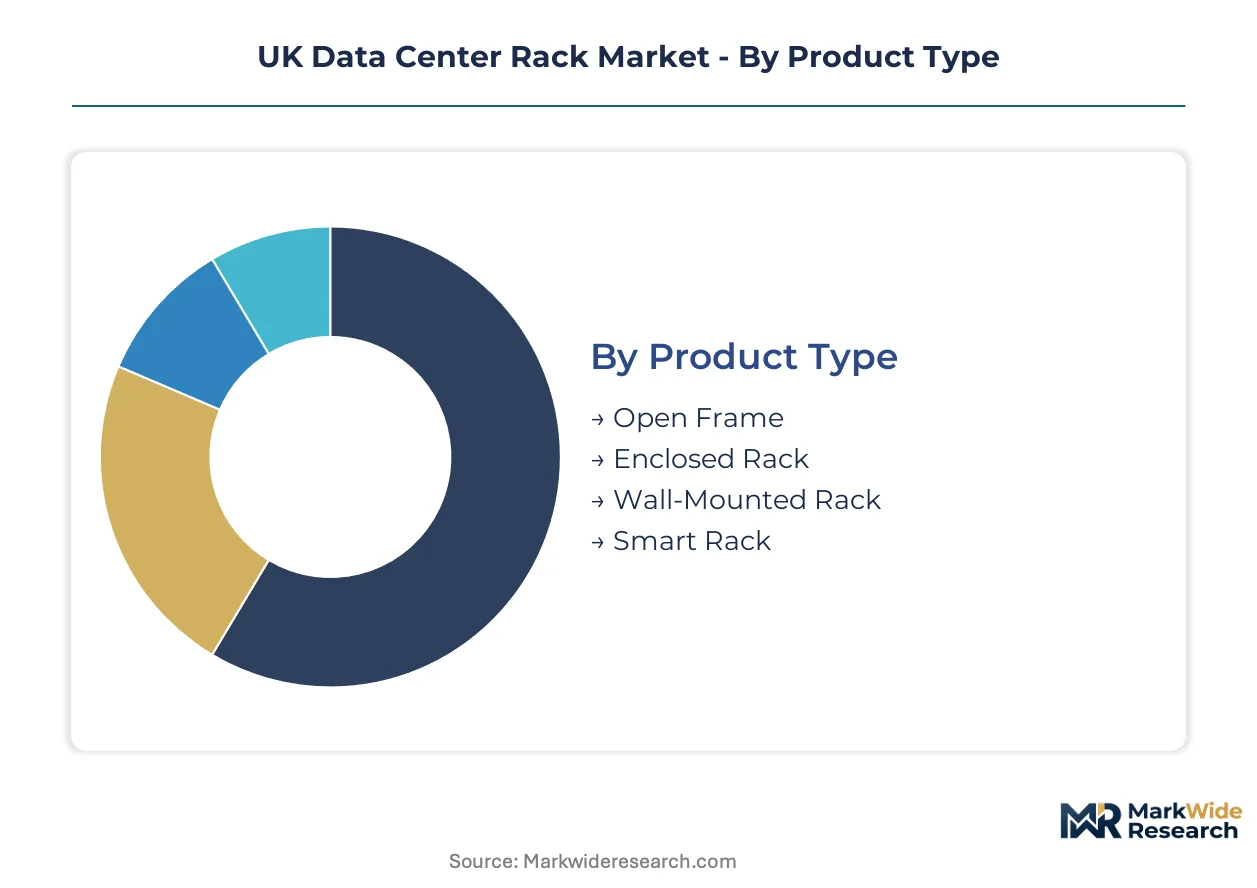
Rack specification authority in the UK market has fragmented across multiple procurement dimensions, with thermal density requirements and carbon reporting obligations now overriding traditional structural considerations. Understanding how demand distributes across product configurations, deployment models, and capacity tiers enables fabricators to align production schedules with the buildout cadence of hyperscale operators and colocation providers.
Product Type:
Supply concentration in precision enclosure manufacturing clusters around two dominant form factors, with fabrication capacity in the Midlands and Greater London calibrated to serve distinct thermal and security requirements.
- Open Frame:Unenclosed four-post structures constructed from cold-rolled steel with minimal airflow obstruction, optimized for controlled-access private data halls where physical security exposure remains negligible. Hyperscale operators in Slough specify these for high-density compute halls with dedicated mechanical infrastructure, prioritizing cost efficiency and unrestricted thermal exhaust over containment.
- Enclosed Rack:Fully enclosed metal cabinets with lockable front and rear doors, side panels, and integrated cable management channels, delivering physical security and airflow containment essential for multi-tenant colocation environments. Demand concentrates among Greater London colocation providers serving financial services and enterprise clients under BSI Group structural load-rating requirements.
- Wall-Mounted Rack:Compact swing-out or fixed enclosures designed for edge computing closets and telecommunications distribution points with severe floor space constraints.
- Smart Rack:Sensor-embedded enclosures with integrated environmental monitoring, power metering, and DCIM platform connectivity, specified under Streamlined Energy and Carbon Reporting obligations.
Enclosed rack configurations absorb the bulk of installed capacity across UK multi-tenant facilities; smart rack segments are expanding most quickly as real-time operational visibility becomes a procurement mandate.
Deployment Model:
Cost tier differentiation separates rack procurement workflows, with capital expenditure constraints governing on-premises decisions while operational expenditure models dominate cloud and hybrid specifications.
- Colocation:Third-party facility deployments where rack density specifications must align with landlord-provided power and cooling allocations, creating procurement complexity around thermal design verification. The Slough-London corridor concentrates this demand as operators compete for limited grid connection capacity under OFGEM protocols.
- On-Premises:Enterprise-owned facility installations where rack selection integrates with legacy raised-floor infrastructure and established mechanical systems, often constraining liquid-cooled adoption in Docklands and City of London facilities.
- Cloud:Hyperscale operator-owned data halls with standardized rack footprints optimized for direct-to-chip liquid cooling at densities exceeding 50kW per rack.
- Hybrid:Mixed infrastructure environments combining on-premises retention with colocation burst capacity, requiring rack standardization across disparate facility types.
Colocation deployments account for the majority of current rack procurement volume; cloud deployments are gaining share fastest as hyperscale operators accelerate Thames Valley buildouts.
End User:
Application-specific thermal and compliance requirements segment rack demand across verticals, with regulatory pressure varying significantly by sector.
- IT Services:Managed service providers and systems integrators serving enterprise clients with diverse workload requirements, driving demand for modular rack configurations with rapid reconfiguration capability.
- Telecommunications:Network operators deploying edge computing infrastructure for 5G latency reduction, specifying compact and wall-mounted racks for street cabinets and micro data centers.
- BFSI:Banking, financial services, and insurance institutions with stringent physical security and audit trail requirements, mandating enclosed racks with access logging in primary and disaster recovery sites.
- Government:Public sector data centers subject to Cabinet Office security classifications and carbon reduction targets, creating procurement preference for UK-manufactured racks with embedded power metering.
IT Services generates the largest share of enterprise rack procurement; BFSI specifications are tightening fastest around physical security and environmental monitoring integration.
Capacity:
Volume distribution across capacity tiers reflects the bifurcation between edge computing minimalism and hyperscale density concentration.
- Large:42U to 48U enclosures supporting 30-50kW per rack with integrated busbar power distribution and liquid cooling manifold preparation, specified by hyperscale operators in West London and Manchester clusters.
- Extra Large:Custom-height enclosures exceeding 48U with reinforced structural members for direct-to-chip cooling infrastructure, deployed in purpose-built facilities with slab-grade floors and overhead fluid delivery.
- Medium:24U to 42U standard enclosures for enterprise data halls and regional colocation facilities with moderate density requirements.
- Small:Sub-24U compact racks for network closets, edge nodes, and distributed IT environments with severe space constraints.
Large capacity racks dominate current hyperscale procurement; extra large configurations are climbing the fastest as liquid-cooled densities exceed 50kW thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-rolled steel feedstock from Sheffield and Rotherham anchors UK rack fabrication capacity, with Midlands metalworking clusters supplying structural components to data center buildouts across England.
London and the Southeast
Hyperscale cloud operators compress deployment timelines across the Slough corridor, where fiber density and power availability concentrate. OFGEM's grid connection queues constrain long-dated rack power density commitments for developers awaiting allocation confirmation. Liquid-cooled rack specifications dominate new builds in West London facilities exceeding 50kW per rack.
Midlands
Precision enclosure manufacturing clusters around Birmingham and Coventry serve enterprise and industrial edge demand. BSI Group structural load-rating certifications create procurement preference for certified fabricators in multi-tenant contracts. Regional metal fabricators recalibrate output schedules to match hyperscale buildout cadence from Thames Valley operators.
North England
Manchester edge expansion creates white space for modular rack deployments in lower-cost power zones outside London. Secondary cluster development pulls demand for standardized air-cooled enterprise formats in regional colocation facilities. Local authorities expedite planning permissions for data center zones to capture investment flowing from constrained Southeast markets.
Scotland
Renewable energy abundance attracts hyperscale operators seeking carbon-neutral power for high-density compute. The Scottish Government's data center sector strategy targets Edinburgh and Glasgow corridors for expansion. Cooler ambient temperatures reduce mechanical cooling loads, favoring air-cooled rack economics for certain workload categories.
Wales
Cardiff and Newport edge nodes serve latency-sensitive applications for Bristol and Birmingham metro markets. Welsh Government innovation funding supports micro data center deployments in former industrial zones. Compact wall-mounted rack configurations address severe floor space constraints in telecommunications distribution points.
UK Data Center Rack Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue liquid-cooled specialization and smart sensor integration. The UK data center rack market structures around three tiers: integrated power-cooling portfolios, precision enclosure engineering specialists, and thermal-optimized architecture providers. Two strategic archetypes dominate: full-stack infrastructure vendors leveraging electrical-mechanical integration, and focused metal fabricators competing on lead times and customization. Competitive moves concentrate on strategic partnerships with hyperscale operators and portfolio diversification into edge-computing form factors.
Among European-headquartered conglomerates, Schneider Electric SE and Rittal GmbH & Co. KG exemplify contrasting archetypes—the former anchoring large-scale colocation contracts through integrated portfolios, the latter sustaining dominance in precision enclosure engineering. Vertiv Group Corp. occupies a position competing on thermal-optimized rack architectures. These three represent the competitive spectrum from electrical integration through mechanical precision to thermal specialization.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rittal GmbH & Co. KG |
| Eaton Corporation |
| Hewlett Packard Enterprise |
| Vertiv Group Corp. |
| Black Box Corporation |
| Dell Inc. |
| Cisco Systems, Inc. |
| Chatsworth Products |
| Others |
Pricing and Supply Chain Analysis
Backward integration into cold-rolled steel production anchors pricing power for UK-based fabricators serving the Slough-London corridor, while outsourced copper thermal interface sourcing exposes margin compression at the liquid-cooled premium tier. This structural split between captive metal feedstock and imported specialty components shapes how rack OEMs defend position across standard versus high-density configurations.
Pricing Analysis
Warranty and after-sales service bundling separates premium rack suppliers from unbundled commodity competitors in UK procurement workflows. Three-tier pricing structure across premium, standard, and economy levels tracks BSI Group certification status and liquid-cooling manifold integration. Cost compression in the standard tier is intensifying because cold-rolled steel price volatility feeds directly into landed costs. Hyperscale cloud operators exhibit lowest price sensitivity due to total-cost-of-ownership framing, while regional colocation providers in Manchester and North England remain most price-constrained.
Supply Chain Analysis
Cold-rolled steel feedstock draws from Sheffield and Rotherham mills, while high-purity copper for liquid-cooled manifolds sources from German and Belgian specialty metal refiners. Structural steel, busbar copper, and precision-machined thermal interfaces constitute the three critical input categories. Single-source vulnerability concentrates in copper thermal interface supply, where limited European refining capacity creates allocation risk during hyperscale buildout surges. Distribution runs through direct OEM engagement with hyperscale operators and mechanical contractor channels serving enterprise and colocation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OFGEM's grid connection queue bottleneck props rack power density pricing, constraining supply elasticity as developers await allocation confirmation before committing to long-dated infrastructure contracts.
For Market Incumbents: Lock in hyperscale operator relationships through integrated power-cooling portfolio contracts before specification authority migrates fully to IT procurement teams. Deepen captive supply of cold-rolled steel structural components through Midlands fabrication capacity expansion. Certification investment under BSI Group load-rating protocols creates switching costs against emerging metal fabricators. For New Entrants and Emerging Players: Streamlined Energy and Carbon Reporting obligations in the UK open a window for smart rack sensor specialists to capture procurement preference from qualifying enterprises above consumption thresholds. Target Manchester edge expansion zones where lower-cost power zones reduce total project economics sensitivity. Direct DCIM platform integration serves as the decisive go-to-market angle against legacy enclosure vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to electrical infrastructure conglomerates seeking thermal-mechanical integration capabilities. Long-term viability hinges on liquid-cooling engineering talent retention and OFGEM queue resolution timing. Acquisition target archetype: Midlands-based precision fabricators with BSI certification and hyperscale reference contracts. Watch OFGEM grid allocation announcement velocity as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Manifold Scale-Up | Direct-to-chip thermal infrastructure captures hyperscale specifications above 50kW per rack in West London. |
| Smart Sensor DCIM Integration | Embedded power metering addresses Streamlined Energy and Carbon Reporting obligations for qualifying UK operators. |
| Midlands Fabrication Capacity Expansion | Sheffield and Rotherham steel feedstock proximity reduces landed cost exposure for standard rack tiers. |
| Hyperscale Direct OEM Engagement | Bypassing mechanical contractor channels accelerates vendor evaluation cycles in Thames Valley corridor. |
| BSI Certification Investment | Structural load-rating credentials create procurement preference in multi-tenant colocation contracts. |
Research Methodology
Independent corroboration across primary interviews with data center engineering directors, colocation procurement leads, and rack OEM product managers underwrites the qualitative findings. Secondary validation draws from OFGEM grid connection databases, BSI Group certification registries, and hyperscaler capital expenditure disclosures. Bottom-up installation volume estimates triangulate against top-down facility buildout tracking across the Slough-London corridor, Manchester clusters, and Midlands edge zones.
Comparable-period anchoring to historical hyperscale deployment cadence in the Thames Valley establishes the forecast reference baseline. The analytical framework models rack demand across product type, deployment model, end-user vertical, and capacity tier throughout the projection horizon. CAGR derivation incorporates facility power density trajectories, liquid-cooled adoption curves, and OFGEM queue resolution assumptions. Industry-specific inputs include cold-rolled steel price indices and copper thermal interface allocation schedules.
The model assumes a particular technology adoption path; alternative pathways for direct-to-chip liquid cooling would alter the outlook if air-cooled hybrid architectures prove more economically viable for legacy facility retrofits. Forecasts reflect assumptions about grid connection timeline resolution and carbon reporting enforcement intensity. A small set of triggers—OFGEM allocation velocity, copper sourcing bottlenecks, and thermal engineering hiring cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Netherlands Data Center Rack Market
Data Center Infrastructure
North America Data Center Power Market