
 Linear Actuator Market | 2026-2036
Linear Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
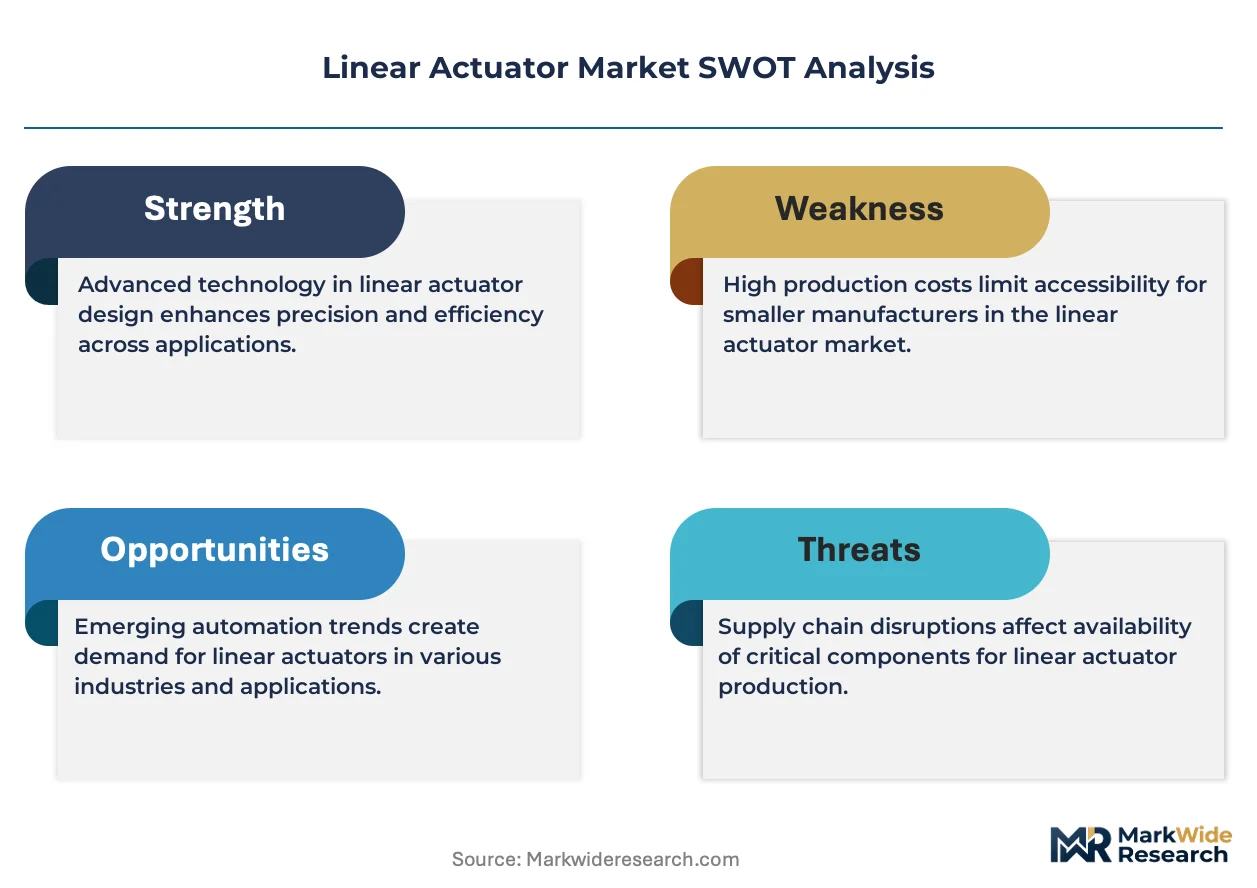
Linear Actuator Market Analysis
The EU Green Deal is realigning industrial equipment procurement across European manufacturing, pushing OEMs toward energy-efficient electromechanical alternatives to pneumatic and hydraulic systems. Parker Hannifin Corp. leverages its fluid power heritage to compete in electromechanical hybrid architectures. Bosch Rexroth AG anchors German automation demand through integrated drive-linear motion platforms. SMC Corporation dominates pneumatic actuator supply while extending its electric actuator portfolio across Asian factory automation markets.
A linear actuator converts rotary motion into precise linear displacement, typically achieving positioning accuracy within micrometers through ball screw, belt drive, or direct drive mechanisms; it serves as the fundamental motion element in automated machinery, medical devices, and aircraft control surfaces. Electrical actuators lead type segmentation due to superior energy efficiency and programmability in robotics and automated manufacturing lines. Aerospace applications command premium pricing tiers where hydraulic redundancy requirements and MIL-spec certification create substantial margin pools. Healthcare end users represent the fastest-growing demand channel as surgical robotics and diagnostic imaging tables require sub-millimeter positioning repeatability.
The EU Machinery Directive, ISO 13849 functional safety standards, and FDA device regulations collectively shape product design requirements, testing protocols, and market access conditions for actuator suppliers across industrial and medical segments. China's GB standards and SAMR certification frameworks impose additional conformity requirements for equipment deployed in domestic automotive and consumer electronics manufacturing. Stakeholders must monitor evolving cybersecurity annexes to functional safety standards as connected actuators become standard in Industry 4.0 architectures.
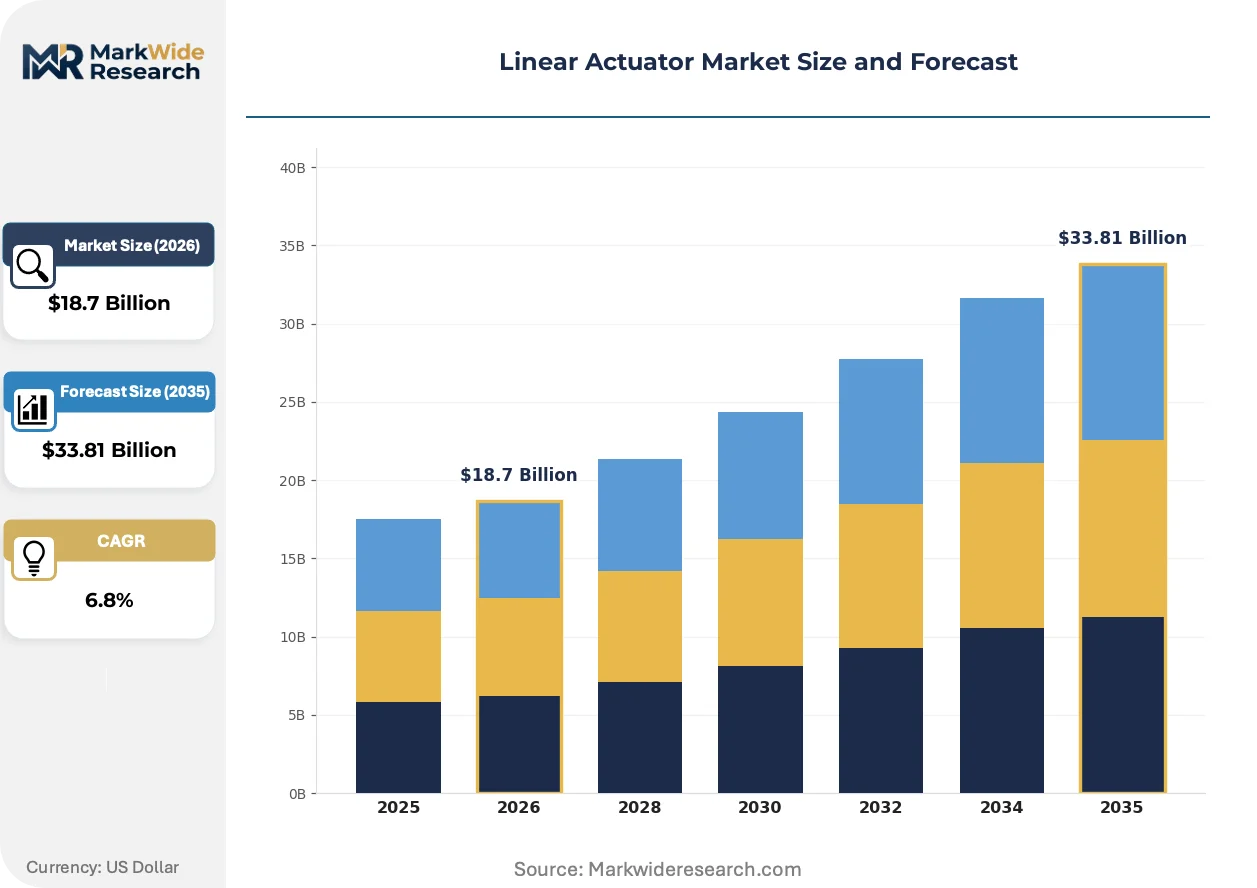
Market Dynamics
Factory automation investment and healthcare infrastructure upgrades are pulling precision motion systems toward electromechanical architectures, compressing pneumatic actuator deployment timelines across automotive and medical device manufacturing.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Energy-efficiency requirements in machinery procurement are accelerating displacement of hydraulic power units with servo-electric linear drives across German and Italian manufacturing clusters.
- Surgical robotics capital deployment:Medical equipment manufacturers are expanding actuator procurement for patient positioning systems requiring sub-millimeter repeatability in operating theaters.
- GB standards harmonization:China's SAMR certification alignment with ISO functional safety frameworks is reducing technical barriers for electromechanical actuator imports into automotive assembly lines.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependency on Chinese processing infrastructure creates input cost volatility for high-performance direct-drive linear motors.
- ISO 13849 certification timeline:Functional safety validation for electromechanical systems extends product development cycles by 8-14 months compared to legacy pneumatic alternatives.
- Pneumatic system installed base:Existing compressed air infrastructure in established automotive plants creates substitution friction for electric actuator retrofits.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Production-linked incentives for medical devices and electronics assembly are attracting actuator suppliers to establish local servo motor and ball screw production.
- Digital twin integration:Convergence of linear actuator position feedback with real-time simulation platforms is enabling predictive maintenance contracts in semiconductor fabrication equipment.
- EU AI Act machinery annex:Emerging requirements for autonomous decision-making in industrial equipment are creating specification windows for intelligent electromechanical actuators with embedded condition monitoring.
Industry Challenges
- Mechatronics engineering scarcity:Cross-functional talent combining servo drive tuning, mechanical design, and safety programming remains concentrated in German and Japanese industrial clusters.
- Legacy controller integration:Fieldbus protocol fragmentation across Siemens, Rockwell, and Mitsubishi automation ecosystems forces custom gateway development for actuator OEMs.
- Cybersecurity certification layering:IEC 62443 industrial security standards are adding compliance documentation burdens atop existing functional safety requirements for connected motion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Actuator Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electrical, Pneumatic, Hydraulic, Mechanical Application: Automated Manufacturing, Robotics, Medical Equipment, Aerospace End User: Industrial, Healthcare, Automotive, Consumer Electronics Installation: Integrated, Stand-alone, Retrofit, Custom |
| Companies Covered | Emerson Electric Co., ABB Ltd., Parker Hannifin Corp., Moog Inc., SMC Corporation, LINAK, Thomson Industries Inc., Bosch Rexroth AG, Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Actuator Market Emerging Trajectories
Linear actuator architecture is converging with power electronics and sensing intelligence, transforming standalone motion components into networked mechatronic nodes. This integration is compressing system boundaries and reshaping supplier value capture.
Integrated servo-linear actuators combining permanent magnet motors with planetary roller screws are rewriting performance benchmarks in high-force precision applications. Semiconductor wafer handling equipment manufacturers in South Korea and Taiwan are adopting these units to eliminate gearbox backlash and reduce footprint by 40 percent. The technology is compressing traditional multi-component supply chains into single-source procurement decisions.
REACH restrictions on per- and polyfluoroalkyl substances are forcing lubrication formulation changes in ball screw assemblies deployed across European medical and food processing machinery. Equipment builders in Germany and Switzerland are qualifying PFAS-free greases that maintain 10,000-hour service intervals under cleanroom conditions. The regulatory pressure is accelerating material science investment among specialty lubricant suppliers serving motion control OEMs.
Buyer preference for total cost of ownership contracting is displacing unit-based actuator procurement in automotive body-in-white lines. Tier-1 integrators in the United States and Mexico are negotiating performance-based agreements where actuator suppliers guarantee mean-time-between-failure rates and absorb downtime risk. This shift is concentrating supplier relationships around predictive analytics capabilities and regional service infrastructure density.
Linear Actuator Market Segmentation
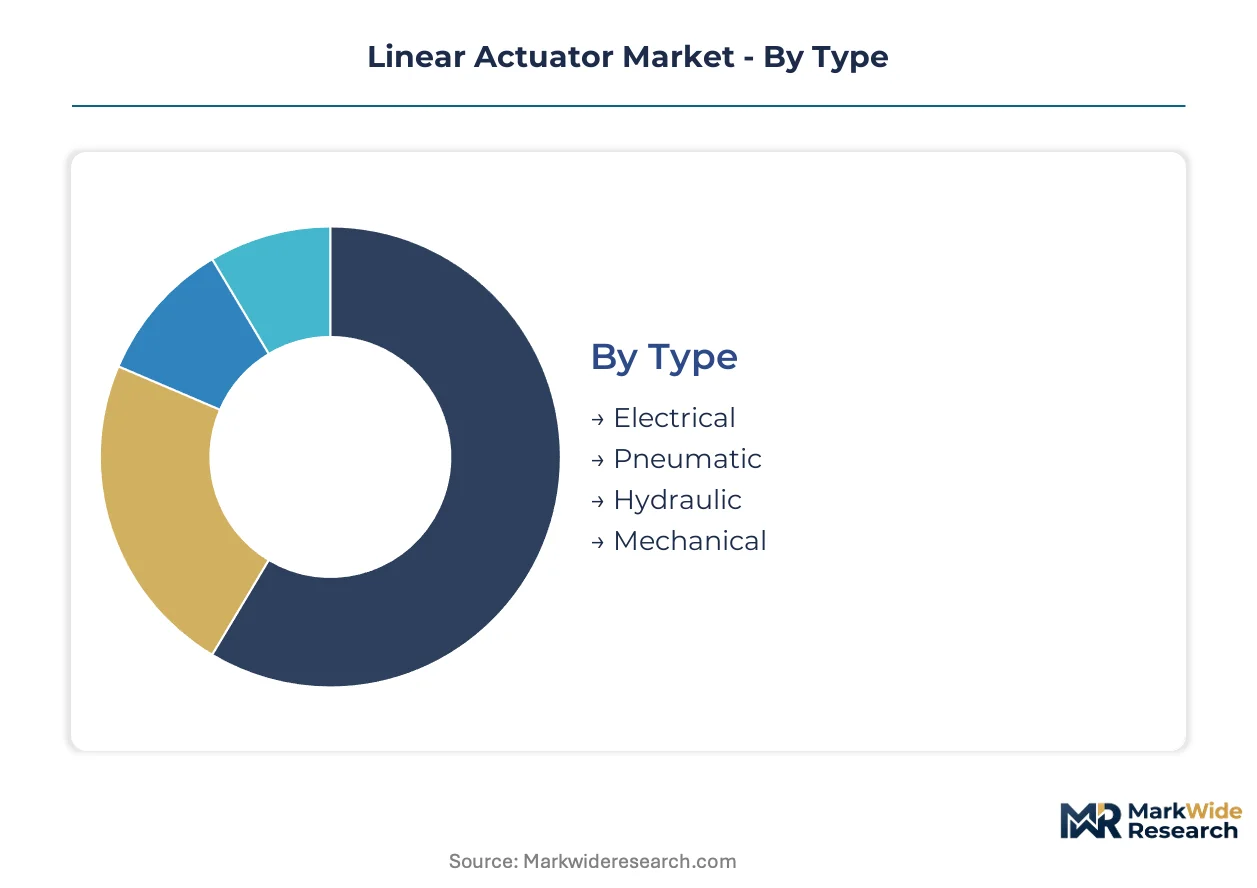
Linear actuator segmentation reveals distinct technology clusters competing for specification in precision motion systems. Each dimension—type, application, end user, and installation—carries different margin profiles and certification burdens that reshape supplier positioning across industrial and medical verticals.
Type:
Supply concentration in high-force precision applications tilts procurement toward integrated electromechanical architectures, compressing legacy hydraulic and pneumatic deployment timelines in automotive and semiconductor manufacturing.
- Electrical:Servo motors paired with ball screws or belt drives achieve micrometer positioning accuracy through closed-loop feedback control. Demand concentrates in German automotive body-in-white lines and South Korean semiconductor wafer handling equipment, where ISO 13849 functional safety certification and energy-efficiency mandates under the EU Green Deal accelerate displacement of fluid power alternatives.
- Pneumatic:Compressed air cylinders deliver high-speed linear motion at lower capital cost but sacrifice precision and energy efficiency. Japan's SMC Corporation and Germany's Festo dominate supply, though pneumatic deployment is compressing in European medical device manufacturing where Ecodesign regulations penalize energy-intensive motion systems.
- Hydraulic:High-force density suits aerospace flight control surfaces and heavy machinery, with Parker Hannifin and Bosch Rexroth anchoring supply through MIL-spec certification and integrated manifold architectures.
- Mechanical:Lead screws and rack-and-pinion systems serve cost-sensitive positioning with minimal electronic complexity, finding residual demand in consumer appliance and agricultural equipment applications.
Today's leader: Electrical. Tomorrow's challenger: Pneumatic in emerging Asian factory automation markets where compressed air infrastructure remains dense.
Application:
Application segmentation tracks capital deployment intensity across end-use sectors, with aerospace and medical equipment commanding premium pricing tiers due to certification layering and liability exposure.
- Automated Manufacturing:Assembly line actuators require 24/7 reliability in high-cycle environments, with automotive OEMs in Michigan, Bavaria, and Guangdong specifying integrated servo-linear units for welding and sealing operations. Mean-time-between-failure guarantees now dominate procurement criteria over unit cost.
- Robotics:Collaborative and industrial robots demand compact, lightweight actuators with torque density maximization. Fanuc and KUKA specification windows favor electromechanical architectures with embedded force-torque sensing for human-robot collaboration compliance.
- Medical Equipment:Surgical robotics and diagnostic imaging tables require sub-millimeter repeatability under FDA and MDR device regulations, creating substantial margin pools for suppliers with biocompatibility and electromagnetic compatibility certifications.
- Aerospace:Flight control and landing gear actuation maintains hydraulic redundancy requirements under FAA and EASA airworthiness directives, though fly-by-wire electromechanical alternatives are penetrating secondary control surfaces.
Medical Equipment captures the steepest expansion trajectory as capital deployment into surgical robotics accelerates across US hospital systems and European university medical centers.
End User:
End user segmentation reflects divergent procurement sophistication, with industrial buyers negotiating performance-based contracts while healthcare purchasers prioritize regulatory documentation and service infrastructure density.
- Industrial:Factory automation integrators in Germany, China, and the United States specify actuators through total cost of ownership frameworks, absorbing downtime risk via predictive maintenance contracts and guaranteed availability clauses.
- Healthcare:Hospital procurement committees and medical device OEMs demand FDA 510(k) or MDR technical documentation packages, with preference concentrating on suppliers with ISO 13485 quality management and US-based field service networks.
- Automotive:Tier-1 suppliers including Bosch and Continental drive specification for electric vehicle battery assembly and electric powertrain manufacturing, where cleanroom-compatible lubrication and PFAS-free formulations are becoming mandatory.
- Consumer Electronics:Smartphone and wearable device assembly requires miniature linear motors with sub-millimeter stroke lengths, with Foxconn and Luxshare specification windows prioritizing volume scale and logistics integration over technical differentiation.
Industrial buyers currently dominate volume procurement. Healthcare represents the fastest-climbing demand channel as diagnostic and surgical capital expenditure accelerates.
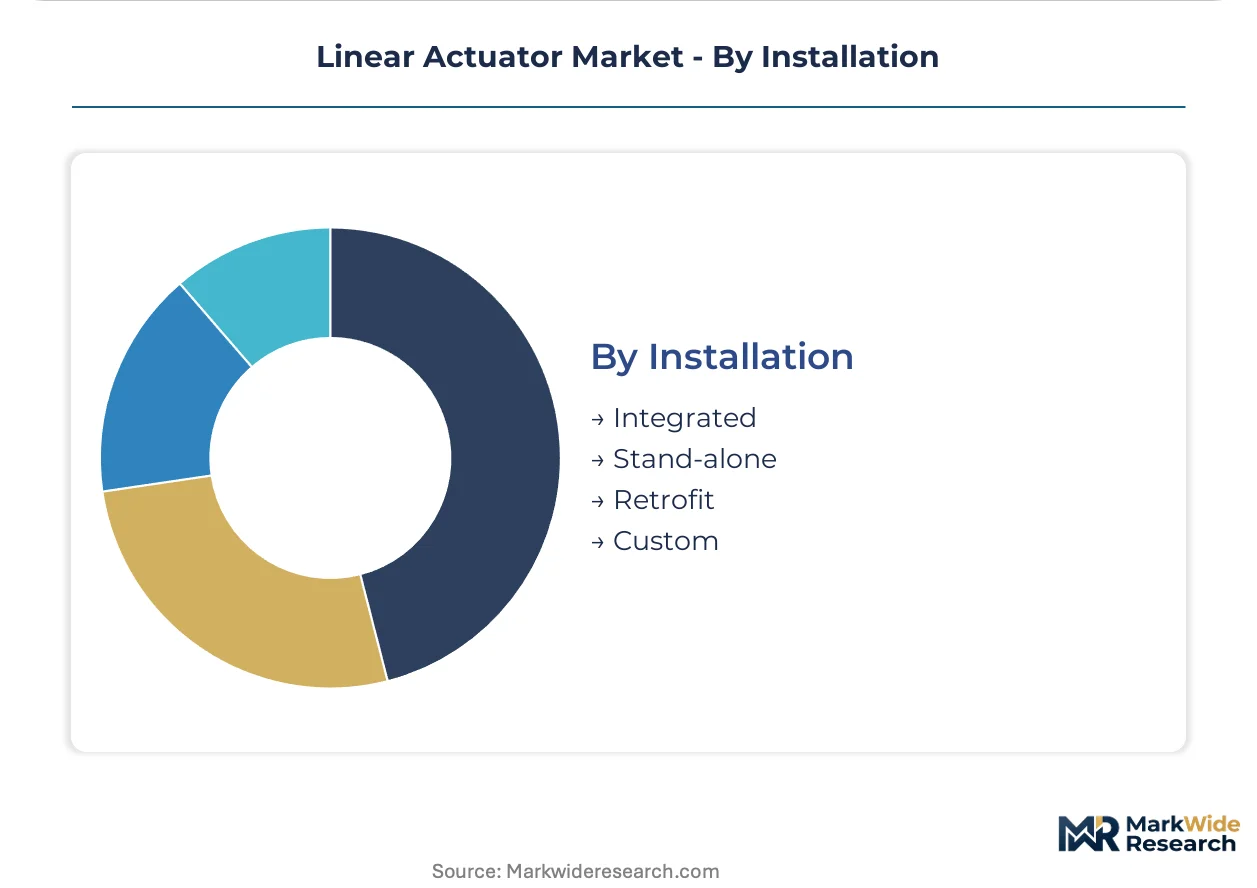
Installation:
Installation mode segmentation tracks customer engineering capability and legacy infrastructure constraints, with integrated solutions capturing value from buyers lacking mechatronics expertise.
- Integrated:Pre-engineered actuator-drive-controller packages from Bosch Rexroth and Parker Hannifin reduce commissioning complexity for automotive and semiconductor OEMs, consolidating multi-component supply chains into single-source procurement decisions.
- Stand-alone:Modular actuators with standardized mechanical interfaces serve machine builders with in-house control engineering, prevalent in Italian packaging machinery and Taiwanese electronics assembly equipment sectors.
- Retrofit:Electric actuator replacement of legacy pneumatic cylinders in established automotive plants faces substitution friction from compressed air infrastructure depreciation schedules, though EU energy-efficiency audits are accelerating conversion timelines.
- Custom:Application-specific stroke lengths, force profiles, and environmental sealing serve aerospace OEMs and nuclear equipment suppliers with non-negotiable performance specifications outside standard product ranges.
Integrated solutions currently anchor supplier margin capture. Retrofit demand is gaining share fastest as industrial decarbonization mandates force equipment refresh cycles in European manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The linear actuator industry traces its precision engineering heritage to German industrial automation clusters established during post-war manufacturing reconstruction. Electromechanical motion control architectures subsequently diffused through Japanese robotics supply chains and American aerospace certification frameworks. Today's demand geography reflects these historical foundations while incorporating new production centers in China and India.
United States
Michigan and Tennessee automotive assembly lines drive specification for integrated servo-linear units in electric vehicle battery manufacturing. The FDA maintains stringent device regulations for surgical robotics actuators deployed across Cleveland Clinic and Mayo Clinic surgical theaters. Boston's medical device corridor concentrates procurement committees demanding ISO 13485 documentation and predictive maintenance service networks.
Germany
Bavarian automotive OEMs specify electromechanical actuators through total cost of ownership frameworks under EU Green Deal industrial decarbonization mandates. The EU Machinery Directive and ISO 13849 functional safety standards compress pneumatic deployment timelines in Stuttgart and Wolfsburg manufacturing clusters. Siemens and Bosch anchor integrated drive-linear motion platform supply through Baden-Württemberg automation ecosystems.
China
Guangdong and Jiangsu province electronics assembly lines absorb miniature linear motors for smartphone and wearable device manufacturing under SAMR certification alignment with ISO frameworks. GB standards harmonization reduces technical barriers for electromechanical actuator imports into automotive facilities near Shanghai. The country's dual carbon goals accelerate displacement of hydraulic power units in Shenzhen and Suzhou factory automation markets.
Japan
Nagoya industrial robotics manufacturers specify compact electromechanical architectures with embedded force-torque sensing for human-robot collaboration compliance. METI industrial policy supports precision motion component development through Kansai and Chubu regional manufacturing subsidies. SMC Corporation anchors pneumatic supply while extending electric actuator portfolios across Asian automation markets from its Tokyo headquarters.
India
Maharashtra and Karnataka medical device manufacturers expand actuator procurement for diagnostic imaging tables under PLI scheme production-linked incentives. CDSCO device regulations shape import substitution strategies for surgical robotics components in Mumbai and Bengaluru healthcare infrastructure upgrades. Local servo motor and ball screw production investments target electronics assembly demand from Tamil Nadu contract manufacturers.
Linear Actuator Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the linear actuator value chain. Integrated manufacturers controlling in-house motor winding, screw grinding, and controller firmware development capture premium pricing in aerospace and medical segments. The market structures around three archetypes: diversified industrial conglomerates with fluid power heritage, specialized electromechanical motion companies, and pneumatic specialists extending electric portfolios. Dominant competitive moves include backward integration into rare earth magnet supply chains and predictive maintenance service infrastructure expansion.
Among diversified industrial conglomerates, Parker Hannifin Corp. and Bosch Rexroth AG exemplify the integrated architecture archetype combining electromechanical and hydraulic competencies. SMC Corporation occupies a distinct position as a pneumatic-native supplier extending into electric actuator markets. These three anchors represent contrasting strategic postures: fluid power heritage leveraged against electromechanical transition, German automation platform integration, and Asian factory automation volume scaling.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB Ltd. |
| Parker Hannifin Corp. |
| Moog Inc. |
| SMC Corporation |
| LINAK |
| Thomson Industries Inc. |
| Bosch Rexroth AG |
| Rockwell Automation Inc. |
| Others |
Supply Flow & Price Mechanics
Integrated servo-linear architectures combining permanent magnet motors with planetary roller screws are compressing multi-component supply chains into single-source procurement decisions while simultaneously elevating performance premiums in semiconductor wafer handling and surgical robotics applications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade MIL-spec certified actuators from industrial automation workhorses and cost-sensitive mechanical alternatives. Price differentiation hinges on ISO 13849 functional safety certification tier and captive rare earth magnet processing capabilities. Cost compression in standard industrial tiers is intensifying because Chinese ball screw manufacturers are expanding servo motor integration. Healthcare OEMs exhibit lowest price sensitivity due to FDA 510(k) documentation burdens and liability exposure, while consumer electronics assembly lines prioritize volume scale over technical differentiation.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium and dysprosium processing infrastructure that feeds permanent magnet production for high-performance direct-drive linear motors. Manufacturing concentrates in Germany, China, and Japan where Bosch Rexroth, domestic champions, and SMC Corporation anchor electromechanical and pneumatic supply respectively. Raw material dependencies span rare earth elements, precision-ground ball screws, and REACH-compliant PFAS-free lubricants. Tariff exposure on processed rare earth compounds threatens input cost stability for European and North American actuator OEMs. Distribution runs through Tier-1 automation integrators in automotive and semiconductor equipment sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The linear actuator market functions as a stable compounder underpinned by irreversible factory automation investment and healthcare infrastructure modernization that sustains replacement demand across economic cycles.
For Market Incumbents: Anchor margin position through backward integration into rare earth magnet supply chains and predictive maintenance service infrastructure density. Defend against emerging Chinese servo motor competitors by accelerating ISO 13849 certification timelines and locking automotive OEMs into total cost of ownership contracts with guaranteed availability clauses.
For New Entrants and Emerging Players: Begin with India's PLI scheme manufacturing corridors where local servo motor and ball screw production gaps create procurement vulnerability for medical device and electronics assembly sectors. Target Maharashtra and Karnataka diagnostic imaging table manufacturers lacking ISO 13485-certified domestic suppliers. Pursue hospital system partnerships emphasizing US-based field service networks over unit cost competition.
For Investors and Strategic Acquirers: Valuations sit cheapest among pneumatic-native suppliers extending electric actuator portfolios without integrated controller firmware development capabilities. Long-term viability favors electromechanical specialists with in-house screw grinding and embedded condition monitoring IP across the 5-10 year window. Monitor EU AI Act machinery annex implementation as inflection indicator for intelligent actuator specification windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium processing insulates Parker Hannifin and Bosch Rexroth from Chinese export volatility. |
| Predictive Maintenance Service Infrastructure Expansion | Regional service density enables outcome-based contracts with Michigan automotive Tier-1 integrators. |
| ISO 13849 Functional Safety Certification Acceleration | Compressed validation timelines differentiate European suppliers against pneumatic retrofit timelines. |
| PFAS-Free Lubrication Formulation Investment | REACH-compliant greases qualify German medical and food processing machinery OEMs for Ecodesign procurement. |
| Embedded Condition Monitoring Firmware Development | Intelligent electromechanical nodes capture EU AI Act machinery annex specification windows. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with maintenance directors at German automotive OEMs, biomedical engineers at US hospital systems, procurement leads at South Korean semiconductor equipment manufacturers, and aftermarket service heads at Japanese robotics integrators were validated against secondary sources including SEC 10-K filings, EU Machinery Directive implementation reports, SAMR certification databases, and customs trade data on ball screw and servo motor imports.
Input-output matrices map electromechanical actuator demand across automated manufacturing, robotics, medical equipment, and aerospace applications against supply capacity in Germany, China, Japan, and the United States. Segmentation dimensions span type (electrical, pneumatic, hydraulic, mechanical), application, end user, and installation mode. CAGRs were derived from elasticity modeling of capital expenditure cycles and regulatory compliance timelines. Forecast inputs incorporate EU Green Deal decarbonization mandates, FDA device regulation trajectories, and GB standards harmonization progress.
Caveats apply where rare earth export restrictions, ISO 13849 certification backlog extensions, or cybersecurity standard layering could materially shift the outlook. Forecasts reflect documented assumptions about industrial automation investment continuity and healthcare infrastructure budget allocations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Sortation Systems Market
Industrial Automation
Utility Automation Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
United States Human Machine Interface Market
Industrial Automation
HMI Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Asia-Pacific Automation Components Market